
 Soft Contact Lenses Market | 2026-2036
Soft Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Contact Lenses Market Intelligence
Market Context
Korean and Japanese silicone hydrogel foundry capacity is hardening as regional producers scale thin-film casting lines. Johnson & Johnson Vision Care, Inc. leverages its Acuvue manufacturing footprint across Ireland and the United States to sustain supply continuity for daily disposables. Alcon competes through its Precision1 platform, while CooperVision differentiates via Biofinity extended wear credentials and toric customization depth.
Technical Definition and Segment Structure
Soft contact lenses are hydrophilic polymer discs, typically 30 to 80 percent water content, that drape over the cornea to refract light and correct ametropia through oxygen-permeable matrices. Silicone hydrogel dominates value generation due to higher oxygen transmissibility and extended wear approvals, while hydrogel retains volume share in price-sensitive cosmetic and entry-level corrective segments. Application demand concentrates in myopia correction as juvenile onset rates climb across East Asian school systems, with presbyopia correction and multifocal designs capturing margin pools in aging Western populations.
Regulatory Frame and Outlook
FDA 510(k) pathways and EU MDR Class IIa designations govern market access, with Japan's PMDA requiring additional moisture retention documentation for extended wear claims. China's NMPA has tightened silicone hydrogel biocompatibility testing protocols, extending registration timelines for imported brands. Stakeholders must monitor how FDA draft guidance on antimicrobial lens case standards and EU Green Deal packaging waste rules reshape sterile container specifications and distribution economics.
Market Dynamics
Silicone hydrogel material substitution is compressing legacy hydrogel margins while FDA extended wear pathways accelerate prescription migration toward higher-oxygen-transmissible formats. Manufacturing concentration in Korean and Japanese casting foundries tightens supply responsiveness.
Growth Catalysts
- Juvenile myopia protocols:East Asian school-based vision screening mandates in China and Japan expand addressable patient pools for daily disposable correction.
- FDA 510(k) extended wear clearance:Streamlined biocompatibility documentation for silicone hydrogel formulations accelerates product pipeline velocity.
- Direct-to-consumer channel maturation:Subscription-based lens replenishment platforms in the United States reduce patient acquisition friction and improve compliance adherence.
Market Restraints
- Raw material concentration:Silicone monomer supply tightens around three Korean petrochemical suppliers, exposing lens manufacturers to input cost volatility.
- Regulatory friction:China's NMPA extended silicone hydrogel biocompatibility testing protocols in 2023, stretching import registration timelines for non-domestic brands.
- Refractive surgery substitution:LASIK and SMILE procedures capture myopic patients aged 25-40 in premium urban markets, compressing long-term lens user lifetime value.
Strategic Opportunities
- Presbyopia-multifocal convergence:Aging Western populations with disposable income create whitespace for toric-multifocal combination designs addressing astigmatism and near-vision loss simultaneously.
- India's underpenetrated correction market:Low contact lens adoption relative to spectacle prevalence offers volume expansion potential as optometric retail chains professionalize.
- EU Green Deal packaging mandates:Sterile blister pack recyclability requirements favor manufacturers with biodegradable polymer R&D capabilities, creating first-mover positioning.
Industry Challenges
- Specialized polymer engineering talent scarcity:Thin-film silicone hydrogel casting requires expertise spanning ophthalmic optics and chemical engineering, with limited training pipeline capacity.
- Legacy ERP integration friction:Direct-to-consumer subscription platforms demand real-time inventory synchronization that conflicts with established wholesale-distributor accounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Contact Lenses Market |
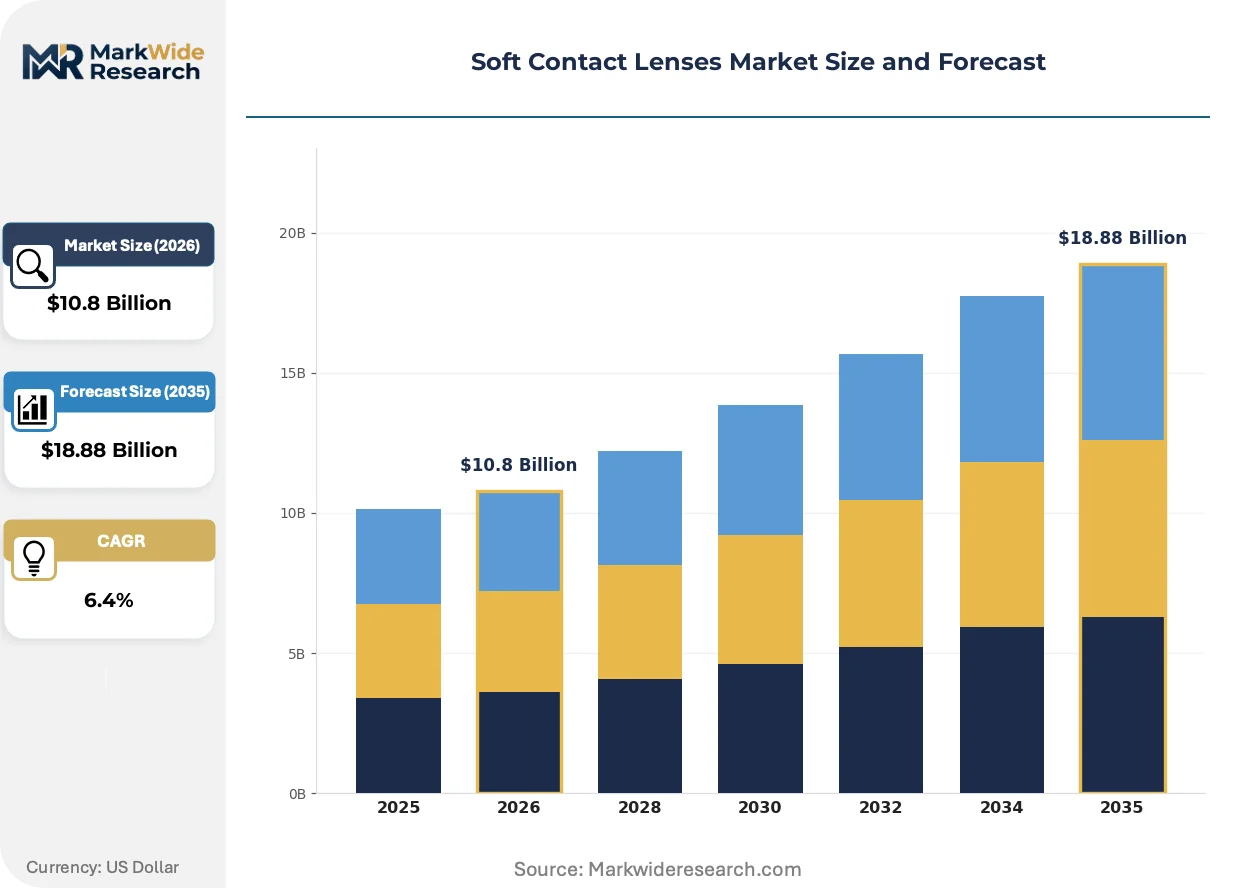
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Silicone Hydrogel, Extended Wear, Cosmetic, Toric, Multifocal Application: Myopia Correction, Astigmatism Correction, Presbyopia Correction, Keratoconus, Therapeutic Use, Cosmetic Enhancement Customer Type: Optometrists, Ophthalmologists, Eye Care Chains, Optical Retailers, Online Retailers, Specialty Clinics Packaging Type: Blister Pack, Multipack Boxes, Vials, Lens Cases, Disposable Packs, Sterile Containers |
| Companies Covered | Johnson & Johnson Vision Care, Inc., Bausch + Lomb, Alcon, CooperVision, Menicon Co., Ltd., HOYA Corporation, EssilorLuxottica, Carl Zeiss Meditec AG, SEED Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Contact Lenses Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory pathway refinements are compressing product development cycles while channel disintermediation reconfigures how patients access prescription renewal. These forces reshape competitive positioning without altering fundamental vision correction economics.
Silicone hydrogel nanofabrication is rewriting oxygen permeability benchmarks. The technology embeds siloxane macromers within hydrophilic matrices to achieve DK/t values exceeding 100 without compromising wettability. Younger myopic patients in the United States and Japan are adopting these lenses for overnight wear at accelerating rates. Extended wear approvals are compressing the replacement cycle frequency that defined legacy hydrogel economics.
REACH chemical substance registration requirements in Europe are tightening monomer traceability obligations for imported lens materials. Manufacturers must document full supply chain substance flows from silicone precursor to finished sterile product. EU MDR Class IIa device classification adds post-market surveillance reporting that particularly burdens smaller private-label brands lacking regulatory affairs infrastructure.
Subscription-based replenishment is displacing traditional optometric office purchasing across the United States. Patients receive scheduled lens shipments with integrated telehealth prescription verification, bypassing biannual office visits. This model concentrates volume with platforms possessing integrated electronic health record connectivity, marginalizing independent optical retailers lacking digital infrastructure investment capacity.
Soft Contact Lenses Market Segmentation
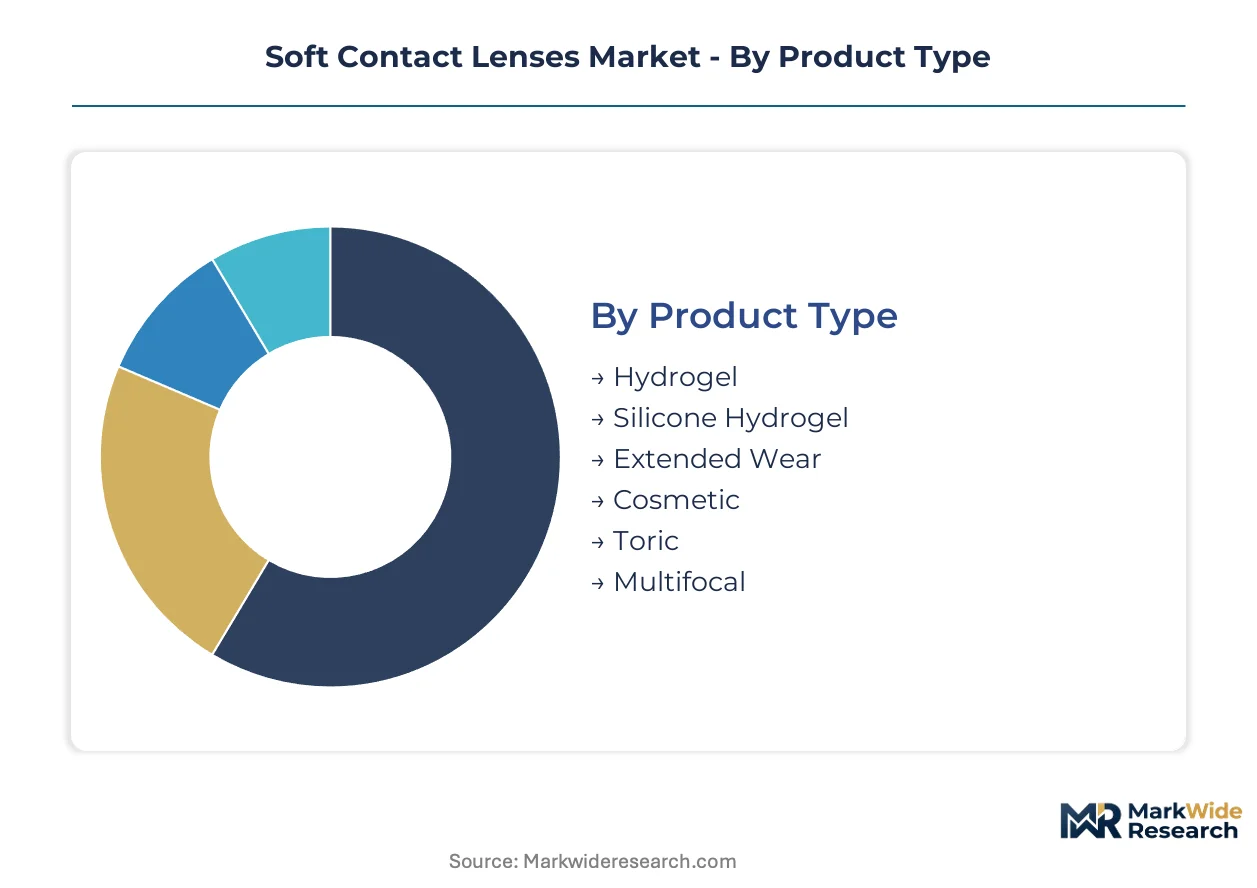
Segmentation in the soft contact lenses market reveals how material science, clinical application, and distribution channel economics partition value capture. Manufacturers calibrate R&D investment and regulatory strategy against these divides to optimize margin extraction.
Product Type:
Volume concentrates in entry-level hydrogel formats, while silicone hydrogel commands premium positioning through oxygen transmissibility advantages.
- Silicone Hydrogel:Siloxane macromers embedded within hydrophilic matrices achieve DK/t values exceeding 100. Demand clusters in the United States and Japan where FDA and PMDA extended wear approvals support overnight use protocols.
- Hydrogel:Legacy polymer formulations with 30-80 percent water content dominate price-sensitive cosmetic and entry-level corrective segments. Volume persists in developing markets where oxygen permeability specifications remain less stringent.
- Extended Wear:FDA 510(k) clearance pathways enable multi-day continuous use claims. Regulatory documentation requirements favor established manufacturers with biocompatibility testing infrastructure.
- Cosmetic:Tinted and patterned lenses for aesthetic modification. Distribution concentrates through optical retailers and online channels with lower clinical oversight thresholds.
- Toric:Cylindrical power correction for astigmatism requiring precise axis alignment. Customization depth differentiates specialist manufacturers from commodity producers.
- Multifocal:Simultaneous distance and near vision correction through concentric or aspheric zone designs. Presbyopia demographics in aging Western populations drive prescription migration.
Mature deployment sits with hydrogel. Newer deployment is concentrated in silicone hydrogel.
Application:
Clinical indication determines reimbursement pathways and practitioner channel selection, with myopia protocols generating volume and presbyopia designs extracting margin.
- Myopia Correction:Spherical power correction for refractive error dominates prescription volume. East Asian school-based vision screening mandates in China and Japan expand addressable patient pools for daily disposable formats.
- Presbyopia Correction:Near-vision loss compensation through multifocal or monovision approaches. Aging populations in the United States and Western Europe sustain premium pricing for combination toric-multifocal designs.
- Astigmatism Correction:Cylindrical lens requirements complicate fitting protocols and elevate practitioner involvement. Toric customization capabilities separate premium manufacturers from standard spherical suppliers.
- Keratoconus:Specialized scleral and hybrid lens configurations for corneal ectasia management. Prescription concentrates in ophthalmology clinics with corneal topography diagnostic capacity.
- Therapeutic Use:Bandage lenses for corneal healing and drug delivery applications. Hospital and specialty clinic procurement channels dominate with distinct sterilization and documentation requirements.
- Cosmetic Enhancement:Non-corrective tinted lenses for aesthetic purposes. Regulatory classification varies by jurisdiction, with some markets treating these as medical devices and others as consumer cosmetics.
Volume leadership belongs to myopia correction. Margin expansion concentrates in presbyopia correction.
Customer Type:
Channel structure fragments between professional fitting services and direct-to-consumer convenience platforms, with inventory synchronization requirements favoring integrated operators.
- Eye Care Chains:Corporate optometric networks with centralized purchasing and electronic health record integration. Scale advantages in subscription-based replenishment platform deployment.
- Online Retailers:Direct-to-consumer platforms with telehealth prescription verification bypassing traditional office visits. Real-time inventory synchronization demands conflict with legacy wholesale-distributor accounting systems.
- Optometrists:Independent practitioners providing comprehensive fitting services and follow-up care. Patient relationship continuity supports premium product recommendation authority.
- Ophthalmologists:Medical specialists managing complex pathologies including keratoconus and post-surgical correction. Therapeutic lens prescribing concentrates in this channel.
- Optical Retailers:Brick-and-mortar outlets with lens dispensing but limited clinical examination capacity. Margin pressure from channel disintermediation threatens independent operators lacking digital infrastructure.
- Specialty Clinics:Corneal and refractive surgery centers with advanced diagnostic equipment. Complex fitting requirements sustain specialist manufacturer relationships.
Established volume flows through eye care chains. Channel expansion is accelerating through online retailers.
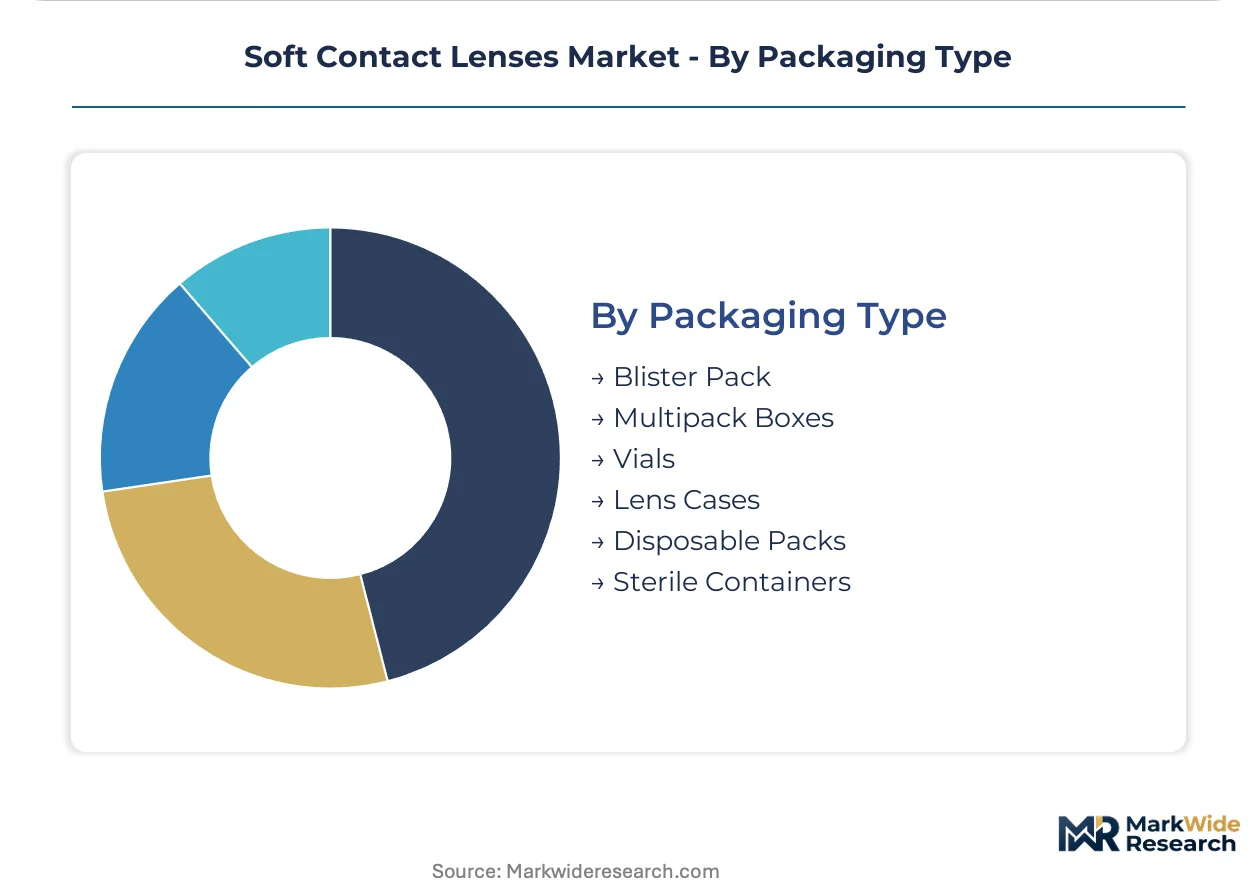
Packaging Type:
Sterile containment specifications face tightening sustainability mandates, with recyclability requirements reshaping material selection and distribution economics.
- Blister Pack:Individual sterile units in foil-laminate or polymer trays. EU Green Deal packaging waste rules drive biodegradable polymer R&D investment.
- Multipack Boxes:Aggregated monthly or quarterly supply configurations. Subscription replenishment platforms favor this format for logistics efficiency.
- Vials:Rigid sterile containers for specialty and therapeutic lenses. Higher unit costs limit deployment to premium therapeutic segments.
- Lens Cases:Reusable storage vessels with antimicrobial coating requirements. FDA draft guidance on lens case standards elevates compliance documentation burdens.
- Disposable Packs:Single-use configurations for travel and trial purposes. Convenience positioning supports premium pricing in direct-to-consumer channels.
- Sterile Containers:Hospital-grade packaging for surgical and therapeutic applications. Regulatory traceability requirements from silicone precursor to finished product elevate supply chain documentation obligations.
Conventional deployment relies on blister packs. Sustainability-driven transition is concentrating in multipack boxes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone monomer feedstock from Korean petrochemical suppliers anchors East Asian manufacturing capacity for oxygen-permeable lens materials. Foundry concentration in Gyeonggi-do and Osaka prefectures shapes regional supply responsiveness for daily disposable and extended wear formats.
United States
FDA 510(k) clearance pathways for extended wear silicone hydrogel accelerate prescription migration toward higher-oxygen-transmissible formats. Subscription-based replenishment platforms with telehealth verification displace traditional optometric office purchasing across metropolitan markets. Johnson & Johnson Vision Care sustains supply continuity through its Acuvue manufacturing footprint in Jacksonville, Florida and Limerick, Ireland.
China
Juvenile myopia protocols in Shanghai and Beijing school systems expand addressable patient pools for daily disposable correction among younger demographics. NMPA tightened silicone hydrogel biocompatibility testing protocols in 2023, stretching import registration timelines for non-domestic brands. Yangtze River Delta optical retail chains professionalize fitting services as domestic lens adoption rises relative to spectacle prevalence.
Japan
PMDA moisture retention documentation requirements for extended wear claims govern market access for overnight-use silicone hydrogel formats. Aging demographics in Tokyo and Osaka sustain prescription volume for multifocal designs addressing presbyopia and near-vision loss. Menicon and SEED anchor domestic manufacturing expertise in Nagoya and Tokyo metropolitan clusters.
South Korea
Thin-film casting foundry capacity hardens in Gyeonggi-do as regional producers scale silicone hydrogel production lines. MFDS device registration aligns with international standards while maintaining additional stability testing for cosmetic tinted lens categories. Seoul-based optical chains integrate direct-to-consumer platforms with in-person fitting verification.
Germany
EU MDR Class IIa designation and REACH chemical substance registration govern monomer traceability for imported lens materials. Carl Zeiss Meditec anchors ophthalmic optics manufacturing in Oberkochen and Jena. Precision optics clusters in Baden-Württemberg and Thuringia concentrate R&D investment for toric and multifocal customization depth.
Soft Contact Lenses Market Key Industry Players
Global majors compete with regional champions across material science capabilities and regulatory pathway expertise. Market structure concentrates around three dominant archetypes: integrated healthcare conglomerates with vision care divisions, specialized ophthalmic device manufacturers, and optical retail-to-manufacturing verticals. Competitive positioning hinges on FDA extended wear clearance portfolios, silicone hydrogel casting foundry access, and direct-to-consumer platform integration. M&A activity targets toric customization technology and subscription platform infrastructure.
Among integrated healthcare conglomerates, Johnson & Johnson Vision Care, Inc. and Alcon occupy positions defined by daily disposable volume scale and extended wear regulatory clearance depth. CooperVision exemplifies the specialized ophthalmic manufacturer archetype through toric and multifocal design customization. Bausch + Lomb sits within the optical retail-to-manufacturing vertical, leveraging distribution heritage with lens case and solution portfolio bundling.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care, Inc. |
| Bausch + Lomb |
| Alcon |
| CooperVision |
| Menicon Co., Ltd. |
| HOYA Corporation |
| EssilorLuxottica |
| Carl Zeiss Meditec AG |
| SEED Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Silicone monomer feedstock from Korean petrochemical suppliers flows through thin-film casting foundries before stratifying into premium oxygen-permeable formats and economy hydrogel tiers downstream. This upstream concentration in Gyeonggi-do and Osaka prefectures compresses margin flexibility for manufacturers while subscription replenishment models reshape end-user pricing expectations.
Pricing Analysis
Extended wear warranty and lens case bundling separate premium silicone hydrogel positioning from unbundled daily disposable economy tiers. Three-tier pricing structure across premium, standard, and economy levels tracks oxygen transmissibility ratings and FDA clearance status. Pricing pressure stems from refractive surgery substitution among myopic patients aged 25-40 in premium urban markets. Independent optical retailers exhibit highest price sensitivity due to channel disintermediation, while integrated eye care chains absorb premium positioning through subscription lock-in.
Supply Chain Analysis
Ocean freight and cold-chain logistics costs from Korean and Japanese casting foundries to distribution hubs in the United States and Western Europe elevate landed costs for imported silicone hydrogel materials. Manufacturing concentrates in South Korea, Japan, and Ireland, with raw material dependencies spanning silicone monomers, hydrophilic polymer bases, and sterile packaging films. Single-source vulnerability around three Korean petrochemical suppliers exposes lens manufacturers to input cost volatility. Distribution runs through wholesale-distributor networks for traditional optical retail, while direct-to-consumer platforms bypass intermediary tiers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over silicone hydrogel casting capacity and downstream subscription platform ownership determine margin capture. Players are pursuing captive supply of thin-film manufacturing lines as the decisive lever.
For Market Incumbents: Cement extended wear regulatory clearance portfolios through accelerated FDA 510(k) submission velocity for next-generation silicone hydrogel formulations. Defend against refractive surgery substitution by deepening toric-multifocal customization capabilities that LASIK cannot replicate. Secure foundry capacity in Korean and Japanese manufacturing clusters through long-term offtake agreements with petrochemical suppliers. For New Entrants and Emerging Players: Enter via India's underpenetrated correction market where spectacle prevalence dwarfs contact lens adoption and optometric retail chains are professionalizing fitting services. Target presbyopia-multifocal convergence designs for aging Western populations as the most penetrable whitespace. Deploy telehealth-integrated subscription platforms with electronic health record connectivity to bypass established wholesale-distributor relationships. For Investors and Strategic Acquirers: FDA draft guidance finalization on antimicrobial lens case standards is the leading indicator that regulatory compliance burdens will consolidate smaller private-label brands and create acquisition opportunities. Position for 5-10 year viability by identifying toric customization technology specialists and subscription platform infrastructure providers as target archetypes. Monitor NMPA biocompatibility testing protocol evolution as the signal for import registration timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Hydrogel Foundry Capacity Expansion | Captive supply from Korean and Japanese casting lines secures oxygen-permeable material continuity. |
| Direct-to-Consumer Platform Integration | Telehealth prescription verification with EHR connectivity displaces traditional optometric office purchasing. |
| Extended Wear Regulatory Clearance | FDA 510(k) pathway acceleration enables overnight-use claims and premium pricing tier access. |
| Toric-Multifocal Combination Development | Simultaneous astigmatism and presbyopia correction addresses aging demographics in Western markets. |
| Biodegradable Packaging R&D Investment | EU Green Deal compliance creates first-mover positioning in sterile blister pack recyclability. |
Research Approach
SEC 10-K filings, FDA 510(k) clearance databases, and EU MDR device registration records formed the secondary backbone for supply chain mapping and regulatory pathway analysis. Primary interviews with silicone hydrogel casting foundry operators, regulatory affairs leads at ophthalmic device manufacturers, and procurement managers at eye care chains validated secondary findings. Bottom-up and top-down triangulation combined patient volume estimates from school-based vision screening mandates with manufacturing capacity data from Korean and Japanese petrochemical suppliers.
Bottom-up modeling tracked daily disposable and extended wear prescription volumes across material type, application indication, and distribution channel. Segmentation dimensions included silicone hydrogel versus hydrogel chemistry, myopia versus presbyopia correction, and eye care chain versus online retailer channel. CAGRs derived from patient population growth curves, replacement cycle frequency shifts, and premium format adoption rates. Industry-specific forecast inputs incorporated PMDA moisture retention documentation timelines and NMPA biocompatibility testing protocol changes.
Revisions become necessary when FDA extended wear guidance finalizes, EU packaging waste rules tighten, or refractive surgery substitution accelerates beyond modeled rates. Forecasts reflect assumptions about regulatory pathway stability, silicone monomer supply continuity, and subscription platform penetration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Spinal Implant Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Deflectable Catheters Market
Medical Devices
North America Laser Hair Removal Market
Medical Devices
Glass Syringe Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Global Medical Composite Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Lactation Massager Market
Medical Devices
3D Printed Implants Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Meniscal Rasps Market
Medical Devices
Intervertebral Implants Market