
 Swine Respiratory Diseases Treatment Market | 2026-2036
Swine Respiratory Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Swine Respiratory Diseases Treatment Market Outlook
mRNA vaccine platform development is tilting R&D investment away from traditional inactivated formulations across the swine health sector. Zoetis Inc. leverages its mammalian cell culture infrastructure to accelerate veterinary mRNA candidates from human pharma spillover. Boehringer Ingelheim Vetmedica Inc. anchors its competitive position through backward integration into adjuvant manufacturing and cold-chain distribution networks. Merck Animal Health specializes in combination respiratory vaccines targeting multiple porcine pathogens simultaneously.
Swine respiratory diseases treatment encompasses pharmaceutical and biological interventions designed to prevent, control, or eliminate bacterial and viral infections affecting the porcine respiratory tract, including porcine reproductive and respiratory syndrome virus (PRRSV), Mycoplasma hyopneumoniae, and Actinobacillus pleuropneumoniae. These treatments function through immunological priming, direct antimicrobial action, or supportive nutritional modulation to maintain lung function and feed conversion efficiency in commercial herds. Vaccines command the largest value share within product type segmentation due to recurring annual revaccination schedules in sow farms and nursery operations. Injectable administration routes dominate therapeutic applications, while oral delivery through water medication systems captures growing share in preventive mass medication protocols among large pork producers.
The USDA Center for Veterinary Biologics oversees licensure of swine vaccines in the United States, requiring efficacy demonstration against field challenge strains before interstate commerce approval. FDA Guidance for Industry 209 and 213 restrict medically important antibiotic use for growth promotion, redirecting pork producers toward preventive vaccine protocols and veterinary feed directive compliance. China's Ministry of Agriculture and Rural Affairs enforces residue monitoring and withdrawal period enforcement that shapes import demand for compliant antimicrobial products. Stakeholders must monitor regulatory divergence between jurisdictions with stringent antibiotic restrictions and those maintaining therapeutic access, as this policy gap will determine which product portfolios retain commercial viability across export markets.
Market Dynamics
mRNA platform migration is compressing development timelines for porcine respiratory vaccines while FDA Guidance 209/213 and EU veterinary medicinal product regulations simultaneously restrict antibiotic growth promoters, forcing producers toward preventive biologicals.
Growth Catalysts
- Veterinary Feed Directive compliance:FDA restrictions on medically important antibiotics in US swine operations redirect capital toward vaccine protocols and diagnostic surveillance systems.
- Integrated sow farm expansion:Large-scale operations in Iowa and North Carolina consolidate nursery-to-finish control, creating captive demand for respiratory disease prevention programs.
- Cold-chain infrastructure maturation:Liquid nitrogen distribution networks now reach 90% of US commercial pork production counties, enabling mRNA vaccine storage at -80°C.
Market Restraints
- Adjuvant supply concentration:Three specialty chemical manufacturers control 80% of veterinary-grade saponin and oil-in-water emulsion inputs, creating price volatility vulnerability.
- PRRSV strain heterogeneity:Genetic divergence between Type 1 and Type 2 porcine reproductive and respiratory syndrome virus lineages forces multi-strain formulation complexity and label claim limitations.
- Biologics manufacturing capex intensity:Mammalian cell culture suites require $50-120 million facility investments with 4-6 year construction timelines, constraining new entrant capacity expansion.
Strategic Opportunities
- Oral vaccine delivery platforms:Microencapsulation technologies enabling water-soluble mRNA administration would capture mass medication protocols currently served by in-feed antibiotics.
- Brazilian integrated producer segment:Underpenetrated preventive vaccination among Mato Grosso and Paraná sow farms with 5,000+ head capacity represents expansion white space for combination respiratory products.
- EU Green Deal veterinary pharmaceutical strategy:Incentives for reduced antimicrobial use create regulatory tailwind for novel immunological products seeking centralized EMA marketing authorization.
Industry Challenges
- mRNA formulation talent scarcity:Veterinary vaccine developers compete with human biopharma for lipid nanoparticle scientists and nucleic acid stability engineers, extending candidate optimization timelines.
- Field efficacy trial design complexity:USDA Center for Veterinary Biologics requires challenge studies against contemporary field isolates, but PRRSV isolate banking and standardization lag behind antigenic drift.
- Multi-pathogen combination stability:Co-formulating Mycoplasma hyopneumoniae bacterins with modified-live viral components risks interference effects that compromise individual antigen immunogenicity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swine Respiratory Diseases Treatment Market |
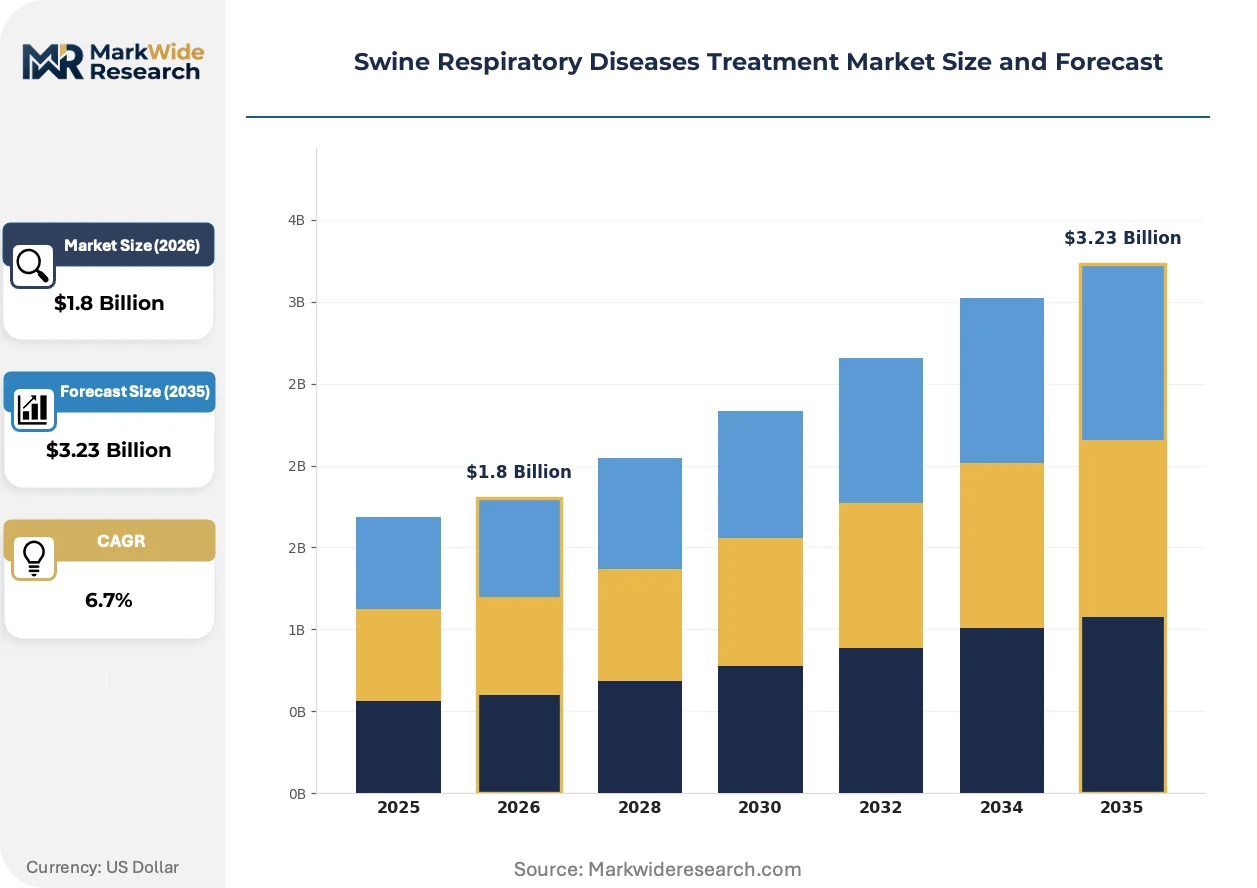
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Antivirals, Antiseptics End User: Pork Producers, Veterinary Clinics, Research Institutions, Animal Farms Treatment Approach: Preventive Care, Therapeutic Care, Combined Therapies, Nutritional Support Administration Route: Oral, Injectable, Topical, Inhalation |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim Vetmedica Inc., Elanco Animal Health, Bayer AG, Ceva Santé Animale, Virbac Group, Vetoquinol, Norbrook, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swine Respiratory Diseases Treatment Market Strategic Shifts
Digital traceability systems and nucleic acid manufacturing advances are restructuring how swine health products move from development through administration, compressing feedback loops between field performance and formulation refinement.
Self-amplifying mRNA (sa-mRNA) constructs are digitizing the dose-response relationship in porcine vaccination by enabling lower antigen mass per dose while maintaining immunogenicity equivalent to conventional platforms. Commercial sow farms with 2,500+ breeding inventory are piloting sa-mRNA protocols for PRRSV and influenza A virus in 2024-2025 cycles. This dose-sparing architecture is compressing manufacturing batch requirements and enabling regional fill-finish facilities closer to concentrated production zones.
EU veterinary medicinal product regulations are mandating environmental risk assessments for all new marketing authorizations, forcing reformulation of oil-based adjuvants toward biodegradable alternatives. Manufacturers must now submit data on metabolite persistence in manure and soil compartments prior to centralized authorization. Sow farm operations in Denmark and the Netherlands are responding by pre-qualifying suppliers with completed environmental impact dossiers, creating first-mover advantage for compliant portfolios.
Diagnostic-driven vaccination protocols are replacing calendar-based revaccination schedules among US integrators with internal veterinary laboratories. Real-time PCR screening of oral fluids and processing fluids now triggers targeted booster administration rather than fixed annual intervals. This pattern is most visible in the Carolina and Midwest production corridors where vertical coordination between genetics, nutrition, and health departments enables rapid protocol adjustment based on pathogen detection thresholds.
Swine Respiratory Diseases Treatment Market Segmentation
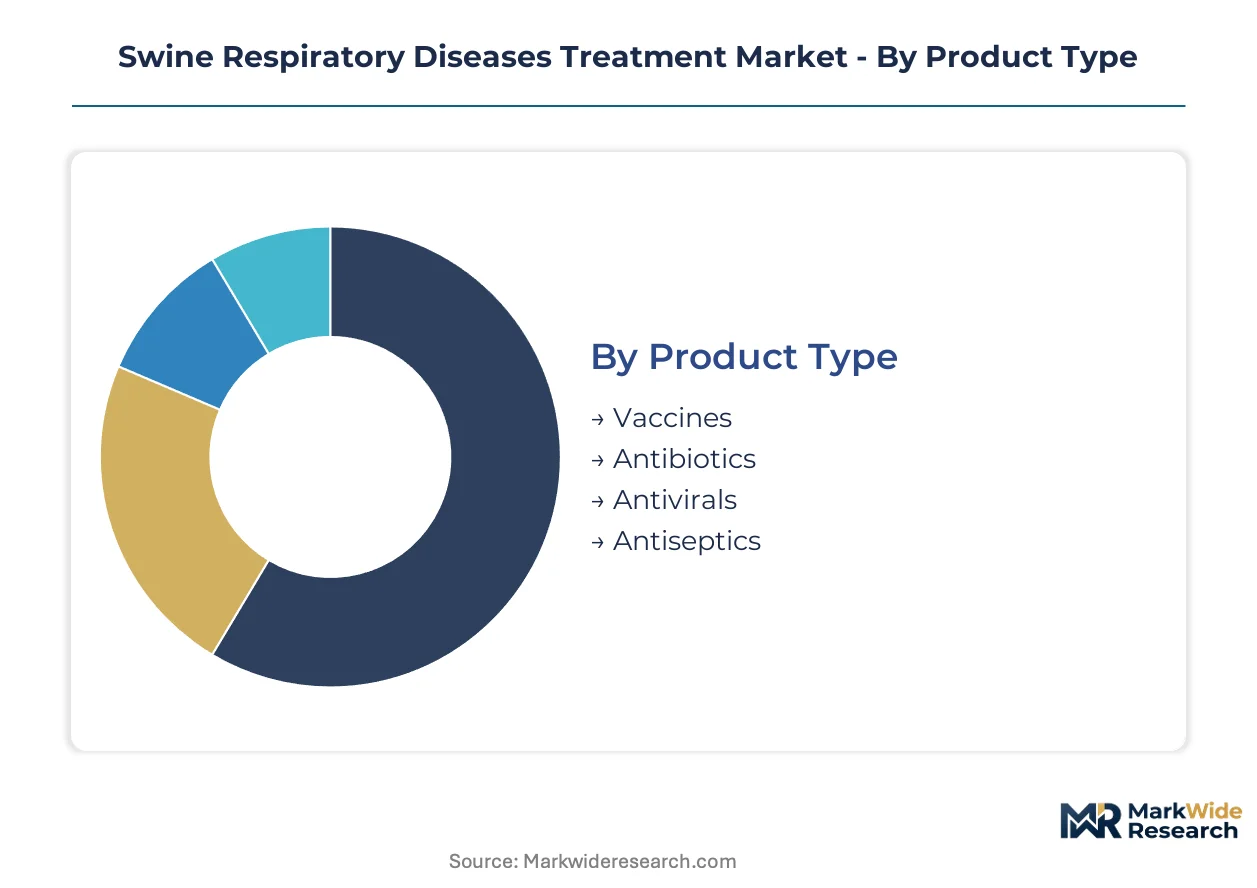
Segmentation in swine respiratory disease treatment reflects divergent procurement patterns between integrated pork operations and independent producers, with product form and delivery mode determining protocol compliance and labor economics across herd sizes.
Product Type:
Biological and chemical interventions span a spectrum from immunological priming to direct antimicrobial action, with cold-chain requirements and regulatory classification shaping distribution economics.
- Vaccines:Modified-live, inactivated, and nucleic acid formulations generate recurring revenue through annual sow revaccination and nursery prime-boost protocols. Demand concentrates among Iowa and North Carolina integrators with captive veterinary staff and internal diagnostic laboratories.
- Antibiotics:Macrolides, tetracyclines, and pleuromutilins face contracting growth-promotion applications under FDA Guidance 213, redirecting volume toward therapeutic metaphylaxis in high-risk transition phases. Water-soluble formulations capture share in large nursery operations.
- Antivirals:Direct-acting agents against PRRSV remain limited to experimental protocols and research herd applications.
- Antiseptics:Chlorhexidine and iodine-based solutions serve environmental disinfection and pre-surgical preparation in farrowing facilities.
Established volume favors vaccines; emerging adoption favors antivirals under development pipelines.
End User:
Customer scale determines purchasing modality, with enterprise procurement systems diverging sharply from distributor-mediated transactions.
- Pork Producers:Operations with 2,500+ sows deploy direct manufacturer contracts for respiratory vaccine bundles, leveraging volume commitments against per-dose pricing. Mato Grosso and Paraná integrators in Brazil represent underpenetrated expansion targets for combination products.
- Veterinary Clinics:Mixed-animal practices in rural US counties serve independent farrow-to-finish producers with intermittent respiratory outbreaks, stocking injectable antibiotics and autogenous vaccine procurement services.
- Research Institutions:University veterinary schools and contract research organizations purchase challenge strain repositories and experimental adjuvants for field efficacy trials required by USDA Center for Veterinary Biologics.
- Animal Farms:Smaller hobby and show-pig operations access respiratory treatments through over-the-counter feed store channels with limited veterinary oversight.
Procurement scale tilts toward pork producers; service intensity concentrates in veterinary clinics.
Treatment Approach:
Protocol philosophy separates preventive capital investment from reactive therapeutic expenditure, with regulatory pressure tilting the balance toward biological prevention.
- Preventive Care:Scheduled vaccination, all-in-all-out management, and air filtration systems dominate respiratory disease economics in Denmark and Netherlands sow farms facing EU Green Deal antimicrobial reduction targets.
- Therapeutic Care:Individual animal treatment with injectable antibiotics persists in finishing barns where PRRSV breakthrough occurs despite vaccination, though withdrawal period compliance constrains product selection.
- Combined Therapies:Simultaneous bacterin and antimicrobial administration addresses Mycoplasma hyopneumoniae coinfection scenarios, requiring careful timing to avoid interference effects.
- Nutritional Support:Feed additives targeting respiratory mucosal immunity capture growing interest as antibiotic alternatives, though efficacy claims face regulatory scrutiny.
Margin stability favors preventive care; acute revenue spikes favor therapeutic interventions.
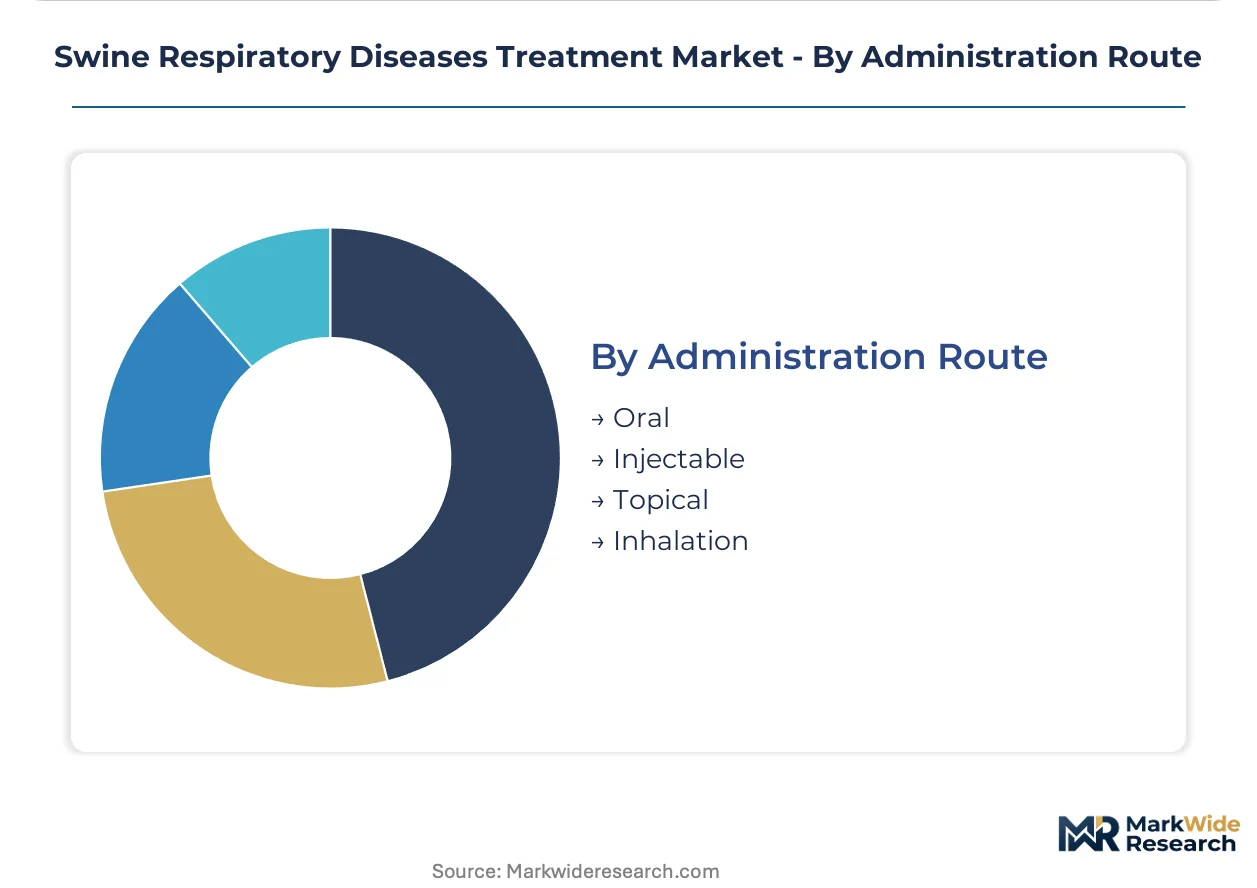
Administration Route:
Delivery mechanics align with labor availability, animal handling infrastructure, and mass medication protocols in continuous-flow versus batch production systems.
- Injectable:Intramuscular and subcutaneous routes ensure precise dosing and rapid onset for individual animal therapy, requiring skilled labor for restraint and needle management in sow farms.
- Oral:Water medication systems enable mass treatment of nursery and grow-finish populations, with flow proportioners and medicator pumps standard equipment in US commercial barns.
- Topical:Limited application to nasal or ocular surfaces for localized antiseptic delivery in individual pig care.
- Inhalation:Nebulized vaccine and antimicrobial delivery remains experimental, with particle size optimization challenges for porcine respiratory deposition.
Labor efficiency favors oral delivery; precision dosing favors injectable administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports live swine genetics and pork protein to China, creating veterinary pharmaceutical trade flows that link South American preventive health protocols to Asian biosecurity standards.
United States
Iowa and North Carolina integrators with 2,500-plus sow capacity drive demand for combination respiratory vaccines. FDA Guidance 209/213 restricts medically important antibiotics, redirecting capital toward biological prevention programs. The Carolina production corridor deploys real-time PCR screening to trigger targeted booster administration.
China
Large-scale sow farms in Sichuan and Henan provinces require compliant antimicrobial products for residue monitoring enforcement. The Ministry of Agriculture and Rural Affairs shapes import demand through withdrawal period regulations. Yangtze River Delta operations consolidate nursery-to-finish control, creating captive demand for respiratory disease prevention.
Brazil
Mato Grosso and Paraná integrators with 5,000-plus head capacity represent underpenetrated targets for preventive vaccination. ANVISA enforces residue monitoring that shapes product selection for export-compliant herds. The Center-West production zone expands cold-chain infrastructure to support mRNA vaccine storage protocols.
Germany
Lower Saxony sow farms face EU Green Deal veterinary pharmaceutical strategy incentives for reduced antimicrobial use. EMA centralized marketing authorization creates regulatory tailwinds for novel immunological products. The North German production belt pilots biodegradable adjuvant formulations ahead of environmental risk assessment mandates.
Denmark
Danish sow operations lead preventive care adoption with scheduled vaccination and all-in-all-out management systems. EU veterinary medicinal product regulations mandate environmental risk assessments for new authorizations. The Jutland production cluster pre-qualifies suppliers with completed environmental impact dossiers.
Swine Respiratory Diseases Treatment Market Competitive Environment
Channel-controlling players compete with product-specialist players across distribution networks and veterinary service relationships. The vendor base concentrates among pharmaceutical conglomerates with human health spillover capabilities and dedicated animal health divisions. Three archetypes dominate: mammalian cell culture infrastructure holders, adjuvant manufacturing integrators, and combination vaccine formulators. Capacity expansion and strategic partnerships constitute the primary competitive moves, with cold-chain distribution networks serving as critical control points.
Within the infrastructure-holder archetype, Zoetis Inc. and Merck Animal Health occupy positions leveraging mammalian cell culture assets for platform technology migration. Boehringer Ingelheim Vetmedica Inc. anchors the adjuvant-integrated tier. These three entities exemplify competitive positioning through backward control over manufacturing inputs and distribution networks rather than product differentiation alone.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim Vetmedica Inc. |
| Elanco Animal Health |
| Bayer AG |
| Ceva Santé Animale |
| Virbac Group |
| Vetoquinol |
| Norbrook |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in legacy attenuated-live vaccine manufacturing across Midwestern US production zones is compressing margins for conventional formulations while simultaneously elevating pricing power for mRNA platform holders with underutilized mammalian cell culture suites. This utilization asymmetry is bifurcating supplier behavior: established players with cold-chain infrastructure defend premium positioning, while capacity-stranded competitors absorb price erosion to maintain fill rates.
Pricing Analysis
mRNA-to-conventional pricing gaps of three-to-five times per dose separate next-generation nucleic acid platforms from prior-generation inactivated formulations, with self-amplifying constructs commanding additional premiums over standard mRNA. Three-tier pricing structure across premium nucleic acid, standard modified-live, and economy inactivated tiers reflects cold-chain compliance costs and USDA Center for Veterinary Biologics label complexity. Pricing pressure stems from antibiotic stewardship regulations redirecting volume toward biologicals, intensifying competition in the standard tier. Large integrated sow farms with direct manufacturer contracts exhibit lowest price sensitivity; independent farrow-to-finish producers purchasing through veterinary clinics show highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration resides with Boehringer Ingelheim Vetmedica Inc., Zoetis Inc., and Merck Animal Health, which collectively control mammalian cell culture capacity for veterinary mRNA production. Geographic supply concentration centers on the United States, Germany, and China, with fill-finish operations drawing from lipid nanoparticle feedstock anchored in North American chemical manufacturing. Raw material dependencies include saponin adjuvants from botanical extraction, oil-in-water emulsion bases, and nucleotide building blocks. Single-source vulnerability in veterinary-grade saponin supply creates structural risk. Distribution runs through captive cold-chain networks owned by major manufacturers rather than third-party logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where USDA licensure timelines and challenge-study requirements create switching costs that protect incumbents while constraining agile entry.
For Market Incumbents: Insulate market position by securing captive adjuvant supply through backward integration into saponin manufacturing or long-term offtake agreements with the three specialty chemical producers controlling veterinary-grade inputs. Expand mammalian cell culture capacity in Iowa and North Carolina production corridors to capture mRNA platform migration before competitor facilities achieve operational readiness. The emerging threat of PRRSV strain heterogeneity demands multi-strain formulation R&D investment to maintain label claim breadth against antigenic drift.
For New Entrants and Emerging Players: Establish a beachhead in Brazilian Mato Grosso and Paraná sow farms with 5,000-plus head capacity, where preventive vaccination penetration remains underdeveloped and ANVISA residue monitoring creates import-aligned demand for compliant products. Oral vaccine delivery platform development represents the most penetrable white space, enabling capture of mass medication protocols currently served by in-feed antibiotics. A go-to-market angle through regional diagnostic laboratory partnerships bypasses incumbent cold-chain infrastructure advantages.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mRNA manufacturing sub-segments, with mammalian cell culture suite investments of $50-120 million and four-to-six year construction timelines creating barriers that favor incumbent expansion over greenfield entry. Long-term viability over the next decade rests on platform technology migration completion and environmental compliance dossier pre-qualification. Acquisition target archetype: mid-scale adjuvant manufacturers with completed veterinary-grade certification. The signal to watch is EU environmental risk assessment mandate enforcement speed, which will determine first-mover advantage timing for biodegradable formulation portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Mammalian cell culture capacity expansion in Iowa and North Carolina secures mRNA platform leadership. |
| Regulatory Approval Pathway | USDA Center for Veterinary Biologics licensure against contemporary PRRSV field isolates defends label claims. |
| Backward Integration | Captive saponin adjuvant production insulates against the three-supplier concentration vulnerability. |
| Geographic Expansion | Brazilian Mato Grosso and Paraná penetration captures underdeveloped preventive vaccination demand. |
| Pipeline Diversification | Self-amplifying mRNA constructs for PRRSV and influenza A virus compress manufacturing batch requirements. |
Study Parameters
The analysis maps nucleic acid platforms, conventional vaccines, antibiotics, and antivirals, each validated through veterinary pharmaceutical executives, sow farm operations managers, regulatory affairs specialists at USDA Center for Veterinary Biologics, and cold-chain logistics coordinators. Primary interviews combined with secondary validation against FDA Guidance 209/213 filings, EMA centralized marketing authorization databases, ANVISA residue monitoring protocols, and EU veterinary medicinal product regulation environmental risk assessment guidelines. Bottom-up and top-down triangulation reconciled procurement volume data from integrated pork producers with manufacturer-reported capacity utilization.
Assumptions held fixed across the analysis window include regulatory enforcement intensity of FDA antibiotic restrictions, EU Green Deal veterinary pharmaceutical strategy implementation pace, and PRRSV strain heterogeneity persistence. Variables tested across sensitivity bands included mRNA platform adoption velocity, cold-chain infrastructure expansion rates, and adjuvant supply concentration resilience. Segmentation dimensions modeled span product type, end user scale, treatment approach philosophy, and administration route. CAGRs derived from installed base growth in sow farm operations, revaccination schedule compliance rates, and per-dose pricing trajectory by technology generation. Industry-specific forecast inputs incorporated diagnostic-driven protocol adoption and environmental compliance pre-qualification timing.
Stress conditions across mRNA manufacturing scale-up delays, adjuvant supply disruption scenarios, and regulatory divergence between antibiotic-restricted and therapeutic-access jurisdictions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions that may require revision upon structural shifts in antimicrobial policy, platform technology efficacy validation, or supply chain reconfiguration. Quarterly review of USDA challenge-study approval cadence, EU environmental risk assessment completion rates, and Brazilian integrated producer vaccination penetration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Software Market
Veterinary
Global Animal Intestinal Health Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Canine Parvovirus Market
Veterinary
Global Animal Parasiticides Market
Veterinary
Global Avian Influenza Vaccines Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Veterinary Home Diagnostics Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
Global Animal Sedative Market
Veterinary
Global Orthopedic Veterinary Implants Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Feline Atopic Dermatitis Treatment Market