
 Global Veterinary Holters Market | 2026-2036
Global Veterinary Holters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Holters Market Foresight
Specialty distributor networks for veterinary cardiology equipment is reshaping how manufacturers reach end users in fragmented geographic markets. IDEXX Laboratories leverages its diagnostic platform integration to bundle Holter data with laboratory information management systems. Dextronix anchors its position through dedicated veterinary focus and product specialization in ambulatory monitoring. Contec Medical Systems competes on manufacturing scale, extending its human-device production capabilities into veterinary-calibrated systems.
Veterinary Holters are portable electrocardiographic recorders adapted for non-human species, typically featuring modified electrode configurations and noise-filtering algorithms to accommodate fur-covered skin and higher heart-rate ranges in small mammals. The primary purpose is continuous ambulatory cardiac monitoring to detect intermittent arrhythmias, assess antiarrhythmic therapy efficacy, and evaluate syncope in companion animals. Wireless Holters command attention as the fastest-expanding product category, driven by owner compliance advantages and reduced artifact from tethered leads. Deployment through cloud-enabled devices concentrates margin pools where recurring software subscription revenue supplements hardware sales. Cardiac monitoring dominates application demand, while post-surgery surveillance represents an emerging use case as orthopedic and soft-tissue procedures in geriatric patients proliferate.
FDA Center for Veterinary Medicine oversees device clearance for diagnostic Holters marketed in the United States, while the EU MDR framework imposes clinical evidence requirements on manufacturers seeking CE marking for wireless and cloud-connected models. Japan's PMDA maintains distinct pharmaceutical and medical device agency pathways that foreign entrants must navigate for market access. Stakeholders should monitor evolving cybersecurity guidance from FDA and PMDA regarding cloud-enabled veterinary devices, as data integrity standards for animal health records increasingly mirror human healthcare precedents.
Market Dynamics
Cloud-enabled Holter systems are compressing traditional hardware-only revenue models as veterinary practices prioritize subscription-based diagnostic platforms over capital-intensive equipment purchases.
Growth Catalysts
- EU MDR Framework:Stricter clinical evidence requirements for wireless veterinary devices are accelerating manufacturer investment in validation studies, raising barrier quality and consolidating credible suppliers.
- Aging companion animal populations:Geriatric cardiology caseloads in Germany and Japan are expanding ambulatory monitoring protocols beyond academic centers into specialty private practices.
- Wireless electrode technology:Improved signal processing algorithms for fur-covered skin are reducing artifact rates and expanding Holter utility to feline and exotic species previously excluded from continuous monitoring.
Market Restraints
- Input cost volatility:Specialized biocompatible adhesives and medical-grade polymers for veterinary electrodes face supply tightness from human-device demand competition.
- Regulatory friction:FDA Center for Veterinary Medicine's evolving cybersecurity guidance for cloud-connected devices is extending premarket notification timelines for software-integrated Holters.
- Technical limitation:Battery chemistry constraints in miniaturized wireless units limit continuous recording duration below the 48-72 hour standard required for intermittent arrhythmia capture in large-breed canines.
Strategic Opportunities
- Underpenetrated geography:Australia's dispersed veterinary network and high companion animal ownership density present channel expansion potential for mobile cardiac monitoring services.
- Regulatory tailwind:Japan's PMDA streamlining of software-as-medical-device pathways creates faster market entry for AI-augmented arrhythmia detection algorithms in veterinary applications.
- Technology convergence:Integration of accelerometer-based activity data with ECG streams is digitizing the correlation between exertion and cardiac events, opening post-surgical rehabilitation monitoring segments.
Industry Challenges
- Certification complexity:Dual compliance requirements for both FDA 510(k) veterinary device clearance and ISO 13485 quality management systems strain mid-tier manufacturer resources.
- Talent scarcity:Veterinary electrophysiology interpretation expertise concentrates in university teaching hospitals, creating bottlenecks for cloud-based diagnostic service scaling.
- Legacy system integration:Practice management software fragmentation across independent clinics impedes seamless Holter data import into existing electronic health record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Holters Market |
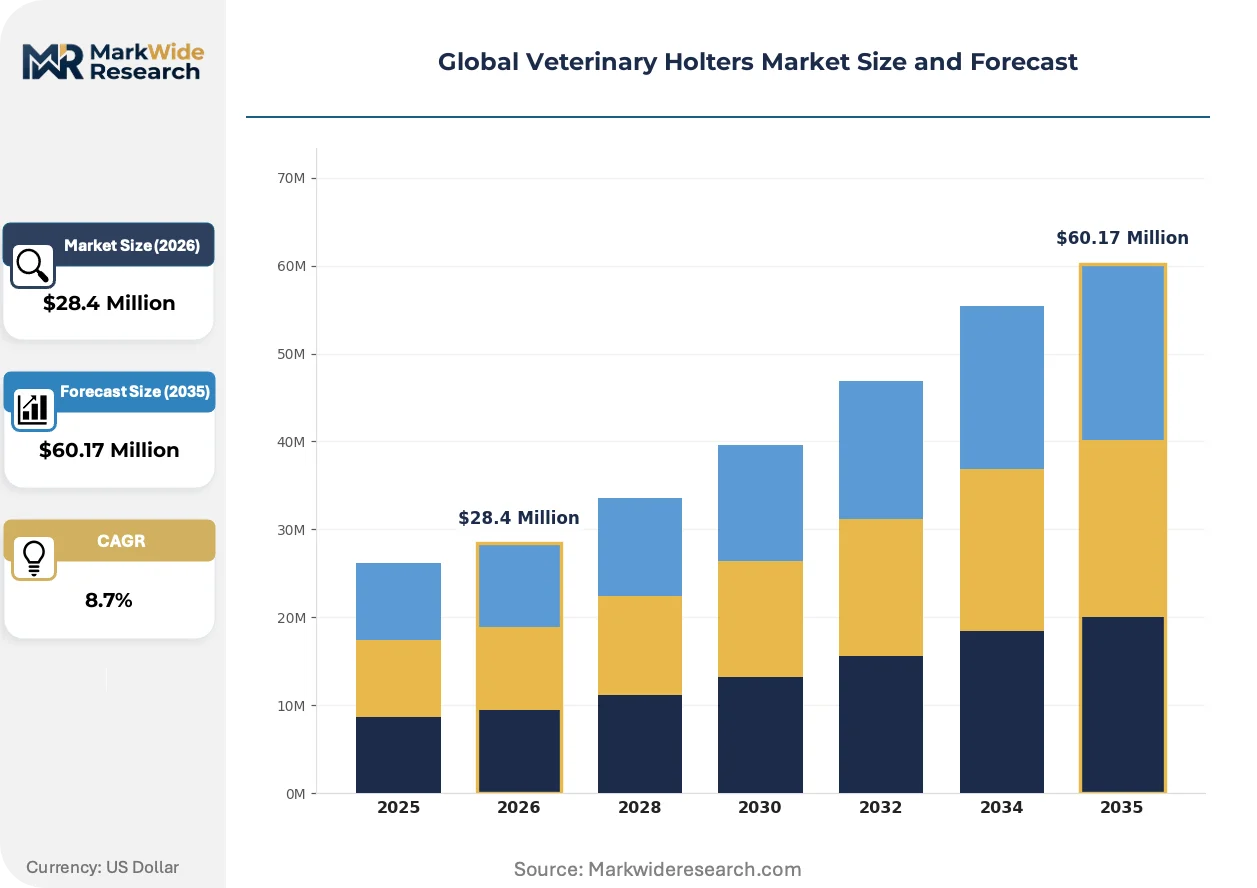
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $60.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3-Lead Holters, 5-Lead Holters, 7-Lead Holters, Wireless Holters Application: Cardiac Monitoring, Respiratory Analysis, Post-Surgery Surveillance, Stress Testing End User: Veterinary Clinics, Animal Research Centers, Diagnostic Laboratories, Specialty Practices Deployment: Standalone Units, Integrated Systems, Cloud-Enabled Devices, Mobile App Enabled Devices |
| Companies Covered | ALBA Medical, Biomedical Instruments, Dextronix, Nasiff Associates, Eickemeyer Veterinary Equipment, Contec Medical Systems, IDEXX Laboratories, Bionet America, VectraCor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Holters Market Shifts & Advancements
Artificial intelligence is penetrating veterinary cardiology at the point of diagnosis, compressing the timeline between data capture and clinical decision while redistributing value from hardware manufacturers to algorithm developers.
Machine learning-based arrhythmia classification is digitizing the interpretation bottleneck that has constrained Holter monitoring scalability in general practice settings. University veterinary teaching hospitals in the United States are piloting FDA-cleared AI modules that flag critical events for clinician review within hours rather than days. This compression is shifting margin capture toward software licensing and away from device hardware.
Japan's PMDA has issued draft cybersecurity guidance for connected veterinary devices that mirrors human medical device data integrity standards. Manufacturers targeting the Japanese market must now demonstrate encryption protocols and breach response procedures previously absent from animal health regulatory frameworks. Wireless Holter systems with cloud transmission capabilities face the steepest compliance adaptation requirements.
Specialty distributor consolidation is reshaping how veterinary cardiology equipment reaches fragmented geographic markets. Independent practices in Germany and France increasingly procure Holter systems through diagnostic platform bundles rather than direct manufacturer relationships. This channel compression privileges suppliers with integrated laboratory information management system compatibility over standalone device vendors.
Global Veterinary Holters Market Segmentation
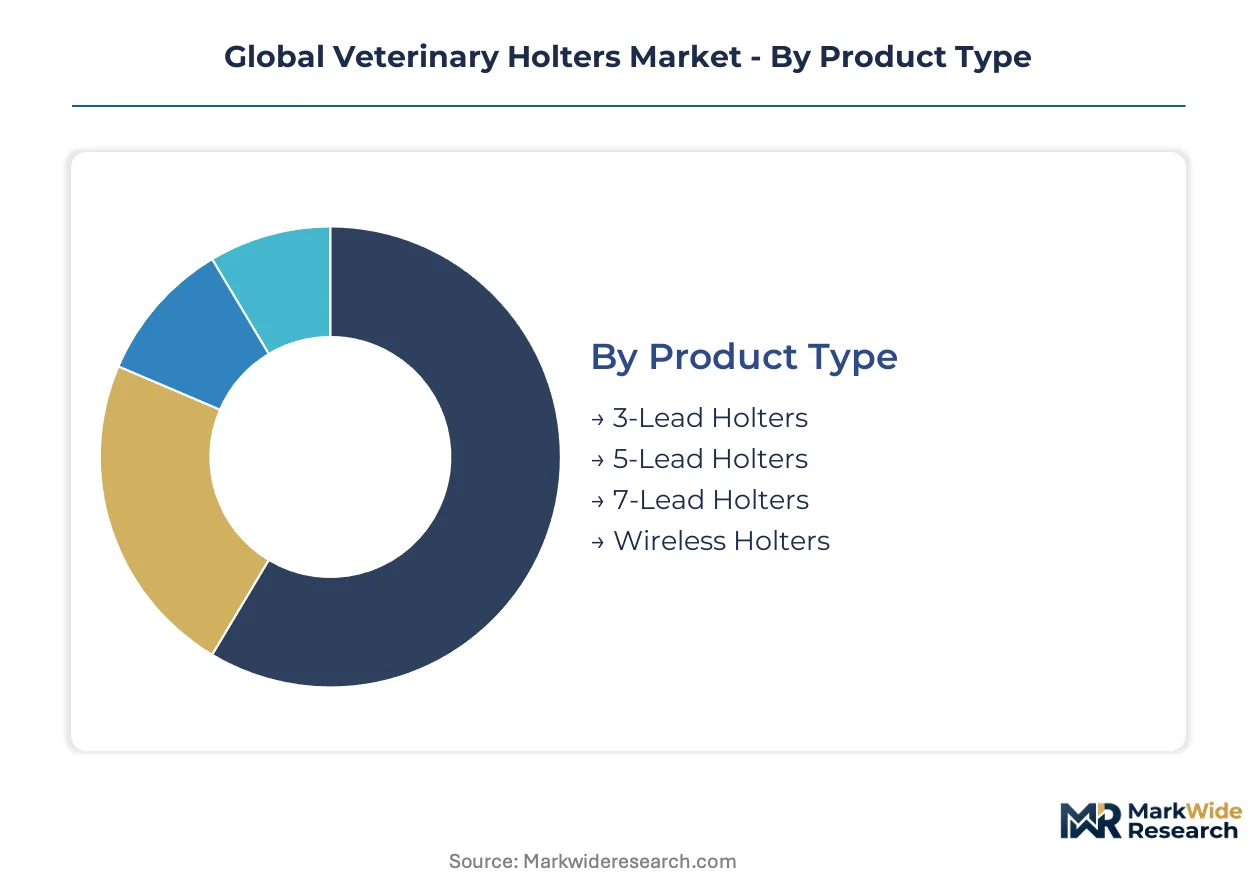
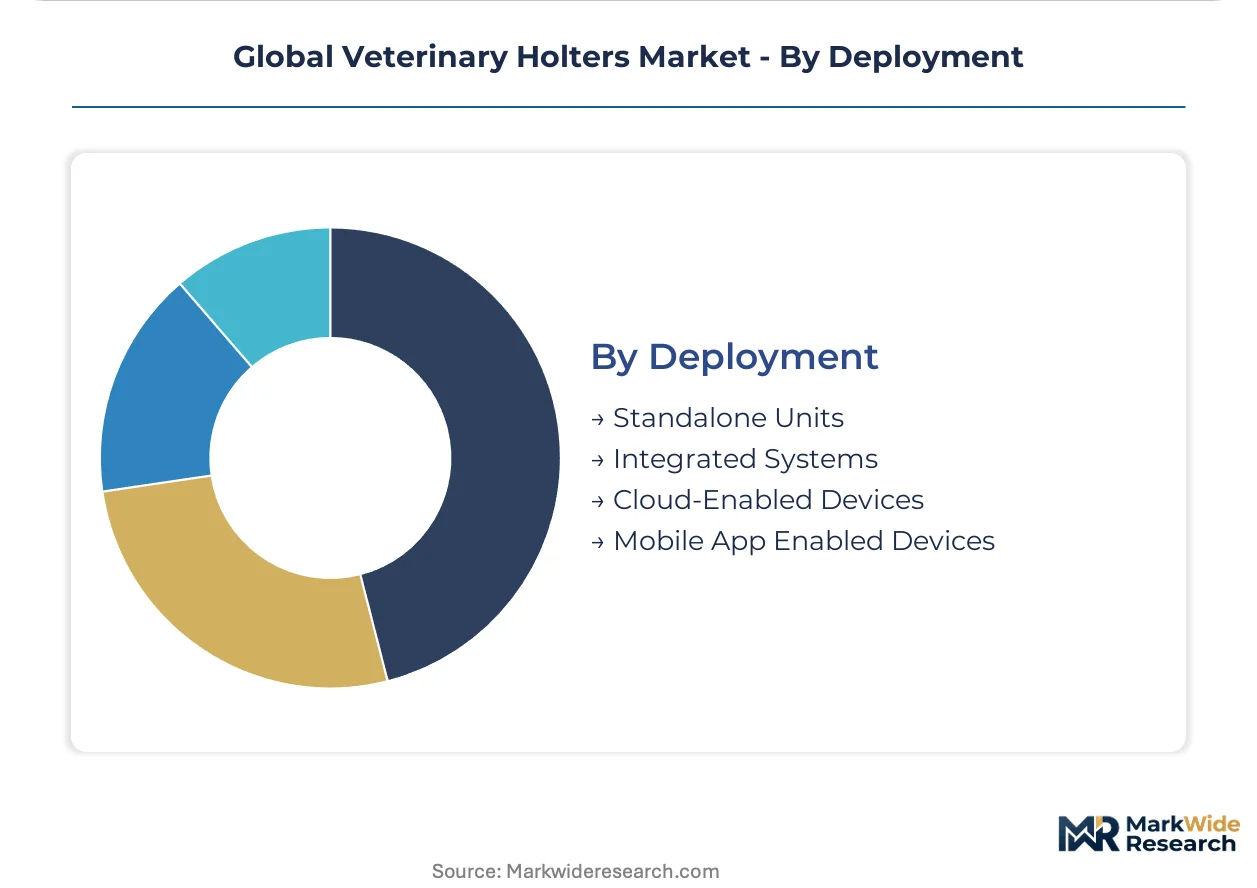
Veterinary Holter segmentation reveals divergent equipment lifecycles across product architectures. Deployment models and lead configurations compress replacement cycles differently, while application specialization and end-user scale dictate purchasing frequency and upgrade timing.
Product Type:
Replacement velocity separates product tiers, with wireless units cycling fastest due to battery degradation and software obsolescence, while wired lead systems persist longer in stable clinical environments.
- 3-Lead Holters:Compact electrode arrays optimized for feline and small-breed canine monitoring where anatomical constraints limit lead placement. German specialty practices favor these units for routine geriatric screening programs, though adhesive artifact rates on fur-covered skin constrain signal reliability during extended recording.
- 5-Lead Holters:Expanded electrode geometry captures multi-vector cardiac electrical activity for arrhythmia localization in large-breed dogs. University veterinary teaching hospitals in the United States standardize on this configuration for protocol consistency across cardiology residencies, driving replacement demand as calibration standards tighten.
- 7-Lead Holters:Comprehensive spatial mapping for complex congenital defect assessment in exotic species and equine applications.
- Wireless Holters:Tether-free designs with Bluetooth transmission to base stations or cloud platforms, gaining share fastest in owner-compliance-sensitive companion animal markets.
3-Lead Holters dominate installed base. Wireless Holters are where expansion concentrates.
Application:
Clinical urgency and reimbursement patterns segment applications by procurement priority, with emergency cardiac workups commanding immediate capital allocation versus elective post-surgical monitoring.
- Cardiac Monitoring:Continuous ambulatory ECG for intermittent arrhythmia detection, antiarrhythmic therapy titration, and syncope etiology determination. Japan's aging companion animal population drives ambulatory program expansion beyond academic centers into Tokyo and Osaka specialty practices, with PMDA cybersecurity guidance accelerating cloud-connected adoption.
- Respiratory Analysis:Integrated impedance pneumography for sleep-disordered breathing assessment in brachycephalic breeds. European reference laboratories in France and the Netherlands develop proprietary algorithms for this emerging indication, though clinical validation lags behind cardiac applications.
- Post-Surgery Surveillance:Orthopedic and soft-tissue procedure monitoring for anesthetic complication detection in geriatric patients.
- Stress Testing:Exercise-induced arrhythmia provocation for breeding soundness evaluation in working dog lines.
Cardiac Monitoring commands capital priority. Post-Surgery Surveillance is climbing the fastest as procedural volumes rise.
End User:
Purchasing sophistication varies sharply, with high-throughput reference laboratories demanding API-integrated platforms while independent clinics prioritize standalone simplicity.
- Veterinary Clinics:General practice settings handling sporadic cardiac cases with limited in-house interpretation expertise. Australia's dispersed network of independent clinics presents channel complexity for manufacturers, with procurement decisions fragmented across individual practice owners rather than centralized health systems.
- Animal Research Centers:Preclinical toxicology and cardiovascular safety pharmacology studies requiring GLP-compliant data integrity. These facilities demand validated hardware with audit trails, extending sales cycles but locking in multi-year service contracts.
- Diagnostic Laboratories:Centralized ECG interpretation services aggregating Holter data from referring practices.
- Specialty Practices:Cardiology-focused hospitals with boarded specialists performing complex electrophysiology.
Diagnostic Laboratories dominate installed base. Specialty Practices are gaining share fastest as referral networks consolidate.
Deployment:
Integration depth determines margin structure, with cloud-enabled subscriptions capturing recurring revenue while standalone hardware exhausts value at point of sale.
- Standalone Units:Self-contained recorders with local storage and manual data download via USB or SD card. These systems persist in price-sensitive markets and regions with unreliable internet infrastructure, though their isolation from practice management software creates workflow friction.
- Integrated Systems:Direct connectivity to laboratory information management systems and electronic health records. IDEXX Laboratories leverages this architecture to bundle Holter data with hematology and chemistry panels, creating platform stickiness in the United States.
- Cloud-Enabled Devices:Automatic encrypted transmission to remote servers with AI-augmented preliminary interpretation.
- Mobile App Enabled Devices:Smartphone-tethered designs appealing to mobile veterinary services and house-call practitioners.
Standalone Units dominate installed base. Cloud-Enabled Devices are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty veterinary cardiology clusters concentrate near university teaching hospitals with established electrophysiology programs. The United States, Germany, Japan, Australia, and Brazil host the most developed ambulatory monitoring infrastructures.
United States
University veterinary teaching hospitals in North Carolina and California drive protocol standardization for canine Holter monitoring. FDA Center for Veterinary Medicine oversees 510(k) clearance pathways for diagnostic devices. The Research Triangle Park corridor anchors concentrated cardiology referral networks.
Germany
Geriatric companion animal populations in Bavaria and North Rhine-Westphalia expand ambulatory cardiac programs beyond academic centers. EU MDR framework imposes tightened clinical evidence requirements on wireless ECG systems. Munich specialty practices pioneer cloud-enabled monitoring integration.
Japan
Aging pet demographics in Tokyo and Osaka metropolitan areas accelerate specialty cardiology service expansion. PMDA maintains distinct pharmaceutical and medical device agency pathways for foreign entrants. Kansai region veterinary hospitals pilot AI-augmented arrhythmia detection modules.
Australia
Dispersed veterinary networks in New South Wales and Victoria create channel complexity for equipment distribution. TGA regulates medical device safety standards applicable to veterinary adaptations. Sydney reference laboratories aggregate Holter interpretation services for rural referring practices.
Brazil
São Paulo and Rio de Janeiro specialty practices develop ambulatory monitoring capabilities for large-breed working dogs. ANVISA oversees medical device registration requirements for imported diagnostic equipment. Southeastern veterinary teaching hospitals establish regional cardiology referral hubs.
Global Veterinary Holters Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with dedicated hardware manufacturing. The vendor base stratifies between diagnostic platform bundlers and standalone device fabricators. Three archetypes dominate: laboratory information system integrators, veterinary-focused monitoring specialists, and human-device manufacturers extending into animal health. Competitive moves concentrate on cloud subscription model adoption and distributor network consolidation.
Among platform integrators, IDEXX Laboratories exemplifies the diagnostic bundling archetype through laboratory system compatibility. Dextronix occupies a position within the veterinary-specialist tier with dedicated ambulatory monitoring focus. Contec Medical Systems represents the manufacturing-scale archetype, extending production capabilities from human-calibrated systems into veterinary adaptations.
| Leading Market Players |
|---|
| ALBA Medical |
| Biomedical Instruments |
| Dextronix |
| Nasiff Associates |
| Eickemeyer Veterinary Equipment |
| Contec Medical Systems |
| IDEXX Laboratories |
| Bionet America |
| VectraCor |
| Others |
Supply & Pricing Matrix
EU MDR compliance costs for wireless veterinary devices are compressing margin structures across manufacturer tiers while simultaneously concentrating procurement power among platform-integrated suppliers with captive validation capabilities. This regulatory chokepoint widens pricing spreads between CE-marked cloud-enabled systems and legacy standalone units, reshaping how component sourcing and final assembly geography align with certification burden distribution.
Pricing Analysis
Volume-discount tiering structures separate enterprise diagnostic laboratory contracts from independent clinic procurement, with three-tier pricing stratification across premium cloud-integrated, standard wired-system, and economy refurbished-hardware levels. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification depth, with university teaching hospitals absorbing premium positioning while Australia's dispersed independent clinics drive cost compression. Pricing pressure stems from cloud subscription models displacing capital-intensive hardware purchases, eroding upfront equipment margins. General practice settings exhibit highest price sensitivity, whereas specialty cardiology hospitals prioritize integration over unit cost.
Supply Chain Analysis
Extended payment terms from Chinese component suppliers are financing working capital cycles for assembly operations in Germany and the United States, where final calibration and regulatory documentation occur. Manufacturing draws from specialized biocompatible adhesive producers in Japan, medical-grade polymer fabricators in Germany, and semiconductor foundries in Taiwan. Single-source vulnerability concentrates in Bluetooth module supply from Taiwan-based vendors. Distribution runs through diagnostic platform bundlers IDEXX Laboratories and specialty veterinary distributors Eickemeyer Veterinary Equipment rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine-enabled cardiac consultation platforms threaten to disintermediate hardware-centric Holter vendors by collapsing interpretation value into software-only offerings, forcing incumbents to defend installed base through data ecosystem lock-in.
For Market Incumbents: Build switching-cost moats through laboratory information management system integration that embeds Holter data within broader diagnostic workflows. Deepen backward integration into electrode manufacturing to secure biocompatible adhesive supply against human-device demand competition. Defend against AI-only interpretation entrants by bundling hardware with cloud-based preliminary analysis services that preserve clinician oversight touchpoints. For New Entrants and Emerging Players: Establish a beachhead in Australia's dispersed independent clinic network where platform bundlers have weakest penetration and procurement fragmentation creates white-space opportunity. Target mobile veterinary services with smartphone-tethered Holter designs that bypass capital-intensive cloud infrastructure requirements. Pursue regulatory arbitrage by securing Japan PMDA software-as-medical-device clearance ahead of FDA cybersecurity guidance finalization. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors diagnostic bundlers with captive distribution over standalone device fabricators. Long-term viability hinges on recurring software revenue attachment rates rather than hardware replacement cycles. Acquisition target archetype: veterinary-focused monitoring specialists with established ISO 13485 quality systems and regulatory dossiers in multiple geographies. Monitor FDA cybersecurity guidance implementation timelines as inflection indicator for cloud-enabled device valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | IDEXX Laboratories bundles Holter data with hematology panels, creating diagnostic ecosystem stickiness. |
| AI-Augmented Interpretation Development | Machine learning modules compress arrhythmia classification timelines, shifting margin capture toward software licensing. |
| EU MDR Validation Investment | Clinical evidence requirements for wireless devices raise barrier quality and consolidate credible supplier pools. |
| Specialty Distributor Consolidation | Channel compression privileges platform-compatible vendors over standalone device manufacturers in fragmented markets. |
| Electrode Manufacturing Backward Integration | Captive biocompatible adhesive production secures input supply against human medical device demand competition. |
Research Methodology
Operator-level perspectives from veterinary cardiologists, diagnostic laboratory directors, biomedical equipment procurement managers, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation across FDA 510(k) device clearances, EU MDR technical documentation databases, PMDA submission records, and veterinary teaching hospital procurement records. Bottom-up unit shipment estimates triangulated against top-down diagnostic platform revenue disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeling across product architecture, lead configuration, deployment model, application specialty, and end-user scale dimensions. CAGRs derived from fitted growth curves applied to veterinary caseload projections and equipment replacement cycle assumptions. Forecast inputs incorporated geriatric companion animal demographic trends, cloud subscription adoption trajectories, and regulatory pathway timeline uncertainties.
Sensitivities concentrate around FDA cybersecurity guidance finalization, EU MDR clinical evidence requirement enforcement intensity, and cloud-enabled device data integrity standard evolution. Forecasts reflect assumptions regarding wireless electrode technology maturation and AI interpretation module regulatory clearance pathways. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Veterinary MRI Market
Veterinary
Spay and Neuter Market
Veterinary
Veterinary Immunodiagnostics Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Veterinary Thermography Market
Veterinary
Global Animal Intestinal Health Market
Veterinary
Homeopathic Veterinary Medicines Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Veterinary Lasers Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Clostridium Vaccine (Animal Health) Market
Veterinary
Veterinary CRO and CDMO Market
Veterinary
North America and Europe Veterinary Telehealth Market