
 Gastritis Market | 2026-2036
Gastritis Market Size, Share, and Industry Trends Forecast 2026-2036
Gastritis Market Foresight
Fixed-dose combination bundling of proton pump inhibitors with antibiotic regimens is restructuring how gastroenterology clinics purchase Helicobacter pylori therapies. Pfizer Inc. leverages its manufacturing scale to supply broad-spectrum antibiotic components, while Takeda Pharmaceutical Company Limited anchors the premium branded proton pump inhibitor segment through specialized gastroenterology channels. Novartis AG differentiates via cytoprotective agent portfolios that target erosive gastritis subpopulations.
Gastritis denotes mucosal inflammation of the stomach lining, typically diagnosed through endoscopic biopsy with histological grading of neutrophil infiltration and H. pylori colonization density. The condition's primary commercial purpose centers on pharmaceutical intervention to prevent ulceration progression and gastric cancer risk stratification. Proton pump inhibitors command the largest revenue pool among product type segments due to chronic therapy dependence and patent extension strategies, while antibiotics represent the fastest-growing category as resistance-guided triple and quadruple regimens expand. Within therapy areas, chronic gastritis generates sustained prescription refill volumes, whereas acute gastritis episodes drive emergency department antacid demand.
The FDA governs New Drug Application and Abbreviated New Drug Application pathways for gastroenterology therapeutics, while the EMA's Committee for Medicinal Products for Human Use coordinates centralized marketing authorization across European member states. These frameworks shape demand by determining bioequivalence standards for generic substitution and pediatric indication expansions. Stakeholders must monitor how pharmacovigilance database signals on long-term proton pump inhibitor safety influence prescriber behavior and formulary placement decisions.
Market Dynamics
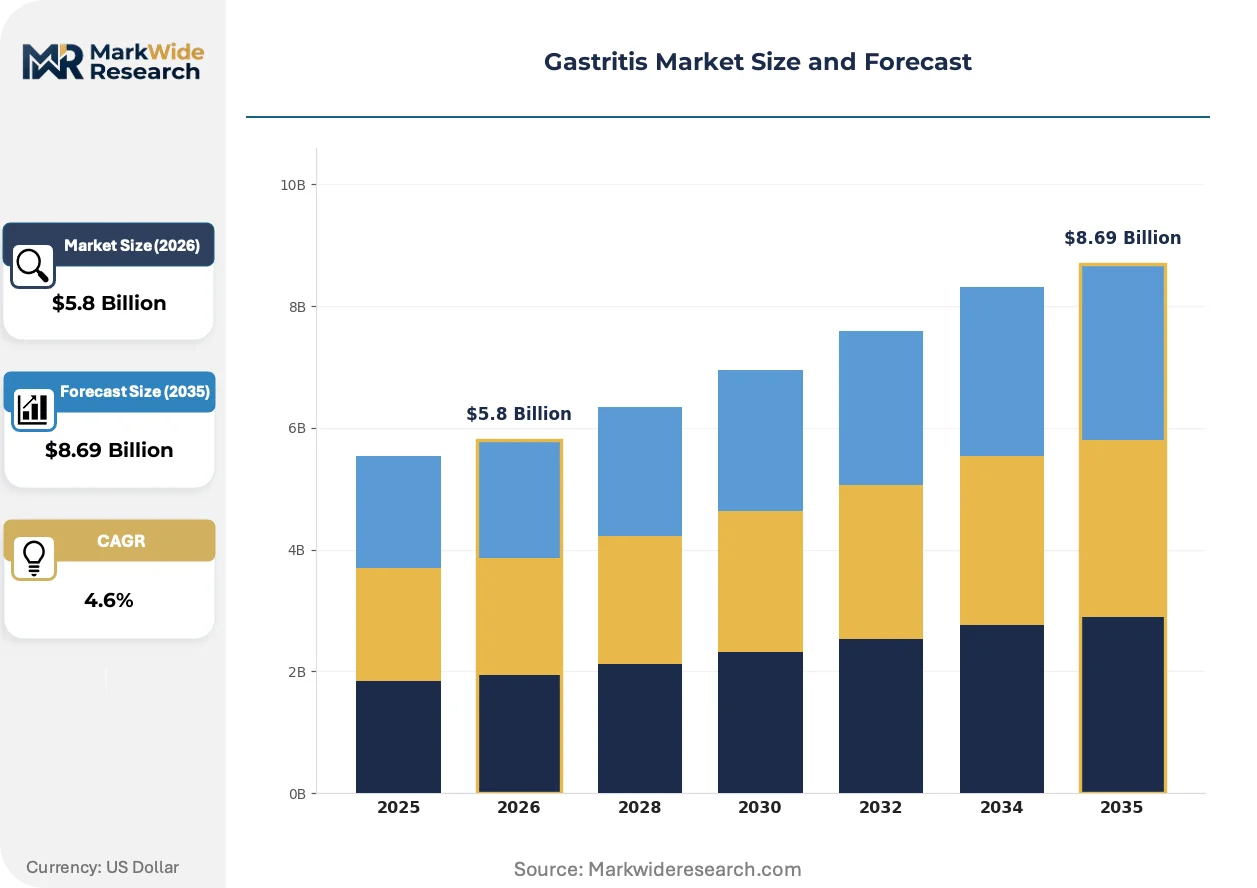
Hospital procurement of proton pump inhibitor therapies is intensifying as healthcare systems prioritize outpatient gastric acid management and resistance-guided H. pylori eradication protocols reshape prescribing patterns across gastroenterology clinics.
Growth Catalysts
- FDA's streamlined ANDA review pathways:The abbreviated new drug application process accelerates generic gastroenterology drug entry, expanding patient access to affordable acid suppression therapies.
- Aging demographics in the United States:Higher diagnostic rates and chronic therapy dependence among elderly populations sustain prescription refill volumes for maintenance regimens.
- Fixed-dose combination bundling:Gastroenterology clinics increasingly purchase proton pump inhibitors co-formulated with antibiotics, streamlining H. pylori treatment protocols and improving adherence.
Market Restraints
- Antibiotic resistance surveillance costs:Resistance-guided triple and quadruple regimens require sophisticated microbiology infrastructure that strains clinic laboratory budgets.
- Long-term proton pump inhibitor safety signals:Pharmacovigilance database concerns regarding bone density and renal function influence prescriber caution and formulary restrictions.
- Supply concentration in active pharmaceutical ingredients:Dependence on limited manufacturing sources for omeprazole and esomeprazole intermediates creates vulnerability to quality disruptions.
Strategic Opportunities
- Underpenetrated cytoprotective agent segments:Erosive gastritis subpopulations represent addressable white space for mucosal defense therapies beyond acid suppression.
- Pediatric indication expansions:Regulatory frameworks enabling bioequivalence studies in younger age groups open maintenance therapy markets currently served off-label.
- Biomarker-guided therapy selection:Convergence of molecular diagnostics with gastroenterology practice enables personalized H. pylori eradication protocols.
Industry Challenges
- Histopathology workforce scarcity:Endoscopic biopsy grading requires specialized gastrointestinal pathologists, creating diagnostic bottlenecks in community hospital settings.
- Legacy formulary integration friction:New quadruple regimens face resistance from pharmacy and therapeutics committees accustomed to standard triple therapy protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastritis Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antacids, Proton Pump Inhibitors, H2 Receptor Antagonists, Antibiotics, Cytoprotective Agents Therapy Area: Acute Gastritis, Chronic Gastritis, Erosive Gastritis, Atrophic Gastritis, Reactive Gastropathy End User: Hospitals, Specialized Clinics, Gastroenterology Centers, Ambulatory Surgical Centers Delivery Mode: Oral Medication, Injectable Formulations, Transdermal Patches, Nasogastric Administration |
| Companies Covered | AstraZeneca PLC, Sun Pharmaceutical Industries, Novartis AG, Perrigo Pharmaceutical, Lupin Ltd, Pfizer Inc., AbbVie Inc., Johnson & Johnson, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastritis Market Shifts & Advancements
Pharmaceutical intervention patterns are restructuring around resistance surveillance, combination therapy optimization, and channel consolidation between manufacturers and institutional purchasers.
Biosimilar proton pump inhibitor development is converging with sophisticated bioequivalence testing platforms that demonstrate pharmacokinetic parity with reference products. Large hospital systems and group purchasing organizations are accelerating adoption of these alternatives to reduce pharmaceutical expenditure. This convergence is compressing brand premium retention and forcing originator manufacturers toward specialized gastroenterology channel strategies.
The EMA's Committee for Medicinal Products for Human Use has tightened centralized marketing authorization requirements for pediatric gastroenterology indications. Manufacturers must now submit extended safety databases for chronic acid suppression in younger populations. European member states are responding with staggered formulary adoption timelines that favor established adult indications while demanding additional real-world evidence.
Integrated delivery networks are consolidating pharmaceutical procurement decisions under centralized pharmacy benefit managers. Community gastroenterology clinics are losing direct purchasing autonomy as health system administrators negotiate enterprise-wide proton pump inhibitor contracts. This concentration is most visible in the United States, where vertical health system integration has absorbed previously independent specialty practices.
Gastritis Market Segmentation
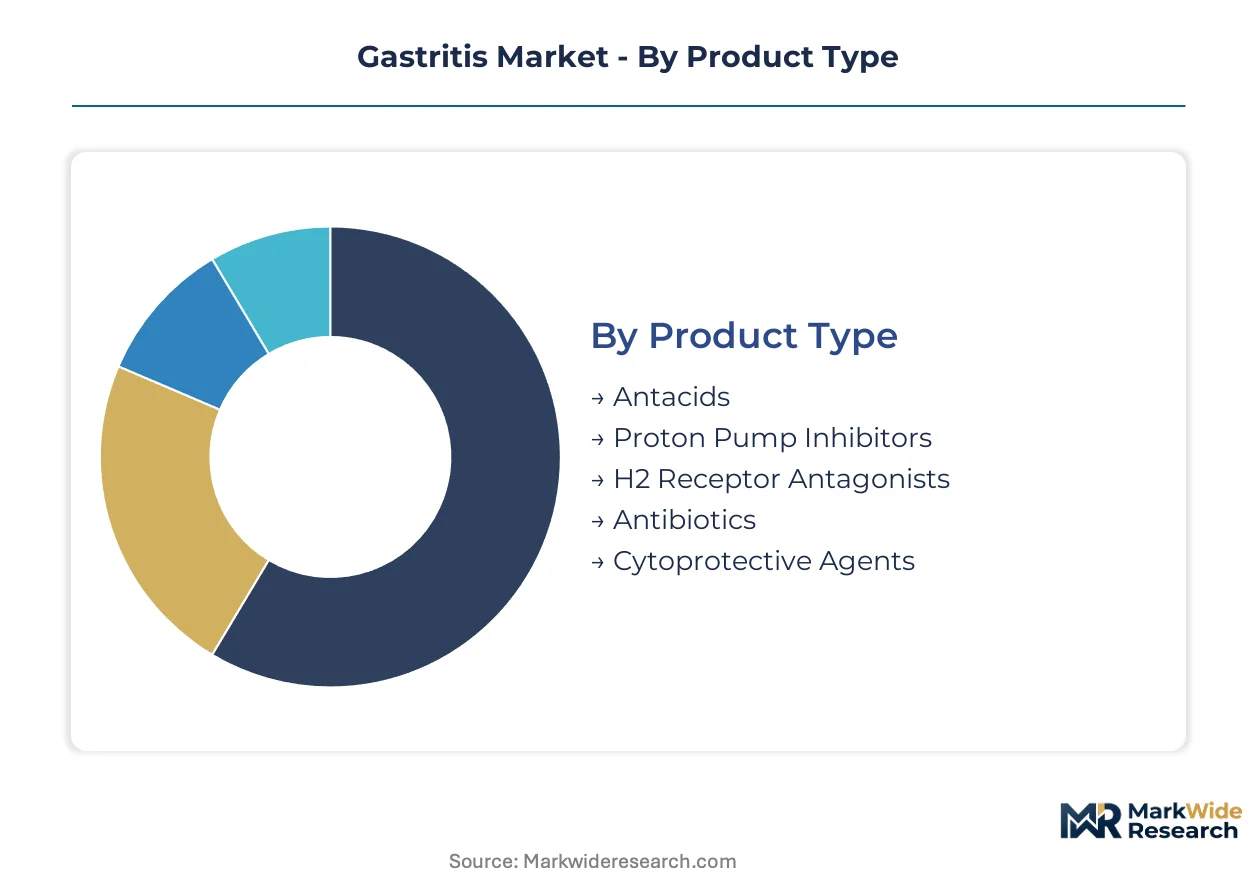
Segmentation in the gastritis market reveals distinct procurement patterns across therapeutic modalities and care settings. Hospital formulary committees and gastroenterology clinics prioritize different product attributes based on patient acuity, reimbursement structures, and resistance surveillance capabilities.
Product Type:
Integration depth varies sharply across pharmaceutical categories, with standalone maintenance therapies dominating chronic care while combination regimens embed into structured eradication protocols.
- Proton Pump Inhibitors:These agents suppress gastric acid secretion through irreversible H+/K+ ATPase inhibition, enabling mucosal healing in erosive and chronic presentations. Hospital procurement in the United States concentrates on esomeprazole and omeprazole formulations for outpatient gastric acid management, driven by chronic therapy dependence and patent extension strategies that sustain prescription refill volumes.
- Antibiotics:Clarithromycin, amoxicillin, metronidazole, and tetracycline components target H. pylori eradication in triple and quadruple regimens. Resistance-guided prescribing patterns across gastroenterology clinics are expanding demand for these agents, though sophisticated microbiology infrastructure requirements strain laboratory budgets.
- Antacids:Rapid acid neutralization for symptomatic relief in acute episodes, purchased primarily through emergency department formularies.
- H2 Receptor Antagonists:Histamine-mediated acid suppression for milder cases, facing formulary displacement by proton pump inhibitors in most health systems.
- Cytoprotective Agents:Mucosal defense therapies including sucralfate and misoprostol for erosive gastritis subpopulations, representing underpenetrated white space beyond acid suppression.
Proton pump inhibitors lead volumes today; antibiotics are gaining share fastest.
Therapy Area:
Cost tier stratification separates maintenance therapies with sustained reimbursement from acute interventions reimbursed through episode-based payment models.
- Chronic Gastritis:Persistent mucosal inflammation requiring long-term acid suppression generates sustained prescription refill volumes. The United States sustains the largest addressable population due to aging demographics and high diagnostic rates through routine endoscopic surveillance.
- Erosive Gastritis:Visible mucosal breaks with active bleeding risk command premium pricing for cytoprotective combination regimens. Gastroenterology centers in integrated delivery networks prioritize these patients for specialized channel access.
- Acute Gastritis:Sudden-onset presentations drive emergency department antacid demand and short-course proton pump inhibitor prescribing.
- Atrophic Gastritis:Glandular loss with intestinal metaplasia requires gastric cancer risk stratification protocols, creating diagnostic and surveillance revenue streams.
- Reactive Gastropathy:Chemical injury patterns from NSAIDs or bile reflux, managed through withdrawal protocols and protective agents.
Chronic gastritis commands the largest revenue pool; erosive gastritis carries the highest per-patient pharmaceutical expenditure.
End User:
Customer type determines purchasing autonomy, with centralized health system administrators displacing independent clinic decision-making.
- Hospitals:Enterprise-wide proton pump inhibitor contracts negotiated by pharmacy benefit managers dominate procurement, particularly in vertically integrated United States health systems absorbing previously independent specialty practices.
- Gastroenterology Centers:Specialized channels retain preference for premium branded agents and resistance-guided therapy selection, though direct purchasing autonomy is eroding.
- Specialized Clinics:Community-based practices losing formulary independence as integrated delivery networks consolidate pharmaceutical decisions.
- Ambulatory Surgical Centers:Limited scope for gastritis intervention, primarily perioperative acid suppression for endoscopic procedures.
Hospitals aggregate the largest procurement volumes; gastroenterology centers preserve the highest brand premium tolerance.
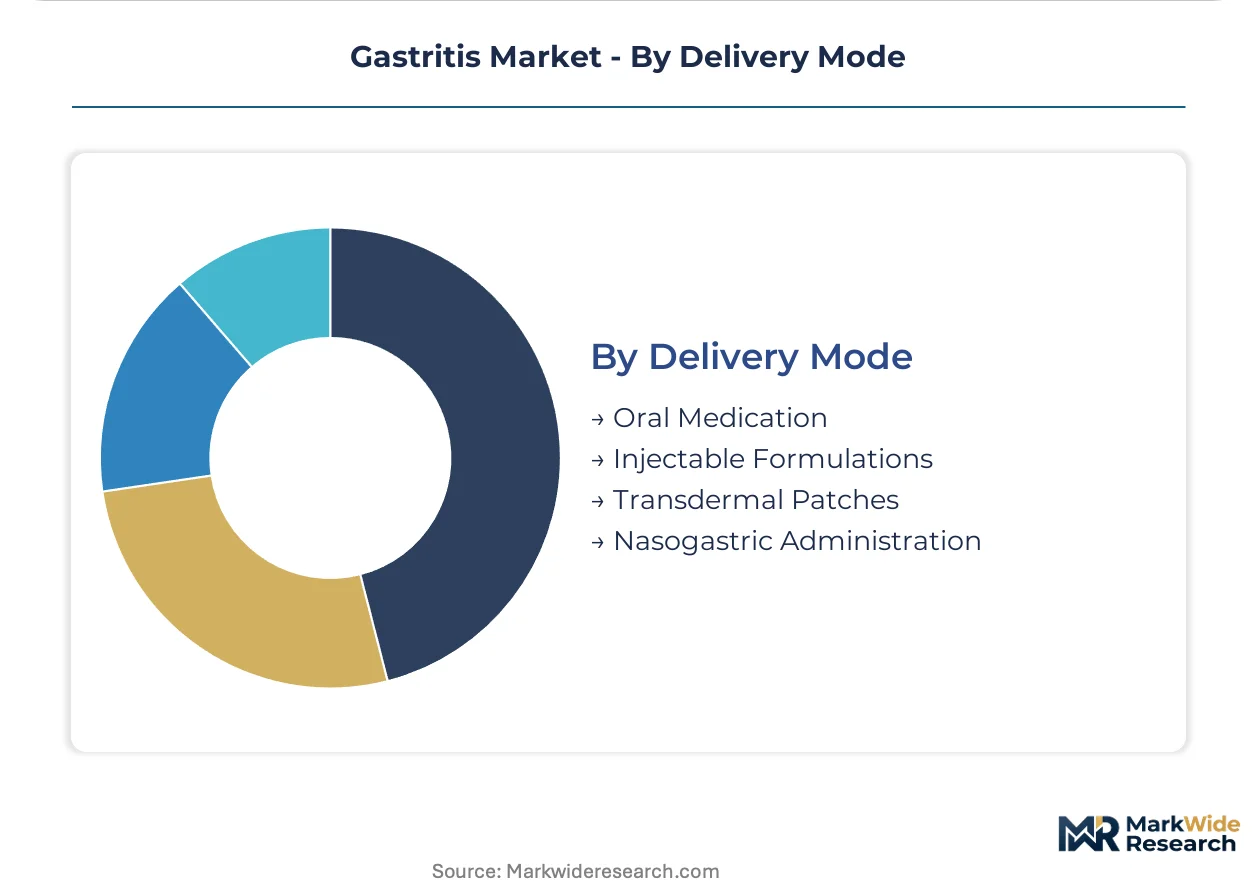
Delivery Mode:
Maturity gradients separate established oral administration from emerging formats requiring bioequivalence validation and reimbursement establishment.
- Oral Medication:Tablets and capsules dominate maintenance therapy, with fixed-dose combination bundling streamlining H. pylori treatment adherence.
- Injectable Formulations:Intravenous proton pump inhibitors for bleeding ulcers or perioperative prophylaxis in hospital settings.
- Nasogastric Administration:Enteral access for intensive care or post-surgical patients unable to tolerate oral intake.
- Transdermal Patches:Experimental formats for continuous acid suppression, lacking established bioequivalence pathways.
Oral medication anchors the market; injectable formulations expand fastest in surgical and critical care applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proton pump inhibitor therapy originated in European pharmaceutical laboratories during the 1980s, with Swedish and British research institutions pioneering the H+/K+ ATPase inhibition mechanism that now dominates gastric acid suppression worldwide.
United States
Medicare Part D reimbursement structures and aging demographics sustain prescription refill volumes for chronic maintenance regimens. The FDA's streamlined ANDA review pathways accelerate generic gastroenterology drug entry, expanding patient access to affordable acid suppression therapies. Hospital systems in the Northeast Corridor and California consolidate enterprise-wide proton pump inhibitor contracts under centralized pharmacy benefit managers.
Germany
EMA centralized marketing authorization requirements shape bioequivalence standards for generic substitution across member states. The country's statutory health insurance funds negotiate reference pricing for acid suppression therapies, compressing brand premium retention. Pharmaceutical manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia supply active pharmaceutical ingredients for omeprazole and esomeprazole formulations.
Japan
PMDA pediatric indication expansions enable bioequivalence studies in younger age groups, opening maintenance therapy markets currently served off-label. METI industrial policy supports domestic fermentation-based antibiotic production for H. pylori eradication regimens. Tokyo and Osaka metropolitan areas concentrate gastroenterology specialist practices with sophisticated resistance surveillance capabilities.
India
CDSCO manufacturing facility inspections and export-oriented production incentives position domestic firms as suppliers of clarithromycin and amoxicillin components for global triple therapy protocols. The country's central government pharmaceutical procurement schemes distribute affordable acid suppression therapies through public hospital networks. Gujarat and Maharashtra host bulk drug manufacturing parks producing proton pump inhibitor intermediates.
Brazil
ANVISA bioequivalence requirements for generic substitution reshape competitive entry timelines for gastroenterology therapeutics in Latin America's largest pharmaceutical market. The country's unified health system formularies prioritize cost-effective acid suppression for chronic gastritis management. São Paulo state concentrates specialized gastroenterology centers with endoscopic biopsy capabilities.
Gastritis Market Competitive Landscape
Premium-margin players sit above commodity-margin players across branded-generic stratification, with originator manufacturers defending specialized gastroenterology channel access while generic suppliers capture institutional procurement volumes. The vendor base organizes into three archetypes: multinational pharmaceutical conglomerates with integrated research and manufacturing capabilities, mid-cap generic specialists with regional manufacturing scale, and contract development organizations supplying active pharmaceutical ingredients. Consolidation pressures intensify as integrated delivery networks centralize purchasing decisions and biosimilar proton pump inhibitors compress therapeutic equivalence premiums.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Takeda Pharmaceutical Company Limited occupy positions reflecting different strategic emphases within the gastric acid suppression ecosystem. Pfizer represents the broad-spectrum manufacturing scale archetype, while Takeda exemplifies premium branded portfolio concentration through specialized therapeutic channels. Novartis AG sits within the cytoprotective agent specialization tier, targeting erosive gastritis subpopulations beyond standard acid suppression protocols.
| Leading Market Players |
|---|
| AstraZeneca PLC |
| Sun Pharmaceutical Industries |
| Novartis AG |
| Perrigo Pharmaceutical |
| Lupin Ltd |
| Pfizer Inc. |
| AbbVie Inc. |
| Johnson & Johnson |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply & Pricing Matrix
EMA pediatric indication expansions for chronic acid suppression therapies gate qualified supply access and premium-tier pricing eligibility, as manufacturers must submit extended safety databases to secure centralized marketing authorization across European member states.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates originator proton pump inhibitors from authorized generics and commodity-grade alternatives. Price differentiation hinges on FDA bioequivalence certification tier and volume procurement scale through integrated delivery networks. Cost compression in the standard tier intensifies as biosimilar entrants force brand premium erosion. Hospital pharmacy benefit managers exhibit highest price sensitivity; specialized gastroenterology centers retain lowest sensitivity due to channel-specific formulary independence.
Supply Chain Analysis
Dual-sourcing requirements mandated by hospital procurement committees drive active pharmaceutical ingredient qualification across multiple manufacturing sites. Supply concentrates in India, China, and Germany for omeprazole and esomeprazole intermediates. Raw material dependencies include clarithromycin fermentation feedstocks, amoxicillin beta-lactam precursors, and H+/K+ ATPase inhibitor chemical cores. Single-source vulnerability in quality-certified API batches creates disruption exposure. Distribution runs through centralized pharmacy benefit managers serving vertically integrated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastritis market represents a late-cycle quality story as resistance-guided H. pylori eradication protocols shift demand toward precision-combination premium regimens with documented microbiology surveillance compatibility.
For Market Incumbents: Deploy specialized gastroenterology channel control to defend against biosimilar proton pump inhibitor displacement. Secure backward integration into active pharmaceutical ingredient manufacturing for omeprazole intermediates. Invest in cytoprotective agent R&D pipelines targeting erosive gastritis subpopulations beyond commoditized acid suppression. For New Entrants and Emerging Players: The premium-to-economy price-point gap in maintenance proton pump inhibitor therapy creates entry opportunity for authorized generic specialists. Target community gastroenterology clinics losing purchasing autonomy to health system consolidation. Pursue pediatric indication expansion through bioequivalence studies in younger age groups as a differentiated regulatory pathway. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap generic gastroenterology specialists because integrated delivery network procurement concentration rewards manufacturing scale. Long-term viability centers on capturing institutional contract volumes rather than brand premium retention. Monitor FDA ANDA approval velocity as the inflection indicator for competitive entry intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA pediatric indication expansions open off-label maintenance therapy markets in Japan. |
| Manufacturing Scale-Up | CDSCO-inspected facilities in Gujarat supply clarithromycin components for global triple therapy protocols. |
| Backward Integration | Captive production of esomeprazole intermediates insulates against API quality disruptions. |
| Hospital System Partnership | Enterprise-wide proton pump inhibitor contracts with Northeast Corridor health systems anchor volume. |
| Pipeline Diversification | Cytoprotective agent development targets underpenetrated erosive gastritis subpopulations beyond acid suppression. |
Research Methodology
Bottom-up gastroenterology clinic procurement modeling reconciled against top-down pharmaceutical manufacturing tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Triangulation between demand-side prescribing patterns and supply-side production capacity anchors volume estimates.
Historical trendline analysis of proton pump inhibitor prescription refill volumes and H. pylori eradication regimen adoption patterns established baseline growth trajectories. The analytical framework segments by product type, therapy area, end user, and delivery mode across the projection horizon. CAGRs derive from regression analysis of chronic therapy dependence rates, resistance-guided prescribing expansion, and generic entry velocity. Forecast inputs incorporate aging demographic projections and microbiology infrastructure investment cycles.
Caveats apply where FDA pharmacovigilance database signals on long-term proton pump inhibitor safety could materially shift the outlook. Forecasts reflect assumptions regarding bioequivalence standard stability, antibiotic resistance surveillance cost trajectories, and integrated delivery network consolidation velocity. Deviation in prescriber caution toward chronic acid suppression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Global Melanoma Therapeutics Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Abetalipoproteinemia Management Market