
 Germany Opioids Market | 2026-2036
Germany Opioids Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Opioids Market Insights
Maintenance contracts for pain-management infusion systems is consolidating around fewer service providers in Germany. Grünenthal leverages its heritage in analgesic development to sustain strong ties with German hospital pharmacies. Teva Pharmaceutical Industries Ltd anchors its position through broad generic opioid portfolios that compete aggressively on tender pricing. Hikma Pharmaceuticals PLC specializes in injectable formulations that differentiate its offering in surgical anesthesia segments.
Germany opioids encompass semisynthetic and synthetic alkaloid derivatives, including morphine, oxycodone, and fentanyl analogues, formulated for controlled-release delivery with defined bioavailability parameters and abuse-deterrent properties. These compounds serve primarily as centrally acting analgesics for moderate-to-severe pain management in clinical and postoperative settings. Prescription opioids dominate value pools due to reimbursement-linked pricing power and strict dispensing controls, while transdermal patches represent the fastest-expanding drug formulation category as clinicians favor steady plasma concentration profiles. Palliative care applications within the therapy area dimension command premium margins, reflecting the complexity of dosing titration and the specialized clinical oversight required.
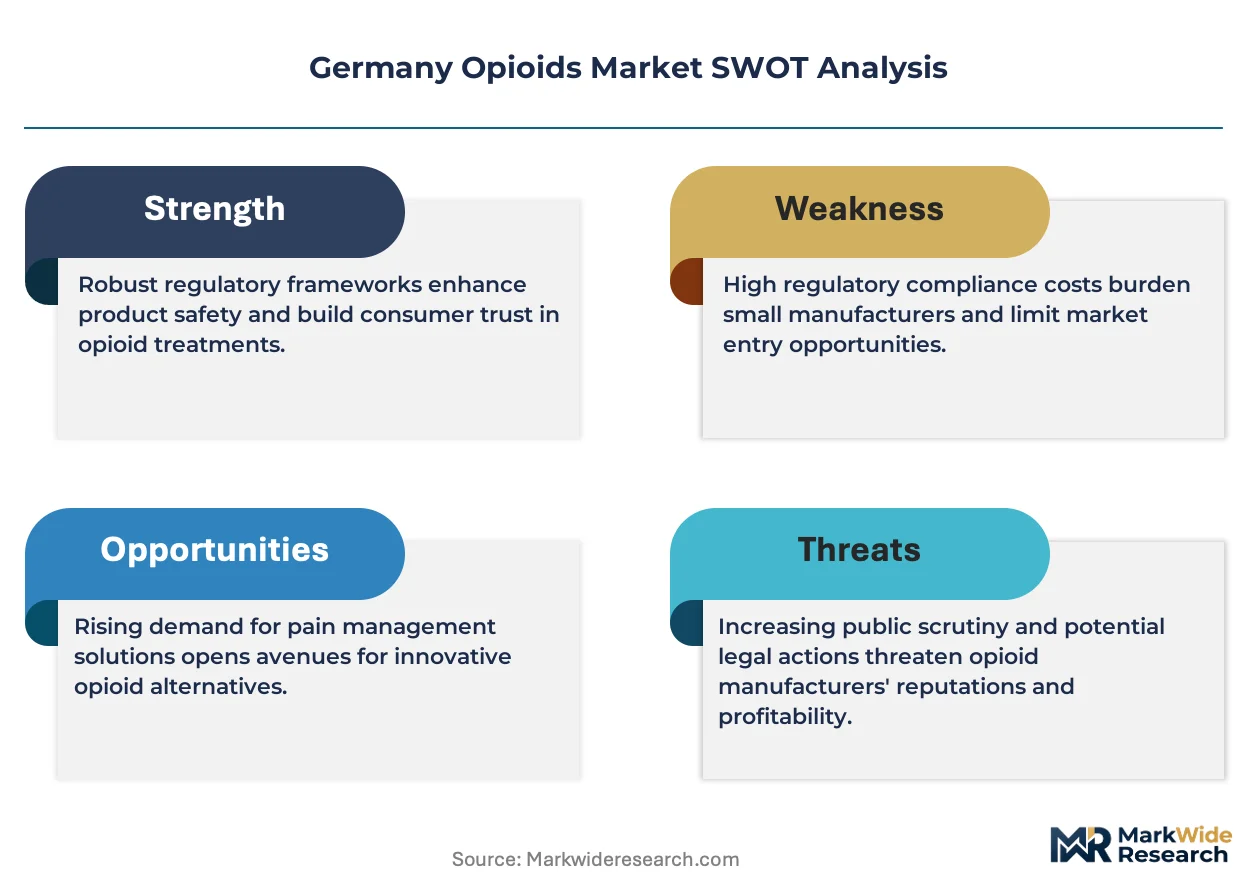
The Federal Institute for Drugs and Medical Devices enforces narcotics prescription regulations under the German Narcotics Act, while the G-BA determines reimbursement thresholds that directly shape physician prescribing incentives and product access. The German Medicines Act and EU Good Manufacturing Practice standards impose batch-testing and traceability requirements that raise compliance costs for imported active pharmaceutical ingredients. Stakeholders must monitor evolving addiction-prevention protocols and reimbursement recalibrations that could redirect volume toward non-opioid alternatives or novel delivery mechanisms.
Market Dynamics
The Federal Institute for Drugs and Medical Devices maintains escalating scrutiny on opioid prescribing thresholds, compressing volume authorization while simultaneously mandating abuse-deterrent formulation upgrades that reshape manufacturer R&D allocation.
Growth Catalysts
- Palliative care expansion:German university hospitals are broadening opioid protocols for terminal cancer patients, creating specialized dosing infrastructure that pulls volume toward controlled-release formulations.
- Transdermal patch adoption:Steady plasma concentration profiles from fentanyl patches reduce breakthrough pain incidents, driving clinician preference shifts in postoperative and chronic pain management.
- North Rhine-Westphalia cluster density:Hospital network concentration in this industrial belt generates economies of scale in procurement and specialized pain services.
Market Restraints
- Active pharmaceutical ingredient import dependency:Batch-testing and traceability requirements under EU Good Manufacturing Practice standards elevate compliance costs for API sourced from non-European suppliers.
- Reimbursement threshold rigidity:The G-BA determines pricing ceilings that compress margin flexibility for novel formulations entering the statutory health insurance system.
- Non-opioid substitution pressure:Multimodal analgesia protocols incorporating regional anesthesia and NSAID combinations displace opioid monotherapy in ambulatory surgical settings.
Strategic Opportunities
- Bavaria underpenetration:Rural hospital networks in southern Germany lack specialized pain management infrastructure, creating whitespace for hub-and-spoke service models.
- Abuse-deterrent technology convergence:Physical barrier formulations combining polymer matrices with aversive agents address the Federal Institute for Drugs and Medical Devices' escalating safety mandates.
- Home-based palliative delivery:Outpatient hospice networks are expanding direct-to-patient distribution channels that bypass traditional hospital pharmacy procurement.
Industry Challenges
- Addiction medicine specialist scarcity:Qualified personnel for opioid rotation and tapering protocols remain concentrated in academic medical centers, constraining community hospital capability.
- Legacy EHR integration friction:Controlled-substance tracking systems require costly interface upgrades to meet the German Narcotics Act's real-time prescription monitoring specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Opioids Market |
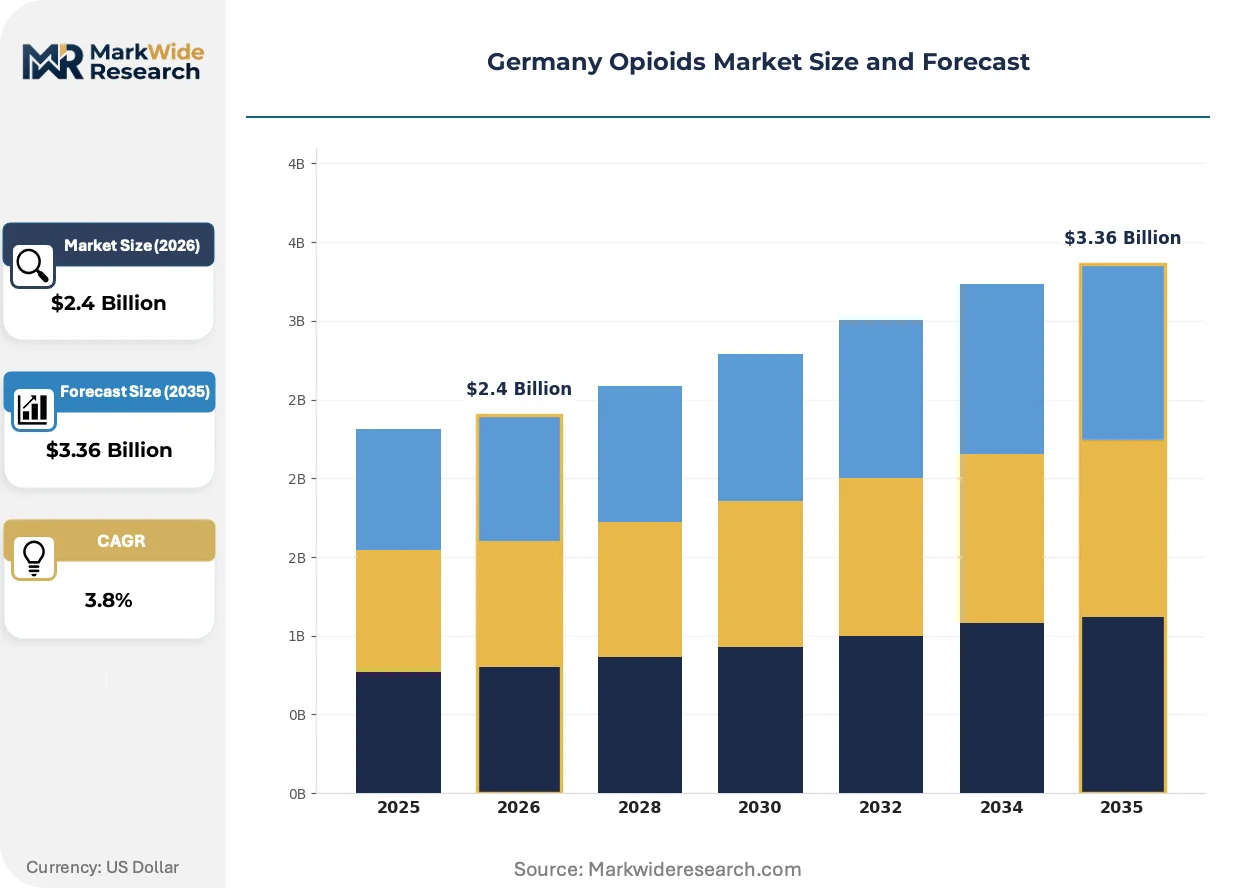
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Opioids, Non-Prescription Opioids, Synthetic Opioids, Natural Opioids Therapy Area: Pain Management, Anesthesia, Cancer Treatment, Palliative Care End User: Hospitals, Clinics, Home Healthcare, Pharmacies Drug Formulation: Tablets, Injections, Transdermal Patches, Oral Solutions |
| Companies Covered | Grünenthal, Teva Pharmaceutical Industries Ltd, Hikma Pharmaceuticals PLC, Mallinckrodt Pharmaceuticals, Endo International plc, Indivior PLC, Alkermes PLC, Purdue Pharma, Neuraxpharm Pharmaceuticals SL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Opioids Market Trends and Innovations
Formulation science and regulatory safety mandates are compressing development timelines while redirecting competitive advantage toward abuse-deterrent properties and delivery precision.
Intrathecal pump systems for refractory pain management are converging with wireless telemetry monitoring, enabling remote dose adjustment by specialized pain centers. German rehabilitation clinics are adopting these platforms for complex regional pain syndrome patients. The technology is compressing hospital readmission rates while shifting service revenue toward maintenance contracts.
The German Narcotics Act's electronic prescription mandate is forcing wholesale digitization of controlled-substance workflows. Pharmacies must now integrate with the telematics infrastructure for real-time validation. Hospital outpatient departments are responding by consolidating opioid prescribing within specialized pain units rather than general practice.
Hospital pharmacy procurement committees are consolidating vendor relationships for infusion system maintenance, reducing service provider counts from fragmented regional models toward national framework agreements. This concentration is visible most acutely in North Rhine-Westphalia's dense hospital networks, where economies of scale in service contracting are displacing equipment ownership models.
Germany Opioids Market Segmentation
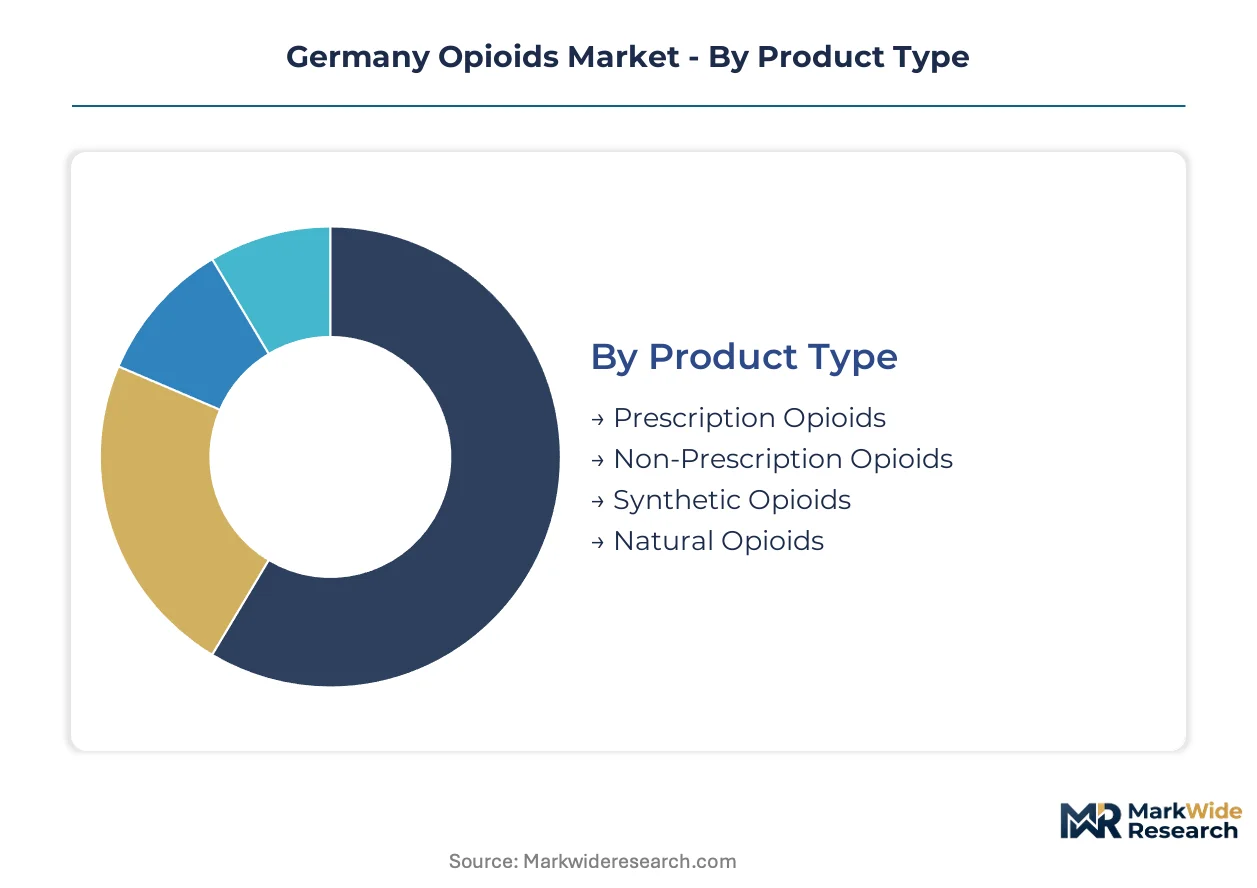
German opioid procurement patterns diverge sharply between high-margin specialized formulations and volume-driven generic substitutes. The Federal Institute for Drugs and Medical Devices' scheduling tiers create natural segmentation boundaries that manufacturers navigate through distinct commercial strategies.
Product Type:
Prescription opioids capture premium value pools through reimbursement-linked pricing power, while synthetic formulations accelerate fastest on abuse-deterrent technology investments.
- Prescription Opioids:Controlled-release morphine and oxycodone formulations dominate hospital pharmacy procurement under strict narcotic prescription protocols. North Rhine-Westphalia's dense hospital networks concentrate demand for these products where specialized pain units manage complex titration regimens.
- Synthetic Opioids:Fentanyl analogues and tramadol derivatives offer standardized potency profiles that simplify dosing protocols in surgical anesthesia. Bavaria's expanding rural hospital networks are adopting these formulations where addiction medicine specialist scarcity constrains complex opioid rotation capabilities.
- Natural Opioids:Morphine sulphate and codeine-based products serve as first-line options in cost-sensitive procurement tenders.
- Non-Prescription Opioids:Low-dose codeine combinations face tightening federal scheduling restrictions that compress distribution channels.
Today's leader: Prescription Opioids. Tomorrow's challenger: Synthetic Opioids.
Therapy Area:
Application complexity determines margin structure, with terminal care commanding specialized clinical oversight premiums and perioperative use facing substitution pressure from multimodal protocols.
- Palliative Care:German university hospitals are expanding dedicated opioid protocols for terminal cancer patients, requiring sophisticated dosing infrastructure and continuous monitoring capabilities that justify premium reimbursement rates.
- Pain Management:Chronic non-cancer pain applications face G-BA reimbursement threshold rigidity that compresses margin flexibility for novel formulations entering statutory health insurance.
- Anesthesia:Injectable fentanyl and remifentanil serve induction and maintenance protocols in operating theaters across industrial belt hospital networks.
- Cancer Treatment:Neuropathic pain management in oncology units pulls volume toward transdermal delivery systems for steady plasma concentration maintenance.
Palliative Care commands the steepest premium ladder. Pain Management faces the sharpest cost compression.
End User:
Procurement authority concentration shapes competitive access, with hospital pharmacy committees consolidating vendor relationships while home-based channels fragment purchasing decisions.
- Hospitals:University medical centers and acute care facilities in North Rhine-Westphalia anchor volume through centralized pharmacy procurement committees that negotiate national framework agreements.
- Home Healthcare:Outpatient hospice networks are expanding direct-to-patient distribution channels that bypass traditional hospital pharmacy procurement and create new service revenue pools.
- Clinics:Ambulatory surgical centers face non-opioid substitution pressure from regional anesthesia and NSAID combination protocols.
- Pharmacies:Community dispensers must integrate with the telematics infrastructure for real-time prescription validation under the German Narcotics Act's electronic mandate.
Hospital concentration is peaking. Home Healthcare channels are fragmenting fastest.
Drug Formulation:
Delivery precision and abuse-deterrent properties are redirecting competitive advantage as the Federal Institute for Drugs and Medical Devices escalates safety mandates.
- Transdermal Patches:Fentanyl patches deliver steady plasma concentration profiles that reduce breakthrough pain incidents in postoperative and chronic pain management, driving clinician preference shifts across German rehabilitation clinics.
- Injections:Intravenous morphine and synthetic opioids serve surgical anesthesia segments where Hikma Pharmaceuticals PLC has built specialized formulation expertise.
- Tablets:Controlled-release oral formulations face polymer matrix upgrade requirements for physical barrier compliance.
- Oral Solutions:Liquid formulations serve palliative care patients with swallowing difficulties in home-based delivery models.
Transdermal Patches are gaining share fastest. Tablets face the steepest reformulation cost curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's opioid procurement patterns diverge substantially from those in neighboring France, where centralized hospital purchasing creates uniform pricing corridors rather than the state-level variation seen across German Länder.
North Rhine-Westphalia
Dense hospital networks and aging demographics create Germany's most concentrated opioid consumption cluster. The Federal Institute for Drugs and Medical Devices enforces strict narcotics prescription regulations under the German Narcotics Act. The Ruhr industrial belt anchors specialized pain management infrastructure where university medical centers manage complex titration regimens.
Bavaria
Rural hospital networks lack specialized pain management infrastructure, creating whitespace for hub-and-spoke service models. The German Medicines Act imposes batch-testing and traceability requirements that raise compliance costs for imported active pharmaceutical ingredients. Munich's academic medical centers concentrate addiction medicine specialists who manage opioid rotation protocols.
Baden-Württemberg
Automotive industry occupational health programs drive demand for workplace injury pain management protocols. The G-BA determines reimbursement thresholds that directly shape physician prescribing incentives. Stuttgart's rehabilitation clinics are adopting intrathecal pump systems for complex regional pain syndrome patients.
Lower Saxony
Agricultural worker injury patterns sustain steady demand for acute postoperative analgesia in rural surgical centers. EU Good Manufacturing Practice standards impose traceability requirements on imported APIs. Hanover's hospital procurement committees are consolidating vendor relationships for infusion system maintenance.
Hesse
Frankfurt's financial sector employee health plans favor rapid-return-to-work pain protocols that emphasize transdermal delivery systems. The German Narcotics Act's electronic prescription mandate forces wholesale digitization of controlled-substance workflows. Outpatient hospice networks in the Rhine-Main region are expanding direct-to-patient distribution channels.
Germany Opioids Market Competitive Landscape
Top-tier vendors anchor hospital pharmacy procurement through national framework agreements, while mid-tier specialists compete on abuse-deterrent formulation differentiation. The vendor base clusters around three strategic archetypes: heritage analgesic developers leveraging clinical relationships, broad generic portfolio operators competing on tender pricing, and injectable formulation specialists targeting surgical anesthesia segments. Dominant competitive moves include consolidation of maintenance contract relationships and polymer matrix technology licensing for physical barrier compliance.
Among European heritage developers, Grünenthal anchors the specialized formulation tier through its longstanding presence in German hospital pharmacies. Teva Pharmaceutical Industries Ltd occupies a position exemplifying the broad generic archetype, with portfolio breadth enabling aggressive tender participation. Hikma Pharmaceuticals PLC represents the injectable specialization vector, with formulation expertise concentrated in surgical anesthesia applications.
| Leading Market Players |
|---|
| Grünenthal |
| Teva Pharmaceutical Industries Ltd |
| Hikma Pharmaceuticals PLC |
| Mallinckrodt Pharmaceuticals |
| Endo International plc |
| Indivior PLC |
| Alkermes PLC |
| Purdue Pharma |
| Neuraxpharm Pharmaceuticals SL |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient import costs from Indian and Chinese suppliers cascade through German opioid pricing tiers, with EU Good Manufacturing Practice batch-testing requirements layering compliance premiums onto landed costs before hospital pharmacy committees negotiate framework agreements.
Pricing Analysis
Capacity additions in synthetic opioid manufacturing hubs are reshaping price floors for fentanyl analogues and tramadol derivatives entering German tenders. Three-tier pricing structure across premium abuse-deterrent formulations, standard controlled-release tablets, and economy generic morphine sulphate segments stratifies procurement. Price differentiation rests on Federal Institute for Drugs and Medical Devices scheduling tier and G-BA reimbursement threshold alignment. Cost compression in the generic tier is intensifying because Teva Pharmaceutical Industries Ltd and Hikma Pharmaceuticals PLC compete aggressively on statutory health insurance formulary placement. Ambulatory surgical centers exhibit highest price sensitivity due to multimodal analgesia substitution pressure, while university hospital palliative care units demonstrate lowest sensitivity given specialized dosing infrastructure requirements.
Supply Chain Analysis
Dual-sourcing requirements mandated by the German Medicines Act compel hospital pharmacy procurement committees to qualify multiple API suppliers across India, China, and Switzerland for morphine alkaloid and synthetic opioid precursors. Raw material dependencies center on poppy straw concentrate from regulated cultivation zones, fentanyl precursor chemicals, and polymer matrix materials for abuse-deterrent formulations. Supply chain risk concentrates in single-source vulnerability for specialized injectable formulations where Hikma Pharmaceuticals PLC has built concentrated expertise. Distribution runs through three channels: direct hospital pharmacy delivery for inpatient units, wholesale pharmaceutical distributors for community pharmacies, and emerging direct-to-patient hospice networks bypassing traditional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German opioid margins expand through abuse-deterrent formulation premium capture and maintenance contract consolidation for infusion systems, offsetting G-BA reimbursement compression in generic segments.
For Market Incumbents: Anticipate Federal Institute for Drugs and Medical Devices escalation of physical barrier formulation mandates by accelerating polymer matrix R&D partnerships before regulatory deadlines crystallize. Consolidate maintenance contract relationships for intrathecal pump systems in North Rhine-Westphalia's dense hospital networks to lock out service competitors. Vertical integration into controlled-release tablet manufacturing reduces API import dependency exposure under EU Good Manufacturing Practice traceability requirements. For New Entrants and Emerging Players: Capture Bavaria's rural hospital whitespace through hub-and-spoke pain management service models that address addiction medicine specialist scarcity. Target home-based palliative care delivery channels where outpatient hospice networks fragment purchasing decisions away from centralized hospital pharmacy committees. Lead with transdermal patch formulations offering steady plasma concentration profiles that reduce breakthrough pain incidents and differentiate from oral generic competition. For Investors and Strategic Acquirers: Roll-up economics work for specialized injectable formulation specialists because surgical anesthesia segments retain pricing power amid multimodal substitution pressure elsewhere. Long-term viability hinges on abuse-deterrent technology licensing positions and maintenance contract recurring revenue streams. Watch Federal Institute for Drugs and Medical Devices scheduling recalibrations as the inflection signal directing volume toward non-opioid alternatives or novel delivery mechanisms.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Licensing | Physical barrier polymer matrix technology addresses Federal Institute for Drugs and Medical Devices safety mandates. |
| Maintenance Contract Consolidation | Intrathecal pump service agreements in North Rhine-Westphalia displace equipment ownership models. |
| Home-Based Palliative Distribution | Direct-to-patient hospice channels bypass traditional hospital pharmacy procurement committees. |
| Hub-and-Spoke Service Expansion | Bavaria rural networks lack specialized pain infrastructure creating whitespace capture opportunity. |
| EHR Integration Partnership | Real-time prescription monitoring compliance with German Narcotics Act telematics infrastructure requirements. |
Research Methodology
Coverage spans German Länder including North Rhine-Westphalia, Bavaria, Baden-Württemberg, Lower Saxony, and Hesse, with primary inputs from each regional cluster. Drug development executives, hospital pharmacy procurement managers, regulatory affairs specialists at the Federal Institute for Drugs and Medical Devices, palliative care clinicians, and G-BA reimbursement policy officers contributed structured interviews. Secondary validation drew from BfArM narcotics prescription statistics, G-BA benefit assessment dossiers, EU Good Manufacturing Practice inspection reports, and German Hospital Federation procurement surveys. Bottom-up volume modeling triangulated against top-down pharmaceutical market sizing across the analysis window.
Rate-of-change decomposition separated volume growth from price/mix effects across prescription opioid, synthetic opioid, natural opioid, and non-prescription opioid product categories. Therapy area segmentation modeled palliative care, pain management, anesthesia, and cancer treatment applications with end-user splits across hospitals, home healthcare, clinics, and pharmacies. Drug formulation dimensions incorporated transdermal patches, injections, tablets, and oral solutions. CAGRs derived from logistic curve fitting to historical narcotics consumption data adjusted for demographic aging trajectories and regulatory intervention scenarios.
Regulatory scheduling shifts, reimbursement threshold recalibrations, and non-opioid substitution acceleration are the dominant revision risks to projection assumptions. Deviation in Federal Institute for Drugs and Medical Devices abuse-deterrent mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market