
 Germicidal UV Lamp Market | 2026-2036
Germicidal UV Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
Germicidal UV Lamp Market Intelligence
Healthcare procurement is decoupling from general commercial lighting budgets as infection control protocols harden. Signify leverages its Lumileds semiconductor arm to dominate UV-C LED substitution roadmaps. Trojan Technologies anchors municipal water contracts across the Great Lakes basin with medium-pressure reactor systems. Heraeus Holding specializes in quartz glass envelope manufacturing, giving it upstream control over lamp durability specifications.
A germicidal UV lamp emits ultraviolet-C radiation at wavelengths between 200 and 280 nanometers to inactivate microorganisms by disrupting nucleic acid structures. Low-pressure mercury vapor lamps emitting at 254 nanometers remain the dominant installed base for water treatment due to proven log-reduction performance and established ballast infrastructure. Pulsed xenon technology is gaining traction in pharmaceutical cleanrooms where rapid cycle validation and mercury-free operation align with corporate sustainability mandates. Fixed installations in municipal water treatment command the largest value pool, while portable units in dental clinics and food processing plants represent the fastest-growing application segment as point-of-use disinfection protocols expand.
The EPA enforces UV dose verification under the Long Term 2 Enhanced Surface Water Treatment Rule, while the EU F-Gas Regulation constrains refrigerant-dependent cooling systems that often accompany UV reactor installations. NSF/ANSI Standard 55 and DVGW W294 in Germany define microbiological reduction claims, creating compliance moats for certified manufacturers. Stakeholders must monitor wavelength-specific efficacy data against emerging cryptosporidium strains and anticipate how amending drinking water directives in North America and Europe will recalibrate minimum UV dose requirements.
Market Dynamics
The germicidal UV lamp sector is undergoing a forced technology transition as mercury-containing products face phase-out timelines under the Minamata Convention, compelling manufacturers to accelerate UV-C LED commercialization while maintaining legacy service infrastructure for installed base revenue protection.
Growth Catalysts
- EPA Long Term 2 Enhanced Surface Water Treatment Rule:Municipal utilities across the United States must verify UV dose delivery, mandating lamp upgrades and validation equipment procurement for cryptosporidium inactivation compliance.
- Pharmaceutical cleanroom validation:Pulsed xenon systems eliminate mercury handling protocols while satisfying corporate sustainability officer mandates for zero-mercury operations in sterile manufacturing environments.
- German hospital accreditation:DVGW W294 certification requirements for medical water systems are accelerating bulk replacement of aging low-pressure mercury installations with medium-pressure reactor systems.
Market Restraints
- Quartz glass supply concentration:High-purity fused silica envelope manufacturing clusters in Hesse and Bavaria, creating single-source dependency for lamp durability specifications.
- UV-C LED efficacy gap:Wall-plug efficiency below 5% at 265 nanometers wavelength constrains substitution economics against optimized mercury vapor architectures.
- EU F-Gas Regulation cooling constraints:Refrigerant-dependent thermal management systems for high-output lamps face retrofit requirements, adding capital burden to reactor installations.
Strategic Opportunities
- Point-of-use dental clinic protocols:Portable UV-C units for intraoral device sterilization represent underpenetrated demand as infection control budgets separate from general facility lighting.
- Food processing plant surface disinfection:Conveyor-integrated pulsed systems are displacing chemical washdowns in ready-to-eat meat facilities seeking validation-compliant rapid cycle times.
- NSF/ANSI Standard 55 Class A certification:Residential drinking water system manufacturers can command premium positioning through microbiological reduction claims backed by third-party validation.
Industry Challenges
- UV dose metrology expertise scarcity:Calibration technicians capable of validating 254 nanometer output against biodosimetry standards command wage premiums that constrain service expansion.
- Legacy ballast infrastructure lock-in:Electromagnetic ballast replacement cycles in 1990s-era municipal installations require electrical contractor coordination that extends project timelines.
- Mercury waste handling compliance:Spent lamp disposal under RCRA subtitle C regulations imposes cradle-to-grave documentation burdens on facility maintenance departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germicidal UV Lamp Market |
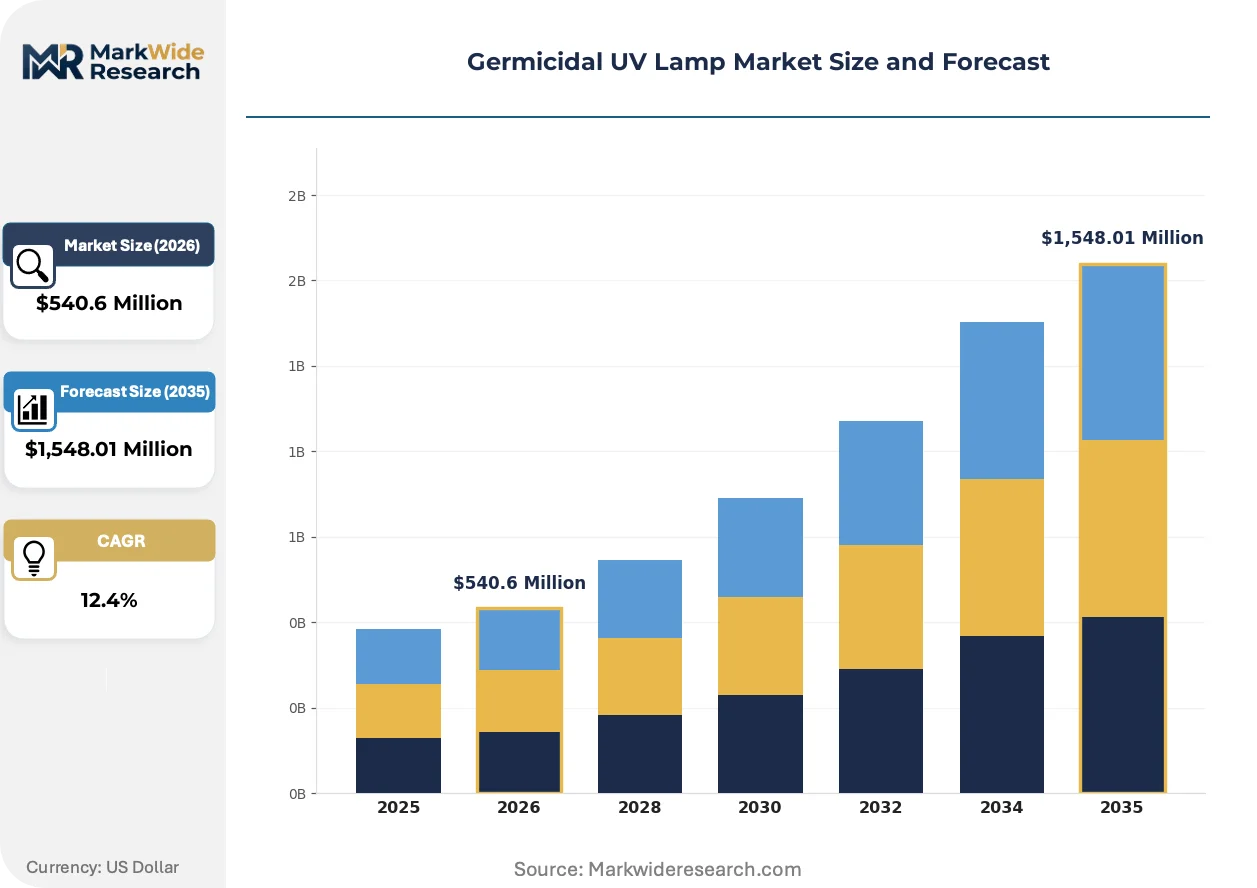
| Market Size in 2026 | $540.6 Million |
| Market Size in 2035 | $1,548.01 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Handheld, Wall-mounted Technology: Mercury Vapor, Low-pressure, High-pressure, Pulsed Xenon Application: Water Treatment, Air Purification, Surface Disinfection, Medical Facilities End User: Hospitals, Laboratories, Households, Industrial Facilities |
| Companies Covered | Osram, Signify, Halma, Atlantic Ultraviolet, Trojan Technologies, Heraeus Holding, Calgon Carbon, Cnlight, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germicidal UV Lamp Market Strategic Shifts & Innovations
Wavelength-specific efficacy optimization and connected validation systems are compressing the gap between laboratory performance claims and field-verified microbial inactivation, reshaping how procurement committees evaluate total cost of ownership.
UV-C LED semiconductor architectures are automating dose monitoring through integrated photodiode feedback loops that adjust output in real-time based on water transmittance fluctuations. Wastewater reclamation facilities in Singapore and Israel are piloting these self-correcting arrays to reduce operator intervention frequency. The technology is automating compliance documentation by generating timestamped irradiance logs that satisfy EPA audit requirements without manual meter readings.
The EU F-Gas Regulation is constraining refrigerant selection for medium-pressure lamp cooling systems, forcing reactor manufacturers toward CO2 transcritical cycles or dry-electrode designs. This policy friction is elevating capital costs for high-output installations while accelerating R&D investment in air-cooled arc tube geometries. German municipal procurement offices are responding by bundling cooling system retrofits into ten-year lamp service contracts to distribute compliance burden.
Buying committees in North American healthcare systems are unbundling UV disinfection equipment from general lighting maintenance contracts, creating dedicated infection control capital budgets with separate vendor qualification pathways. This behavioral shift is elevating clinical engineering influence over procurement decisions and compressing sales cycles for validated medical-grade systems. The pattern is most visible in California and Texas hospital networks where Joint Commission survey preparation drives preventive technology refresh schedules.
Germicidal UV Lamp Market Segmentation
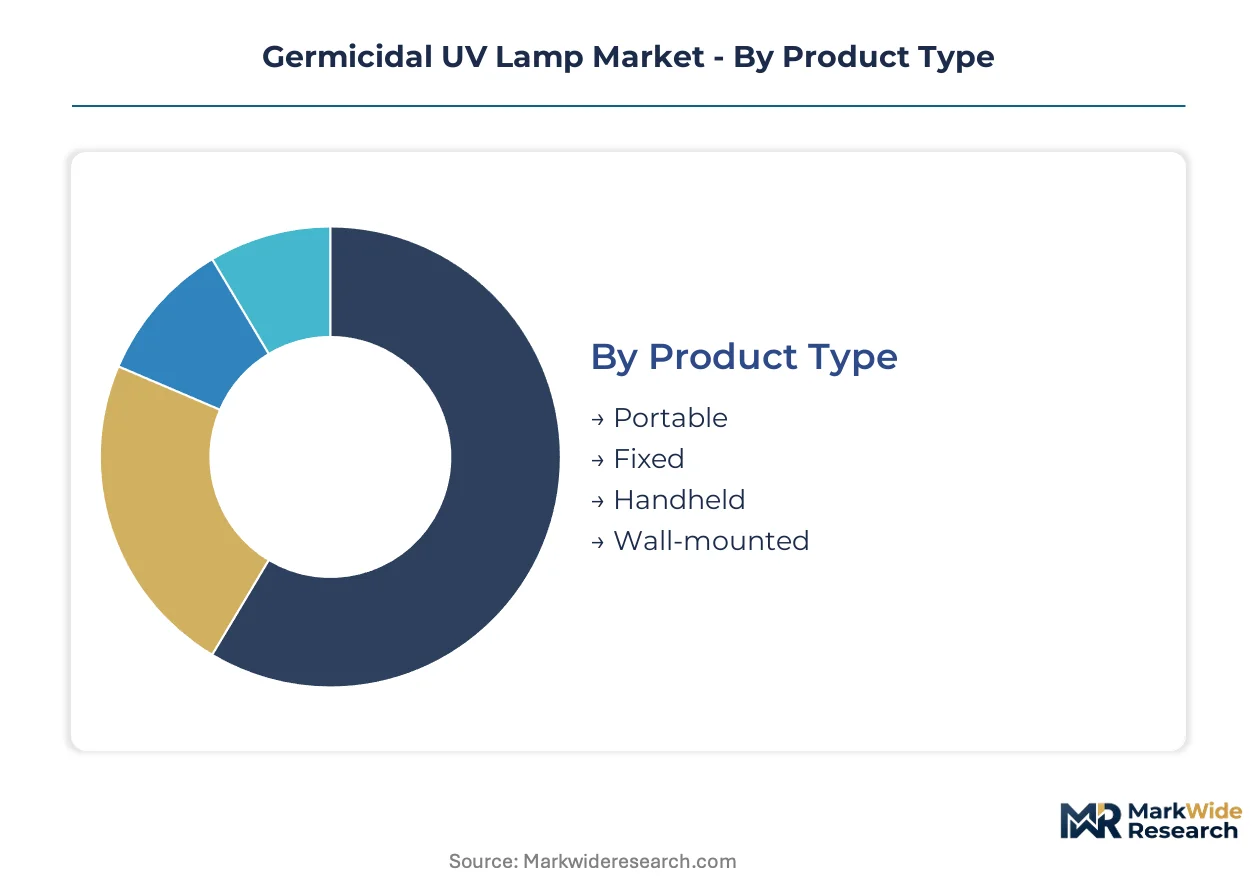
Procurement patterns across germicidal UV applications diverge sharply by installation permanence, energy infrastructure, and regulatory validation requirements. Understanding these fault lines clarifies why technology roadmaps and pricing architectures vary so dramatically across customer types.
Product Type:
Buyers differentiate primarily by mobility requirements and integration depth with existing building systems.
- Fixed:Permanently installed reactor systems dominate municipal water treatment infrastructure with medium-pressure mercury or pulsed xenon arc tubes housed in stainless steel vessels. German utilities and North American Great Lakes basin plants specify these for EPA Long Term 2 Enhanced Surface Water Treatment Rule compliance, bundling ten-year service contracts to distribute cooling system retrofit costs under EU F-Gas Regulation constraints.
- Portable:Self-contained units with battery or corded power enable point-of-use protocols in dental clinics and food processing plants where infection control budgets have separated from general facility lighting. California hospital networks are unbundling these purchases into dedicated clinical engineering procurement pathways.
- Handheld:Compact devices target surface disinfection in laboratories and small medical practices, constrained by operator dose verification challenges and limited irradiance output.
- Wall-mounted:Semi-permanent installations serve air purification in commercial buildings and industrial facilities, occupying a middle ground between fixed infrastructure flexibility and portable deployment speed.
Fixed installations lead volumes today; portable systems are gaining share fastest as point-of-use protocols expand beyond traditional infrastructure.
Technology:
Technology selection hinges on mercury handling protocols, wall-plug efficiency thresholds, and corporate sustainability mandates.
- Mercury Vapor:Low-pressure and medium-pressure arc tubes emitting at 254 nanometers anchor the installed base for water treatment, leveraging proven log-reduction performance and established electromagnetic ballast infrastructure. Replacement cycles accelerate under EPA Stage 2 Disinfectants and Disinfection Byproducts Rule enforcement.
- Pulsed Xenon:Mercury-free broadband emission systems satisfy pharmaceutical cleanroom validation requirements and corporate sustainability officer mandates for zero-mercury sterile manufacturing environments, gaining traction where rapid cycle validation outweighs capital cost premiums.
- Low-pressure:Optimized 254 nanometer output with proven biodosimetry standards dominates residential and small commercial NSF/ANSI Standard 55 Class A certification pathways.
- High-pressure:Intense broadband output serves specialized industrial applications requiring rapid microbial inactivation in high-flow water treatment scenarios.
Mercury vapor architectures dominate installed value; pulsed xenon is climbing the fastest as pharmaceutical sustainability mandates harden.
Application:
Application prioritization reflects regulatory pressure gradients and public health exposure risks.
- Water Treatment:Municipal utilities and medical facilities deploy validated reactor systems for cryptosporidium inactivation under EPA and DVGW W294 requirements. Singapore and Israeli wastewater reclamation facilities pilot UV-C LED self-correcting arrays to automate compliance documentation.
- Surface Disinfection:Conveyor-integrated pulsed systems displace chemical washdowns in ready-to-eat meat facilities, while handheld units address laboratory and food processing point-of-use needs.
- Air Purification:Upper-room and in-duct installations respond to healthcare accreditation requirements, particularly in German hospitals and Texas hospital networks preparing for Joint Commission surveys.
- Medical Facilities:Dedicated capital budgets for infection control equipment now operate separately from general lighting maintenance contracts in North American healthcare systems.
Water treatment commands the largest value pool; surface disinfection shows the steepest expansion trajectory as chemical substitution accelerates.
End User:
End user segmentation tracks budget autonomy, technical expertise availability, and regulatory scrutiny intensity.
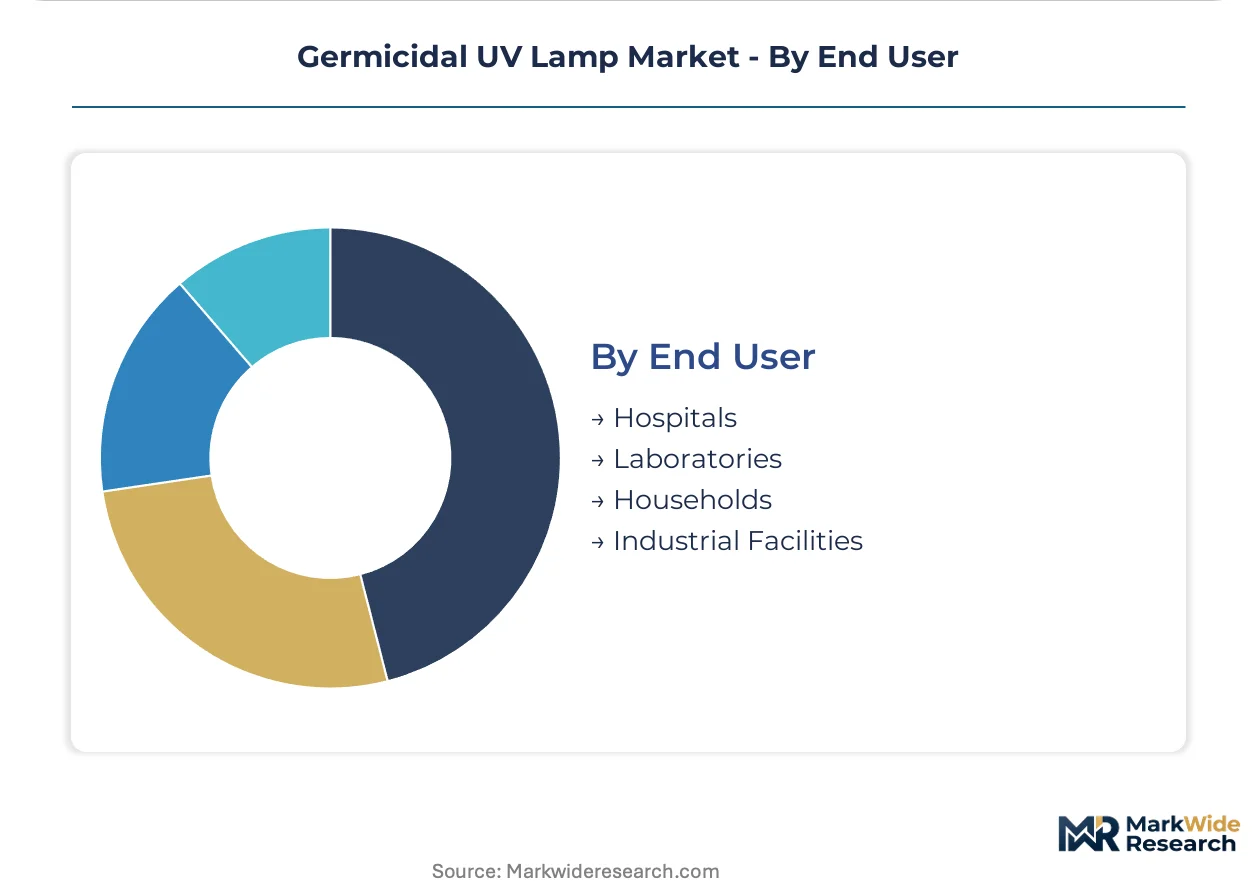
- Hospitals:Clinical engineering departments now control dedicated infection control capital budgets, elevating vendor qualification requirements and compressing sales cycles for validated medical-grade systems in California and Texas networks.
- Industrial Facilities:Food processing and pharmaceutical manufacturing sites balance rapid cycle validation needs against corporate sustainability mandates, driving pulsed xenon adoption where mercury-free operation aligns with ESG reporting.
- Laboratories:Research and diagnostic facilities require precise dose control and biodosimetry documentation, constrained by UV dose metrology technician scarcity.
- Households:Residential drinking water systems pursuing NSF/ANSI Standard 55 Class A certification represent emerging demand as point-of-entry disinfection protocols expand beyond municipal supply reliance.
Hospitals anchor procurement value today; industrial facilities are expanding most quickly as food safety and pharmaceutical validation requirements converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate toward jurisdictions with favorable mercury-handling protocols and established quartz glass supply chains. Compliance cost differentials between the Minamata Convention signatories and regional enforcement intensities are accelerating facility relocation toward Germany, China, and the United States.
United States
Municipal water utilities across the Great Lakes basin and Southwest are expanding UV disinfection capacity under EPA Long Term 2 Enhanced Surface Water Treatment Rule mandates. The Stage 2 Disinfectants and Disinfection Byproducts Rule is compressing lamp replacement cycles in legacy installations. California and Texas hospital networks are unbundling infection control equipment into dedicated clinical engineering budgets.
Germany
DVGW W294 certification requirements for medical water systems are driving bulk procurement of medium-pressure mercury systems in Bavaria and Hesse. Municipal infrastructure upgrades in North Rhine-Westphalia are bundling cooling system retrofits into ten-year lamp service contracts. The EU F-Gas Regulation is forcing reactor manufacturers toward CO2 transcritical thermal management cycles.
China
Domestic semiconductor fabrication investments in Jiangsu and Zhejiang provinces are expanding demand for validated cleanroom disinfection systems. The country's national environmental protection regulator is tightening industrial wastewater discharge standards that incorporate UV dose verification. Shanghai and Shenzhen municipal water authorities are piloting UV-C LED arrays for automated compliance documentation.
Singapore
Wastewater reclamation facilities are deploying self-correcting UV-C LED systems with integrated photodiode feedback loops to reduce operator intervention. The national water agency's NEWater program mandates cryptosporidium inactivation validation that exceeds WHO guidelines. Jurong Island industrial clusters are adopting pulsed xenon surface disinfection for pharmaceutical manufacturing environments.
Israel
Desalination and wastewater reuse facilities in the Negev and coastal plain are piloting connected validation systems for real-time irradiance logging. National water security policies prioritize treatment redundancy that favors redundant UV reactor installations. Tel Aviv metropolitan utilities are automating EPA-equivalent audit documentation through timestamped dose monitoring.
Germicidal UV Lamp Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with municipal water contracts favoring established validation histories while point-of-use applications tolerate newer entrants. The installed base of legacy mercury vapor systems creates recurring revenue streams for incumbents with service infrastructure. Two strategic archetypes dominate: vertically integrated quartz glass producers controlling envelope durability specifications, and semiconductor-led UV-C LED developers automating dose feedback systems. Competitive moves center on cooling system retrofit bundling under EU F-Gas Regulation constraints and ten-year service contract structures that distribute compliance capital burdens.
Among European-headquartered specialists, Heraeus Holding and Signify occupy positions that exemplify upstream control and semiconductor-led substitution roadmaps respectively. Trojan Technologies anchors North American municipal water contracts. These three represent divergent strategic bets on mercury-phase transition timing and LED commercialization readiness.
| Leading Market Players |
|---|
| Osram |
| Signify |
| Halma |
| Atlantic Ultraviolet |
| Trojan Technologies |
| Heraeus Holding |
| Calgon Carbon |
| Cnlight |
| Xylem |
| Others |
Cost & Logistics Intelligence
UV-C LED semiconductor commercialization is compressing legacy mercury vapor economics while concentrating production scale among semiconductor foundries in Taiwan and South Korea. This technology transition simultaneously elevates R&D amortization burdens for LED developers and fragments pricing power across quartz glass envelope manufacturers in Germany.
Pricing Analysis
Distributor margins on medium-pressure mercury systems compress 15-25 points below direct municipal utility contracts due to validation documentation burdens. Three-tier pricing structure across premium certified, standard commercial, and economy residential levels separates NSF/ANSI Standard 55 Class A validation tiers. Cost compression in low-pressure lamp segments is intensifying because Chinese manufacturers are scaling fused silica production. Municipal water utilities exhibit lowest price sensitivity; dental clinic procurement committees show highest.
Supply Chain Analysis
Freight costs for quartz glass envelopes from Hesse and Bavaria to North American reactor assemblers add 8-12% landed cost premiums versus intra-EU distribution. High-purity fused silica concentrates in Germany, China, and the United States; mercury amalgam feedstocks draw from Kyrgyzstan and Spain. Single-source vulnerability sits with German quartz suppliers controlling lamp durability specifications. Distribution runs through authorized service contractors for municipal installations and dental supply distributors for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-C LED efficacy improvements above 265 nanometers are expanding premium-tier addressable markets while mercury waste compliance costs erode legacy margin structures. Semiconductor-led substitution roadmaps favor players with captive epitaxy capacity.
For Market Incumbents: Anchor installed base revenue through ten-year service contract bundling that distributes EU F-Gas Regulation cooling retrofit costs. Deepen backward integration into quartz glass envelope specifications to defend against Chinese fused silica entrants. Prioritize certification maintenance under EPA Long Term 2 Enhanced Surface Water Treatment Rule validation protocols.
For New Entrants and Emerging Players: Begin with portable dental clinic units where infection control budgets have separated from general facility lighting and vendor qualification pathways remain underdeveloped. Target California and Texas hospital networks preparing for Joint Commission surveys. Pursue NSF/ANSI Standard 55 Class A certification as premium positioning anchor.
For Investors and Strategic Acquirers: Valuations sit cheapest among quartz glass specialists with upstream envelope control and underutilized medium-pressure reactor service infrastructure. Five-to-ten year viability favors semiconductor-led UV-C LED developers with integrated photodiode feedback patent estates. Watch EPA dose requirement amendments as inflection indicator for mercury substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| UV-C LED Epitaxy Capacity Expansion | Captive semiconductor fabrication in Taiwan and South Korea locks in wavelength optimization at 265 nanometers. |
| Quartz Glass Backward Integration | In-house fused silica production in Hesse and Bavaria secures lamp durability specification control against Chinese competition. |
| Cooling System Retrofit Bundling | Ten-year service contracts distribute EU F-Gas Regulation compliance costs across German municipal procurement offices. |
| NSF/ANSI Standard 55 Certification Investment | Class A validation creates compliance moats for residential drinking water system manufacturers in North America. |
| Photodiode Feedback Loop Patent Development | Integrated dose monitoring automates EPA audit documentation for Singapore and Israeli wastewater reclamation facilities. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged municipal water utility engineers, hospital clinical engineering directors, dental clinic procurement managers, and quartz glass manufacturing technical leads. Secondary validation drew from EPA enforcement databases, DVGW certification registries, EU F-Gas Regulation implementation reports, and semiconductor foundry capacity disclosures. Bottom-up unit economics triangulated against top-down addressable market sizing.
Segment-weighting applied technology type, application permanence, and end-user budget autonomy as core dimensions across the modeling period. CAGRs derived from installed base replacement cycle analysis, regulatory compliance deadline mapping, and LED efficacy improvement trajectories. Forecast inputs incorporated Minamata Convention phase-out timelines and municipal infrastructure depreciation schedules.
Caveats apply where UV-C LED wall-plug efficiency breakthroughs or amended EPA dose requirements could materially shift the outlook. Forecasts reflect assumptions on mercury handling compliance cost trajectories and quartz glass supply concentration persistence. A model refresh is warranted upon material change in semiconductor foundry capacity allocation or drinking water directive amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Clinical Hand Hygiene Products Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Dental Infection Treatment Market
Infection Control
Sterility Indicators Market
Infection Control
Sterilization Technologies Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Sterilization Monitoring Market
Infection Control
Sanitizers Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Hygiene Stations Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
North America Hand Sanitizer Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market