
 Global Hotel Dental Kits Market | 2026-2036
Global Hotel Dental Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hotel Dental Kits Market Analysis
Market Context
EU REACH chemical compliance is repositioning the cost-of-entry calculus for dental kit suppliers seeking European hotel contracts. Colgate-Palmolive leverages its oral care R&D infrastructure to sustain formulation advantages across premium and standard tiers. Procter & Gamble anchors North American supply relationships through direct procurement partnerships with major hotel chains. Henkel dominates the European private-label segment with manufacturing scale that supports customized branding programs.
Technical Definition and Segment Structure
Hotel dental kits are pre-assembled oral hygiene collections containing toothbrushes, toothpaste, and ancillary items, typically formulated with sodium fluoride concentrations between 1000-1500 ppm and packaged for single-guest consumption cycles. These kits serve the hospitality industry's amenity provisioning requirements, where brand consistency and guest satisfaction metrics govern procurement decisions. Toothpaste and toothbrush combinations occupy the largest product type share, while eco-friendly package formats are expanding fastest as hotels respond to sustainability mandates. The direct supply distribution channel captures the highest margin pools through long-term contracts with international hotel groups, whereas wholesale channels compete primarily on volume throughput.
Regulatory Framework
FDA cosmetic and drug regulations govern toothpaste formulations in the United States, while EU REACH and the F-Gas Regulation constrain aerosol-based mouthwash propellants across European markets. China's SAMR enforces GB standards for oral care product safety, creating a fragmented compliance landscape that shapes regional manufacturing footprints and export eligibility. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine which package types remain viable across key sourcing jurisdictions.
Market Dynamics
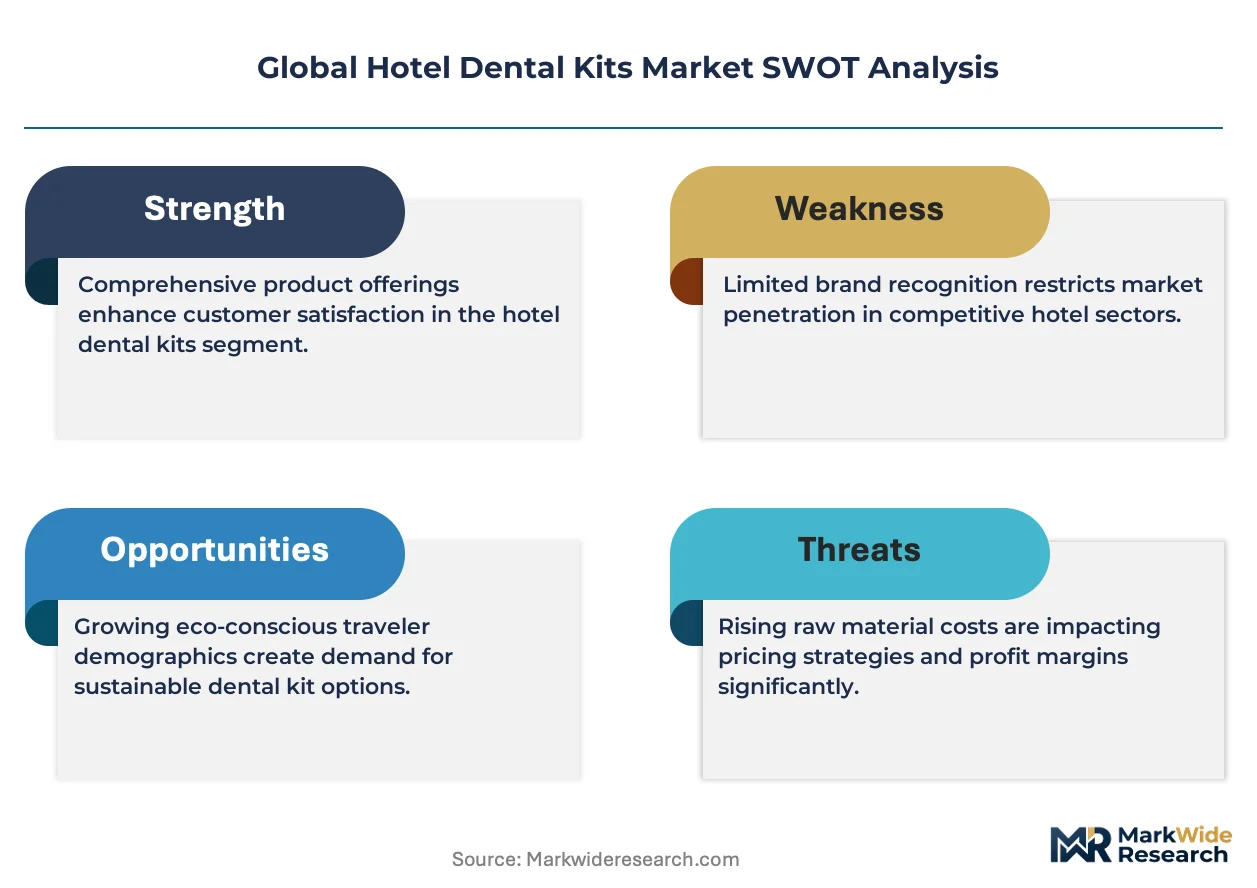
The EU Green Deal's single-use plastics directive is forcing a wholesale material transition across hotel amenity supply chains, compressing the viable window for petroleum-based packaging and redirecting procurement budgets toward bio-based alternatives.
Growth Catalysts
- Extended Producer Responsibility frameworks:France's AGEC law and Germany's VerpackG mandate hotel suppliers to register packaging with national compliance schemes, accelerating adoption of compostable toothbrush handles and recyclable toothpaste tubes.
- Boutique hotel premiumization:Southeast Asian boutique properties in Bangkok, Bali, and Ho Chi Minh City are expanding amenity budgets to differentiate guest experiences through branded dental kit partnerships.
- Fluoride formulation standardization:Sodium fluoride concentrations between 1000-1500 ppm now dominate procurement specifications, simplifying supplier qualification and enabling scale economies in toothpaste manufacturing.
Market Restraints
- Biopolymer cost volatility:PLA and PHA resin prices fluctuate with corn starch and sugarcane feedstock markets, compressing margins for eco-format kit producers against conventional plastic competitors.
- Supply concentration in Zhejiang province:China's toothbrush manufacturing clusters around Yangzhou and Hangzhou create geographic risk exposure for brands dependent on single-source injection molding capacity.
- EU F-Gas Regulation constraints:Aerosol mouthwash propellants face phase-down schedules under the 2024 quota system, eliminating a product format historically favored by luxury hotel chains.
Strategic Opportunities
- India's hospitality expansion:Marriott, Hilton, and IHG are adding 50,000+ rooms across Mumbai, Delhi, and Bengaluru through 2030, creating first-mover advantage for dental kit suppliers establishing direct procurement relationships.
- QR-code traceability integration:Blockchain-verified supply chain data is converging with guest-facing sustainability storytelling, enabling premium pricing for kits with full material provenance documentation.
- Refill station deployment:Wall-mounted bulk toothpaste dispensers in corridor amenity rooms reduce per-stay packaging waste by 70%, aligning with corporate ESG reporting requirements for Scope 3 emissions reduction.
Industry Challenges
- ISO 22716 GMP certification timelines:New manufacturing facilities require 12-18 months for cosmetics good manufacturing practice accreditation, delaying market entry for regional suppliers targeting European hotel contracts.
- Legacy ERP integration friction:Hotel procurement platforms running on 1990s-era systems resist API connectivity with supplier inventory management tools, forcing manual order reconciliation and stockout risks.
Report Scope
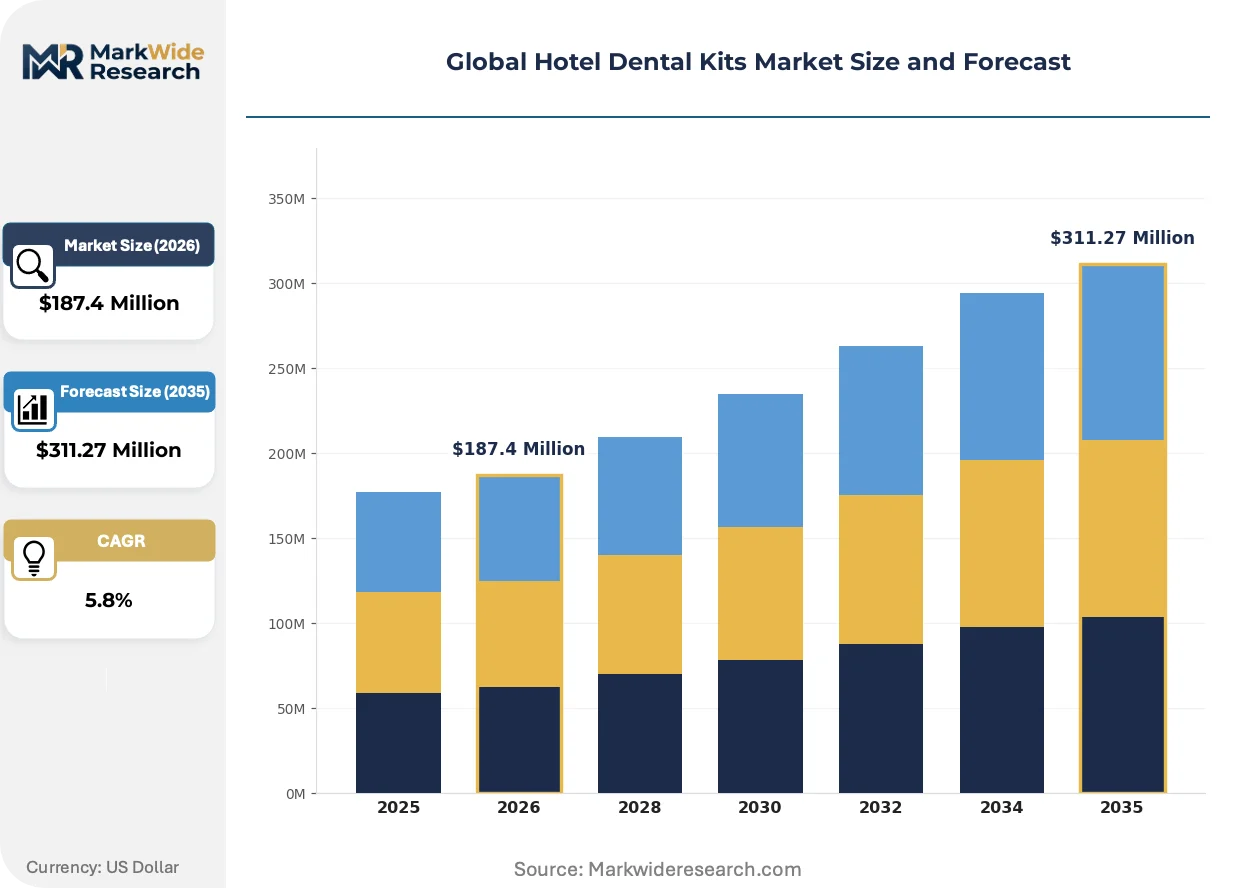
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hotel Dental Kits Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothbrush, Toothpaste, Mouthwash, Floss Package Type: Disposable, Reusable, Eco-friendly, Travel-size Distribution Channel: Online, Wholesale, Retail, Direct Supply Customer Type: Hotels, Resorts, Hostels, Bed & Breakfasts |
| Companies Covered | Liuzhou Liangmianzhen, Colgate-Palmolive, Procter & Gamble, GlaxoSmithKline, Church & Dwight, Henkel, LG Household & Health Care, Lion, Sunstar Suisse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hotel Dental Kits Market Emerging Trajectories
Bamboo fiber and molded pulp technologies are displacing virgin plastic across toothbrush and packaging applications, while digital procurement platforms compress supplier qualification cycles from quarters to weeks.
Biodegradable toothbrush handles derived from bamboo cellulose and wheat straw composites is converging with injection molding equipment retrofitted for biopolymer processing. Mid-scale hotel chains in Germany and the Netherlands are adopting these formats at 40% year-over-year replacement rates. This convergence is collapsing the traditional three-year supplier contract cycles into annual sustainability reviews with mandatory material disclosure requirements.
REACH Annex XVII restrictions on microplastics in rinse-off cosmetics now capture polyethylene beads in whitening toothpaste formulations, forcing reformulation toward silica and calcium carbonate abrasives. The industrial consequence is a 15-20% raw material cost increase for premium toothpaste SKUs. Luxury hotel amenity programs in France and Italy are responding by consolidating SKU counts and negotiating multi-year supply agreements to lock in reformulation costs.
Guest preference data from digital feedback platforms is redirecting procurement decisions away from brand-name toothpaste toward private-label formulations with equivalent fluoride efficacy. Third-party amenity distributors in China's tier-one cities are losing share to direct manufacturer relationships as IHG and Marriott centralize global category management. This behavioral shift is most visible in Shanghai and Beijing, where international chains have terminated wholesale channel contracts in favor of Henkel and Colgate-Palmolive direct supply agreements.
Global Hotel Dental Kits Market Segmentation
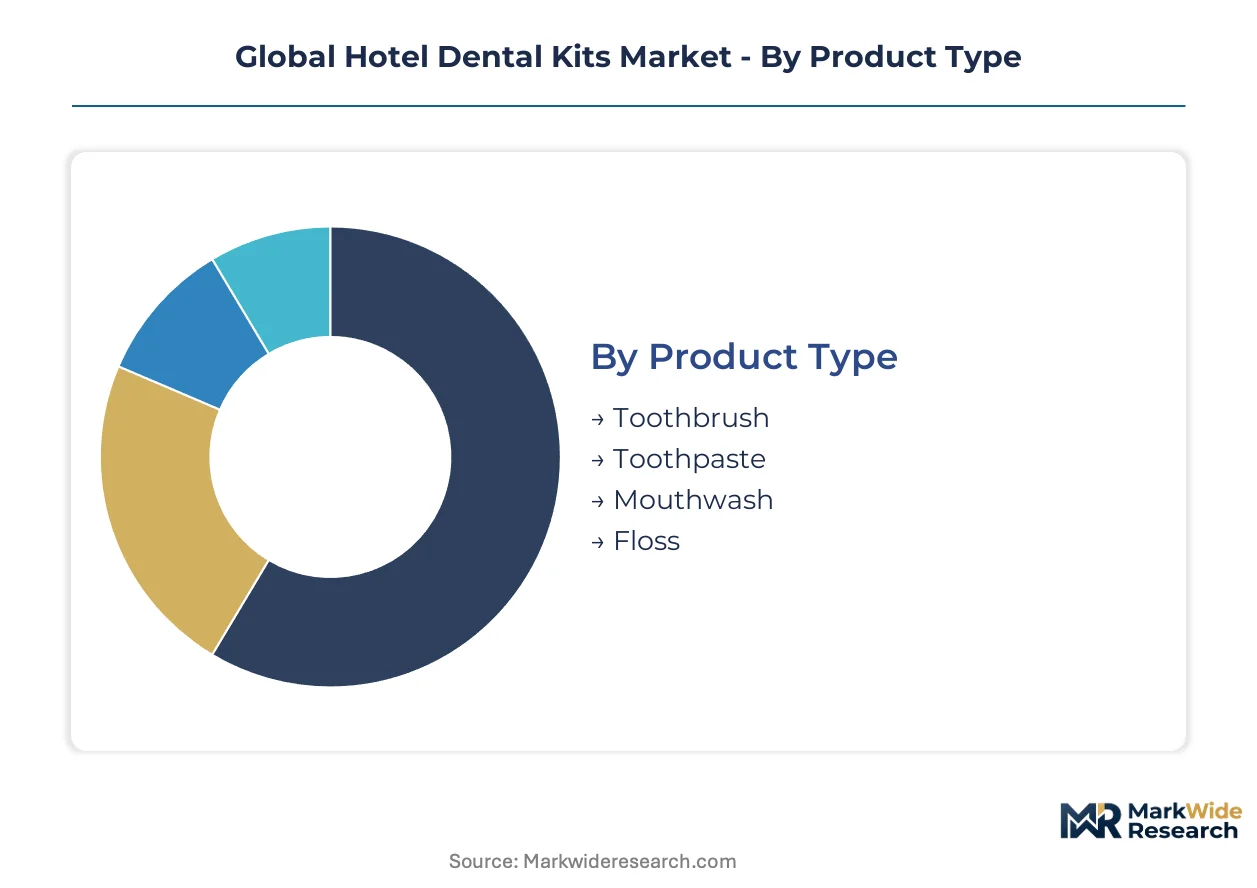
Procurement specifications in the Global Hotel Dental Kits Market diverge sharply between integrated amenity programs and standalone guest provisions. Understanding segment boundaries illuminates where suppliers can capture premium positioning versus commodity volume.
Product Type:
Standalone oral care items dominate procurement contracts, while bundled combinations serve embedded amenity configurations.
- Toothbrush:Nylon-bristle configurations with bamboo or wheat-straw cellulose handles now constitute the primary specification in EU Green Deal-compliant tenders. Demand concentrates in Germany and France where extended producer responsibility frameworks mandate compostable materials.
- Toothpaste:Sodium fluoride formulations between 1000-1500 ppm anchor procurement standards across international hotel chains. China's tier-one cities drive volume as Marriott and IHG centralize global category management toward direct manufacturer relationships.
- Mouthwash:Aerosol propellant formats face phase-down constraints under EU F-Gas Regulation quota systems.
- Floss:PTFE and silk thread variants occupy niche positioning within luxury boutique segments.
Volume placements concentrate in Toothpaste; the faster expansion belongs to Toothbrush.
Package Type:
Cost tier stratification separates single-use convenience formats from capital-intensive reusable systems.
- Eco-friendly:Molded pulp and PLA biopolymer packaging commands procurement priority in Netherlands and German mid-scale chains undergoing 40% year-over-year material transitions. Bangkok and Bali boutique properties specify these formats for guest-facing sustainability storytelling.
- Disposable:Petroleum-based laminate wraps retain volume dominance in price-sensitive hostel segments across India and Southeast Asia.
- Reusable:Rigid cases with refillable toothpaste cartridges target extended-stay hotel formats.
- Travel-size:TSA-compliant 100ml thresholds govern airline partnership amenity programs.
Disposable formats retain the largest volume footprint; eco-friendly alternatives are climbing the fastest.
Distribution Channel:
Margin structure varies with channel control depth, from arms-length wholesale to captive direct supply.
- Direct Supply:Long-term contracts with international hotel groups capture the highest margin pools through centralized procurement platforms. Colgate-Palmolive and Henkel anchor these relationships in North America and Europe respectively.
- Wholesale:Third-party amenity distributors in Shanghai and Beijing are losing share to manufacturer-direct relationships as procurement centralization accelerates.
- Online:Digital procurement platforms compress supplier qualification cycles from quarters to weeks.
- Retail:Pharmacy and convenience store channels serve independent bed-and-breakfast operators.
Wholesale channels process the highest transaction volumes; direct supply is gaining share fastest.
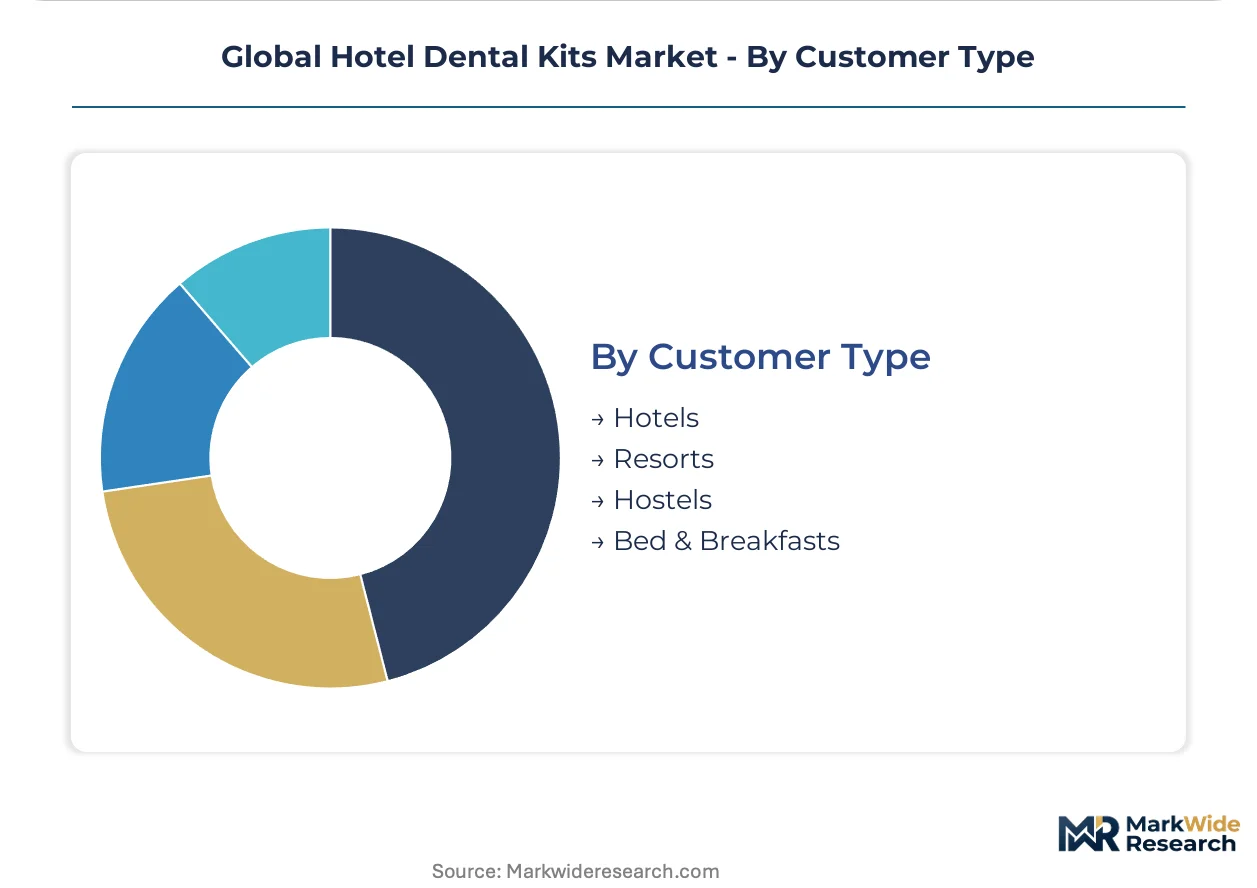
Customer Type:
Application intensity separates high-frequency commercial hospitality from low-turnover residential-adjacent lodging.
- Hotels:International chains in Mumbai, Delhi, and Bengaluru are adding 50,000-plus rooms through 2030, creating concentrated demand for standardized dental kit specifications across Marriott, Hilton, and IHG properties.
- Resorts:Premium amenity budgets in Bali and Ho Chi Minh City boutique properties differentiate through branded dental kit partnerships with full material provenance documentation.
- Hostels:Budget constraints favor disposable-format procurement through wholesale channels.
- Bed & Breakfasts:Fragmented owner-operated demand relies on retail and online sourcing.
Contract volume concentrates in Hotels; the steepest expansion trajectory belongs to Resorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangzhou's toothbrush manufacturing clusters in Jiangsu province attract preferential tax treatment under China's special economic zone framework, concentrating injection molding capacity for international hotel supply chains.
United States
Marriott and Hilton's centralized procurement platforms drive standardization across 50,000-plus properties. FDA cosmetic and drug regulations govern sodium fluoride formulations between 1000-1500 ppm. Chicago and Dallas serve as distribution hubs where direct supply relationships with Colgate-Palmolive and Procter & Gamble bypass wholesale channels.
Germany
Mid-scale hotel chains in Berlin and Munich adopt bamboo cellulose toothbrush handles at 40% year-over-year replacement rates. Extended producer responsibility under the VerpackG law mandates compostable packaging registration with national compliance schemes. Henkel's manufacturing scale in Düsseldorf anchors European private-label production for branded amenity programs.
China
IHG and Marriott expand footprints across Shanghai and Beijing tier-one cities, terminating wholesale distributor contracts for direct manufacturer relationships. SAMR enforces GB standards for oral care product safety, fragmenting export eligibility requirements. Yangzhou and Hangzhou clusters around Zhejiang province concentrate injection molding capacity for global supply.
India
Marriott, Hilton, and IHG add 50,000-plus rooms across Mumbai, Delhi, and Bengaluru through 2030, creating concentrated demand for standardized specifications. BIS certification requirements for imported oral care products shape supplier qualification timelines. Maharashtra's hospitality corridor attracts first-mover dental kit suppliers establishing direct procurement relationships.
France
Luxury hotel amenity programs in Paris and Lyon consolidate SKU counts under REACH Annex XVII microplastic restrictions on whitening toothpaste formulations. The AGEC law mandates packaging registration with national compliance schemes, accelerating compostable material transitions. Cosmetic good manufacturing practice accreditation timelines of 12-18 months delay regional supplier market entry.
Global Hotel Dental Kits Market Vendor Landscape
Chinese producers anchor the volume tier through Yangzhou and Hangzhou manufacturing clusters; European specialists hold premium positioning through REACH-compliant formulation capabilities. The vendor base separates into consolidated multinational oral care divisions and fragmented regional injection molding operations. Three archetypes dominate: R&D-integrated consumer goods conglomerates, private-label manufacturing scale players, and bamboo fiber material specialists. Competitive dynamics center on direct procurement partnership formation and biopolymer processing equipment retrofitting.
Within the R&D-integrated tier, Colgate-Palmolive and Procter & Gamble exemplify formulation advantage sustainment across premium and standard tiers through captive oral care infrastructure. Henkel occupies a distinct position in European private-label manufacturing, leveraging Düsseldorf-based scale for customized branding programs. Liuzhou Liangmianzhen represents the Chinese specialist archetype, sitting within the Yangzhou cluster's injection molding concentration.
| Leading Market Players |
|---|
| Liuzhou Liangmianzhen |
| Colgate-Palmolive |
| Procter & Gamble |
| GlaxoSmithKline |
| Church & Dwight |
| Henkel |
| LG Household & Health Care |
| Lion |
| Sunstar Suisse |
| Others |
Supply Flow & Price Mechanics
PLA biopolymer resin spot prices in Rotterdam and Shanghai trading hubs cascade through toothbrush handle manufacturing into three distinct procurement tiers across European and Asian hotel supply contracts. Buyers negotiating annual frameworks with Yangzhou injection molders absorb feedstock volatility through volume commitments, while spot purchasers in India's hospitality corridor face compressed margins from sugarcane-derived input cost swings.
Pricing Analysis
Short lead-time premiums of 15-25% apply to rush orders from boutique properties in Bangkok and Bali seeking bamboo-fiber toothbrush configurations outside standard production cycles. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European formulations from private-label Asian production and unbranded commodity kits. Cost compression in the economy tier is intensifying because Yangzhou molders compete on volume throughput for Indian hostel chains. Budget hostel operators in Mumbai and Delhi exhibit highest price sensitivity, while Paris luxury properties prioritize material provenance documentation over unit cost.
Supply Chain Analysis
France's AGEC law and Germany's VerpackG domestic-content mandates are reshaping sourcing patterns toward EU-registered packaging suppliers with national compliance scheme registrations. Manufacturing gravity centers on China's Zhejiang province, with secondary concentrations in Germany's Düsseldorf-Ruhr corridor and India's Maharashtra state. Raw material flows draw from corn starch feedstocks in the American Midwest, bamboo cellulose plantations in Anhui province, and wheat straw composites from Punjab agricultural regions. Single-source vulnerability concentrates in Yangzhou's injection molding cluster, where fire or regulatory shutdown would disrupt global toothbrush supply. Distribution runs through direct procurement platforms at Marriott and IHG, bypassing wholesale channels in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Hotel Dental Kits Market has become a vertical-integration race where control over biopolymer processing equipment and REACH-compliant formulation capabilities determines contract eligibility. Players capturing upstream injection molding capacity or downstream direct procurement relationships gain pricing power that spot-market competitors cannot replicate.
For Market Incumbents: Acquire bamboo fiber processing lines in Anhui province to secure raw material throughput for EU Green Deal-compliant tenders. Colgate-Palmolive and Henkel should consolidate Yangzhou molding partnerships through equity stakes, preempting emerging Chinese specialists from scaling REACH-certified production. Defensive moves must address the threat of QR-code traceability integration, where blockchain-verified supply chain data enables premium pricing that legacy ERP-dependent competitors cannot match. For New Entrants and Emerging Players: Begin with India's hospitality expansion corridor, where Marriott, Hilton, and IHG room additions in Mumbai, Delhi, and Bengaluru outpace established supplier relationships. The most penetrable segment lies in mid-scale properties seeking BIS-certified alternatives to imported kits. A direct-to-procurement-platform go-to-market angle bypasses entrenched wholesale distributors losing share in Shanghai and Beijing. For Investors and Strategic Acquirers: Distressed-cycle entries favor bamboo fiber material specialists with existing EU packaging registrations, positioned in Germany's North Rhine-Westphalia manufacturing belt. Long-term viability over a five-to-ten year horizon rests on biopolymer processing equipment retrofitting capabilities that conventional injection molders lack. Watch for inflection when India's BIS certification timelines compress, signaling first-mover suppliers have locked in direct relationships with expanding international chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Processing | Captive PLA and PHA resin capacity insulates margins from corn starch price volatility in American feedstock markets. |
| REACH Compliance Certification Investment | EU chemical registration unlocks tender eligibility for Paris and Lyon luxury hotel amenity programs under Annex XVII restrictions. |
| Direct Procurement Platform Integration | API connectivity with Marriott and IHG centralized systems eliminates manual order reconciliation and stockout risks. |
| QR-Code Traceability Deployment | Blockchain-verified material provenance documentation enables premium pricing for Bangkok and Bali boutique properties. |
| Refill Station Infrastructure Partnership | Wall-mounted bulk toothpaste dispensers align with corporate ESG Scope 3 reporting requirements for packaging waste reduction. |
Methodological Framework
Trade customs databases, EU packaging compliance registries, and hospitality procurement platform disclosures formed the secondary backbone for volume and value estimation. Primary interviews with hotel category managers, amenity program directors, injection molding plant engineers, and biopolymer procurement leads at oral care manufacturers validated secondary findings. The analytical approach combined bottom-up property-level room counts with top-down oral care amenity spend benchmarks, triangulating through Yangzhou cluster production data and Indian hospitality development pipeline tracking.
Bottom-up modeling aggregated individual property configurations across Marriott, Hilton, IHG, and independent boutique portfolios, while top-down analysis calibrated against aggregate hospitality supply spend patterns across the analysis window. Segmentation dimensions included product type, package format, distribution channel depth, and customer tier. CAGRs derived from weighted average of historical procurement growth rates and forward pipeline visibility on room additions. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and India's BIS certification timeline compression assumptions.
Underlying measurement precision varies by segment; direct supply channel data carries tighter precision than fragmented wholesale and retail channels where distributor reporting gaps persist. Forecasts reflect assumptions on regulatory implementation timelines, feedstock price trajectory, and hospitality development completion rates. Supply concentration risk in Zhejiang province and biopolymer cost volatility represent primary revision factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Supplies
Plaque Disclosing Market
Dental Supplies
Dental Preventive Supplies Market
Dental Supplies
Orthodontic Supplies Market
Dental Supplies
Dental Consumables Market
Dental Supplies
Dental Caries Treatment Market
Dental Supplies
Endodontic Supplies Market
Dental Supplies
Orthodontic Consumables Market
Dental Supplies
Fissure Sealants Market
Dental Supplies
Global Dental Suture Market