
 North America Respiratory Monitoring Market | 2026-2036
North America Respiratory Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Respiratory Monitoring Market Analytics
ISO 80601-2-55 for respiratory gas monitors is redrawing competitive boundaries across North America. Philips Healthcare leverages integrated ventilator-to-monitor platforms to sustain technology leadership in acute care settings. Medtronic anchors its position through deep R&D investment in sensor miniaturization for ambulatory applications. ResMed dominates the home care channel with cloud-connected devices that bypass traditional hospital procurement cycles.
Respiratory monitoring encompasses devices that measure ventilation parameters, gas exchange efficiency, and airway patency through electrochemical, optical, or acoustic sensing modalities, with pulse oximeters typically operating at wavelengths near 660 nm and 940 nm to quantify oxygen saturation via differential light absorption. These systems serve to detect respiratory compromise, titrate therapeutic interventions, and document disease progression across clinical and non-clinical environments. Pulse oximetry and capnometry lead technology adoption due to their non-invasive profile and real-time output, while wearable sensors represent the fastest-expanding segment as semiconductor fabrication enables continuous biometric streaming. Home care and hospital end-use categories split margin pools, with home care capturing volume growth and hospitals retaining premium pricing for multi-parameter systems.
FDA 510(k) clearance requirements, FCC wireless device authorizations, and Health Canada Medical Device Licensing establish layered compliance obligations that extend development timelines and elevate capital barriers for new entrants. The Centers for Medicare & Medicaid Services reimbursement codes directly determine commercial viability for home-based respiratory monitoring deployments. Stakeholders must track evolving FDA guidance on artificial intelligence-enabled diagnostic algorithms, as software-as-medical-device classifications will determine which product architectures require premarket submission versus streamlined documentation pathways.
Market Dynamics
Home care migration is compressing hospital-centric procurement models as portable pulse oximetry and capnography devices bypass traditional capital equipment cycles. CMS reimbursement code expansions for remote patient monitoring are accelerating this channel shift.
Growth Catalysts
- FDA 510(k) Streamlining:Expedited pathways for predicate device submissions reduce time-to-market for pulse oximetry upgrades, encouraging iterative sensor innovation.
- Ambulatory Surgery Centers:These facilities drive demand for compact multi-parameter monitors that integrate capnography with standard vital signs.
- Cloud Infrastructure:HIPAA-compliant data architectures enable continuous respiratory data streaming from patient homes to clinical dashboards.
Market Restraints
- Semiconductor Supply Concentration:Photodiode and LED chip fabrication concentrates in East Asian foundries, exposing device manufacturers to input volatility.
- ISO 80601-2-55 Compliance Burden:Electromagnetic compatibility testing for respiratory gas monitors extends development timelines and elevates validation costs.
- Optical Interference Limitations:Pulse oximetry accuracy degrades with poor perfusion or motion artifact, restricting deployment in high-acuity ambulatory settings.
Strategic Opportunities
- Mexico Manufacturing:Medical device production clusters in Baja California and Tijuana offer tariff-advantaged export platforms serving US demand.
- AI-Enabled Diagnostic Algorithms:FDA guidance on software-as-medical-device classifications creates pathways for predictive respiratory failure alerts.
- Chronic Obstructive Pulmonary Disease Home Management:Underpenetrated rural US markets present volume expansion for cloud-connected spirometry and overnight oximetry systems.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Firmware development for wearable respiratory sensors competes with consumer electronics for embedded systems specialists.
- Legacy Hospital IT Integration:HL7 FHIR interoperability requirements force middleware investments that strain mid-tier device manufacturer R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Respiratory Monitoring Market |
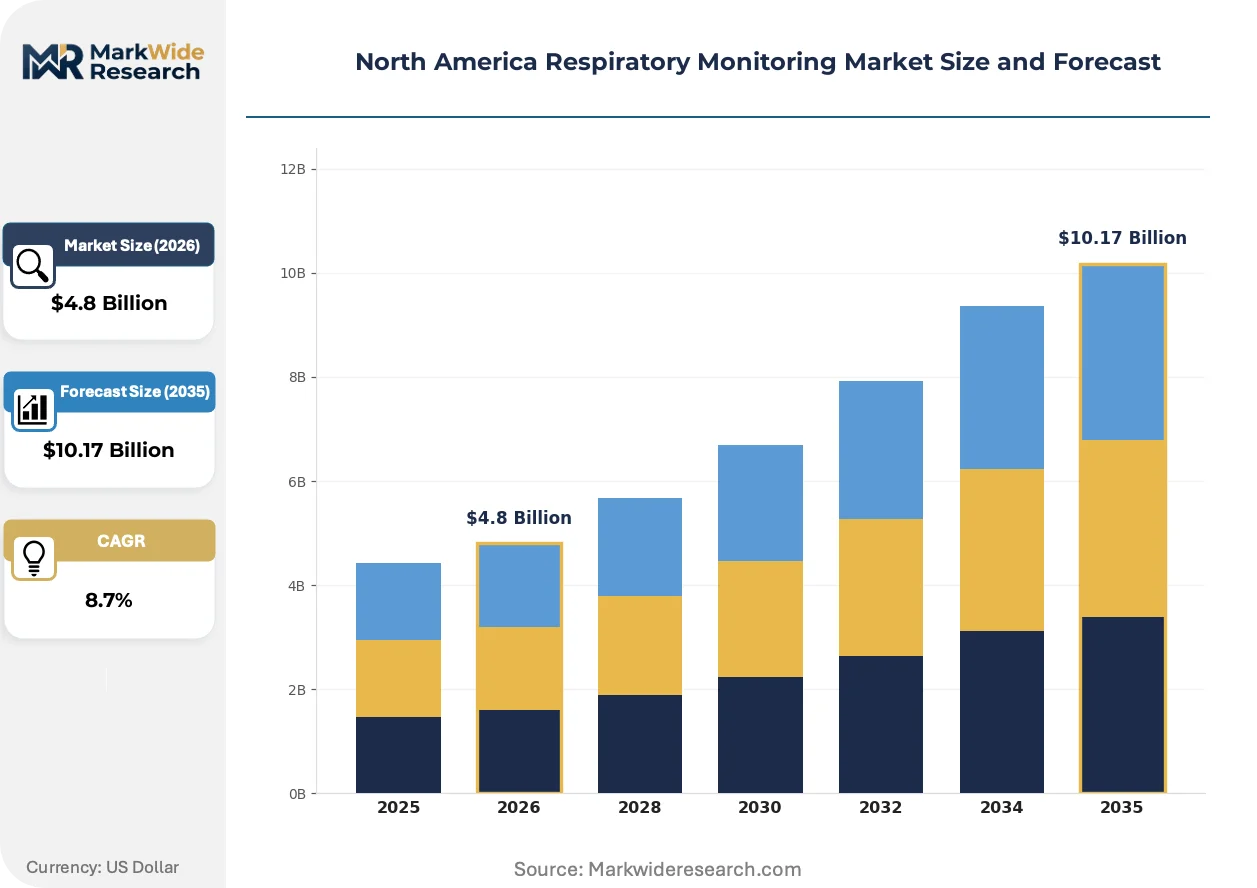
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Tabletop Monitors, Handheld Devices, Wearable Sensors End User: Home Care, Hospitals, Clinics, Research Institutions Technology: Pulse Oximetry, Capnometry, Spirometry, Acoustic Monitoring Application: Chronic Obstructive Pulmonary Disease, Asthma Management, Sleep Apnea, Lung Function Testing |
| Companies Covered | Philips Healthcare, Medtronic, ResMed, Masimo Corporation, Nihon Kohden Corporation, GE Healthcare, Drägerwerk AG & Co. KGaA, Getinge AB, Vyaire Medical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Respiratory Monitoring Market Evolving Landscape
Optical sensing architectures are fragmenting into modular, application-specific configurations that separate hardware acquisition from algorithmic service layers. This decomposition is redrawing value capture across the respiratory monitoring stack.
Reflectance pulse oximetry is decomposing the traditional fingertip sensor monopoly by enabling placement at alternative anatomical sites. Emergency medical services and sleep laboratories are adopting forehead and ear canal configurations for patients with compromised peripheral perfusion. This flexibility is compressing the addressable market for conventional transmission-mode devices while expanding total monitoring occasions.
Health Canada Medical Device Licensing harmonization with FDA quality system regulations is reducing duplicative audit burdens for cross-border manufacturers. Dual-registered production facilities in Ontario and Quebec are consolidating regulatory affairs functions. The acute care segment is responding by prioritizing devices with concurrent US-Canadian approvals to simplify procurement standardization.
Hospital procurement departments are unbundling device hardware from data analytics subscriptions, forcing manufacturers to defend recurring revenue through software differentiation. This disintermediation of the traditional capital sale model is most visible in integrated delivery networks across Texas and California, where multi-hospital systems negotiate enterprise-wide respiratory monitoring platforms with separate pricing for sensors, gateways, and cloud dashboards.
North America Respiratory Monitoring Market Segmentation
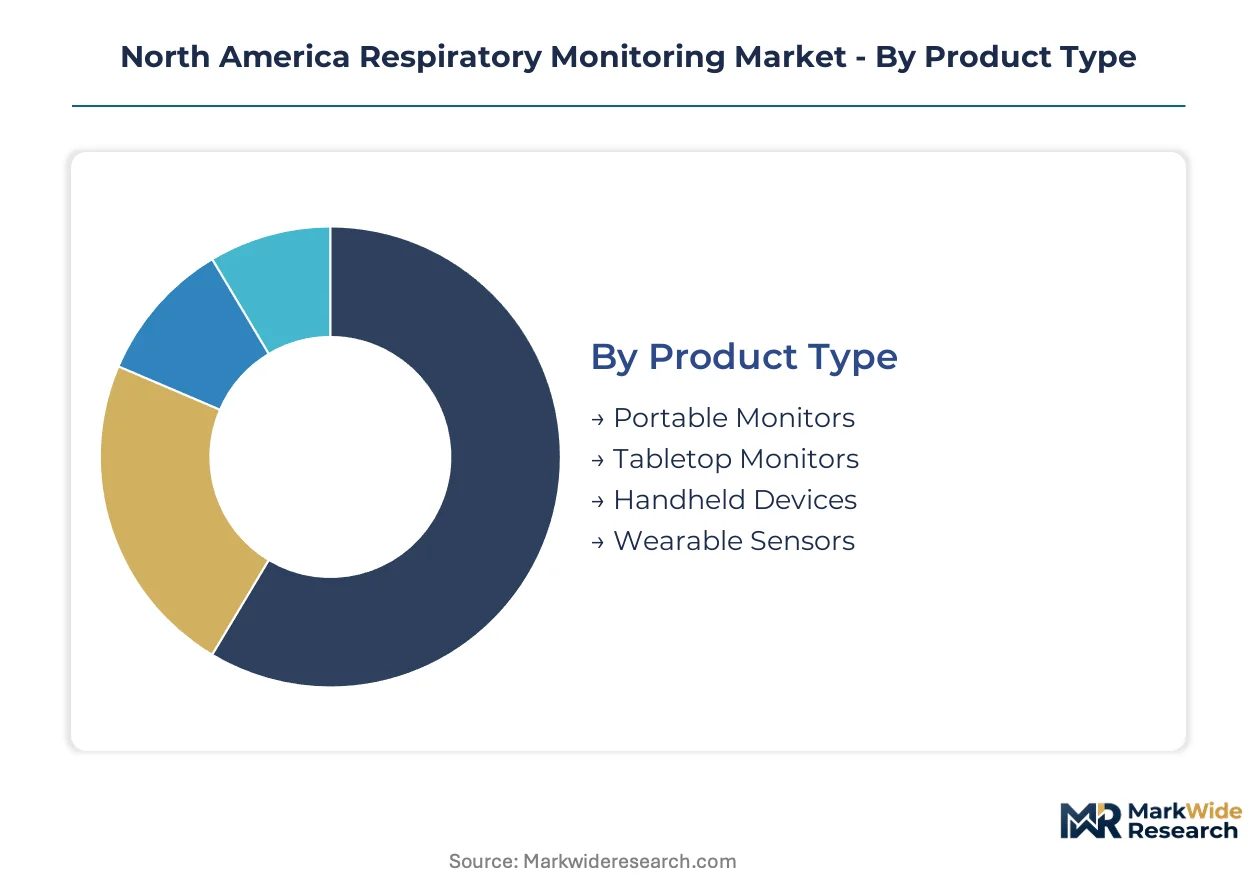
Respiratory monitoring equipment fragments across four distinct taxonomies that determine procurement pathways, reimbursement codes, and competitive positioning. Each segmentation axis reveals divergent margin structures and regulatory exposure profiles that shape vendor strategy across the United States, Canada, and Mexico.
Product Type:
Domestic demand concentrates in portable and wearable configurations that bypass hospital capital committees, while tabletop systems retain export concentration toward Canadian and Mexican institutional buyers.
- Portable Monitors:Battery-powered multi-parameter units weighing under 2 kg integrate pulse oximetry with capnography for ambulance and home care deployment. United States EMS agencies in Texas and California are standardizing on these devices to replace stationary bedside equipment.
- Wearable Sensors:Semiconductor miniaturization enables continuous respiratory rate and oxygen saturation streaming via Bluetooth Low Energy protocols. CMS reimbursement code expansions for remote patient monitoring are accelerating Medicare-covered deployment in rural US markets.
- Tabletop Monitors:AC-powered units with 12-15 inch displays serve ICU and operating room environments requiring simultaneous multi-patient visibility.
- Handheld Devices:Single-parameter pocket units dominate clinician spot-check workflows in Mexican outpatient clinics where capital constraints limit equipment procurement.
Portable monitors hold the largest share; momentum sits with wearable sensors.
End User:
Cost tier stratification separates premium hospital installations from economy home care deployments, with clinics occupying a mid-tier procurement position sensitive to bundled reimbursement rates.
- Home Care:Patient-operated pulse oximeters and overnight capnography systems bypass clinical oversight through cloud-connected dashboards. FDA 510(k) clearances for over-the-counter pulse oximetry are expanding direct-to-consumer channels beyond traditional Durable Medical Equipment suppliers.
- Hospitals:Enterprise-wide telemetry networks demand HL7 FHIR interoperability and centralized alarm management. Integrated delivery networks in Ontario and Quebec negotiate multi-year service contracts that bundle hardware, software, and biomed support.
- Clinics:Federally qualified health centers in US border states prioritize dual-purpose devices that serve both walk-in respiratory assessment and telemedicine consultation workflows.
- Research Institutions:Academic medical centers in Boston and Toronto procure research-grade spirometry with raw data export capabilities for algorithm development.
Hospitals retain the dominant revenue pool; home care is climbing the fastest.
Technology:
Application maturity separates established optical modalities from emerging acoustic architectures, with corresponding divergence in regulatory pathway complexity and clinical validation requirements.
- Pulse Oximetry:Dual-wavelength photoplethysmography at 660 nm and 940 nm quantifies oxygen saturation through differential hemoglobin absorption. FDA predicate device pathways enable rapid iteration of sensor form factors for alternative anatomical placement.
- Capnometry:Sidestream and mainstream infrared spectroscopy measures end-tidal CO2 for airway patency verification. Ambulatory surgery centers across the US Southwest are mandating capnography integration for procedural sedation monitoring.
- Spirometry:Volume-displacement and flow-sensing configurations document forced expiratory volume for COPD staging.
- Acoustic Monitoring:Contact microphone arrays detect respiratory rate and airflow obstruction through tracheal sound analysis.
Pulse oximetry holds the largest share; momentum sits with acoustic monitoring.
Application:
Volume concentration aligns with chronic disease prevalence, while margin concentration follows reimbursement intensity and monitoring frequency requirements.
- Chronic Obstructive Pulmonary Disease:Long-term oxygen therapy qualification requires documented resting and ambulatory oxygen saturation below 88 percent. Medicare Advantage plans in Florida and Arizona are deploying connected oximetry to reduce acute exacerbation hospitalizations.
- Sleep Apnea:Home sleep testing devices with peripheral arterial tone and oximetry channels displace in-laboratory polysomnography for diagnostic screening. Health Canada licensing harmonization enables concurrent US-Canadian product launches.
- Asthma Management:Peak flow meters and fractional exhaled nitric oxide devices guide anti-inflammatory therapy titration in pediatric populations.
- Lung Function Testing:Body plethysmography and diffusion capacity assessment serve occupational health surveillance and pre-surgical risk stratification.
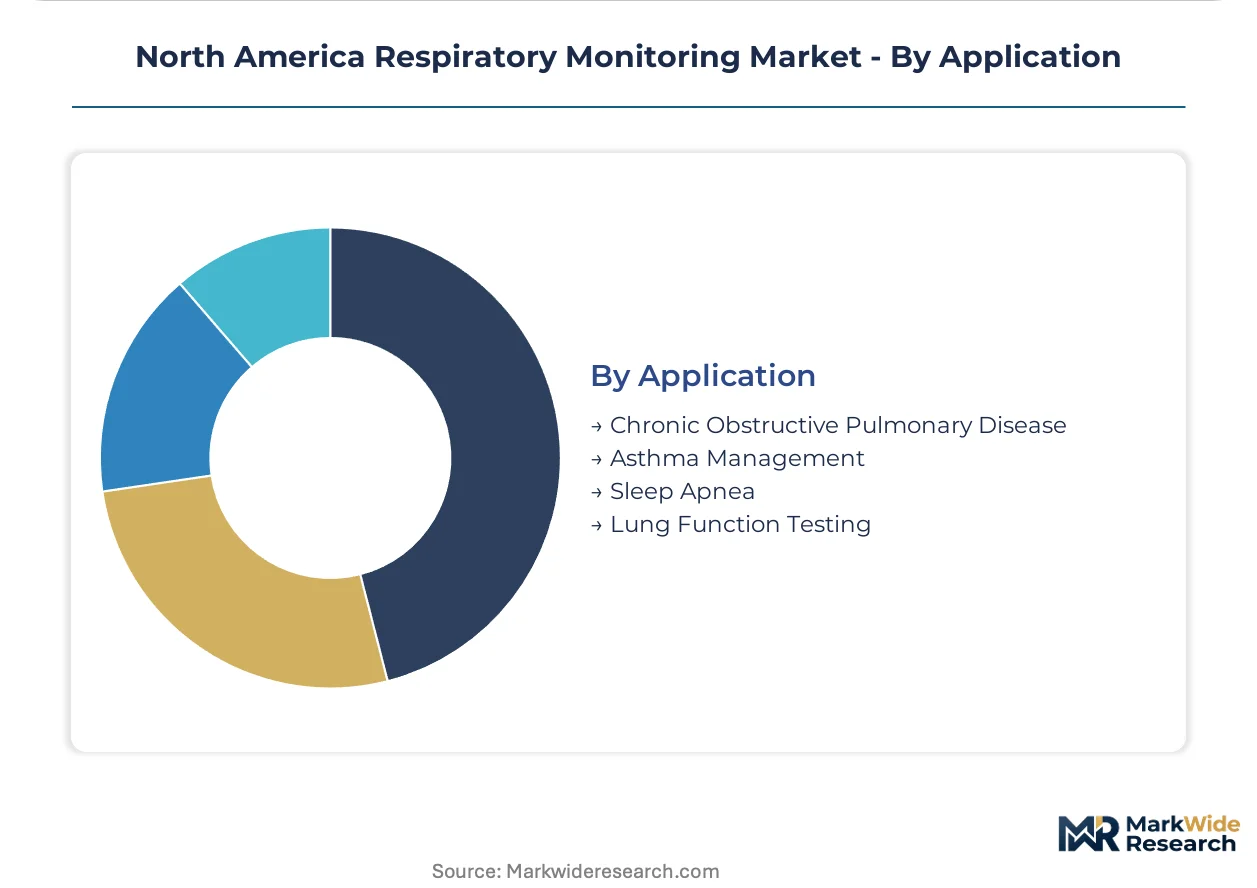
COPD management holds the largest share; sleep apnea is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States drive the largest volume commitments, while Canadian institutional buyers prioritize dual-registered devices and Mexican manufacturing clusters capture export-oriented production. Buyer archetypes split across integrated delivery networks, ambulatory surgery centers, and home care distributors with divergent compliance requirements.
United States
Integrated delivery networks in Texas and California negotiate enterprise-wide telemetry contracts that bundle hardware, software, and biomed support. CMS reimbursement code expansions for remote patient monitoring accelerate Medicare-covered home deployment. FDA 510(k) clearance pathways in Silver Spring, Maryland shape competitive entry timelines for pulse oximetry and capnography predicate devices.
Canada
Health Canada Medical Device Licensing harmonization with FDA quality system regulations reduces duplicative audit burdens for cross-border manufacturers. Dual-registered production facilities in Ontario and Quebec consolidate regulatory affairs functions. Academic medical centers in Toronto procure research-grade spirometry with raw data export capabilities for algorithm development partnerships.
Mexico
Medical device production clusters in Baja California and Tijuana offer tariff-advantaged export platforms serving US demand. Capital constraints in Mexican outpatient clinics drive procurement of handheld single-parameter devices for clinician spot-check workflows. ANVISA-aligned quality standards in Tijuana maquiladoras position manufacturers for Latin American market access.
Greater Boston
Research institutions in Massachusetts anchor algorithm development for AI-enabled respiratory failure prediction. NIH-funded clinical trials at Boston-area medical centers validate acoustic monitoring architectures. Venture-backed sensor startups in Cambridge compete with consumer electronics firms for embedded systems engineering talent.
North America Respiratory Monitoring Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with ventilator-to-monitor integration capabilities and specialized respiratory device pure-plays with cloud-connected home care platforms. Market structure concentrates around three strategic archetypes: acute care system integrators, ambulatory monitoring specialists, and home sleep therapy platform operators. Dominant competitive moves include strategic partnerships for HIPAA-compliant data architecture and portfolio diversification into wearable sensor form factors.
Within the acute care system integrator tier, Philips Healthcare and GE Healthcare exemplify diversified conglomerates with enterprise telemetry capabilities. Medtronic occupies a position bridging hospital and ambulatory segments through sensor miniaturization investment. ResMed anchors the home care pure-play archetype with cloud-connected devices that bypass traditional hospital procurement cycles. These three companies represent distinct competitive vectors: integrated platform scale, sensor technology depth, and direct-to-patient channel control.
| Leading Market Players |
|---|
| Philips Healthcare |
| Medtronic |
| ResMed |
| Masimo Corporation |
| Nihon Kohden Corporation |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Getinge AB |
| Vyaire Medical |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between integrated delivery networks and device manufacturers lock in multi-year supply access while capping price escalation through indexed material cost adjustments. These structures transfer semiconductor volatility risk to vendors while securing predictable procurement budgets for hospital systems across Texas and California.
Pricing Analysis
Cost-plus contracts with photodiode indexation dominate component sourcing agreements between device manufacturers and East Asian foundries. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hospital-grade monitors from over-the-counter home devices and unbranded clinic spot-check units. Pricing pressure stems from CMS reimbursement compression on remote patient monitoring codes, squeezing margins for cloud-connected wearable platforms. Home care distributors exhibit highest price sensitivity due to thin Durable Medical Equipment supplier margins, while academic medical centers retain lowest sensitivity given research grant funding buffers.
Supply Chain Analysis
Taiwan and South Korea anchor photodiode and LED chip fabrication for pulse oximetry sensors, while Mexico's Baja California maquiladoras assemble finished devices for tariff-advantaged US export. Semiconductor wafers, infrared optical components, and Bluetooth Low Energy modules constitute critical input dependencies. Single-source vulnerability concentrates in 940 nm LED supply from specific Taiwanese foundries. Distribution runs through group purchasing organizations for hospital procurement and direct-to-patient e-commerce channels for home care bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation across Texas and California, compressing vendor margins as enterprise-wide telemetry contracts displace fragmented hospital-by-hospital procurement.
For Market Incumbents: Secure cloud infrastructure partnerships with HIPAA-compliant data architectures to defend recurring revenue streams against software disintermediation. Deepen sensor miniaturization R&D to maintain technology differentiation as semiconductor fabrication commoditizes. Capacity reservation agreements with Taiwanese foundries hedge photodiode supply disruption. For New Entrants and Emerging Players: FDA 510(k) predicate device fast-tracks enable rapid market entry for pulse oximetry form factor innovations targeting alternative anatomical placement. Rural Medicare Advantage plans in Florida and Arizona present the most penetrable white-space for connected COPD management platforms. Direct-to-consumer channels bypass traditional Durable Medical Equipment supplier gatekeeping. For Investors and Strategic Acquirers: Capital is best deployed toward ambulatory monitoring specialists with software-as-medical-device FDA clearances and established cloud data architectures. Long-term viability hinges on reimbursement code expansion sustainability and AI-enabled diagnostic algorithm validation. Watch CMS remote patient monitoring code value adjustments as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Pathway | Expedited clearance for iterative sensor innovations accelerates pulse oximetry form factor deployment. |
| Hospital System Partnership | Enterprise-wide telemetry contracts with Texas IDNs secure multi-year recurring revenue streams. |
| Software Companion Development | HIPAA-compliant cloud dashboards differentiate hardware vendors from commodity sensor suppliers. |
| Reimbursement Strategy | CMS remote patient monitoring code alignment determines commercial viability for home care platforms. |
| CE Marking Pathway | Health Canada harmonization enables concurrent US-Canadian product launches for dual-registered facilities. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and remote patient monitoring platform executives and refined through secondary validation against FDA 510(k) clearance databases, CMS reimbursement code filings, Health Canada Medical Device Licensing records, and hospital procurement transaction databases. Bottom-up demand modeling triangulated with top-down market sizing across the analysis window.
Variance decomposition separated volume growth from price trajectory across portable monitor, wearable sensor, tabletop monitor, and handheld device categories. Modeled dimensions spanned product type, end user, technology modality, and application indication. CAGRs derived from weighted average of historical trend extrapolation and driver-based elasticity modeling. Forecast inputs incorporated semiconductor supply lead times and CMS reimbursement code value projections.
Underlying assumptions cover continued FDA 510(k) pathway stability and CMS remote patient monitoring code maintenance, with deviation risk concentrated in semiconductor supply disruption and AI-enabled diagnostic algorithm reclassification. Recalibration cycles align with material shifts in reimbursement policy and regulatory guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Portable Multi-Parameter Monitors Market