
 Gastrointestinal Diagnostics Market | 2026-2036
Gastrointestinal Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Gastrointestinal Diagnostics Market Intelligence
CE-marked molecular assay tiers are redrawing competitive boundaries in gastrointestinal diagnostics. Abbott Laboratories leverages its integrated diagnostics platform to anchor hospital laboratory workflows across North America. bioMérieux specializes in syndromic infectious disease panels that differentiate its offering in infection detection segments. F. Hoffmann-La Roche Ltd. sustains R&D intensity in automated tissue diagnostics that positions it for advanced biopsy applications.
Gastrointestinal diagnostics encompasses in vitro and in vivo methods for detecting structural, functional, and molecular abnormalities of the digestive tract, including enzyme-linked immunosorbent assays with picogram-level sensitivity and video capsule systems capturing 50,000+ images per procedure. The primary purpose is enabling early-stage disease identification to improve therapeutic outcomes and reduce intervention costs. Endoscopy product types occupy mature, high-volume positions while capsule endoscopy technology captures expanding share in small-bowel evaluation where conventional scopes face anatomical limits. Colorectal screening applications command the largest patient throughput, though IBD monitoring segments attract premium pricing through repeat-testing protocols.
The FDA regulates in vitro diagnostic devices through premarket notification and approval pathways that directly shape commercialization timelines for new gastrointestinal assays. EMA's In Vitro Diagnostic Regulation enforces stricter clinical evidence standards for CE-marked products entering European diagnostic labs. The EPA oversees reagent waste streams from high-throughput pathology laboratories, adding operational compliance layers. Stakeholders must weigh regulatory capital requirements against the margin profiles of automated versus manual testing platforms when allocating product development resources.
Market Dynamics
Hospital procurement committees are consolidating vendor relationships around integrated diagnostic platforms that bundle molecular assays with automated workflow management, compressing the addressable supplier base while elevating technical service requirements.
Growth Catalysts
- FDA Stool-Based DNA Guidelines:The agency's evolving reimbursement pathways for non-invasive colorectal screening are accelerating hospital laboratory investment in molecular detection infrastructure.
- Capsule Endoscopy:Video capsule systems capturing 50,000+ images per procedure are displacing conventional scopes in small-bowel evaluation where anatomical limits restrict access.
- Value-Based Care Contracts:United States health systems are embedding early detection protocols into risk-sharing arrangements that reward diagnostic accuracy over procedure volume.
Market Restraints
- Reagent Supply Concentration:High-throughput pathology laboratories depend on concentrated enzyme and antibody suppliers in Germany and Switzerland, exposing workflows to single-source disruption.
- EMA Clinical Evidence Standards:The In Vitro Diagnostic Regulation's stricter documentation requirements are extending CE-marking timelines for European market entry.
- Manual Platform Margin Compression:Automated tissue diagnostics are eroding pricing power for manual histopathology services in hospital settings.
Strategic Opportunities
- IBD Monitoring Protocols:Repeat-testing arrangements for inflammatory bowel disease management command premium pricing through longitudinal patient relationships.
- India Diagnostic Infrastructure:Tier-2 and tier-3 cities present underpenetrated demand for syndromic infectious disease panels as hospital networks expand.
- AI-Assisted Image Analysis:Machine learning integration with capsule endoscopy systems is creating new service revenue streams in image interpretation.
Industry Challenges
- Pathologist Workforce Scarcity:Gastrointestinal subspecialty training programs in the United States are failing to match rising biopsy volumes from screening expansion.
- Laboratory Information System Integration:Molecular assay platforms require costly middleware development to connect with legacy hospital EMR architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastrointestinal Diagnostics Market |
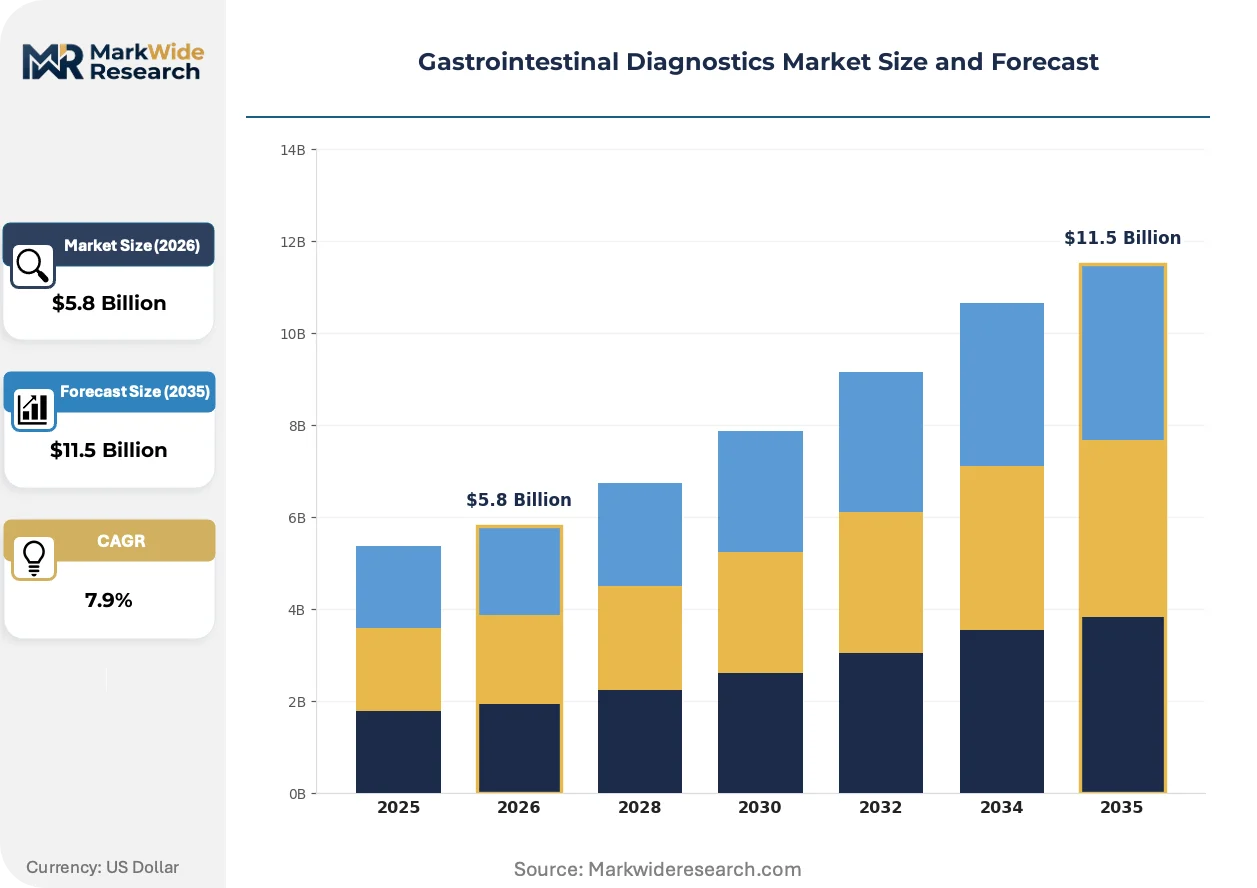
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopy, Imaging, Biopsy, Test Kits Application: Colorectal Screening, GERD Management, IBD Monitoring, Infection Detection Technology: Capsule Endoscopy, Ultrasound, MRI, CT Scans End User: Hospitals, Clinics, Diagnostic Labs, Research Institutes |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd., bioMérieux, Siemens Healthineers AG, QIAGEN, DiaSorin S.p.A, Beckman Coulter, Inc., Meridian Bioscience, Hologic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastrointestinal Diagnostics Market Strategic Shifts & Innovations
Molecular diagnostic platforms are fragmenting into distinct performance tiers that separate premium automated systems from manual laboratory workflows, while regulatory agencies on both sides of the Atlantic rewrite compliance frameworks for next-generation screening technologies.
Next-generation sequencing panels for gastrointestinal cancer profiling are bifurcating the oncology diagnostics market into high-complexity reference laboratories and streamlined hospital-based platforms. Academic medical centers are consolidating molecular pathology services around comprehensive genomic profiling, while community hospitals adopt targeted hotspot panels that prioritize turnaround time over breadth. This technological stratification is compressing the middle market for single-gene assays and forcing reagent suppliers to choose between scale and specialization.
The European Union's In Vitro Diagnostic Regulation is mandating expanded clinical performance studies for CE-marked gastrointestinal assays, forcing manufacturers to generate prospective evidence from European patient populations. This regulatory burden is favoring established players with dedicated European clinical affairs teams while smaller innovators delay market entry. Gastrointestinal cancer screening products face the steepest compliance ramps, with notified bodies prioritizing high-risk device reviews.
Hospital laboratory directors are unbundling after-sales service contracts from capital equipment purchases, negotiating standalone technical support agreements that separate hardware maintenance from assay consumable supply. This procurement pattern is disrupting the traditional bundled pricing model that diagnostic manufacturers relied upon to recover instrument placement costs. The United States health system consolidation is accelerating this shift, as centralized supply chain offices demand line-item transparency across multi-hospital networks.
Gastrointestinal Diagnostics Market Segmentation
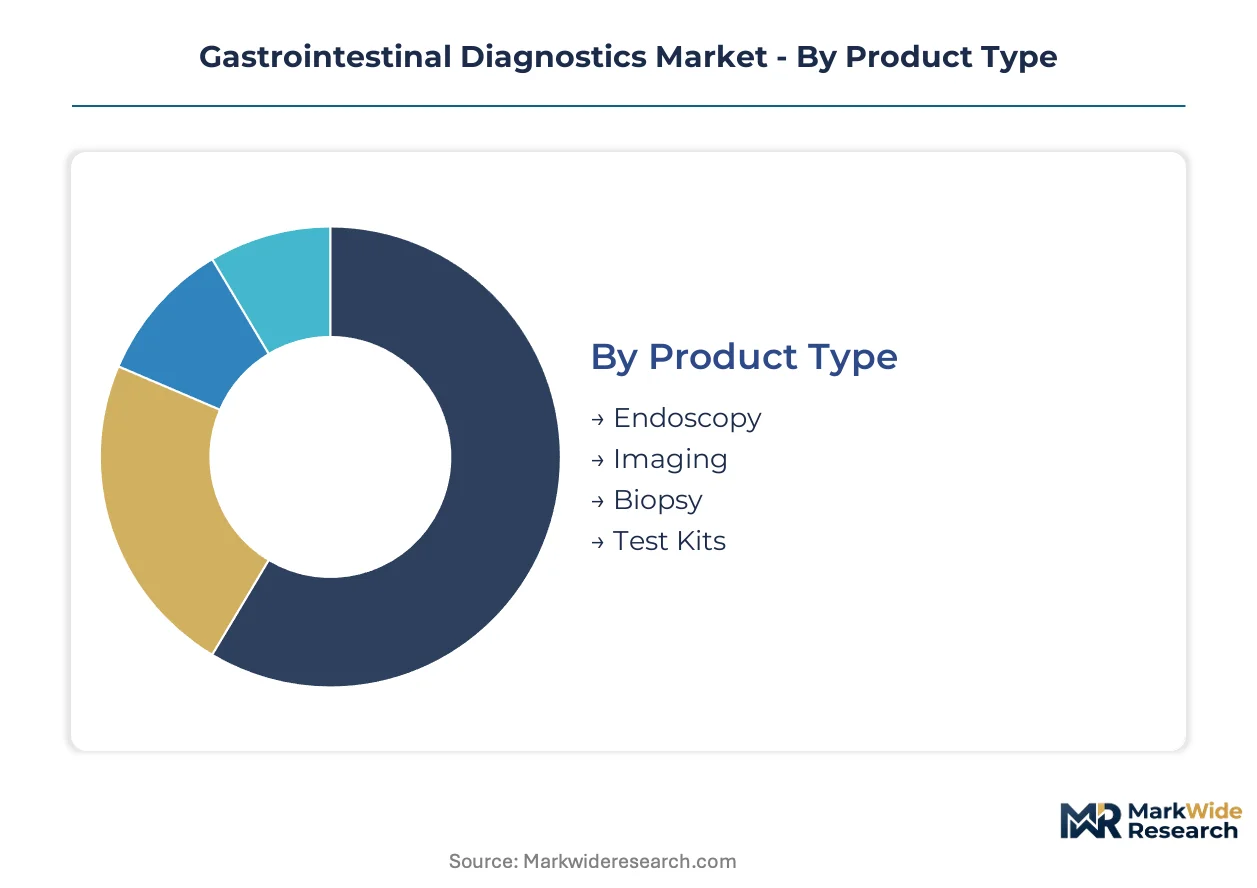
Segmentation in gastrointestinal diagnostics reveals how substitution pressures reshape competitive boundaries across product categories. Hospital procurement committees prioritize integrated platforms that bundle multiple testing modalities, compressing standalone product margins while elevating workflow automation requirements.
Product Type:
Endoscopy faces the strongest substitution threat from capsule systems in small-bowel applications, while biopsy maintains procedural indispensability in histopathological confirmation.
- Endoscopy:Conventional flexible scopes with high-definition imaging capabilities dominate therapeutic interventions where tissue manipulation is required. Demand concentrates in United States hospital systems where value-based care contracts reward diagnostic accuracy, though reimbursement compression is accelerating platform consolidation around single-vendor contracts.
- Test Kits:Molecular stool-based assays with picogram-level sensitivity are displacing invasive screening protocols in asymptomatic populations. United States health systems embed these into population health programs, with FDA guideline evolution directly shaping laboratory infrastructure investment decisions.
- Imaging:Cross-sectional modalities including CT enterography serve complex IBD cases where mucosal healing assessment drives repeat procedure scheduling.
- Biopsy:Tissue acquisition remains the definitive diagnostic standard for dysplasia grading in colorectal surveillance protocols.
Endoscopy retains volume leadership; test kits hold the steepest expansion curve.
Application:
Cost tier stratification separates high-frequency screening applications from premium-priced monitoring segments with repeat-testing economics.
- Colorectal Screening:Population-scale detection programs generate the highest absolute procedure volumes across all gastrointestinal diagnostics. United States health systems deploy non-invasive molecular assays as first-line filters, reserving colonoscopy capacity for positive-screen follow-through where reimbursement rates sustain facility economics.
- IBD Monitoring:Longitudinal disease management protocols command premium pricing through recurring biomarker surveillance and endoscopic mucosal healing assessment. Academic medical centers in the United States consolidate these services around comprehensive genomic profiling platforms that prioritize therapeutic optimization over initial diagnosis.
- GERD Management:Ambulatory pH monitoring and impedance testing serve refractory cases where proton pump inhibitor failure necessitates surgical candidacy evaluation.
- Infection Detection:Syndromic molecular panels differentiate bacterial, viral, and parasitic etiologies in acute diarrheal presentations.
Colorectal screening dominates absolute throughput; IBD monitoring captures the highest per-patient lifetime value.
Technology:
Volume concentration favors established imaging modalities, while technology maturity curves determine capital replacement cycles.
- Capsule Endoscopy:Video capsule systems capturing 50,000+ images per procedure address anatomical segments beyond conventional scope reach. United States hospital laboratories integrate these into small-bowel bleeding protocols where negative CT angiography results redirect diagnostic pathways.
- CT Scans:Rapid acquisition protocols with enteric contrast distension dominate emergency department presentations where obstruction or perforation suspicion demands immediate structural assessment.
- Ultrasound:Point-of-care applications in IBD monitoring leverage sonographic bowel wall thickness measurement for therapy response tracking.
- MRI:Pelvic protocols without ionizing radiation serve young IBD cohorts requiring repeated disease activity surveillance.
CT scans retain volume leadership; capsule endoscopy is climbing the fastest.
End User:
Customer type determines procurement sophistication, with centralized supply chain offices demanding line-item transparency that fragments traditional bundled pricing models.
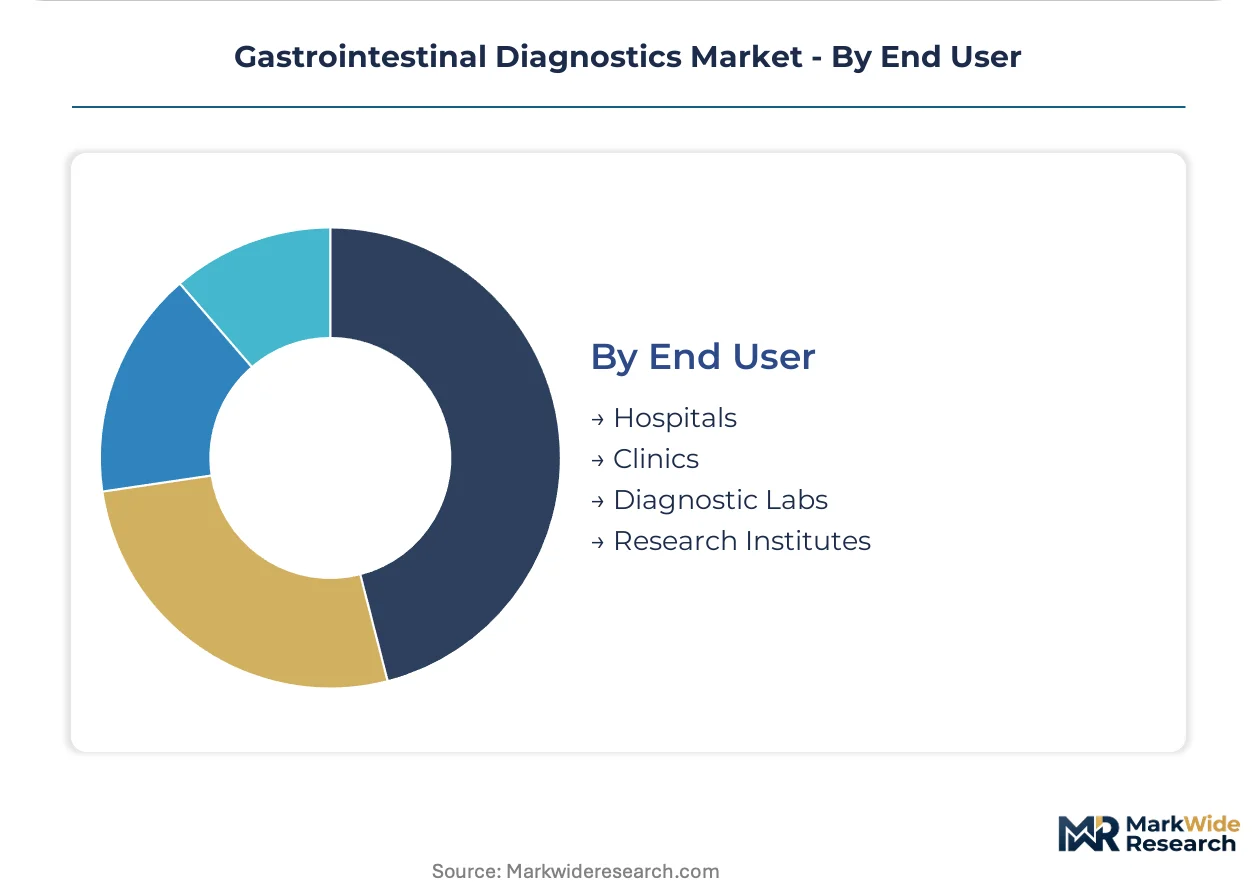
- Hospitals:Integrated delivery networks consolidate vendor relationships around diagnostic platforms that bundle molecular assays with automated workflow management. United States health system mergers are accelerating this concentration, as multi-hospital networks negotiate enterprise pricing with single-source technical service agreements.
- Diagnostic Labs:Independent reference laboratories specialize in high-complexity molecular pathology services that community hospitals outsource. These facilities face EMA In Vitro Diagnostic Regulation compliance ramps that favor established players with dedicated European clinical affairs teams.
- Clinics:Ambulatory settings concentrate rapid antigen testing and fecal immunochemical screening for initial triage.
- Research Institutes:Academic medical centers drive next-generation sequencing panel development for gastrointestinal cancer profiling.
Hospitals dominate capital equipment placement; diagnostic labs are gaining share fastest in molecular assay outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in gastrointestinal diagnostics favor net-importing markets with aging populations, while manufacturing concentration in Germany and Switzerland supplies reagent-dependent laboratories across multiple continents. The United States absorbs the largest absolute import volumes of molecular diagnostic platforms, though domestic production of automated tissue diagnostics sustains partial self-sufficiency.
United States
Hospital consolidation into integrated delivery networks concentrates procurement decisions in centralized supply chain offices across multi-state systems. FDA stool-based DNA test guidelines reshape reimbursement pathways for non-invasive colorectal screening, accelerating molecular assay infrastructure investment. The Boston-Cambridge corridor anchors academic medical center demand for next-generation sequencing panels in gastrointestinal cancer profiling.
Germany
High-throughput pathology laboratories depend on concentrated enzyme and antibody suppliers concentrated in Baden-Württemberg and Bavaria. EMA In Vitro Diagnostic Regulation enforcement extends CE-marking timelines, favoring established manufacturers with dedicated clinical affairs teams. The Rhine-Main cluster around Frankfurt hosts diagnostic reagent production facilities serving hospital laboratories across the European Union.
China
Tier-2 and tier-3 city hospital networks expand diagnostic infrastructure as domestic manufacturers scale syndromic infectious disease panel production. NMPA regulatory pathways for in vitro diagnostic devices prioritize clinical performance studies conducted within Chinese patient populations. The Yangtze River Delta around Shanghai concentrates capsule endoscopy system assembly operations for domestic consumption and selective export.
India
Diagnostic laboratory chains in Maharashtra and Karnataka deploy syndromic molecular panels as hospital networks penetrate tier-2 cities previously dependent on manual microscopy. CDSCO medical device regulations for in vitro diagnostics mandate local clinical trials for imported assay platforms. The Delhi-NCR corridor attracts reference laboratory investment targeting gastrointestinal cancer screening demand from northern states.
Japan
Aging demographics drive demand for non-invasive colorectal screening alternatives to conventional colonoscopy in urban prefectures. PMDA regulatory review timelines for novel molecular diagnostics maintain rigorous clinical evidence standards that filter market entrants. The Kansai region around Osaka maintains concentration in automated tissue processing equipment manufacturing for domestic hospital laboratories.
Gastrointestinal Diagnostics Market Key Industry Players
Concentration sits with diversified diagnostic conglomerates that bundle molecular assays with automated workflow platforms, compressing the addressable supplier base for standalone reagent manufacturers. Hospital procurement committees negotiate enterprise pricing with single-source technical service agreements, elevating barriers for mid-scale entrants lacking integrated platform portfolios. Three archetypes dominate: integrated diagnostics platforms, syndromic infectious disease specialists, and automated tissue diagnostics developers. Competitive moves center on unbundling after-sales service contracts from capital equipment purchases and consolidating molecular pathology services around comprehensive genomic profiling.
Within the integrated platform tier, Abbott Laboratories and F. Hoffmann-La Roche Ltd. occupy positions anchoring hospital laboratory workflows across North America and Europe. bioMérieux represents the syndromic panel specialization archetype, differentiating through infectious disease detection segments. These three entities exemplify how regulatory capital requirements and technical service scale separate sustainable competitors from niche position holders.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| bioMérieux |
| Siemens Healthineers AG |
| QIAGEN |
| DiaSorin S.p.A |
| Beckman Coulter, Inc. |
| Meridian Bioscience |
| Hologic, Inc. |
| Others |
Cost & Logistics Intelligence
Long-term assay supply agreements with multi-hospital networks lock in molecular reagent access while compressing per-test price visibility for standalone diagnostic labs. Hospital procurement committees in the United States leverage these contracts to unbundle after-sales service from capital equipment, fragmenting traditional bundled pricing models that manufacturers relied upon to recover instrument placement costs.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels in gastrointestinal diagnostics. Premium automated tissue diagnostics command price premiums through FDA-cleared workflows and integrated technical service, while manual histopathology platforms face margin compression from automation substitution. Pricing pressure stems from value-based care contracts that reward diagnostic accuracy over procedure volume, elevating price sensitivity among independent reference laboratories least equipped to absorb platform consolidation costs.
Supply Chain Analysis
Germany and Switzerland anchor enzyme and antibody production for high-throughput pathology laboratories serving hospital networks across North America and Europe. Reagent supply draws from concentrated specialty chemical manufacturers in Baden-Württemberg and Bavaria, with raw material dependencies on chromatography resins, recombinant proteins, and diagnostic-grade solvents. Single-source vulnerability runs through Swiss antibody suppliers subject to EMA In Vitro Diagnostic Regulation export documentation requirements. Distribution runs through regional diagnostic distributors maintaining cold-chain logistics for temperature-sensitive molecular assay components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation across United States health systems, compressing vendor counts and elevating technical service scale requirements.
For Market Incumbents: Secure molecular assay platform placements through bundled workflow automation that locks out standalone reagent competitors. Deepen backward integration into critical enzyme supply to mitigate single-source disruption risks from Swiss and German suppliers. Anchor hospital laboratory relationships with standalone technical service agreements that separate hardware maintenance from consumable supply. For New Entrants and Emerging Players: Lead with AI-assisted image analysis for capsule endoscopy interpretation as a service-based entry point bypassing capital equipment barriers. Target tier-2 and tier-3 Indian cities where syndromic infectious disease panel demand outpaces domestic manufacturing scale. Pursue CDSCO regulatory pathways with local clinical trial data to differentiate from import-dependent competitors. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors integrated diagnostics conglomerates with European clinical affairs capabilities. Long-term viability over the next decade hinges on CE-marking execution speed under EMA In Vitro Diagnostic Regulation enforcement. Watch FDA stool-based DNA test guideline evolution as the signal for reimbursement pathway expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation compliance accelerates market access for established clinical affairs teams. |
| Hospital System Partnership | Integrated delivery network contracts bundle molecular assays with automated workflow management. |
| Software Companion Development | AI-assisted capsule endoscopy image analysis creates recurring service revenue streams. |
| Reimbursement Strategy | FDA stool-based DNA test guidelines reshape colorectal screening payment pathways. |
| Backward Integration | In-house enzyme production mitigates single-source supply risk from German and Swiss suppliers. |
Research Approach
Desk research of FDA 510(k) filings, EMA CE-marking databases, and hospital procurement contract disclosures preceded structured interviews with hospital laboratory directors, GPO contracts managers, biomedical engineers, and diagnostic reagent procurement leads. Primary fieldwork across United States integrated delivery networks, German pathology laboratory clusters, and Indian diagnostic chains was validated against secondary sources including CMS Medicare reimbursement data, notified body approval registers, and customs trade records. Bottom-up test volume modeling and top-down market sizing triangulated segmentation outputs.
Variance decomposition across product type, application, technology, and end user dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from test volume trajectories and average selling price evolution by segment. Forecast inputs incorporated FDA regulatory timeline assumptions, EMA In Vitro Diagnostic Regulation implementation pace, and hospital consolidation patterns by United States health system.
The analysis sits within stated boundaries; outcomes outside sustained FDA reimbursement pathway expansion or accelerated EMA compliance timelines would require recalibration. Forecasts reflect documented assumptions regarding test kit substitution rates and capsule endoscopy technology adoption curves. Recalibration cycles align with material shifts in regulatory guidance, health system merger activity, and pathologist workforce supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
D-Dimer Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Glaucoma Diagnostics Market