
 Europe Womens Health Diagnostics Market | 2026-2036
Europe Womens Health Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Womens Health Diagnostics Market Analytics
Project finance for large-scale laboratory instrumentation is narrowing the competitive field in European women's health diagnostics. Siemens Healthineers leverages long-term equipment leasing programs to secure multi-year contracts with national health systems. Hologic Inc anchors its position through captive supply of proprietary sample preparation systems tied to screening protocols.
Women's health diagnostics encompasses clinical assays and imaging modalities designed to detect, monitor, and manage conditions specific to female physiology including reproductive function, pregnancy status, oncologic markers, and infectious agents. These systems employ immunoassay chemistry with detection thresholds typically reaching picogram-per-milliliter sensitivity for hormone quantification, serving both centralized laboratories and decentralized care settings. Cancer screening commands the largest revenue pool within product type segments due to established national cervical and breast screening mandates across EU member states, while point-of-care delivery modes are expanding fastest as clinics seek to reduce patient visit cycles for routine pregnancy and infectious disease testing.
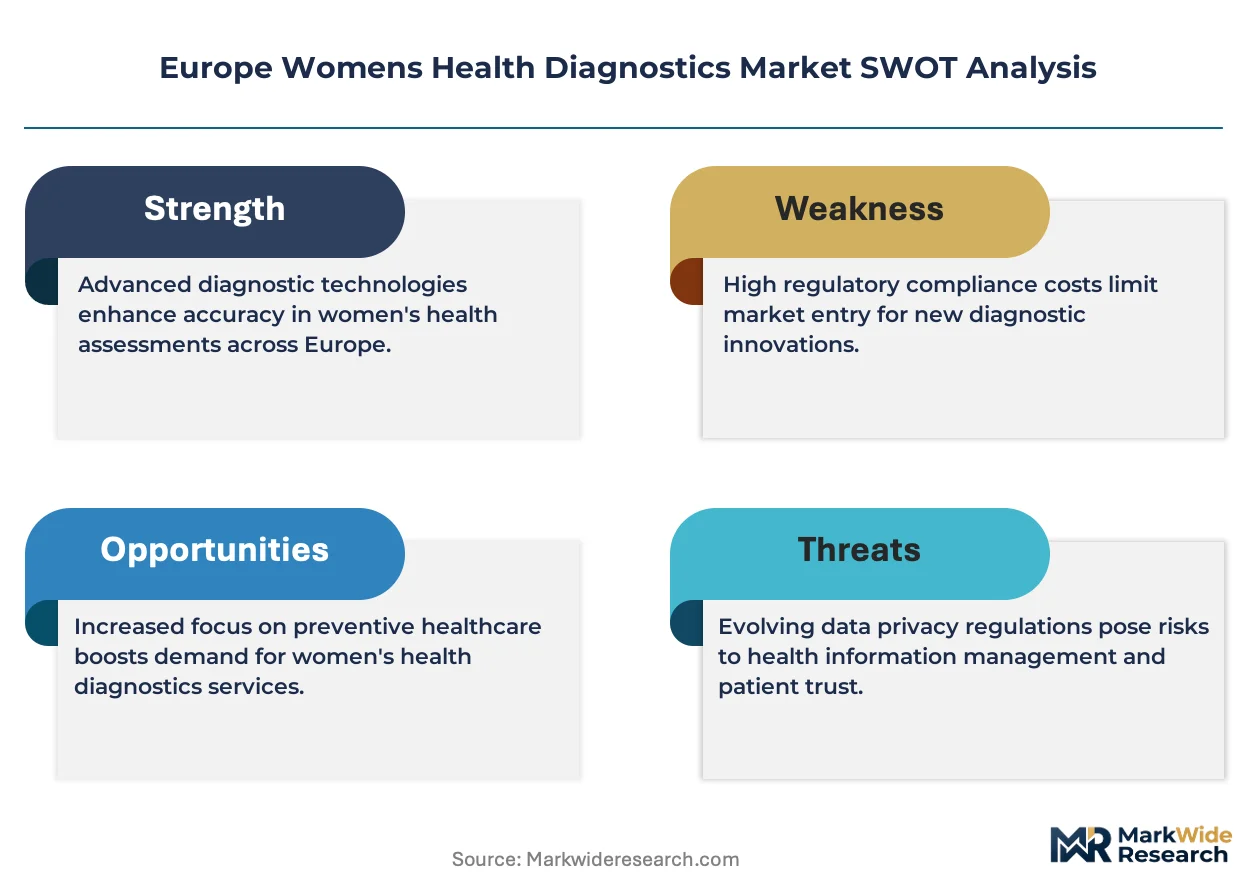
The European Medicines Agency (EMA) coordinates centralized marketing authorization for companion diagnostics linked to oncology therapeutics, while the In Vitro Diagnostic Regulation (IVDR) imposes stricter clinical evidence requirements on legacy test kits. EMA pathways and IVDR compliance deadlines together filter market access, favoring manufacturers with established quality management systems and clinical data repositories. Stakeholders must monitor how notified body capacity constraints affect certification timelines for novel biomarker assays.
Market Dynamics
The European women's health diagnostics sector faces structural pressure from the IVDR transition timeline, which compresses certification windows and forces manufacturers to consolidate clinical evidence portfolios ahead of notified body capacity constraints.
Growth Catalysts
- EMA companion diagnostic pathways:Centralized marketing authorization for oncology-linked assays accelerates commercial rollout across EU member states, creating predictable revenue timelines for biomarker developers.
- Germany's hospital network consolidation:Large-scale laboratory instrumentation procurement at the Land level favors vendors with integrated workflow platforms, pulling through molecular testing volume for HPV and breast cancer screening.
- Point-of-care chemistry miniaturization:Picogram-per-milliliter sensitivity thresholds in handheld hormone quantification devices enable decentralized pregnancy and infectious disease testing outside centralized lab infrastructure.
Market Restraints
- Notified body bottlenecks:IVDR technical documentation review queues extend certification timelines for legacy immunoassay kits, freezing product line refreshes and straining working capital.
- Reagent supply concentration:Proprietary sample preparation chemistries for cervical cytology remain captive to single-source suppliers, exposing screening programs to discontinuation risk.
- High-sensitivity antibody specificity:Cross-reactivity in picogram-scale hormone detection generates false-positive rates that undermine clinical confidence in decentralized testing modalities.
Strategic Opportunities
- France's regional screening digitization:Integration of digital pathology platforms with centralized cytology hubs creates demand for AI-augmented diagnostic software in cervical cancer programs.
- At-home infectious disease sampling:Self-collection devices for STI panels bypass clinic visit cycles, opening direct-to-patient channels previously blocked by sample stability requirements.
- EU Green Deal procurement criteria:Sustainability disclosure mandates in public health tenders favor manufacturers with lifecycle-assessed reagent packaging and energy-efficient instrumentation.
Industry Challenges
- IVDR clinical evidence generation:Retrospective studies for legacy assays require access to archived patient cohorts with linked outcomes, a capability concentrated in academic medical centers with restrictive data-sharing protocols.
- Interoperability with hospital information systems:Point-of-care devices must map results to HL7 FHIR standards for integration with centralized laboratory information management systems, demanding specialized firmware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Womens Health Diagnostics Market |
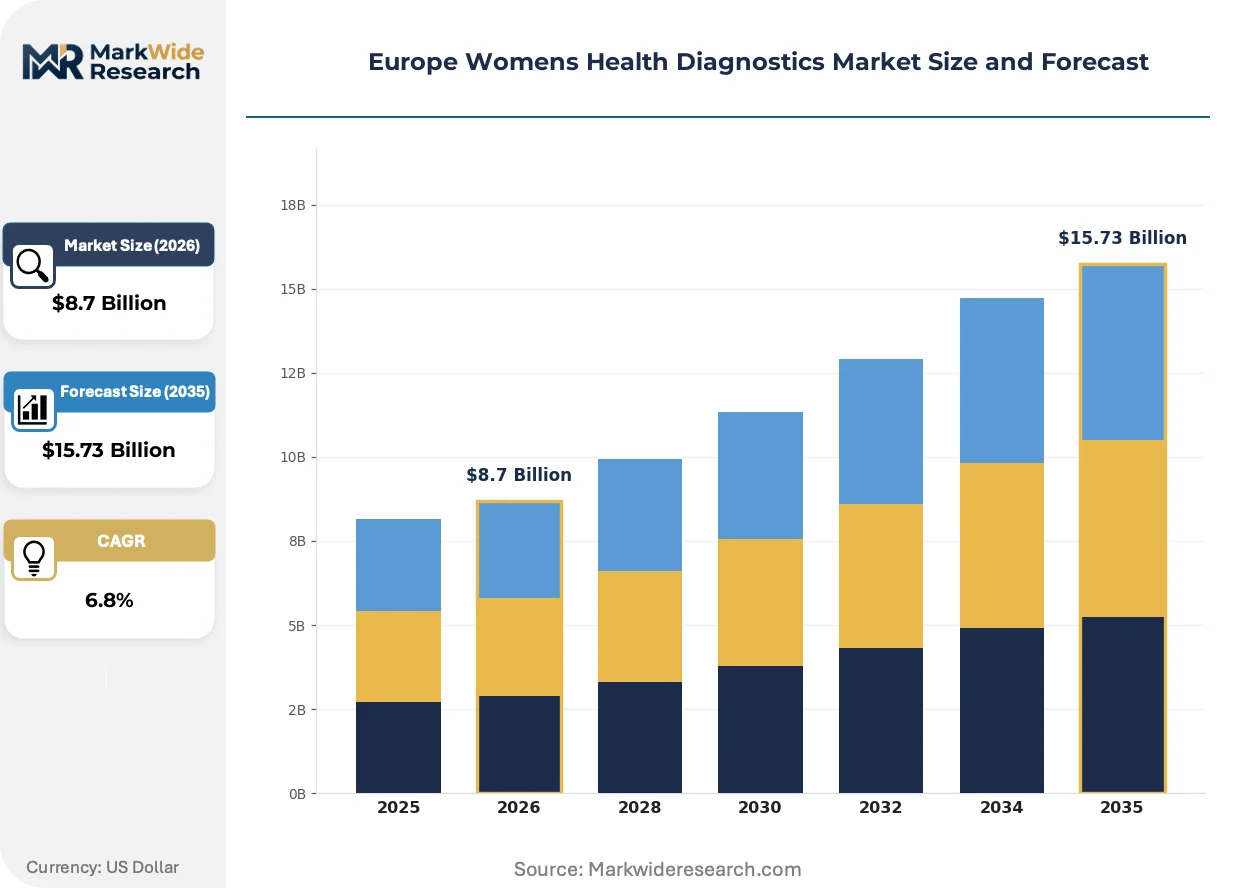
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Tests, Pregnancy Tests, Infectious Disease Tests, Cancer Screening Technology: ELISA, PCR, Immunoassay, Microarray End User: Hospitals, Diagnostic Laboratories, Clinics, Home Care Delivery Mode: Point of Care, Laboratory Testing, Remote Monitoring, Telehealth |
| Companies Covered | Roche Diagnostics, Siemens Healthineers, Hologic Inc, Abbott Laboratories, GE HealthCare, Koninklijke Philips NV, Quest Diagnostics Incorporated, Becton Dickinson, bioMérieux SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Womens Health Diagnostics Market Evolving Landscape
Digital pathology and artificial intelligence are compressing diagnostic turnaround times while regulatory frameworks force simultaneous compliance investment. Three developments dominate strategic planning.
Whole-slide imaging coupled with computational cytology is virtualizing the physical microscopy workflow that has defined cervical cancer screening for decades. Regional pathology networks in France and the Netherlands are deploying these platforms at scale to address workforce shortages. The technology is virtualizing glass-slide logistics, eliminating courier-dependent transport between collection sites and centralized reading centers.
EMA's expanded mandate for companion diagnostic co-development with oncology therapeutics is tightening evidentiary standards for biomarker assays. Manufacturers must now generate prospective clinical utility data rather than relying on analytical validation alone. Breast cancer HER2 testing protocols face the steepest compliance burden, with notified bodies demanding extended follow-up cohorts.
Hospital procurement departments are unbundling after-sales service contracts from equipment leases, forcing diagnostic vendors to compete on discrete maintenance pricing. German university hospitals pioneered this shift, and the model is spreading to French and Italian regional health authorities. Radiology and pathology departments now source break-fix coverage from third-party service integrators rather than original equipment manufacturers.
Europe Womens Health Diagnostics Market Segmentation
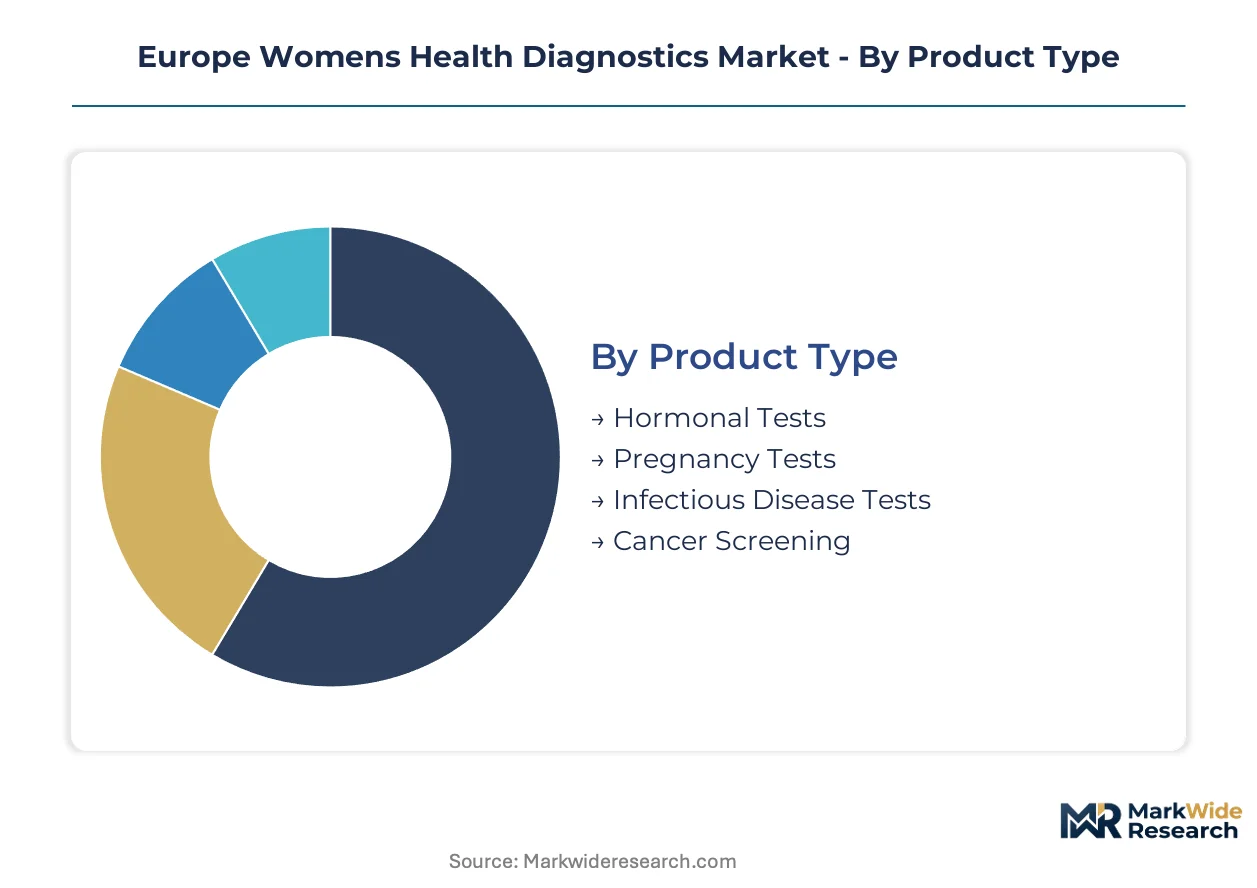
Segmentation in European women's health diagnostics reveals how regulatory frameworks, care delivery models, and technology maturation create distinct competitive arenas. Product type and delivery mode segments face divergent certification pressures under IVDR, while end-user concentration in hospital networks shapes procurement leverage across the region.
Product Type:
Cost tier stratification separates commodity screening assays from premium molecular diagnostics, with reimbursement schedules reinforcing tier boundaries.
- Hormonal Tests:Immunoassay-based quantification of estradiol, progesterone, and FSH operates at picogram-per-milliliter sensitivity thresholds. German hospital networks concentrate demand for automated analyzer-compatible formats, though IVDR clinical evidence requirements for legacy fertility panels extend recertification timelines.
- Cancer Screening:Cervical cytology and breast cancer biomarker assays command the highest revenue concentration within this category. France's regional screening digitization programs and established EU-wide mammography mandates sustain volume, while HER2 companion diagnostic co-development with EMA-linked oncology therapeutics tightens evidentiary standards.
- Pregnancy Tests:Lateral flow human chorionic gonadotropin detection dominates home-use channels across Western Europe.
- Infectious Disease Tests:HPV and STI panels integrate into national prevention programs with centralized laboratory procurement.
Cancer screening holds installed capacity. Infectious disease testing is rotating up the share rankings.
Technology:
Application maturity varies sharply, with nucleic acid amplification displacing serological methods in oncology and infectious disease workflows.
- PCR:Real-time amplification platforms enable HPV genotyping and breast cancer mutation screening with analytical specificity exceeding 99%. Diagnostic laboratories in Germany and the Netherlands concentrate installed base expansion, driven by EMA companion diagnostic mandates requiring quantitative nucleic acid detection.
- Immunoassay:Chemiluminescent and electrochemiluminescent detection systems anchor hormone quantification and tumor marker workflows. Siemens Healthineers and Roche Diagnostics dominate analyzer placements in French and Italian hospital networks, with long-term reagent rental contracts locking in volume commitments.
- ELISA:Enzyme-linked formats persist in research-use and lower-throughput clinical settings across Southern Europe.
- Microarray:Multiplexed nucleic acid detection supports pharmacogenomic and complex genotyping applications in academic medical centers.
Immunoassay maintains analyzer fleet dominance. PCR is climbing the fastest as molecular menus expand.
End User:
Customer type determines procurement complexity, with centralized tenders favoring integrated workflow vendors over point solution specialists.
- Diagnostic Laboratories:High-throughput automated platforms process national screening program volumes for cervical cytology and HPV testing. Germany's Land-level hospital network consolidation creates procurement leverage for multi-year instrumentation leases tied to reagent minimums.
- Hospitals:Acute care settings integrate STAT laboratory testing with core laboratory workflows, demanding bidirectional LIS connectivity and middleware compatibility. French university hospitals pioneered unbundled service contract sourcing, now spreading to Italian regional health authorities.
- Clinics:Outpatient facilities drive point-of-care chemistry miniaturization for pregnancy and infectious disease testing.
- Home Care:Self-collection devices for STI panels bypass traditional clinic channels, opening direct-to-patient distribution.
Diagnostic laboratories command volume concentration. Home care is gaining share fastest through sampling innovation.
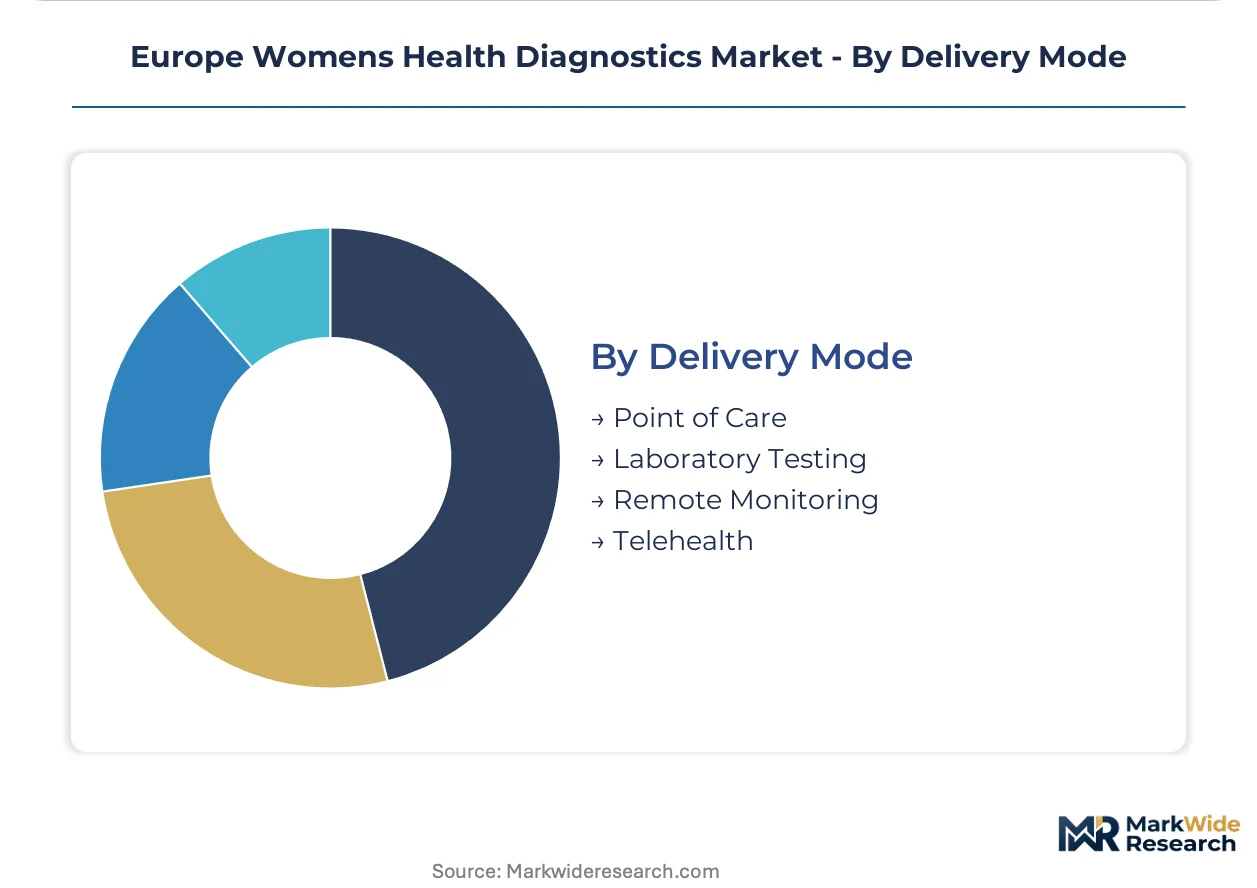
Delivery Mode:
Geography shapes deployment feasibility, with rural coverage gaps accelerating decentralized modalities in Nordic and Mediterranean peripheries.
- Laboratory Testing:Centralized processing with automated pre-analytical handling sustains quality control for cancer screening programs. Dutch and Danish regional pathology networks deploy digital pathology platforms to virtualize glass-slide logistics, eliminating courier-dependent transport between collection sites and reading centers.
- Point of Care:Handheld hormone quantification and rapid infectious disease testing reduce patient visit cycles in primary care settings. Cross-reactivity in picogram-scale detection generates false-positive rates that undermine clinical confidence, constraining expansion beyond pregnancy confirmation.
- Remote Monitoring:Connected devices for fertility tracking and chronic condition management extend monitoring outside clinical encounters.
- Telehealth:Virtual consultation integration with at-home sampling creates hybrid care pathways for STI and reproductive health screening.
Laboratory testing anchors quality-assured diagnostics. Point of care shows the steepest expansion trajectory as miniaturization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German hospital networks while French regional screening programs negotiate from standardized tariff schedules. This asymmetry shapes vendor contract structures across the continent.
Germany
Land-level hospital consolidation drives multi-year instrumentation leases with reagent minimums. IVDR compliance deadlines compress certification windows for legacy immunoassay kits. Siemens Healthineers anchors the Bavarian diagnostics corridor with automated analyzer placements tied to national screening volumes.
France
Regional pathology digitization programs create demand for AI-augmented cervical cytology platforms. ANSM coordinates post-market surveillance for companion diagnostics under EMA-linked oncology protocols. The Île-de-France screening hub virtualizes glass-slide logistics through whole-slide imaging deployment.
United Kingdom
NHS England's centralized procurement framework favors vendors with integrated laboratory information system connectivity. MHRA operates parallel regulatory pathways for IVDs during the post-Brexit transition. London teaching hospitals concentrate demand for high-throughput molecular testing platforms.
Netherlands
Dutch regional pathology networks deploy digital platforms to eliminate courier-dependent specimen transport. EMA centralized marketing authorization accelerates commercial rollout for biomarker assays. The Utrecht-Leiden corridor houses specialized cytology hubs serving national screening programs.
Italy
Regional health authorities unbundle service contracts from equipment leases, forcing discrete maintenance pricing competition. IVDR notified body capacity constraints extend timelines for kit recertification. Lombardy hospital networks integrate point-of-care chemistry with centralized laboratory workflows.
Europe Womens Health Diagnostics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The European women's health diagnostics sector exhibits tiered consolidation, with multinational conglomerates controlling analyzer placements and mid-cap manufacturers competing on assay menu breadth. Three archetypes dominate: integrated workflow vendors with captive reagent streams, point-of-care miniaturization specialists, and digital pathology software providers. Competitive moves concentrate on long-term equipment leasing structures and unbundled service contract sourcing.
Within the integrated platform tier, Roche Diagnostics and Siemens Healthineers exemplify the equipment-plus-consumables model that locks hospital networks into multi-year volume commitments. Hologic Inc occupies a position in the sample preparation systems segment, anchoring proprietary workflows tied to screening protocols. These three entities represent distinct geographic footprints—Swiss, German, and American origins respectively—while converging on similar contract structures with European national health systems.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Siemens Healthineers |
| Hologic Inc |
| Abbott Laboratories |
| GE HealthCare |
| Koninklijke Philips NV |
| Quest Diagnostics Incorporated |
| Becton Dickinson |
| bioMérieux SA |
| Others |
Value Network & Pricing Analysis
Single-source dependency on proprietary sample preparation chemistries for cervical cytology concentrates pricing power among captive suppliers while compressing margin flexibility for screening program operators across German and French hospital networks. IVDR recertification timelines extend working capital cycles for legacy immunoassay manufacturers, forcing tier spreads that separate EMA-validated companion diagnostics from commodity hormone quantification panels.
Pricing Analysis
Diagnostic laboratory procurement managers anchor three-tier pricing structure across premium, standard, and economy levels, with EMA companion diagnostic validation and IVDR certification grade driving the widest spreads. Siemens Healthineers and Roche Diagnostics extract brand premiums through long-term reagent rental contracts tied to analyzer placements, while price erosion runs through economy-tier ELISA formats as Southern European clinics consolidate purchasing. Hospital networks in Germany exhibit lowest price sensitivity due to Land-level budget autonomy, whereas Italian regional health authorities force discrete maintenance pricing competition through unbundled service contract sourcing.
Supply Chain Analysis
Specialized antibody feedstock production centers on the United States, Germany, and Switzerland, with monoclonal reagent supply drawing from academic medical center spin-offs and established diagnostics chemical manufacturers. Polymerase chain reaction enzymes, chemiluminescent substrates, and digital pathology scanner components feed from concentrated vendor bases in the Netherlands and Japan. Single-source vulnerability in HPV genotyping reagent supply exposes screening programs to discontinuation risk, while distribution runs through diagnostic laboratory consortiums and hospital procurement frameworks rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers expand faster than hardware placements as hospital procurement departments unbundle maintenance contracts and demand discrete break-fix pricing, creating recurring income streams that outpace capital equipment sales cycles.
For Market Incumbents: Build captive reagent moats through IVDR-compliant assay menu expansion that locks hospital networks into multi-year volume commitments. Siemens Healthineers anchors this approach with automated analyzer placements tied to Bavarian screening volumes, while Hologic Inc reinforces proprietary sample preparation workflows against emerging digital pathology substitutes. Capacity addition in French regional cytology hubs and certification investment for HER2 companion diagnostics defend against mid-cap molecular specialists.
For New Entrants and Emerging Players: Pursue at-home infectious disease sampling white space where self-collection devices bypass clinic visit cycles and open direct-to-patient channels. Italy's regional health authorities present the most penetrable procurement environment due to unbundled contract structures, while AI-augmented cervical cytology software for French digitization programs offers a software-centric go-to-market angle without heavy analyzer infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated workflow vendors with established notified body relationships and clinical data repositories. Long-term viability hinges on IVDR compliance completion ahead of capacity-constrained certification deadlines. Acquisition targets should demonstrate EMA companion diagnostic co-development experience or digital pathology platform deployment at scale. The signal to watch is notified body queue length for novel biomarker assays, which indicates competitive access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Pathway Acceleration | Notified body engagement ahead of queue congestion secures certification timelines for legacy assay refreshes. |
| Hospital System Partnership | Land-level German contracts lock multi-year reagent minimums through integrated analyzer placements. |
| Software Companion Development | AI-augmented cytology platforms for French regional digitization programs create recurring SaaS revenue. |
| CE Marking Pathway | EMA-linked oncology therapeutic co-development tightens evidentiary standards but accelerates EU-wide rollout. |
| Reimbursement Strategy | National screening program inclusion guarantees volume commitment for HPV and breast cancer assays. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, diagnostic procurement managers, biomedical engineers, and GPO contracts administrators. Secondary validation drew from EMA centralized marketing authorization databases, IVDR notified body certification records, hospital procurement disclosure filings, and regional health authority screening program reports. Bottom-up installed base enumeration for molecular analyzers and top-down revenue triangulation across product type segments were cross-referenced for consistency.
Calibration against historical instrument placement cycles and reagent consumption patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, technology platform maturity, delivery mode deployment, and end-user procurement complexity. CAGRs were derived from slope analysis of instrument replacement cycles and menu expansion trajectories, with EMA companion diagnostic approval velocity and IVDR compliance progression serving as industry-specific forecast inputs.
Sensitivities concentrate around notified body capacity constraints, reagent supply discontinuation events, and hospital network consolidation pace that could accelerate or delay procurement decisions. Cross-checking against national screening program budget allocations and regional pathology network digitization timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Animal Diagnostics Market
Diagnostics
Prostate Cancer Diagnostics Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Preeclampsia Diagnostics Market