
 Latent Tuberculosis Infection Detection Market | 2026-2036
Latent Tuberculosis Infection Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Latent Tuberculosis Infection Detection Market Intelligence
Recombinant antigens are restructuring the economics of latent TB detection by displacing purified protein derivative in tuberculin skin tests with more specific peptide-based formulations. QIAGEN N.V. leverages its QuantiFERON platform to dominate the interferon gamma release assay segment across European reference laboratories. Abbott Laboratories sustains broad geographic reach through integrated molecular diagnostics workflows that anchor hospital laboratory procurement decisions. bioMérieux differentiates via automated sample-to-answer systems that reduce technician hands-on time in high-throughput screening environments.
Latent tuberculosis infection detection encompasses immunological and molecular methods for identifying Mycobacterium tuberculosis infection without active disease symptoms, typically measuring interferon-gamma release after stimulation with ESAT-6 and CFP-10 antigens or detecting bacterial DNA via nucleic acid amplification. The primary purpose is to enable preventive therapy initiation before progression to active tuberculosis, particularly in immunocompromised and close-contact populations. In vitro tests command the largest revenue share due to higher per-test pricing of IGRA platforms, while molecular diagnostics represents the fastest-expanding technology dimension as Gene-Expert systems displace conventional culture methods in resource-limited settings. Public health centers absorb the highest test volumes through national screening mandates, though hospital laboratories generate superior margins from bundled service contracts.
WHO prequalification requirements shape product standards for TB diagnostics in low- and middle-income countries, while FDA clearance governs market access in the United States and influences purchasing decisions across Latin American regulatory agencies. EMA oversight through the In Vitro Diagnostic Medical Devices Regulation tightens clinical evidence requirements for European market entry, favoring established manufacturers with robust quality management systems. Stakeholders must monitor evolving WHO guideline revisions on test algorithm preferences and preemptive regulatory harmonization across African and Southeast Asian national control programs.
Market Dynamics
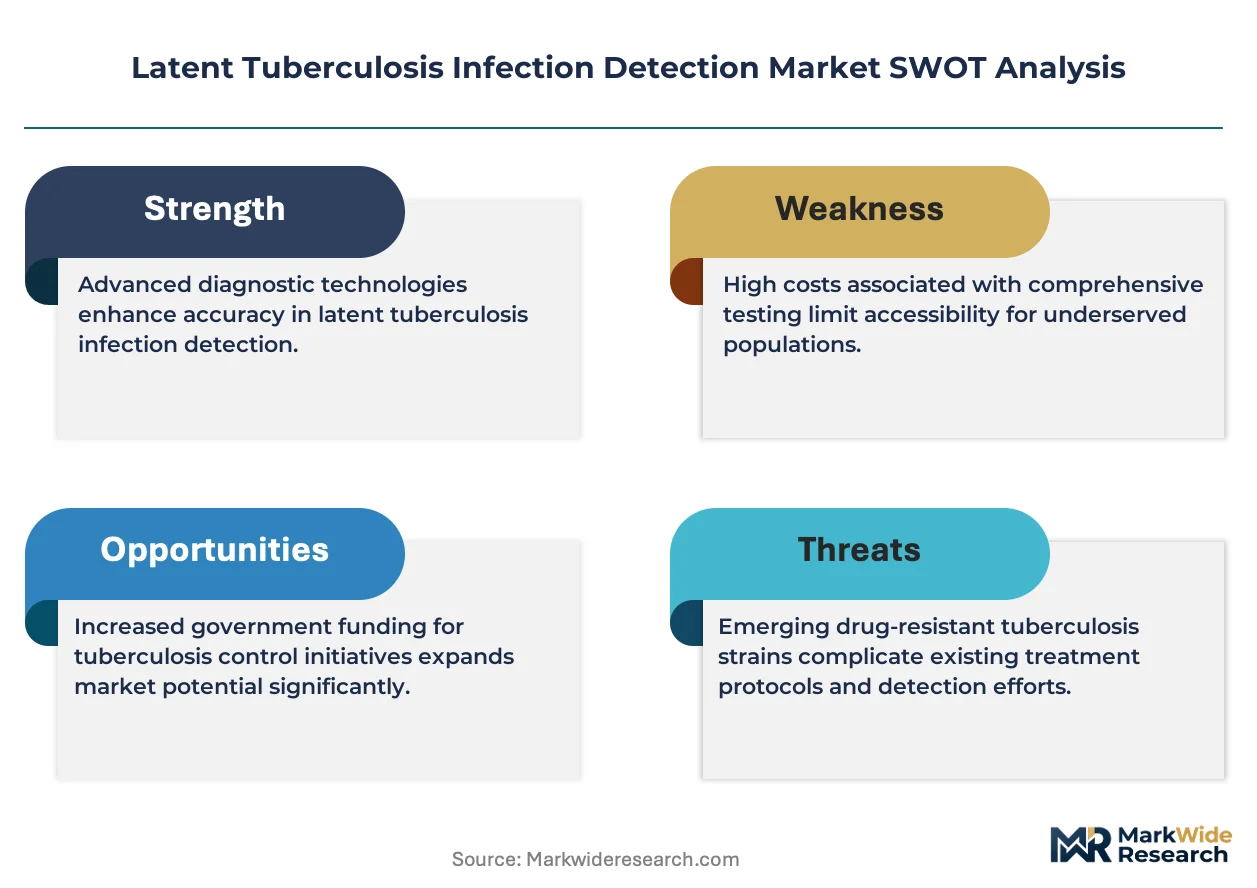
Recombinant antigen platforms are restructuring latent TB detection economics by displacing purified protein derivative with peptide-based formulations that eliminate cross-reactivity with BCG vaccination, compressing test interpretation timelines from days to hours.
Growth Catalysts
- Revised National Tuberculosis Control Program:India's centralized procurement mandates for Gene-Expert platforms and IGRA consumables create sustained volume commitments across public health infrastructure.
- ESAT-6 and CFP-10 antigens:These Mycobacterium tuberculosis-specific proteins enable interferon-gamma release assays to distinguish latent infection from BCG-induced immune response, expanding test utility in vaccinated populations.
- Immunocompromised screening protocols:HIV clinics and transplant centers deploy molecular diagnostics per WHO algorithm preferences, generating recurring demand for preventive therapy initiation workflows.
Market Restraints
- Platform concentration in high-income reference laboratories:Automated sample-to-answer systems require capital investment and cold-chain logistics that limit deployment in peripheral health facilities.
- Reagent import dependence:Peptide-based formulations and nucleic acid amplification chemistries rely on concentrated manufacturing in European and North American supply nodes, exposing procurement to currency volatility and shipping disruptions.
- Technician training requirements:Molecular diagnostics demand laboratory personnel with nucleic acid handling competencies that remain scarce in resource-limited settings with high TB burden.
Strategic Opportunities
- Point-of-care molecular platforms:Battery-operated cartridge-based systems can penetrate rural clinics in India and Indonesia where laboratory infrastructure is absent.
- Digital connectivity integration:Cloud-based result reporting to national TB registries enables real-time surveillance and treatment cascade monitoring.
- Prequalification pathway acceleration:WHO prequalification for simplified IGRA formats opens procurement channels across African national control programs.
Industry Challenges
- Quality management system certification:EMA In Vitro Diagnostic Medical Devices Regulation tightens clinical evidence requirements, extending European market entry timelines for emerging manufacturers.
- Sample-to-answer integration complexity:Automated platforms must interface with diverse laboratory information systems across hospital networks, requiring customized middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latent Tuberculosis Infection Detection Market |
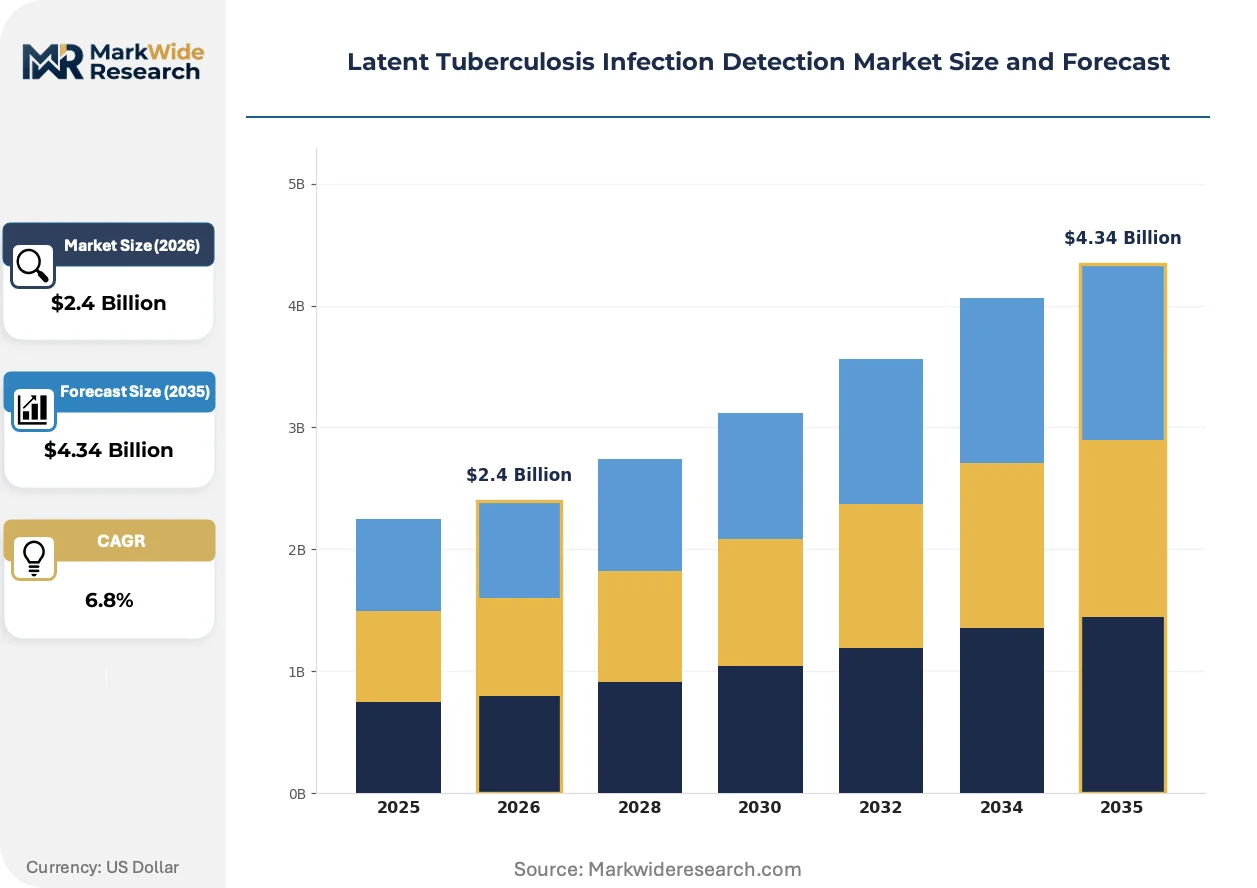
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Vivo Tests, In Vitro Tests, Ancillary Equipment, Diagnostic Kits End User: Hospitals, Clinics, Laboratories, Public Health Centers Technology: Interferon Gamma Release Assays, Tuberculin Skin Test, Molecular Diagnostics, Gene-Expert Application: Screening, Diagnosis, Monitoring, Research |
| Companies Covered | QIAGEN N.V., Revvity, Abbott Laboratories, SD Biosensor Inc., Thermo Fisher Scientific Inc., Oxford Immunotec Ltd., bioMérieux, F. Hoffmann-La Roche Ltd., PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latent Tuberculosis Infection Detection Market Strategic Shifts & Innovations
Peptide-based immunological detection and cartridge-based molecular platforms are converging to compress testing workflows from multi-day laboratory processes to same-day clinical decision-making at peripheral health facilities.
Multiplexed antigen panels are unifying ESAT-6, CFP-10, and TB7.7 epitopes into single-tube interferon-gamma release formats. European reference laboratories adopt these consolidated workflows to reduce technician hands-on time and plate handling errors. This unification is compressing per-test operational costs while maintaining diagnostic specificity against BCG cross-reactivity.
EMA In Vitro Diagnostic Medical Devices Regulation imposes stricter clinical performance documentation for CE marking of latent TB diagnostics. Manufacturers must generate prospective cohort data across immunocompromised and pediatric populations. Hospital laboratory procurement committees in Germany and France now prioritize vendors with completed MDR technical files, shifting competitive advantage toward established quality management systems.
Integrated service contracts are displacing reagent rental models in high-throughput screening environments. Public health programs in India and South Africa negotiate bundled pricing for platforms, consumables, and maintenance across multi-year procurement cycles. This consolidation is most visible in national TB control programs where volume commitments secure preferential per-test rates from diagnostics suppliers.
Latent Tuberculosis Infection Detection Market Segmentation
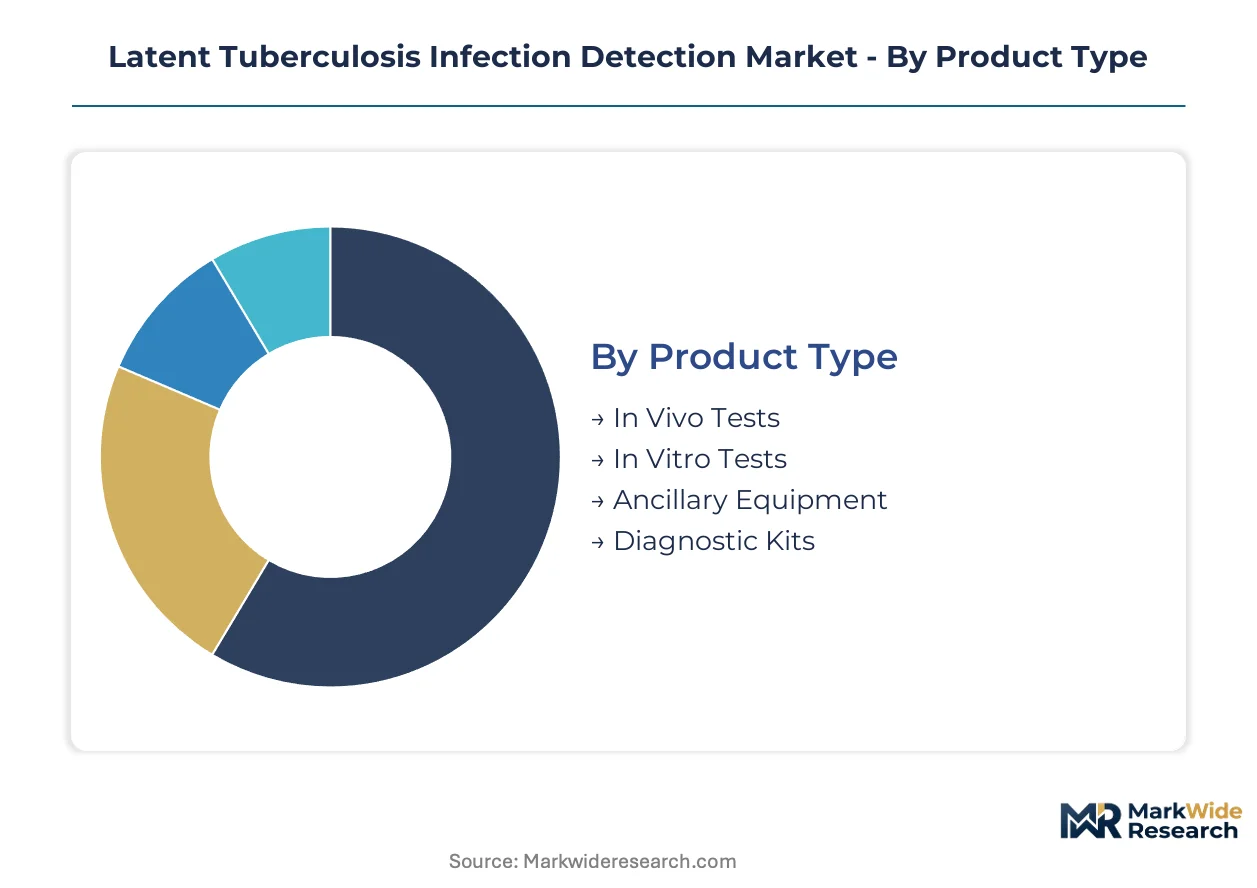
Latent TB detection markets fragment across immunological and molecular technology platforms, each commanding distinct procurement channels and margin structures. Understanding these segment boundaries clarifies where volume concentrates versus where pricing power accumulates.
Product Type:
Supply concentration in European and North American manufacturing nodes shapes availability and cost structures across product categories.
- In Vitro Tests:Interferon-gamma release assays and enzyme-linked immunospot platforms dominate revenue generation through higher per-test pricing and centralized laboratory processing. Demand clusters in European reference laboratories and Indian tertiary hospitals where bundled service contracts anchor procurement decisions.
- Diagnostic Kits:Peptide-based antigen formulations and nucleic acid amplification chemistries enable decentralized testing workflows. Procurement is accelerating in Indian district hospitals and Indonesian primary health centers where cold-chain logistics remain manageable.
- In Vivo Tests:Tuberculin skin tests utilizing purified protein derivative persist in resource-limited settings despite BCG cross-reactivity limitations.
- Ancillary Equipment:Automated incubators and plate readers support high-throughput screening environments in national reference laboratories.
In Vitro Tests absorb the bulk of installed capacity; Diagnostic Kits are expanding most quickly.
End User:
Customer type determines contract structure, with public procurement favoring volume commitments and private channels prioritizing margin preservation.
- Public Health Centers:National TB control programs in India, South Africa, and Indonesia drive sustained volume through centralized Gene-Expert platform deployment and IGRA consumable tenders. WHO prequalification requirements filter supplier eligibility, concentrating procurement among established manufacturers with quality management system certification.
- Hospitals:Tertiary care institutions in Germany, France, and the United States generate superior margins through integrated molecular diagnostics workflows and preventive therapy initiation protocols for immunocompromised patients. EMA In Vitro Diagnostic Medical Devices Regulation tightens clinical evidence requirements, extending procurement committee evaluation timelines.
- Laboratories:Reference and hospital-affiliated facilities process high-throughput screening volumes with automated sample-to-answer systems.
- Clinics:HIV clinics and transplant centers deploy point-of-care molecular platforms for same-day clinical decision-making.
Public Health Centers command the greatest test volumes; Hospitals capture the steepest margin expansion trajectory.
Technology:
Platform maturity and technical complexity create divergent deployment economics across health system tiers.
- Molecular Diagnostics:Nucleic acid amplification technologies detect Mycobacterium tuberculosis DNA with high analytical sensitivity, enabling same-day result reporting. India's Revised National Tuberculosis Control Program anchors global demand through centralized Gene-Expert platform procurement and cartridge volume commitments.
- Interferon Gamma Release Assays:ESAT-6 and CFP-10 antigen stimulation eliminates BCG cross-reactivity, expanding utility in vaccinated populations. European reference laboratories adopt multiplexed formats consolidating TB7.7 epitopes to reduce technician hands-on time and plate handling errors.
- Gene-Expert:Cartridge-based systems automate nucleic acid extraction and amplification for peripheral health facility deployment.
- Tuberculin Skin Test:Purified protein derivative injection persists where IGRA cost and cold-chain requirements prove prohibitive.
Molecular Diagnostics is gaining share fastest; Interferon Gamma Release Assays retain the largest installed base.
Application:
Use case determines test frequency and reimbursement pathway, with screening mandates generating recurring demand versus episodic diagnostic testing.
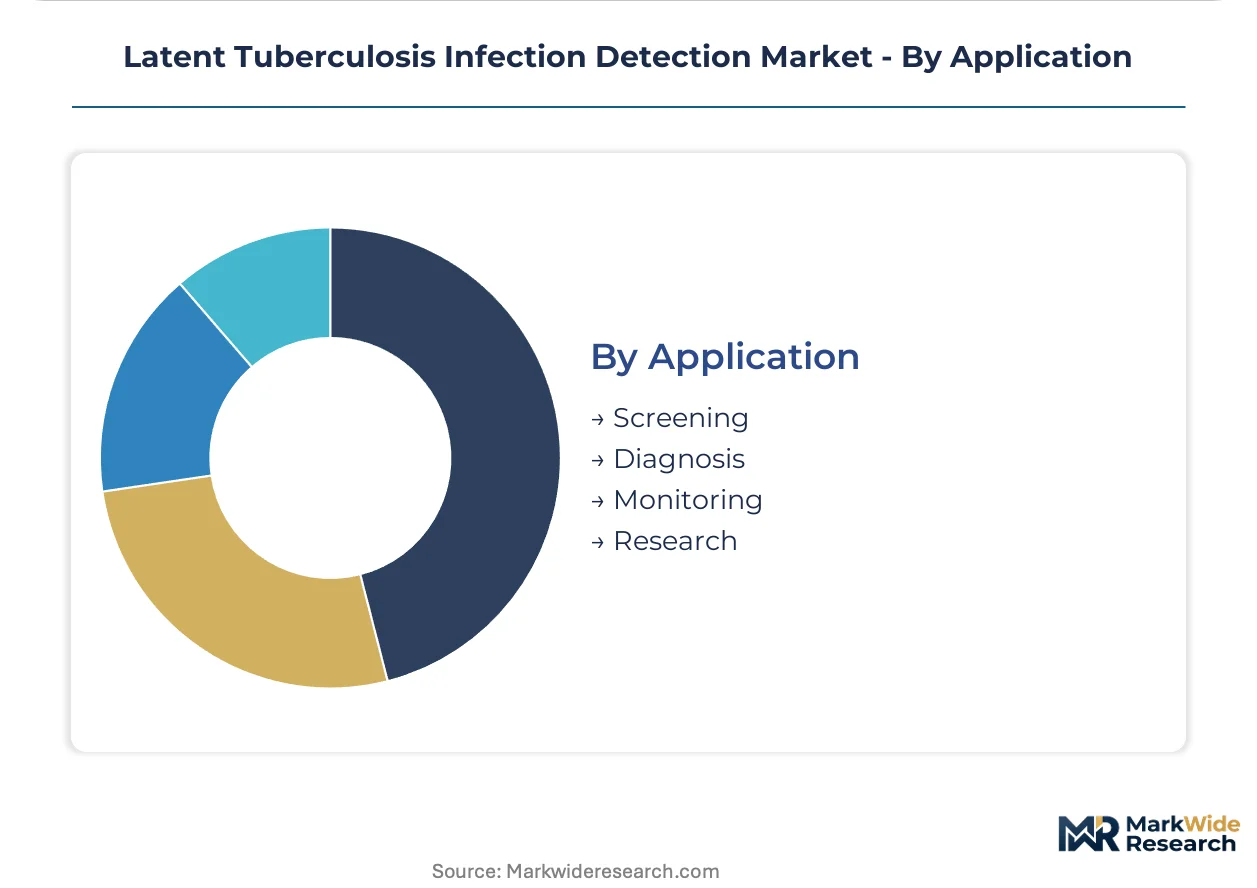
- Screening:Systematic testing of close contacts, healthcare workers, and immunocompromised populations drives recurring volume through national program mandates. India's district-level procurement of Gene-Expert platforms and IGRA consumables exemplifies screening-driven demand concentration.
- Diagnosis:Confirmatory testing for symptomatic patients with suspected latent infection supports hospital laboratory revenue through bundled molecular diagnostics workflows. EMA oversight through the In Vitro Diagnostic Medical Devices Regulation tightens clinical performance documentation requirements.
- Monitoring:Treatment response assessment for preventive therapy patients generates lower-frequency testing demand.
- Research:Clinical trial endpoints and epidemiological studies utilize specialized antigen panels and digital connectivity integration for registry reporting.
Screening absorbs the dominant share of test volume; Diagnosis commands the highest per-test pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones and biotechnology parks concentrate latent TB detection manufacturing and procurement decisions for emerging markets.
India
The Revised National Tuberculosis Control Program drives centralized procurement of Gene-Expert platforms and IGRA consumables across district hospitals. CDSCO regulates diagnostic kit manufacturing through mandatory quality audits and premarket approvals. Hyderabad and Bengaluru clusters host contract manufacturing facilities supplying peptide-based antigen formulations to African and Southeast Asian national control programs.
United States
Hospital laboratories and transplant centers generate recurring demand for molecular diagnostics workflows serving immunocompromised patient populations. FDA clearance governs market access and influences purchasing decisions across Latin American regulatory agencies. Boston and San Francisco metropolitan areas concentrate reference laboratory capacity for interferon-gamma release assay processing.
Germany
EMA oversight through the In Vitro Diagnostic Medical Devices Regulation tightens clinical evidence requirements for European market entry. The country's quality management system certification infrastructure favors established manufacturers with completed MDR technical files. Munich and Heidelberg industrial zones anchor automated sample-to-answer system development for high-throughput screening environments.
South Africa
National TB control programs deploy point-of-care molecular platforms in HIV clinics for same-day clinical decision-making. The country's national pharmaceutical regulator enforces WHO prequalification alignment for public procurement eligibility. Johannesburg and Cape Town metropolitan laboratories process screening volumes from mining industry occupational health mandates.
Indonesia
Primary health centers in Java and Sumatra accelerate procurement of diagnostic kits where cold-chain logistics remain manageable. The national control program integrates digital connectivity for cloud-based result reporting to TB registries. Jakarta's biomedical distribution hubs coordinate cartridge-based system deployment to peripheral health facilities lacking laboratory infrastructure.
Latent Tuberculosis Infection Detection Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with multinational diagnostics conglomerates commanding premium pricing in reference laboratories while regional assemblers penetrate price-sensitive public health programs. The vendor base concentrates among three strategic archetypes: platform-integrated systems suppliers, reagent-focused consumables specialists, and automated workflow enablers. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers seek WHO prequalification pathways and MDR technical file completion.
Among Netherlands-based diagnostics conglomerates, QIAGEN N.V. and Oxford Immunotec Ltd. occupy positions within the interferon-gamma release assay segment. Abbott Laboratories and bioMérieux exemplify platform-integrated systems suppliers, with the former representing broad geographic reach through hospital laboratory procurement anchoring and the latter sitting within automated sample-to-answer workflows. These three companies collectively represent the tier where bundled service contracts and quality management system certification determine competitive positioning.
| Leading Market Players |
|---|
| QIAGEN N.V. |
| Revvity |
| Abbott Laboratories |
| SD Biosensor Inc. |
| Thermo Fisher Scientific Inc. |
| Oxford Immunotec Ltd. |
| bioMérieux |
| F. Hoffmann-La Roche Ltd. |
| PerkinElmer Inc. |
| Others |
Cost & Logistics Intelligence
Skilled nucleic acid handling technicians in Indian biotechnology clusters compress labor-cost differentials into pricing-tier spreads that separate automated sample-to-answer systems from manual IGRA workflows. CDSCO quality audits and WHO prequalification requirements add compliance premiums that widen the gap between certified and uncertified diagnostic suppliers.
Pricing Analysis
Volume concentrates in public health centers while margins accumulate in hospital laboratories. Three-tier pricing structure across premium, standard, and economy levels reflects EMA MDR certification status, cold-chain logistics requirements, and bundled service contract scope. Cost compression in economy tiers intensifies because Indian national control programs negotiate multi-year cartridge volume commitments. Public procurement committees exhibit highest price sensitivity; transplant centers and reference laboratories demonstrate lowest sensitivity due to preventive therapy protocol mandates.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical special economic zones are reshaping sourcing patterns for peptide-based antigen formulations. Manufacturing concentrates in Germany, the United States, and India for automated platforms, nucleic acid amplification chemistries, and recombinant antigens respectively. Supply chains draw from European reagent suppliers, Asian electronics components, and Indian packaging materials. Single-source vulnerability in ESAT-6 and CFP-10 antigen production exposes procurement to shipping disruptions. Distribution runs through Jakarta's biomedical hubs for Southeast Asian peripheral health facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over recombinant antigen manufacturing determines margin capture against reagent-import-dependent competitors.
For Market Incumbents: Lock in long-term peptide supply agreements with Hyderabad and Bengaluru contract manufacturers to neutralize currency volatility exposure. Deepen backward integration into recombinant antigen production before emerging diagnostics assemblers secure captive supply. QIAGEN N.V. and Abbott Laboratories anchor positioning through existing WHO prequalification portfolios that new entrants cannot rapidly replicate. For New Entrants and Emerging Players: Begin with point-of-care molecular platforms for Indonesian primary health centers where laboratory infrastructure gaps exceed incumbent deployment capacity. Target HIV clinic networks in South African townships for same-day clinical decision-making workflows. Pursue digital connectivity integration as the go-to-market angle, offering cloud-based registry reporting that national control programs now mandate. For Investors and Strategic Acquirers: Re-rating potential sits with automated workflow enablers given EMA MDR technical file completion timelines that freeze out undercapitalized competitors. Five-to-ten year viability hinges on WHO prequalification pathway access and African national program procurement eligibility. Watch for WHO guideline revisions on test algorithm preferences as the inflection signal indicating platform technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Opens procurement channels across African national TB control programs requiring quality certification. |
| Automated Sample-to-Answer Development | Reduces technician hands-on time in Indian district hospitals processing high screening volumes. |
| Digital Connectivity Integration | Enables real-time cloud-based reporting to national TB registries for surveillance monitoring. |
| Recombinant Antigen Manufacturing Scale-Up | Displaces purified protein derivative economics with BCG-specific peptide formulations. |
| Point-of-Care Platform Miniaturization | Penetrates rural Indonesian clinics lacking cold-chain logistics and laboratory infrastructure. |
Research Approach
Document review covered WHO prequalification databases, CDSCO manufacturing audit records, and EMA MDR technical file registries, complemented by interviews with public health procurement officers, hospital laboratory directors, and diagnostics platform engineers. Secondary validation drew from national TB control program tender documents, Gene-Expert platform deployment reports, and interferon-gamma release assay clinical performance studies. Bottom-up test volume estimates triangulated against top-down market value reconstructions.
Segment-level projections across product type, end user, technology, and application dimensions fed into analytical framework calculations over the projection horizon. CAGRs derived from test volume growth trajectories in Indian district hospitals, European reference laboratory expansion, and Indonesian primary health center procurement acceleration. Modeled inputs included WHO guideline revision timelines, EMA MDR compliance cost curves, and cold-chain logistics penetration rates.
Underlying measurement precision varies by segment; molecular diagnostics and IGRA consumables carry tighter precision than tuberculin skin test persistence estimates. Forecasts incorporate assumptions regarding national screening mandate expansion, regulatory harmonization progress, and reagent import tariff stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Global Blood Culture Tests Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Sperm Count Test Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Global Companion Animal Diagnostics Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Multiplex Molecular Diagnostics Market