
 Rapid RNA Testing Kits Market | 2026-2036
Rapid RNA Testing Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid RNA Testing Kits Market Analytics
Modular assay cartridge formats is restructuring how hospital procurement teams evaluate RNA testing platforms against standalone instrument purchases. Thermo Fisher Scientific leverages its reagent-instrument bundling strategy to lock in multi-year laboratory contracts. QIAGEN competes through sample-to-answer automation that reduces technician touchpoints. Abbott Laboratories anchors its position in point-of-care settings with palm-sized devices that bypass central lab workflows.
Rapid RNA testing kits comprise pre-formulated reagent mixes, thermal cycling instruments, and disposable assay cartridges designed to detect and amplify ribonucleic acid sequences within 15-90 minutes, primarily serving infectious disease diagnosis, oncology profiling, and agricultural pathogen screening. The reagents segment captures recurring revenue through consumable pull-through tied to installed instrument bases, while point-of-care delivery modes are gaining fastest as decentralized health networks prioritize same-result clinical workflows. RT-PCR technology dominates current volume owing to regulatory familiarity, though CRISPR-based formats are attracting R&D investment for multiplexing capability.
The FDA's emergency use authorization framework and the EMA's in vitro diagnostic medical devices regulation shape product validation timelines and market entry pathways for manufacturers. ISO 13485 quality management standards and WHO prequalification programs further constrain supplier eligibility in publicly funded procurement channels. Stakeholders must monitor how decentralized testing reimbursement policies evolve against centralized laboratory economics.
Market Dynamics
Portable RNA detection platforms are compressing the traditional central-lab testing model, forcing procurement teams to rebalance capital expenditure between high-throughput instruments and distributed point-of-care devices. Thermo Fisher Scientific, QIAGEN, and Abbott Laboratories are restructuring contract terms around consumable pull-through rather than upfront instrument sales.
Growth Catalysts
- EMA In Vitro Diagnostic Medical Devices Regulation:The MDR framework is accelerating quality benchmarks across European reference labs, creating pull-through demand for pre-validated assay cartridges that reduce internal validation burdens.
- Infectious disease surveillance networks:Hospital systems in Germany and Japan are embedding rapid RNA workflows into emergency department triage protocols, shortening time-to-diagnosis for respiratory panels.
- CRISPR-based multiplexing:Next-generation detection chemistries are expanding test menus per cartridge, enabling oncology profiling from limited sample volumes without sequential testing runs.
Market Restraints
- Lyophilized reagent supply concentration:Three specialty chemical suppliers control polymerase enzyme production, exposing manufacturers to input cost volatility and batch-to-batch consistency risks.
- ISO 13485 certification timelines:Quality management system audits require 12-18 month validation cycles, freezing product iterations for mid-tier manufacturers lacking regulatory affairs scale.
- Antigen rapid tests:Lateral flow immunoassays compete for respiratory diagnostic budgets in low-acuity settings, pressuring RNA kit pricing in price-sensitive procurement channels.
Strategic Opportunities
- Agricultural pathogen screening:Veterinary diagnostic networks in Brazil and Australia are adopting portable RNA platforms for foot-and-mouth disease surveillance, opening non-clinical revenue streams.
- Reimbursement code expansion:CMS and private payors are evaluating separate payment tiers for point-of-care molecular testing, potentially unlocking margin expansion for decentralized delivery models.
- Cloud-connected instrument telemetry:Integration of real-time performance monitoring with laboratory information systems is enabling predictive maintenance contracts and consumable auto-replenishment.
Industry Challenges
- Multiplex assay design complexity:Cross-reactivity between target sequences demands specialized bioinformatics talent that concentrates in Boston and San Diego biotech clusters, inflating R&D salaries.
- Thermal cycler calibration drift:Field service networks must maintain temperature accuracy within 0.5°C across distributed device fleets, stretching technical support capacity in rural hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid RNA Testing Kits Market |
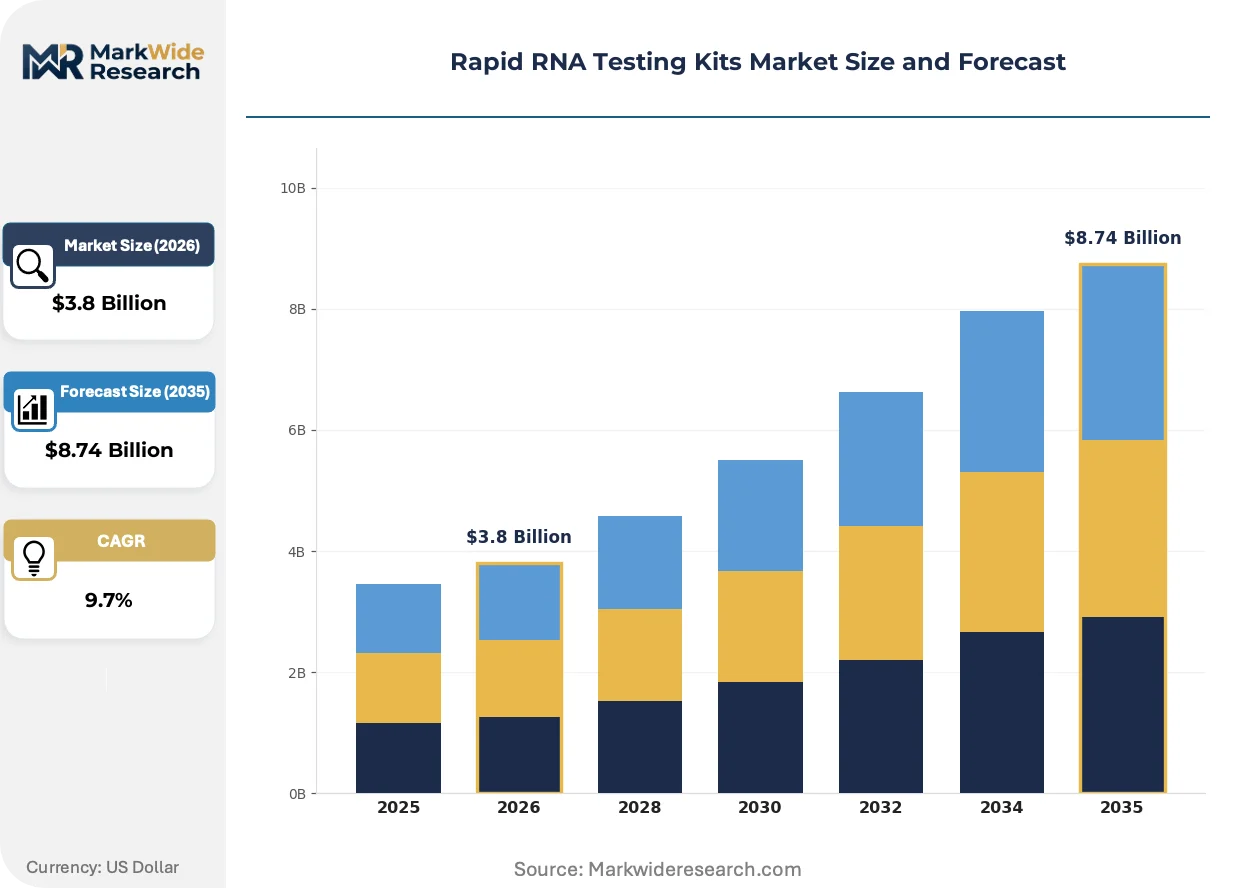
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Assay Kits, PCR Kits End User: Hospitals, Laboratories, Academic Institutions, Research Facilities Delivery Mode: Point-of-Care, Laboratory-Based, Home Use, Mobile Testing Technology: RT-PCR, LAMP, CRISPR, Microarray |
| Companies Covered | Thermo Fisher Scientific, Abbott Laboratories, Roche Diagnostics, Bio-Rad Laboratories, Quidel Corporation, QIAGEN, PerkinElmer, Illumina, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid RNA Testing Kits Market Evolving Landscape
CRISPR-Cas detection systems are compressing assay development timelines while expanding multiplexing capability beyond traditional RT-PCR constraints. Regulatory frameworks are adapting to accommodate these platform shifts without sacrificing analytical validation standards.
Loop-mediated isothermal amplification (LAMP) chemistry paired with smartphone-read fluorescence detection is decentralizing infectious disease diagnostics into pharmacy clinics and mobile health units. Community health centers in Kenya and India are piloting these workflows for tuberculosis screening. The technology is decentralizing specimen transport requirements and enabling same-day treatment initiation that central lab turnaround times previously prevented.
The FDA's emergency use authorization pathway has normalized accelerated nucleic acid test review timelines, compressing the traditional 510(k) submission cycle for novel detection platforms. European manufacturers are leveraging this precedent to negotiate parallel EMA scientific advice meetings. Point-of-care instrument developers face the steepest compliance burden as they must demonstrate analytical performance equivalent to laboratory-grade systems.
Hospital procurement committees are unbundling instrument-acquisition decisions from reagent-supply contracts, forcing vendors to compete on per-test economics rather than capital lease structures. Group purchasing organizations are consolidating negotiating power across multi-hospital systems in the United States. This behavior is most visible in Texas and Florida health networks where private equity-backed hospital rollups have centralized laboratory spend decisions.
Rapid RNA Testing Kits Market Segmentation
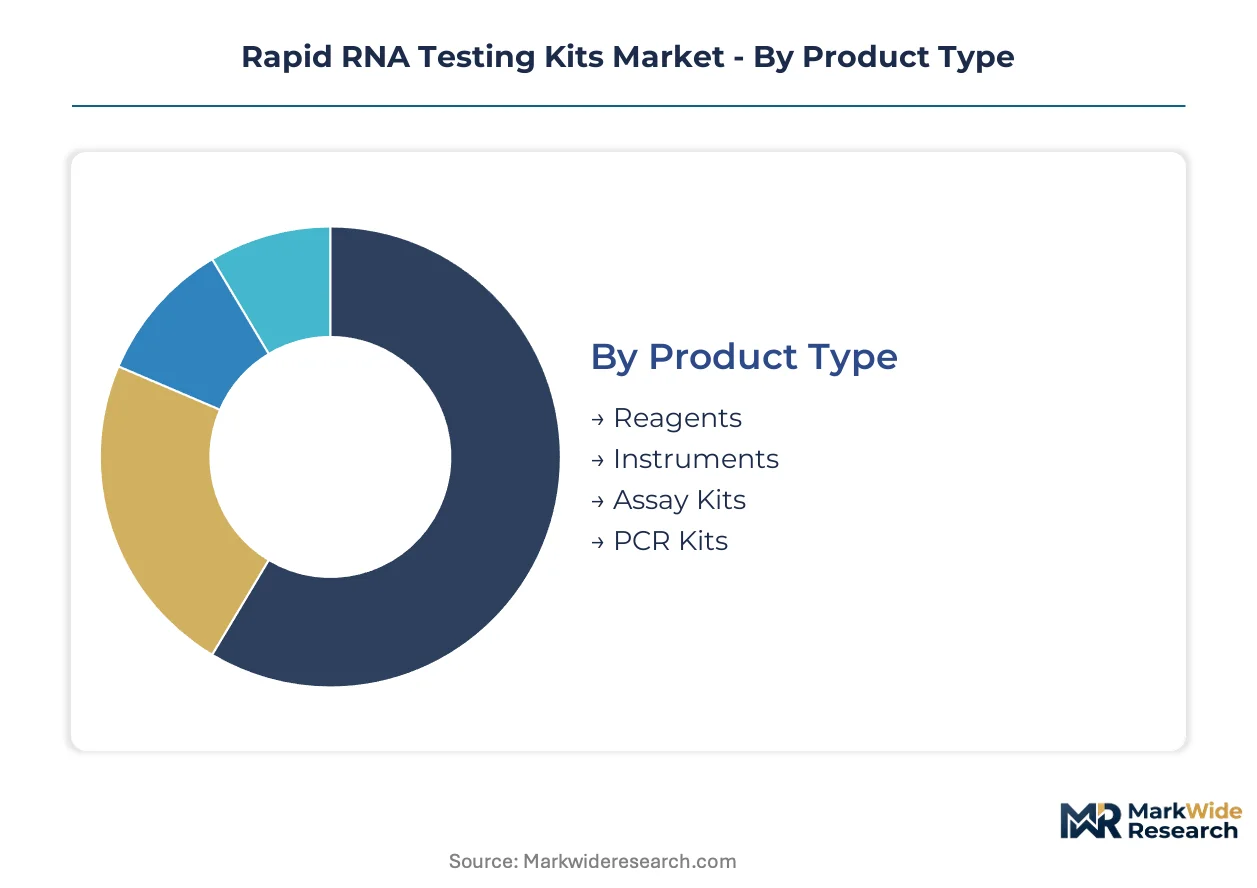
Procurement teams evaluate RNA testing platforms across four distinct dimensions that determine contract economics and operational integration. Each segmentation axis reveals divergent margin structures and regulatory compliance burdens that reshape vendor selection criteria.
Product Type:
Hospital procurement committees distinguish capital expenditure tolerance from recurring consumable budgets when evaluating these categories.
- Reagents:Pre-formulated polymerase master mixes, primers, and fluorescent probes generate pull-through revenue tied to installed instrument bases. Academic medical centers in the United States negotiate multi-year reagent supply agreements that lock in per-test pricing floors. Enzyme supply concentration among three specialty chemical manufacturers exposes buyers to batch consistency risks.
- Instruments:Thermal cyclers, real-time detection systems, and sample preparation workstations represent upfront capital outlays of $50,000-$500,000 depending on throughput capacity. German reference laboratories favor modular platforms that accommodate cartridge format upgrades without full instrument replacement.
- Assay Kits:Pre-validated pathogen-specific panels reduce internal validation burdens for mid-sized hospital networks. Japan's emergency department triage protocols specify respiratory and gastrointestinal panel configurations.
- PCR Kits:Complete workflow solutions bundling reagents, disposables, and quality control materials target laboratories without dedicated molecular biology expertise. Community hospital networks in Texas and Florida prioritize these integrated formats.
Reagents lead volumes today; instruments is gaining share fastest in point-of-care deployment models.
End User:
Testing volume per site and reimbursement pathway complexity create divergent customer lifetime values across these institutional types.
- Hospitals:Emergency departments and intensive care units demand sub-60-minute turnaround times that compress traditional central lab workflows. CMS reimbursement code evaluation for point-of-care molecular testing directly affects procurement committee willingness to decentralize.
- Laboratories:Reference labs and hospital-based core facilities prioritize batch throughput and LIS integration over speed. EMA MDR compliance requirements accelerate demand for pre-validated assay cartridges that reduce internal validation documentation.
- Academic Institutions:Research-use-only applications drive demand for customizable primer design and open-platform thermal cyclers. Funding agency requirements for data reproducibility constrain vendor selection to ISO 13485-certified suppliers.
- Research Facilities:Biotechnology companies and contract research organizations value assay development flexibility and technical support responsiveness. Boston and San Diego biotech clusters concentrate specialized bioinformatics talent that enables multiplex assay design.
Laboratories anchor current revenue; hospitals is expanding most quickly as decentralized testing reimbursement frameworks mature.
Delivery Mode:
Specimen transport requirements and result turnaround expectations determine where each format captures procurement budgets.
- Point-of-Care:Palm-sized devices bypass central lab infrastructure entirely, serving pharmacy clinics and urgent care centers. Abbott Laboratories anchors this segment with FDA-cleared platforms that demonstrate analytical equivalence to laboratory systems.
- Laboratory-Based:High-throughput batch processing maintains cost efficiency for screening programs and surveillance networks. Germany's infectious disease surveillance infrastructure embeds these workflows into statutory reporting obligations.
- Home Use:Self-collection kits with mail-back or smartphone-read components remain limited to research and wellness applications pending FDA clearance for diagnostic claims. Regulatory uncertainty constrains commercial investment.
- Mobile Testing:Vehicle-mounted or backpack-portable platforms enable field deployment for agricultural pathogen screening and outbreak response. Veterinary networks in Brazil and Australia pilot these configurations for foot-and-mouth disease surveillance.
Laboratory-based systems dominate procurement volumes today; point-of-care is climbing the fastest as health networks prioritize same-result clinical workflows.
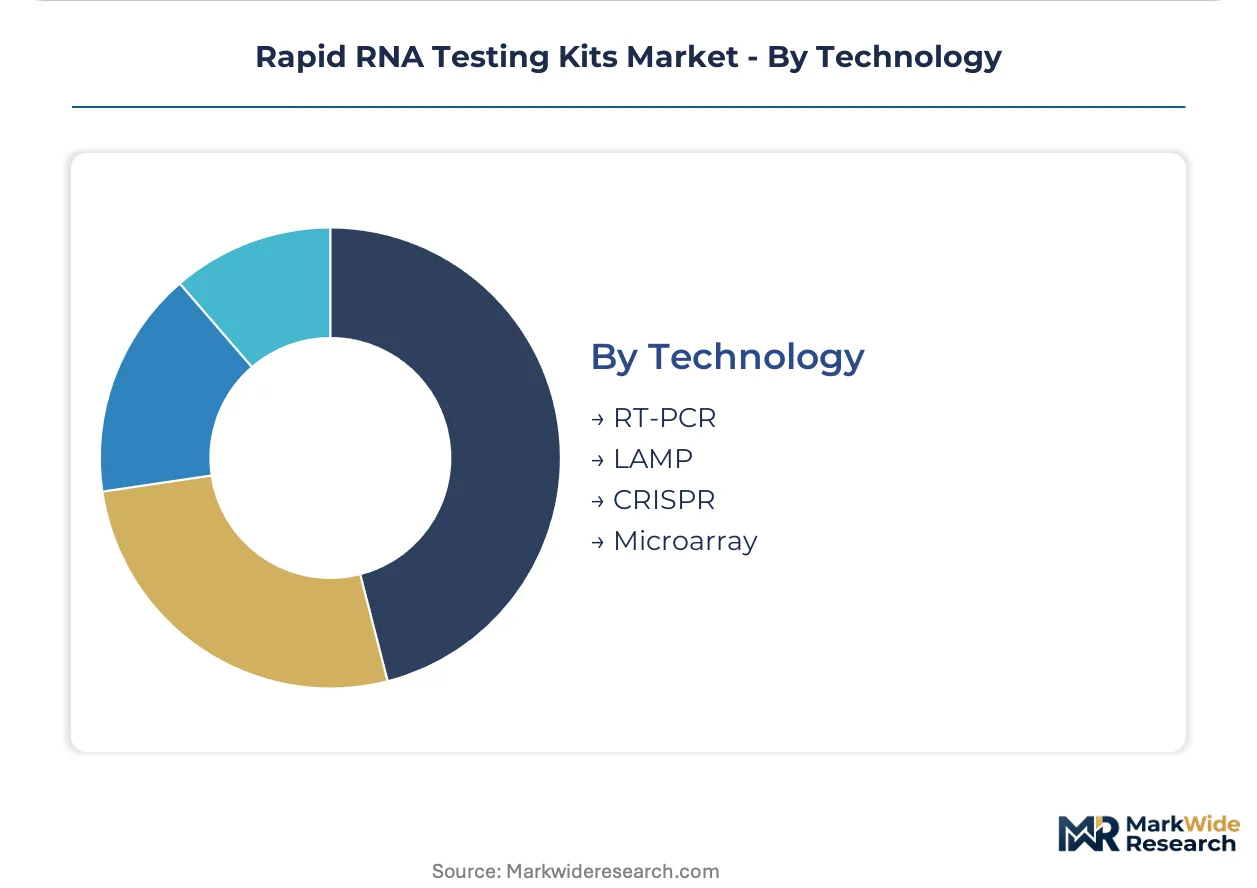
Technology:
Regulatory familiarity, multiplexing capability, and assay development timeline trade-offs differentiate platform selection.
- RT-PCR:Reverse transcription polymerase chain reaction remains the gold standard for quantitative RNA detection with established FDA 510(k) and EUA pathways. Thermo Fisher Scientific leverages its installed base to maintain reagent-instrument bundling contracts.
- LAMP:Loop-mediated isothermal amplification eliminates thermal cycling requirements, enabling simpler instrument designs and smartphone-read fluorescence detection. Community health pilots in Kenya and India deploy these workflows for tuberculosis screening without cold chain specimen transport.
- CRISPR:Cas-mediated detection systems compress assay development timelines while expanding multiplexing beyond traditional PCR constraints. R&D investment concentrates in oncology profiling applications where limited sample volumes demand simultaneous target detection.
- Microarray:High-density probe arrays enable transcriptome-wide expression profiling for research and oncology subtyping applications. Academic medical centers maintain these platforms for biomarker discovery despite higher per-sample costs.
RT-PCR leads installed base and regulatory clearance volume; CRISPR is gaining share fastest as multiplexing requirements intensify in precision oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rapid RNA testing industry traces its commercial scaling to the United States, where FDA emergency use authorization pathways established regulatory templates later adopted by European and Asian health authorities. Diagnostic platform development concentrated initially around Boston and San Diego biotech clusters before diffusing to German reference laboratories and Japanese hospital networks.
United States
Emergency department triage protocols in Texas and Florida health networks drive point-of-care molecular testing procurement. CMS reimbursement code evaluation for decentralized testing shapes hospital committee willingness to bypass central laboratory workflows. Boston and San Diego biotech clusters concentrate specialized bioinformatics talent enabling multiplex assay design for precision oncology applications.
Germany
Reference laboratories prioritize batch throughput and laboratory information system integration for infectious disease surveillance networks. EMA In Vitro Diagnostic Medical Devices Regulation accelerates demand for pre-validated assay cartridges that reduce internal validation documentation burdens. The Rhine-Ruhr metropolitan region anchors statutory reporting obligations embedding rapid RNA workflows into public health infrastructure.
Japan
Hospital networks maintain centralized procurement of respiratory and gastrointestinal panel configurations for emergency department protocols. PMDA regulatory frameworks shape product validation timelines for manufacturers seeking market entry. Tokyo and Osaka metropolitan areas concentrate diagnostic laboratory capacity serving aging population screening programs.
China
NMPA regulatory pathways increasingly accommodate nucleic acid testing formats following pandemic-era platform familiarization. Domestic manufacturers compete on per-test economics against established multinational reagent-instrument bundling contracts. The Yangtze River Delta biotech corridor attracts CRISPR-based detection chemistry research investment for oncology profiling applications.
Brazil
Veterinary diagnostic networks adopt portable RNA platforms for foot-and-mouth disease surveillance in agricultural regions. ANVISA regulatory requirements constrain supplier eligibility in publicly funded procurement channels. São Paulo state anchors pilot programs for mobile testing configurations enabling field deployment without cold chain specimen transport infrastructure.
Rapid RNA Testing Kits Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with captive reagent supply chains. Three to five multinational entities capture the majority of installed instrument bases through multi-year laboratory contracts. Strategic archetypes include reagent-instrument bundlers, sample-to-answer automation specialists, and point-of-care miniaturization leaders. Dominant competitive moves encompass consumable pull-through contract restructuring and predictive maintenance telemetry integration with laboratory information systems.
Among diversified life science conglomerates, Thermo Fisher Scientific and QIAGEN exemplify contrasting strategic archetypes within the same competitive space. Thermo Fisher Scientific occupies a position representing reagent-instrument bundling scale, while QIAGEN anchors the sample-to-answer automation tier reducing technician touchpoints. Abbott Laboratories sits within the point-of-care miniaturization archetype, representing palm-sized device formats that bypass central laboratory workflows entirely.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Roche Diagnostics |
| Bio-Rad Laboratories |
| Quidel Corporation |
| QIAGEN |
| PerkinElmer |
| Illumina |
| Danaher Corporation |
| Others |
Value Network & Pricing Analysis
Hospital procurement committee consolidation across Texas and Florida health networks is compressing per-test pricing negotiations and forcing reagent suppliers to absorb cost volatility from concentrated polymerase enzyme sources.
Pricing Analysis
Consumable pull-through contracts with multi-year reagent supply floors dominate hospital laboratory economics. Price differentiation rests on ISO 13485 certification tier and batch consistency guarantees from enzyme manufacturers. Cost compression in point-of-care cartridge tiers is intensifying because antigen rapid tests compete for respiratory diagnostic budgets. Community hospital networks exhibit highest price sensitivity; academic medical centers with captive validation capacity show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for thermal cycler field service networks. Manufacturing draws from three specialty chemical suppliers controlling polymerase enzyme production, plus precision temperature sensor foundries in South Korea and Japan. Single-source vulnerability for lyophilized reagent enzymes exposes batch-to-batch consistency risks. Distribution runs through group purchasing organizations consolidating multi-hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rapid RNA testing kits market compounds returns through regulatory milestone density, with FDA emergency use authorization precedents now accelerating EMA parallel review timelines for novel detection platforms.
For Market Incumbents: To counter CRISPR-based multiplexing entrants, Thermo Fisher Scientific and QIAGEN should deepen backward integration into polymerase enzyme supply and lock in multi-year reagent-instrument bundling contracts with German reference laboratories. Priority investment targets predictive maintenance telemetry integration with laboratory information systems. For New Entrants and Emerging Players: Capture agricultural pathogen screening white space in Brazil and Australia veterinary networks where ANVISA procurement channels remain underpenetrated by multinational reagent bundlers. Mobile testing configurations for foot-and-mouth disease surveillance offer lowest competitive density. Go-to-market should emphasize cold chain elimination value proposition. For Investors and Strategic Acquirers: Asymmetric upside sits with sample-to-answer automation specialists holding ISO 13485 certification and installed bases in Japanese hospital networks. Long-term viability hinges on reimbursement code expansion for point-of-care molecular testing across CMS and private payor frameworks. Watch for decentralized testing policy inflections as signal for margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Instrument Bundling Restructuring | Thermo Fisher Scientific locks multi-year laboratory contracts against CRISPR entrant pricing pressure. |
| Sample-to-Answer Automation Scale-Up | QIAGEN reduces technician touchpoints to defend margin position in German reference lab procurement. |
| Point-of-Care Miniaturization Investment | Abbott Laboratories anchors palm-sized device formats bypassing central laboratory workflows entirely. |
| Cloud-Connected Telemetry Integration | Predictive maintenance contracts enable consumable auto-replenishment with hospital information systems. |
| Agricultural Pathogen Screening Expansion | Veterinary networks in Brazil pilot mobile testing configurations for foot-and-mouth disease surveillance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, regulatory affairs leads at diagnostic manufacturers, and GPO contracts specialists with secondary validation against FDA 510(k) and EUA filing databases, EMA MDR submission records, hospital procurement contract disclosures, and CMS reimbursement code evaluation documents. Bottom-up instrument installation tracking and top-down reagent revenue estimates were triangulated for segment sizing.
Segment-weighting approaches modeled technology platform splits, delivery mode configurations, end-user institutional types, and regional regulatory cluster adoption patterns across the analysis window. CAGRs were derived from installed base expansion rates and consumable pull-through coefficients. Forecast inputs incorporated thermal cycler replacement cycles and point-of-care reimbursement policy evolution scenarios.
Regulatory timeline delays, enzyme supply batch failures, and antigen test pricing competition are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
RT-PCR Kits Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Home Diagnostics Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Global Predictive and Presymptomatic Testing Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Viral Antigens Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Global Molecular Diagnostics Services Market