
 Predictive Disease Analytics Market | 2026-2036
Predictive Disease Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Predictive Disease Analytics Market Analytics
Project finance and leasing arrangements for cloud infrastructure is rewriting competitive access in predictive disease analytics. Oracle leverages its vertically integrated cloud stack to anchor enterprise deployments across hospital systems. IBM sustains credibility through decades of healthcare data governance expertise and specialized Watson Health infrastructure. SAS competes on statistical depth, occupying a defensible niche among research institutions with complex modeling requirements.
Predictive disease analytics encompasses computational systems that ingest structured and unstructured clinical data—electronic health records, genomic sequences, imaging metadata, and real-time biometric streams—to generate probability-weighted forecasts of disease onset, progression, or treatment response, typically operating with prediction horizons ranging from hours to decades depending on clinical application. The primary commercial purpose centers on shifting healthcare delivery from reactive intervention to preemptive resource allocation and personalized therapeutic planning. Clinical Decision Support and Predictive Modeling Software command the largest installed bases, though Data Integration Platforms are capturing disproportionate investment growth as health systems confront interoperability mandates and fragmented EHR architectures. Among end users, pharmaceutical companies represent the fastest-growing adoption segment, driven by trial-enrichment and commercial-forecasting applications that demand longitudinal patient trajectory modeling.
The FDA's Software as a Medical Device framework and HIPAA security rule collectively shape product architecture, forcing vendors to embed audit trails, access controls, and model-explainability features into core platform design. ISO 13485 quality management standards and the 21 CFR Part 11 electronic records requirements further constrain market entry, privileging established players with compliance infrastructure over nascent competitors. Stakeholders must monitor how CMS reimbursement policy for AI-augmented diagnostics evolves, as payment parity decisions will determine whether hospital capital committees prioritize predictive analytics alongside traditional clinical IT spending.
Market Dynamics
The FDA's Software as a Medical Device framework is forcing predictive analytics vendors to rearchitect platforms around explainability and auditability, privileging incumbents with compliance infrastructure over new entrants lacking quality management systems.
Growth Catalysts
- CMS reimbursement policy evolution:Medicare's expanding coverage determinations for AI-augmented diagnostics are unlocking hospital capital committee budgets for enterprise analytics procurement.
- Pharmaceutical trial enrichment:Drug developers are deploying longitudinal patient trajectory modeling to identify biomarker-defined subpopulations, compressing enrollment timelines for precision therapy studies.
- Cloud infrastructure leasing:Project finance arrangements for compute resources are lowering barriers for mid-tier health systems to access enterprise-grade predictive platforms.
Market Restraints
- EHR interoperability fragmentation:Disparate data architectures across Cerner, Epic, and Meditech installations impose integration costs that consume 30-40% of implementation budgets.
- HIPAA security rule compliance:Encryption, access control, and breach notification mandates require dedicated infrastructure investments that strain smaller vendor balance sheets.
- Model validation timelines:FDA premarket review pathways for AI/ML-based SaMD extend commercialization cycles by 18-24 months versus traditional software.
Strategic Opportunities
- Rural health network penetration:Critical access hospitals in the United States remain underserved by predictive analytics, presenting white space for cloud-native, lower-touch deployment models.
- Real-world evidence integration:Convergence of claims data streams with clinical biometrics is enabling post-market surveillance applications that pharmaceutical sponsors will pay premium rates to access.
- EU AI Act compliance services:The risk-classification framework for high-risk AI systems creates advisory revenue streams for vendors positioning as compliance partners.
Industry Challenges
- Biostatistician talent scarcity:Health systems compete with technology firms and pharmaceutical sponsors for professionals capable of validating machine learning models against clinical endpoints.
- Legacy EHR integration complexity:On-premise installations from the 1990s lack API architectures, forcing expensive middleware development or data warehouse replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Predictive Disease Analytics Market |
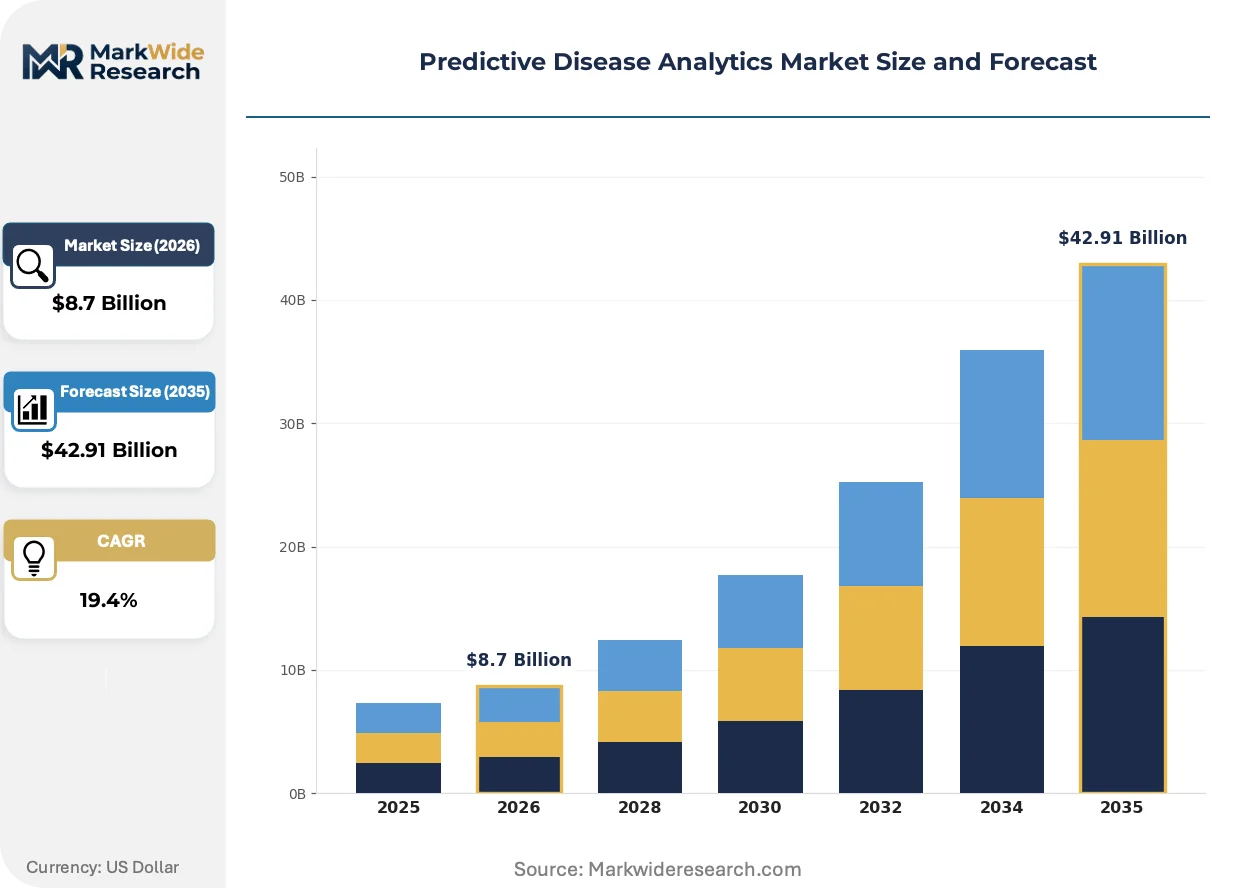
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Decision Support, Risk Assessment Tools, Predictive Modeling Software, Data Integration Platforms End User: Hospitals, Research Institutions, Healthcare Providers, Pharmaceutical Companies Technology: Machine Learning, Data Mining, Natural Language Processing, Cloud Computing Application: Patient Stratification, Health Monitoring, Disease Outbreak Prediction, Treatment Optimization |
| Companies Covered | Oracle, IBM, SAS, Cerner Corporation, Allscripts Healthcare Solutions Inc., Health Catalyst, MedeAnalytics, Inc., Apixio Inc, Optum, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Predictive Disease Analytics Market Evolving Landscape
Federated learning architectures and multimodal data fusion are reshaping how predictive models are trained and deployed, shifting competitive advantage from raw data volume toward governance sophistication and edge-computing capabilities.
Multimodal neural networks is hybridizing structured EHR extracts with unstructured clinical notes and imaging metadata into unified embedding spaces. Academic medical centers in the United States are piloting these systems for sepsis prediction, achieving lead times of 6-8 hours ahead of clinical deterioration. The approach is compressing the feature engineering bottleneck that previously consumed 60-70% of model development cycles.
The EU AI Act's risk-based classification system is mandating conformity assessments for predictive diagnostic tools deployed in European hospitals. Manufacturers must now document training data provenance, performance metrics across demographic subgroups, and human oversight protocols before CE marking. German and French notified bodies are developing specialized expertise, creating regulatory capacity constraints that favor larger vendors with dedicated compliance teams.
Hospital procurement committees are unbundling analytics software from traditional EHR vendor bundles, issuing standalone RFPs for best-of-breed predictive platforms. Integrated delivery networks in California and Texas are leading this shift, establishing data governance committees with independent technical evaluation authority. The pattern is most pronounced among systems that have completed cloud migration programs and possess modernized data lake architectures.
Predictive Disease Analytics Market Segmentation
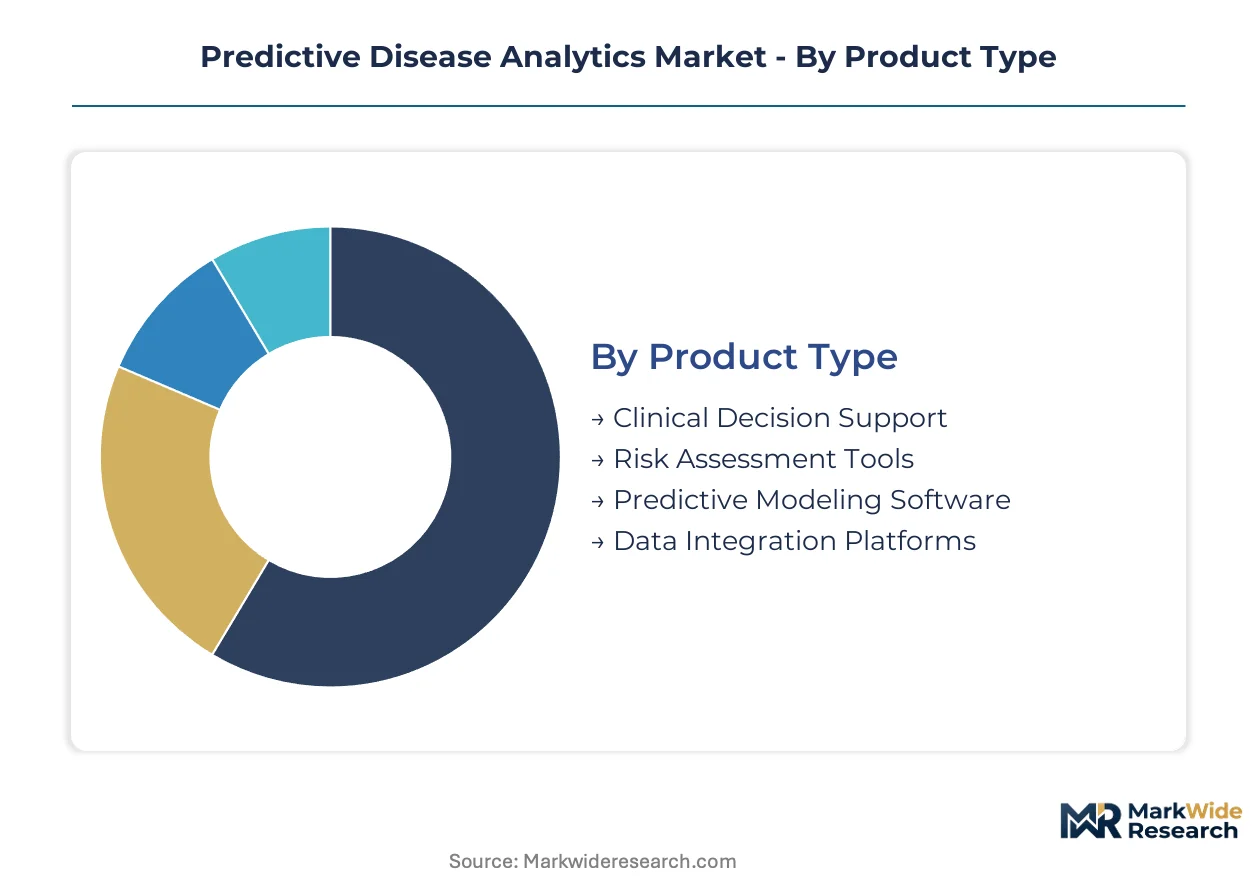
Predictive disease analytics vendors architect product portfolios around distinct deployment models and user workflows. Segmentation reveals where pricing power concentrates and which integration pathways command implementation priority.
Product Type:
After-sales service intensity varies sharply across product categories, with enterprise platforms demanding dedicated clinical informaticists while lightweight tools operate through self-service portals.
- Clinical Decision Support:Embedded algorithms that surface probability scores within EHR workflows, requiring continuous model retraining and alert calibration. United States integrated delivery networks prioritize these tools for sepsis and deterioration warnings, though alert fatigue management consumes substantial ongoing vendor support.
- Data Integration Platforms:Middleware architectures that normalize fragmented EHR, laboratory, and imaging data streams into queryable formats. Health systems in California and Texas are capturing disproportionate investment growth here as interoperability mandates harden and cloud data lakes mature.
- Risk Assessment Tools:Point solutions for readmission prediction and complication forecasting.
- Predictive Modeling Software:Standalone statistical environments for custom model development.
By volume, Clinical Decision Support leads. By growth pace, Data Integration Platforms are expanding most quickly.
End User:
Customer archetypes diverge in procurement sophistication, with pharmaceutical sponsors emphasizing longitudinal trajectory modeling while hospitals prioritize real-time intervention triggers.
- Pharmaceutical Companies:Trial-enrichment applications requiring decade-scale patient trajectory reconstruction and biomarker-defined subpopulation identification. These deployments compress enrollment timelines for precision therapy studies and command premium pricing for access to proprietary real-world data streams.
- Hospitals:Enterprise analytics procurement concentrated among large hospital systems with capital committee authority and cloud migration completion. Academic medical centers in the United States pilot multimodal neural networks for sepsis prediction, achieving lead times of 6-8 hours ahead of clinical deterioration.
- Research Institutions:Complex modeling requirements emphasizing statistical depth and methodological transparency.
- Healthcare Providers:Ambulatory and specialty clinic deployments with lighter integration footprints.
By revenue concentration, Hospitals dominate current procurement. By expansion trajectory, Pharmaceutical Companies are gaining share fastest.
Technology:
Technology selection determines infrastructure requirements, with cloud-native architectures lowering barriers for mid-tier health systems through project finance arrangements.
- Machine Learning:Supervised and unsupervised algorithms trained on structured clinical data, now shifting toward federated learning architectures that train models across distributed sites without centralizing protected health information. Academic medical centers are piloting these privacy-preserving approaches.
- Natural Language Processing:Extraction systems that transform unstructured clinical notes into structured features, compressing the feature engineering bottleneck that previously consumed 60-70% of model development cycles.
- Data Mining:Pattern discovery across historical claims and clinical datasets.
- Cloud Computing:Elastic compute resources enabling scalable inference without on-premise capital expenditure.
By deployment scale, Machine Learning leads. By capability advancement, Natural Language Processing shows the steepest improvement curve.
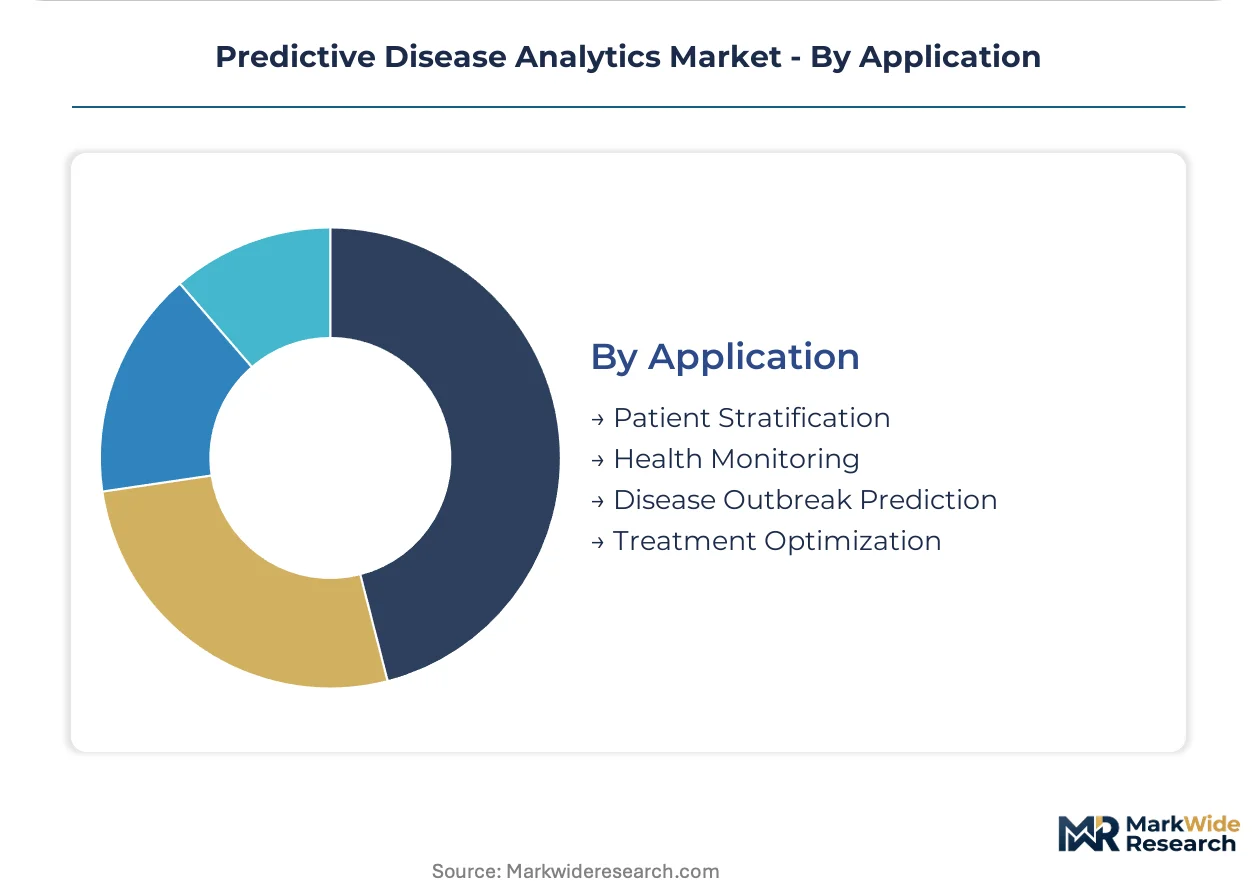
Application:
Application focus shapes regulatory exposure, with diagnostic prediction tools facing FDA Software as a Medical Device scrutiny while operational optimization sits outside premarket review pathways.
- Patient Stratification:Risk scoring systems that segment populations for care management resource allocation. United States health systems deploy these tools to identify high-cost beneficiaries for proactive outreach, with CMS reimbursement policy evolution determining budget priority alongside traditional clinical IT spending.
- Treatment Optimization:Response prediction models that guide therapeutic selection, requiring rigorous validation against clinical endpoints and facing extended FDA premarket review timelines of 18-24 months versus traditional software.
- Health Monitoring:Continuous biometric surveillance for early deterioration detection.
- Disease Outbreak Prediction:Population-level surveillance integrating syndromic data and environmental signals.
By installed base, Patient Stratification leads. By regulatory investment intensity, Treatment Optimization is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement policy evolution in the United States is unlocking hospital capital budgets for predictive analytics procurement, while the EU AI Act's risk-classification framework is mandating conformity assessments for European deployments.
United States
Integrated delivery networks in California and Texas command enterprise analytics procurement budgets, driven by cloud migration completion and independent data governance committees. The FDA's Software as a Medical Device framework forces vendors to embed audit trails and model-explainability features into platform design. Academic medical centers in Boston and the San Francisco Bay Area pilot multimodal neural networks for sepsis prediction, achieving 6-8 hour lead times ahead of clinical deterioration.
Germany
University hospitals in Munich and Heidelberg drive adoption of federated learning architectures that train models across distributed sites without centralizing protected health information. The EU AI Act mandates documented training data provenance and performance metrics across demographic subgroups before CE marking. German notified bodies are developing specialized regulatory expertise, creating capacity constraints that favor larger vendors with dedicated compliance teams.
United Kingdom
NHS integrated care systems in London and Manchester prioritize patient stratification tools for high-cost beneficiary identification and proactive care management outreach. NHS England's AI Award program provides funding and regulatory support for predictive diagnostic technologies entering national procurement frameworks. The Francis Crick Institute and Imperial College London anchor research partnerships with vendors seeking validation data for multimodal neural network development.
China
Top-tier hospitals in Beijing and Shanghai deploy machine learning platforms for treatment optimization and clinical decision support, supported by national health informatization initiatives. The NMPA's evolving guidance on AI-based medical device software shapes product approval pathways and local compliance investments. Shenzhen and Hangzhou technology clusters host domestic vendors developing edge-computing capabilities for real-time biometric surveillance applications.
India
Corporate hospital chains in Maharashtra and Karnataka pilot predictive modeling software for readmission reduction and complication forecasting in tier-1 metropolitan markets. The CDSCO's digital health regulations are gradually formalizing approval pathways for AI-augmented diagnostic tools. Hyderabad and Bangalore health technology clusters attract pharmaceutical sponsors seeking trial-enrichment partnerships and real-world evidence generation capabilities.
Predictive Disease Analytics Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated cloud infrastructure providers and specialized healthcare data governance platforms. Three strategic archetypes dominate: enterprise technology conglomerates with captive cloud stacks, statistical software specialists with decades of research institution relationships, and healthcare-native vendors with embedded EHR integration expertise. Dominant competitive moves include strategic partnerships with integrated delivery networks for data access and portfolio diversification into real-world evidence services for pharmaceutical sponsors.
Within the enterprise technology tier, Oracle leverages its vertically integrated cloud stack to anchor hospital system deployments, while IBM sustains credibility through specialized healthcare data governance infrastructure. SAS occupies a defensible position among research institutions with complex statistical modeling requirements. These three exemplify how compliance infrastructure and legacy healthcare relationships create barriers against newer entrants lacking quality management systems and FDA premarket review experience.
| Leading Market Players |
|---|
| Oracle |
| IBM |
| SAS |
| Cerner Corporation |
| Allscripts Healthcare Solutions Inc. |
| Health Catalyst |
| MedeAnalytics, Inc. |
| Apixio Inc |
| Optum, Inc. |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure concentration in the United States anchors margin capture for predictive disease analytics vendors, with hyperscaler leasing arrangements determining downstream pricing flexibility for hospital system deployments. Certification-grade differentiation and compliance infrastructure investments shape where value pools accumulate across the vendor landscape.
Pricing Analysis
Certification level creates the primary spread between enterprise and mid-market tiers, with FDA-grade platforms commanding premium positioning against lighter CE-marked alternatives. Subscription-based SaaS licensing dominates hospital procurement, though pharmaceutical sponsors increasingly negotiate value-based arrangements tied to trial-enrichment outcomes. Price differentiation rests on ISO 13485 quality management maturity and embedded audit-trail architecture. Cost compression in the mid-tier is intensifying as cloud-native entrants undercut legacy on-premise deployments. Critical access hospitals exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over license fees.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Oracle and IBM are reshaping vendor liquidity positions and customer acquisition economics. Compute hardware sourcing concentrates in the United States, Taiwan, and South Korea, with GPU availability constraining model training capacity for specialized clinical applications. Raw material dependencies span semiconductor substrates, encryption modules, and biometric sensor arrays. Single-source vulnerability in FDA-designated quality management system auditing creates regulatory chokepoints. Distribution runs through direct enterprise sales teams and strategic partnerships with GPOs and integrated delivery network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital capital expenditure cycles are recovering from post-pandemic compression, with CMS reimbursement policy evolution providing the cyclical impetus for predictive analytics procurement acceleration.
For Market Incumbents: Entrench compliance infrastructure advantages by accelerating FDA premarket submission pipelines for multimodal diagnostic tools before EU AI Act conformity assessments mature. Deepen backward integration into federated learning architectures to preempt cloud-native challengers lacking quality management systems. Defensive patent positioning around model-explainability algorithms will raise barriers against statistical software specialists encroaching on hospital system accounts.
For New Entrants and Emerging Players: Build out lightweight, cloud-native deployment models targeting critical access hospitals in rural Texas and California health networks, where incumbent footprint remains shallow. Rural health network penetration offers the most penetrable white space, with SaaS-based patient stratification tools requiring minimal EHR integration. A channel partnership strategy with regional health information exchanges accelerates trust-building without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward healthcare-native vendors with embedded Epic and Cerner integration expertise and established FDA premarket review track records. Long-term viability hinges on regulatory capacity rather than algorithmic novelty alone. Acquisition target archetype: mid-scale platforms with ISO 13485 certification and existing pharmaceutical sponsor relationships. The signal to watch is CMS national coverage determination velocity for AI-augmented diagnostic categories.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Accelerates hospital procurement cycles by satisfying capital committee risk thresholds. |
| Hospital System Partnership | Locks in data access for model retraining and creates switching costs against rivals. |
| CE Marking Pathway | Opens EU reimbursement channels ahead of AI Act conformity assessment bottlenecks. |
| Software Companion Development | Extends platform utility into pharmaceutical trial-enrichment and RWE generation. |
| Reimbursement Strategy | Aligns product positioning with CMS coverage determinations for AI-augmented diagnostics. |
Research Methodology
The analysis maps clinical decision support systems, data integration platforms, and predictive modeling software environments, each validated through hospital purchasing committees, biomedical informaticists, pharmaceutical development executives, and regulatory affairs specialists. Primary interviews with GPO contracts managers and cloud procurement officers combined with secondary validation against FDA 510(k) filings, CMS national coverage determinations, hospital procurement databases, and EHR vendor partnership disclosures. Bottom-up deployment sizing and top-down market aggregation triangulate volume estimates.
Assumptions held reimbursement policy evolution and FDA review timelines within observed trajectories, while cloud infrastructure pricing and biostatistician labor availability varied across sensitivity scenarios. Segmentation modeling spans product architecture, end-user procurement sophistication, deployment technology, and clinical application risk classification. CAGRs derive from logistic adoption curves fitted to health system cloud migration completion rates and pharmaceutical pipeline precision therapy ratios.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by hyperscalers into healthcare-native compliance services would shift outcomes. Macroeconomic contraction affecting hospital capital committees, regulatory deviation in FDA Software as a Medical Device guidance, or breakthrough federated learning standardization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
In-Vitro Diagnostics Enzymes Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Population Screening Market
Diagnostics
Netherlands in-Vitro Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market