
 Fructosamine Reagents Market | 2026-2036
Fructosamine Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Fructosamine Reagents Market Foresight
The capital-intensity divergence between automated platform suppliers and manual kit producers is collapsing as mid-scale diagnostic manufacturers achieve parity in reagent stability engineering. Randox Laboratories leverages integrated calibrator production across UK and Irish facilities to sustain margin control in colorimetric kit supply. DiaSys Diagnostic Systems GmbH anchors its European position through specialized enzymatic assay formulations for glycated protein quantification. Trinity Biotech plc competes in fluorometric assay segments where technical differentiation demands proprietary signal amplification chemistry.
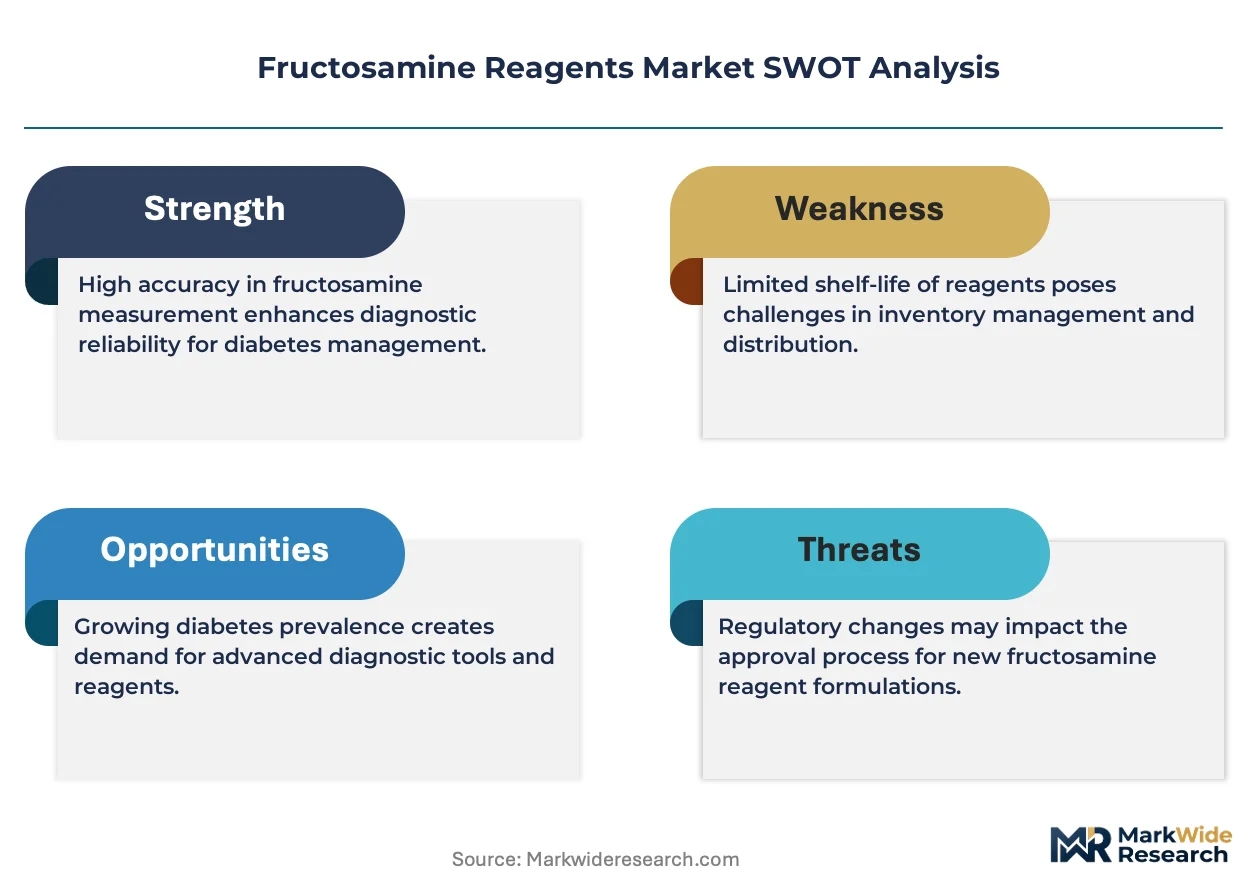
Fructosamine reagents measure glycated serum proteins—primarily albumin—through non-enzymatic glycation reactions that produce ketoamine structures detectable via colorimetric, enzymatic, or fluorometric methods; these reagents serve clinical diabetes monitoring by reflecting average blood glucose over two-to-three week windows, shorter than hemoglobin A1c and useful for gestational diabetes or hemoglobin variant conditions. Enzymatic assays command the largest installed base among product types due to standardization compatibility with high-throughput analyzers, while immunoassay kits represent the fastest-growing format as veterinary diagnostics and pharmaceutical stability testing expand. Clinical laboratories generate the dominant end-user demand, though research institutes are capturing growing volume from precision medicine glycation studies.
FDA clearance pathways for Class II in vitro diagnostic reagents shape product development timelines and predicate device selection for US market entrants, while CE marking under EU IVDR intensifies clinical evidence requirements for European commercialization. ISO 13485 quality management certification functions as a baseline procurement filter for hospital laboratory tenders across OECD markets. Stakeholders must monitor evolving glycation biomarker guidelines from diabetes associations and parallel regulatory convergence between FDA and EMA on companion diagnostic reagent classifications.
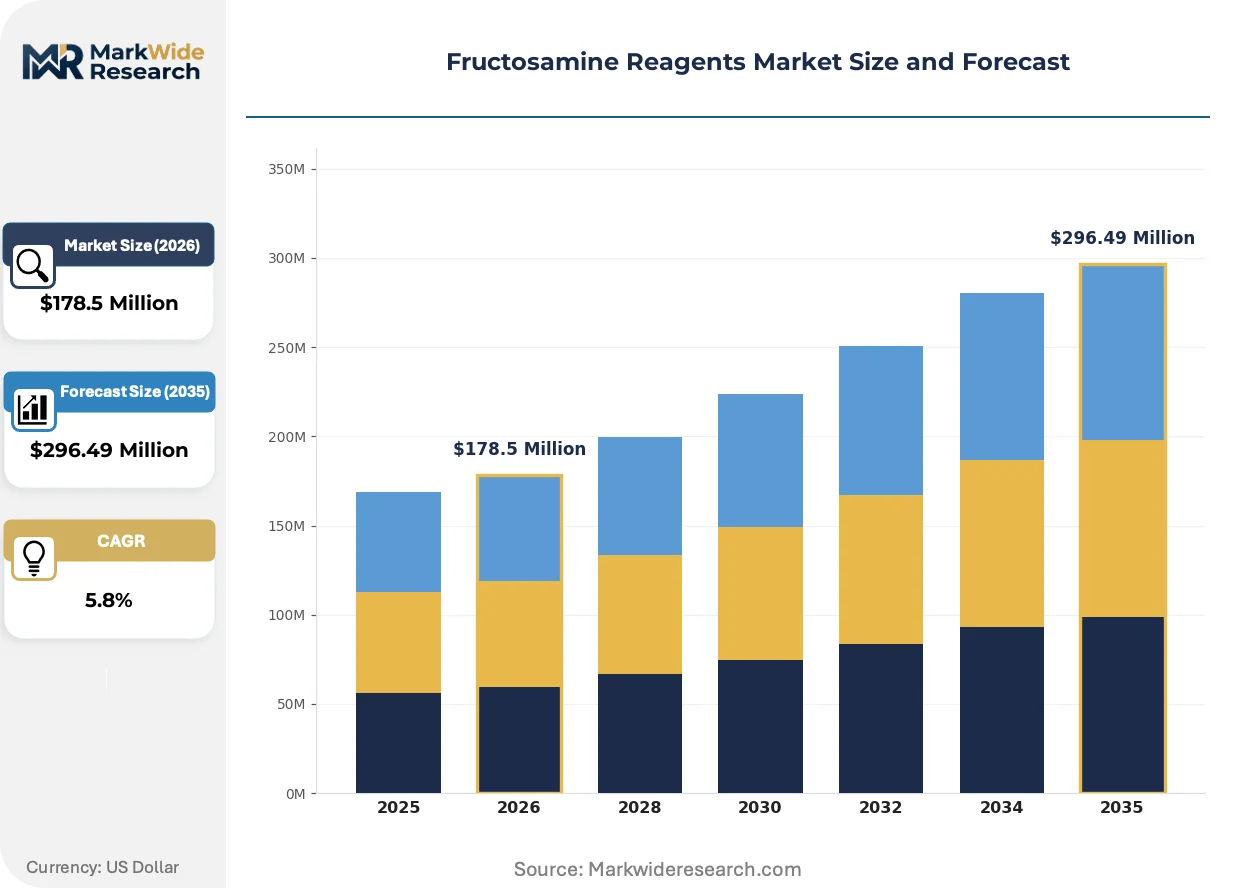
Market Dynamics
CMS reimbursement frameworks in the United States are pivoting toward value-based diabetes care, forcing clinical laboratories to consolidate glycemic monitoring assays onto high-throughput automated platforms while squeezing manual kit margins.
Growth Catalysts
- Enzymatic Assay Standardization:High-throughput analyzer compatibility pulls hospital networks toward unified reagent procurement, reducing protocol fragmentation across multi-site laboratory systems.
- EU IVDR Clinical Evidence Requirements:CE marking intensification under the 2017/746 regulation favors established manufacturers with robust quality management systems, filtering out marginal suppliers.
- Gestational Diabetes Screening Protocols:Hemoglobin variant interference limitations position fructosamine as the preferred intermediate glycation marker in obstetric populations.
Market Restraints
- Albumin Concentration Variability:Serum protein level fluctuations introduce measurement uncertainty that limits clinical confidence in certain patient populations.
- Hemoglobin A1c Substitution Pressure:Continuous glucose monitoring integration with A1c reporting compresses the addressable window for alternative glycation markers.
- Reagent Stability Engineering Costs:Lyophilization and cold-chain requirements for enzymatic formulations concentrate production among capital-intensive manufacturers.
Strategic Opportunities
- Veterinary Diagnostic Expansion:Companion animal diabetes management protocols in North American and Western European veterinary chains create parallel demand for species-validated assay kits.
- Pharmaceutical Stability Testing:Biologics manufacturers require glycated protein quantification for shelf-life validation, opening industrial contract research channels.
- Point-of-Care Format Development:Dry chemistry strip miniaturization for capillary blood sampling addresses clinic-based diabetes monitoring outside centralized laboratories.
Industry Challenges
- ISO 13485 Certification Timeline Compression:Hospital procurement tenders increasingly mandate current quality management certification, extending market entry lead times for new entrants.
- Legacy Analyzer Integration Complexity:Proprietary reagent protocols on installed chemistry analyzers create switching friction that locks laboratories into incumbent supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fructosamine Reagents Market |
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $296.49 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Assays, Colorimetric Kits, Immunoassay Kits, Fluorometric Assays, Electrochemical Sensors Application: Diabetes Monitoring, Glycemic Control, Research Laboratories, Veterinary Diagnostics, Pharmaceutical Testing End User: Clinical Laboratories, Diagnostic Centers, Research Institutes, Veterinary Clinics, Pharmaceutical Companies Distribution Channel: Direct Sales, Online Platforms, Distributors, Pharmacies, Medical Supply Stores |
| Companies Covered | Randox Laboratories Ltd, Sekisui Diagnostics, BioSystems S.A, Kamiya Biomedical Co, Sentinel Diagnostics, Asahi Kasei Pharma Corporation, DiaSys Diagnostic Systems GmbH, Trinity Biotech plc, EKF Diagnostics Holdings plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fructosamine Reagents Market Shifts & Advancements
Reagent format evolution and regulatory convergence are compressing product development cycles while fragmenting the competitive landscape between platform-integrated and standalone kit suppliers.
Enzymatic fructosamine quantification is bifurcating the installed base between high-throughput clinical chemistry analyzers and compact point-of-care devices. Hospital central laboratories in the United States and Germany are consolidating onto automated platforms with onboard calibration traceability, while primary care clinics in underserved regions adopt handheld fluorometric readers. This technology divergence is compressing margins for mid-scale manual kit producers while enabling premium pricing for integrated system suppliers.
CE marking under EU IVDR is intensifying clinical performance documentation requirements for glycated protein assays entering European markets. Manufacturers must now submit expanded analytical and clinical validation data to notified bodies, extending regulatory timelines by twelve to eighteen months. This policy shift most affects enzymatic assay suppliers seeking first-time market authorization, favoring incumbents with established post-market surveillance infrastructure.
Contracting patterns among United States hospital networks are consolidating reagent procurement through group purchasing organizations with multi-year exclusive agreements. Independent clinical laboratories and smaller health systems are losing negotiating leverage as purchasing volume concentrates among three dominant supply aggregators. This channel consolidation is most visible in the Southeast and Midwest regions, where hospital network mergers have compressed supplier rosters to two or three approved vendors per chemistry category.
Fructosamine Reagents Market Segmentation
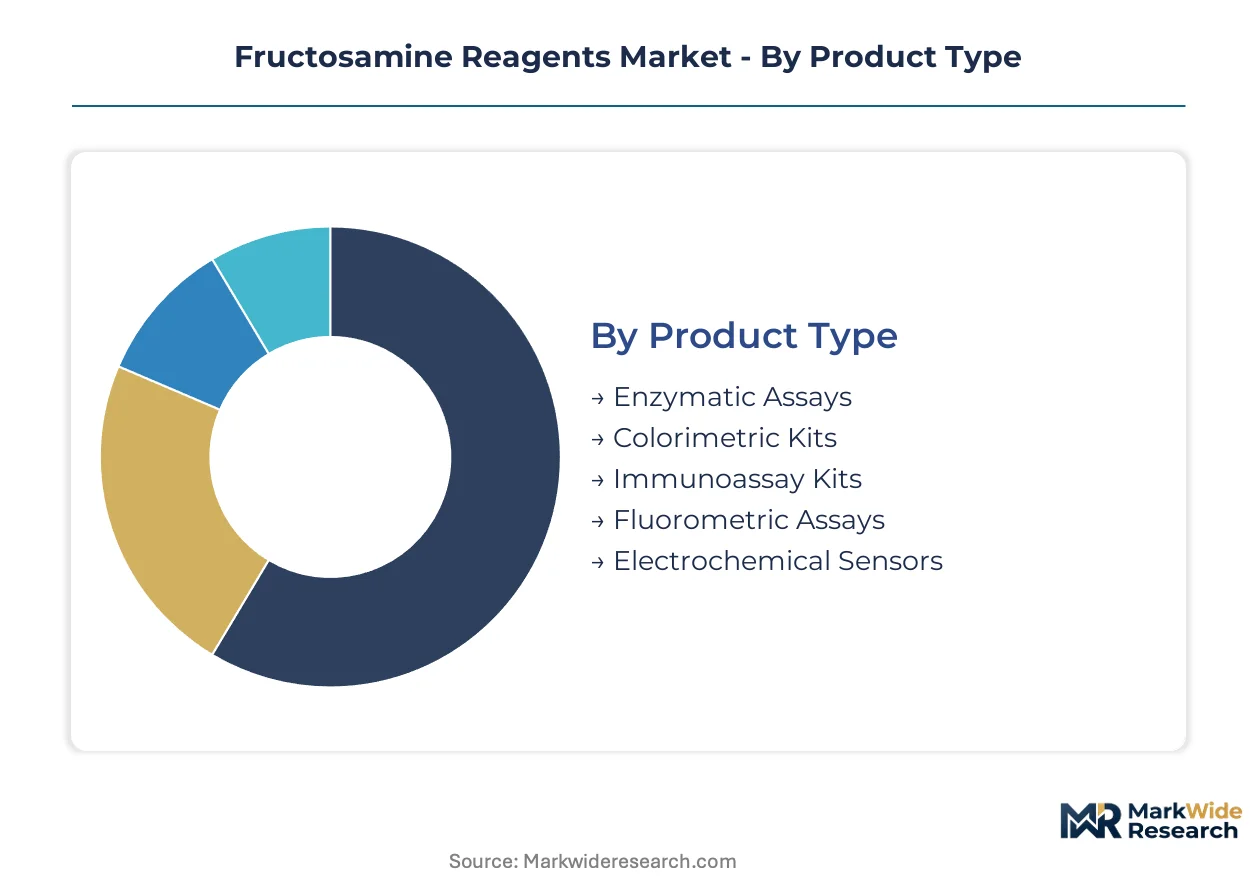
Fructosamine reagent manufacturers navigate distinct procurement pathways across hospital networks, research consortia, and veterinary chains. Channel selection directly shapes margin structures and technical support requirements for each segment cluster.
Product Type:
Hospital procurement teams route enzymatic and colorimetric formats through group purchasing organizations, while immunoassay and fluorometric kits flow more directly to specialized laboratories.
- Enzymatic Assays:These formulations rely on ketoamine oxidase enzymes to hydrolyze glycated protein bonds before colorimetric detection. United States hospital networks concentrate demand here as CMS reimbursement frameworks favor standardized high-throughput protocols. Legacy analyzer compatibility locks many laboratories into enzymatic workflows despite higher per-test costs.
- Colorimetric Kits:Nitroblue tetrazolium reduction chemistry produces measurable formazan dye proportional to fructosamine concentration. Mid-scale diagnostic centers in Germany and France favor these kits for manual batch processing where capital equipment constraints prevent full automation.
- Immunoassay Kits:Antibody-based detection systems offer species-specific quantification for veterinary and pharmaceutical applications.
- Fluorometric Assays:Proprietary signal amplification chemistry enables detection sensitivity below enzymatic thresholds.
- Electrochemical Sensors:Amperometric transducer miniaturization supports point-of-care format development.
By volume, enzymatic assays lead. By growth pace, immunoassay kits are expanding most quickly.
Application:
Cost tier differentiation separates premium clinical diagnostics from economy research-grade formulations, with veterinary and pharmaceutical applications occupying mid-tier pricing bands.
- Diabetes Monitoring:Clinical laboratories deploy fructosamine testing for gestational diabetes management and hemoglobin variant interference scenarios where A1c reliability degrades. Obstetric populations in United States academic medical centers generate concentrated demand for intermediate glycation markers.
- Glycemic Control:Endocrinology practices track short-term glucose trends in patients with rapid red blood cell turnover or recent transfusion history.
- Research Laboratories:Precision medicine glycation studies require assay flexibility over regulatory certification.
- Veterinary Diagnostics:Companion animal diabetes protocols in North American veterinary chains validate species-specific reference ranges.
- Pharmaceutical Testing:Biologics manufacturers quantify glycated protein stability for shelf-life validation under ICH guidelines.
Clinical applications dominate absolute volume. Pharmaceutical testing shows the steepest expansion trajectory as biologics pipelines mature.
End User:
Customer type determines service intensity, with clinical laboratories demanding comprehensive technical support while research institutes prioritize reagent flexibility.
- Clinical Laboratories:Hospital central laboratories in the United States and Germany consolidate procurement through multi-year exclusive agreements with approved vendor rosters. ISO 13485 certification functions as a baseline tender filter, extending market entry lead times for new suppliers.
- Diagnostic Centers:Independent laboratories lose negotiating leverage as purchasing volume concentrates among dominant supply aggregators.
- Research Institutes:Academic glycation biology groups source specialized formulations outside clinical regulatory pathways.
- Veterinary Clinics:Chain-affiliated practices in Western Europe adopt standardized protocols from human diagnostics.
- Pharmaceutical Companies:Contract research organizations integrate fructosamine quantification into stability study portfolios.
Clinical laboratories command the largest revenue pool. Research institutes are gaining share fastest in absolute volume terms.
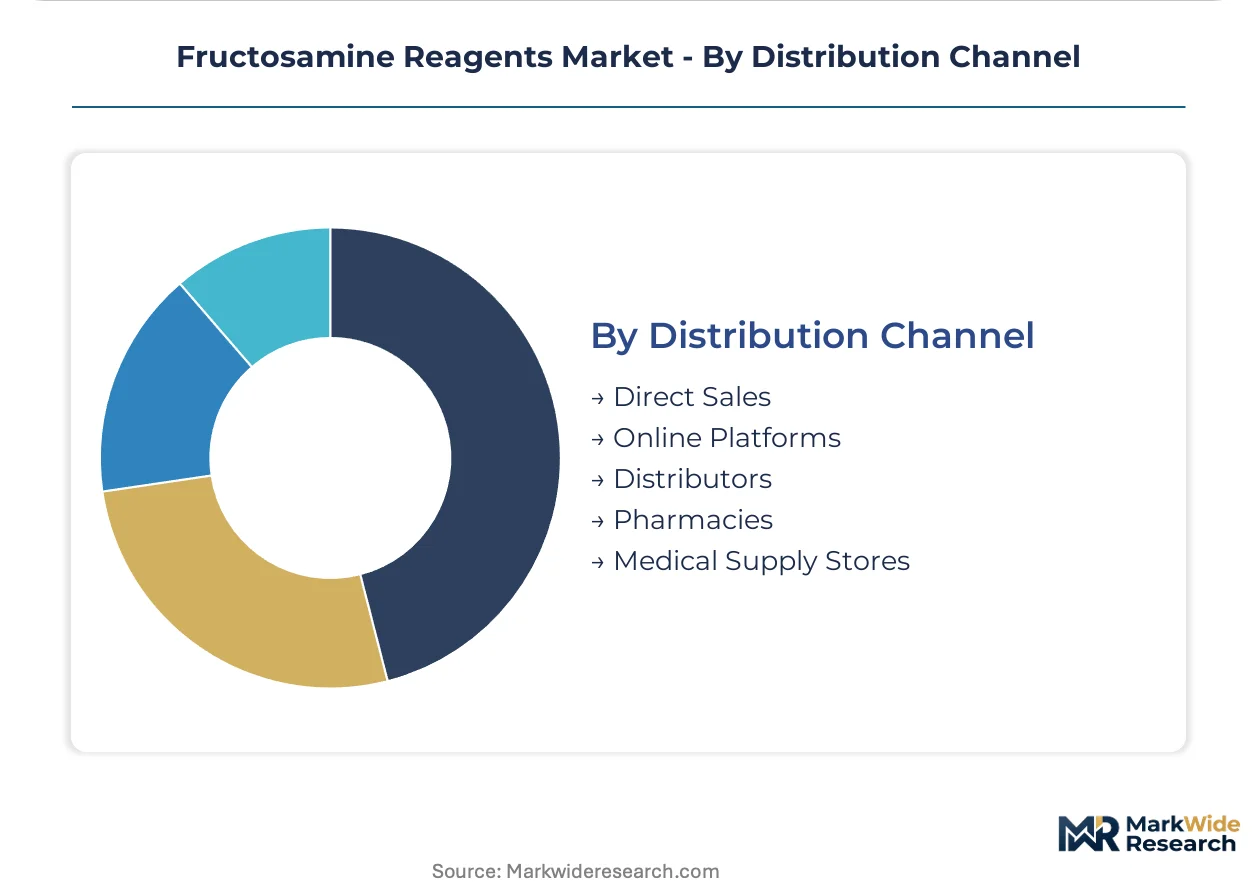
Distribution Channel:
Supply concentration favors direct manufacturer relationships for high-volume hospital networks, while fragmented channels serve smaller end users.
- Direct Sales:Field application scientists support instrument-integrated reagent contracts for automated platform users. United States hospital network mergers in the Southeast and Midwest regions have compressed supplier rosters to two or three approved vendors per chemistry category.
- Online Platforms:E-procurement portals enable price transparency for standard kit formats.
- Distributors:Regional medical supply houses maintain cold-chain infrastructure for temperature-sensitive enzymatic formulations.
- Pharmacies:Limited point-of-care strip availability in select European markets.
- Medical Supply Stores:Minimal fructosamine reagent penetration outside emergency veterinary settings.
Direct sales channels capture the highest value per transaction. Online platforms are climbing the fastest in transaction volume among non-clinical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks demonstrate the lowest price elasticity as CMS reimbursement frameworks consolidate procurement through group purchasing organizations, while German diagnostic centers exhibit higher sensitivity to per-test costs amid regional budget fragmentation.
United States
Academic medical centers in the Southeast and Midwest drive enzymatic assay demand for gestational diabetes protocols. FDA Class II clearance pathways shape product development timelines for market entrants. The Southeast hospital network corridor concentrates multi-site laboratory consolidation activity.
Germany
Mid-scale diagnostic centers favor colorimetric kit formats where capital equipment constraints prevent full automation. CE marking under EU IVDR intensifies clinical evidence requirements for notified body submissions. The North Rhine-Westphalia industrial cluster anchors reagent stability engineering capabilities.
United Kingdom
NHS laboratory networks prioritize ISO 13485-certified suppliers for centralized glycemic monitoring tenders. MHRA post-Brexit regulatory divergence from EMA creates parallel compliance pathways. Greater Manchester and Birmingham academic hospital trusts lead assay standardization initiatives.
Japan
PMDA approval timelines for in vitro diagnostic reagents compress market entry windows for foreign manufacturers. METI industrial standards for clinical chemistry analyzers drive interoperability requirements. The Kanto region around Tokyo concentrates hospital laboratory automation deployment.
France
ANSM oversight of companion diagnostics creates specialized pathways for glycated protein assay commercialization. Regional hospital groupings in Île-de-France negotiate consolidated reagent contracts through centralized purchasing platforms. Paris-area academic medical centers generate concentrated demand for intermediate glycation markers.
Fructosamine Reagents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with automated platform suppliers commanding premium positioning while manual kit producers compete on per-test economics. The vendor base spans three tiers: integrated system manufacturers with captive reagent supply, mid-scale diagnostic specialists with regional manufacturing footprints, and contract research suppliers serving pharmaceutical stability testing. Strategic moves concentrate on M&A for analyzer-reagent integration and geographic expansion through distributor partnerships.
Among European diagnostic specialists, DiaSys Diagnostic Systems GmbH and Randox Laboratories Ltd occupy positions within the mid-scale tier where integrated calibrator production sustains margin control. Trinity Biotech plc sits within the fluorometric assay segment where proprietary chemistry differentiation supports premium positioning. These three entities exemplify how regional manufacturing concentration and specialized formulation capabilities anchor competitive standing.
| Leading Market Players |
|---|
| Randox Laboratories Ltd |
| Sekisui Diagnostics |
| BioSystems S.A |
| Kamiya Biomedical Co |
| Sentinel Diagnostics |
| Asahi Kasei Pharma Corporation |
| DiaSys Diagnostic Systems GmbH |
| Trinity Biotech plc |
| EKF Diagnostics Holdings plc |
| Others |
Supply & Pricing Matrix
ISO 13485 certification gates both supplier qualification and price tier placement, forcing manufacturers to absorb audit and documentation costs that stratify the vendor base between certified premium providers and uncertified economy alternatives. This quality management filter concentrates procurement power among established players while compressing margins for aspirants seeking hospital laboratory entry.
Pricing Analysis
After-sales service contracts and multi-year calibrator supply agreements generate the dominant lifetime value for automated platform suppliers, not the initial reagent kit sale. Three-tier pricing structure across premium, standard, and economy levels separates instrument-integrated systems from manual batch kits and research-grade formulations. Pricing pressure stems from group purchasing organization consolidation in United States hospital networks, where exclusive vendor rosters limit competitive bidding. Independent diagnostic centers exhibit the highest price sensitivity, while academic medical centers prioritize assay standardization over per-test cost.
Supply Chain Analysis
Cold-chain logistics for enzyme formulations creates a chokepoint that concentrates production among manufacturers with lyophilization capabilities and validated temperature-controlled distribution. Supply concentrates in Germany, the United Kingdom, and the United States for finished reagent kits, while specialty enzymes and signal amplification chemistry draw from Japanese and Swiss suppliers. Single-source vulnerability runs through ketoamine oxidase enzyme production, where limited fermentation capacity creates bottleneck exposure. Distribution runs through direct manufacturer relationships for high-volume hospital networks and regional medical supply houses for mid-scale laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous glucose monitoring integration with hemoglobin A1c reporting threatens to compress the addressable window for fructosamine as an intermediate glycation marker, forcing incumbents to defend substitution risk through clinical protocol entrenchment.
For Market Incumbents: Secure exclusive multi-year reagent contracts with Southeast and Midwest hospital networks before group purchasing organization consolidation completes vendor roster compression. Deepen backward integration into calibrator production to sustain margin control against mid-scale competitors. FDA Class II clearance maintenance and EU IVDR clinical evidence dossiers function as defensive moats against fast-follower entrants seeking hospital laboratory access. For New Entrants and Emerging Players: Veterinary diagnostic service layers represent an under-served channel where species-specific assay validation and companion animal diabetes protocol development create white-space opportunity. Target Western European veterinary chains adopting standardized protocols from human diagnostics. Pharmaceutical stability testing contracts offer a second penetrable entry point, with biologics manufacturers requiring glycated protein quantification for ICH guideline compliance. For Investors and Strategic Acquirers: EU IVDR implementation reshapes the acquisition landscape by extending regulatory timelines twelve to eighteen months for enzymatic assay suppliers lacking post-market surveillance infrastructure. Five-to-ten year viability hinges on capturing platform-integrated positioning rather than standalone kit supply. Vertically integrated mid-scale specialists with captive calibrator production anchor the preferred acquisition archetype. The signal to monitor is CMS reimbursement framework evolution toward bundled diabetes care payments, which would accelerate high-throughput platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Completion | EU IVDR clinical evidence requirements filter marginal suppliers from European commercialization. |
| Hospital System Partnership | Exclusive reagent contracts with Southeast and Midwest networks lock in multi-year revenue streams. |
| Backward Integration into Calibrators | In-house production of reference materials sustains margin control against kit-only competitors. |
| Veterinary Diagnostic Expansion | Species-specific assay validation opens parallel demand outside saturated human clinical channels. |
| Point-of-Care Format Development | Dry chemistry strip miniaturization addresses clinic-based monitoring outside centralized laboratories. |
Research Methodology
Initial hypotheses were tested against primary input from clinical laboratory directors, diagnostic procurement managers, regulatory affairs specialists, and veterinary chain medical officers and refined through secondary validation across FDA 510(k) filings, EMA notified body guidance documents, CMS reimbursement databases, and ISO certification registries. Bottom-up demand modeling from hospital network reagent procurement volumes triangulated against top-down market sizing from manufacturer production disclosures.
Variance decomposition across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Modeled inputs included enzymatic assay installed base expansion rates, EU IVDR regulatory timeline compression effects, and group purchasing organization vendor roster consolidation patterns.
Forecasts assume regulatory continuity in FDA Class II clearance pathways and EU IVDR notified body operations; material policy shifts would require re-modeling of market entry timelines and competitive positioning. Practitioners should keep alternative scenarios live as CMS value-based diabetes care reimbursement frameworks and continuous glucose monitoring substitution threats evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Europe Molecular Diagnostics Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Global Sepsis Diagnostics Market
Diagnostics
Lipid Panel Test Market