
 France in-Vitro Diagnostics Market | 2026-2036
France in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
France in-Vitro Diagnostics Market Foresight
CE-IVDR certification upgrades are redrawing competitive barriers for multinational suppliers entering France. bioMérieux leverages its Lyon-based manufacturing footprint to sustain domestic reagent supply security. Roche Diagnostics anchors high-throughput immunoassay demand through installed base expansion across AP-HP hospital networks. Abbott Laboratories differentiates via point-of-care connectivity platforms that integrate with France's DMP electronic health record infrastructure.
In-vitro diagnostics encompasses analytical testing performed on biological specimens outside the living organism, utilizing reagent-based biochemical reactions with sensitivity thresholds typically ranging from picogram to nanogram detection limits to identify disease markers, pathogen presence, or metabolic states for clinical decision support. Molecular diagnostics and immunoassay technologies command the deepest margin pools due to proprietary reagent lock-in and recurring consumable revenue models. Clinical chemistry maintains volume leadership across public hospital laboratories but faces pricing pressure from centralized procurement frameworks, while hematology instrumentation renewal cycles are lengthening as facilities prioritize capital allocation toward molecular platforms.
ANSM enforces CE-IVDR conformity assessment pathways that mandate expanded clinical performance data for higher-risk device classes, directly elevating regulatory compliance costs for market participants. France's HAS evaluation criteria for diagnostic innovation reimbursement create parallel hurdles that filter commercial access before public funding commitment. Stakeholders must monitor evolving LPPR nomenclature revisions and regional ARS tender specifications to anticipate reimbursement and procurement trajectory shifts.
Market Dynamics
ANSM's CE-IVDR implementation is compressing certification timelines while elevating clinical evidence requirements, forcing manufacturers to restructure regulatory affairs functions and accelerate post-market surveillance infrastructure investment.
Growth Catalysts
- LPPR nomenclature expansion:France's HAS is broadening reimbursement codes for companion diagnostics, unlocking public funding for precision oncology testing across AP-HP networks.
- Molecular platform automation:Île-de-France hospital laboratories are deploying integrated sample-to-answer systems that consolidate previously fragmented testing workflows.
- Regional ARS procurement centralization:Consolidated tender frameworks are standardizing instrument specifications, reducing vendor fragmentation in public sector purchasing.
Market Restraints
- CE-IVDR conformity assessment costs:ANSM's expanded clinical performance requirements for Class C and D devices are elevating regulatory compliance expenditures disproportionately for mid-scale manufacturers.
- Reagent supply concentration:Domestic production of critical diagnostic enzymes remains concentrated within a narrow supplier base, exposing testing continuity to single-source vulnerabilities.
- Capital allocation competition:Hospital laboratories face extended hematology instrumentation renewal cycles as budgets pivot toward molecular diagnostics infrastructure.
Strategic Opportunities
- DMP electronic health record integration:Point-of-care platforms that interface directly with France's national health data infrastructure command premium positioning in regional tenders.
- Decentralized testing networks:Community pharmacy and primary care expansion of rapid diagnostic capabilities addresses geographic access gaps in rural Auvergne-Rhône-Alpes and Occitanie regions.
- AI-assisted pathology algorithms:Convergence of digital imaging and machine learning classification is creating new service revenue streams for academic medical center laboratories.
Industry Challenges
- Clinical bioinformatics specialization gap:Shortages of trained personnel capable of interpreting complex genomic variant data are constraining molecular diagnostics throughput expansion.
- Legacy LIS integration complexity:Hospital information systems require costly middleware development to accommodate next-generation instrument connectivity standards.
- Post-market surveillance resource intensity:ANSM's strengthened vigilance reporting mandates demand dedicated pharmacovigilance infrastructure that many market entrants lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France in-Vitro Diagnostics Market |
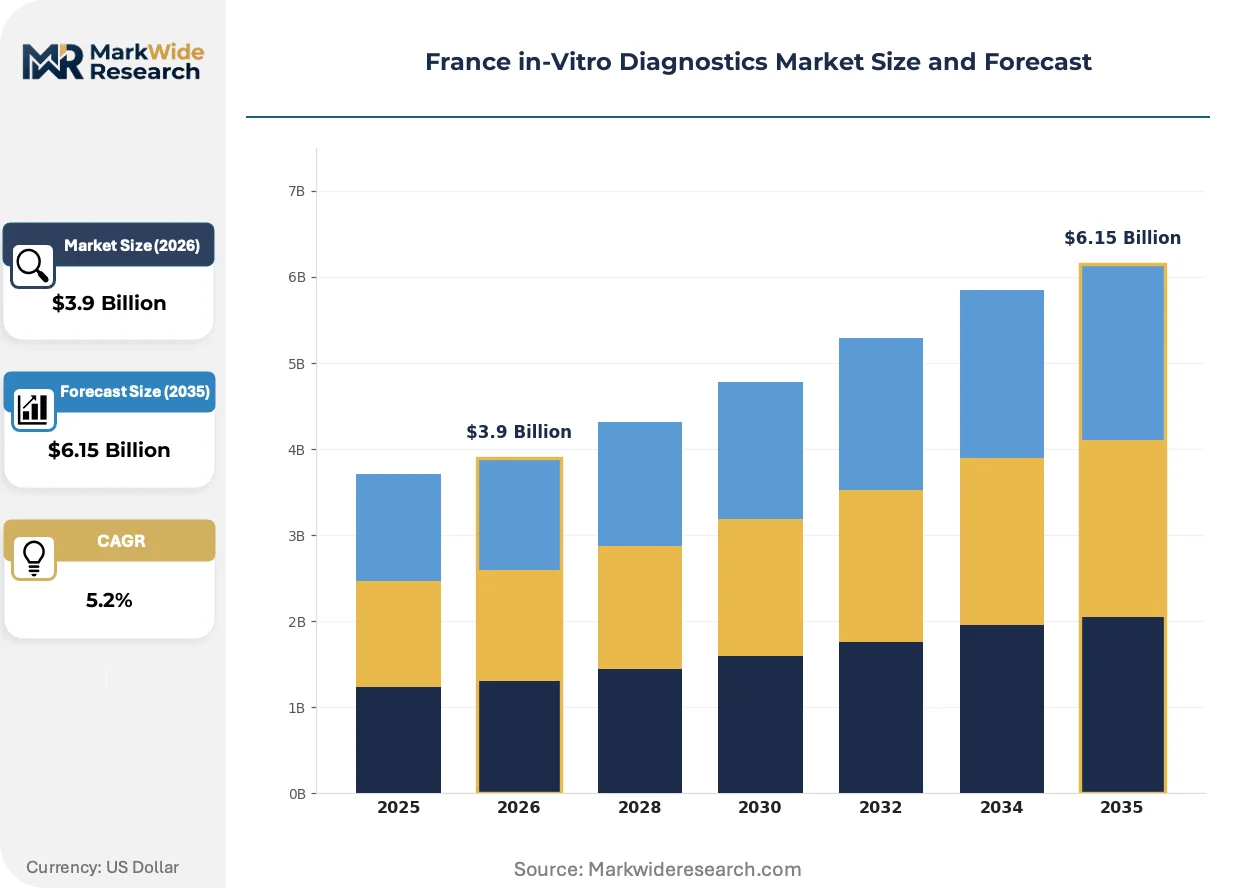
| Market Size in 2026 | $3.9 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents & Kits, Instruments, Software & Services, Consumables Technology: Immunoassay, Molecular Diagnostics, Clinical Chemistry, Hematology, Microbiology Application: Infectious Diseases, Oncology, Cardiology, Neurology, Endocrinology, Genetic Testing End User: Diagnostic Laboratories, Research Institutes, Physician Offices, Independent Testing Facilities |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, bioMérieux, Danaher Corporation, Becton, Dickinson and Company, QIAGEN, Sysmex Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France in-Vitro Diagnostics Market Shifts & Advancements
Automation architectures and regulatory data requirements are restructuring competitive advantage sources, while procurement consolidation and connectivity standards reshape how diagnostic value reaches clinical decision-makers.
Next-generation sequencing workflows are fragmenting the traditional centralized laboratory model by enabling distributed testing nodes with equivalent analytical performance. Regional hospital networks in Provence-Alpes-Côte d'Azur are piloting federated sequencing platforms that preserve sample proximity while maintaining quality uniformity. This topology is compressing logistics costs and turnaround times for time-critical oncology panels.
ANSM's alignment with MDR/IVDR transition timelines is elevating quality management system rigor across the domestic supplier base. Manufacturers must now maintain systematic post-market clinical follow-up registries that track real-world diagnostic accuracy. Higher-risk device categories face disproportionate documentation burdens, filtering market participation toward entities with established regulatory affairs scale.
Consolidated procurement through regional ARS frameworks is displacing hospital-level purchasing autonomy with standardized technical specifications and volume commitments. Multi-year reagent supply agreements now dominate AP-HP and HCL network tenders, locking in vendor relationships across extended contractual horizons. This concentration is most visible in immunoassay and clinical chemistry segments where platform switching costs deter competitive displacement.
France in-Vitro Diagnostics Market Segmentation
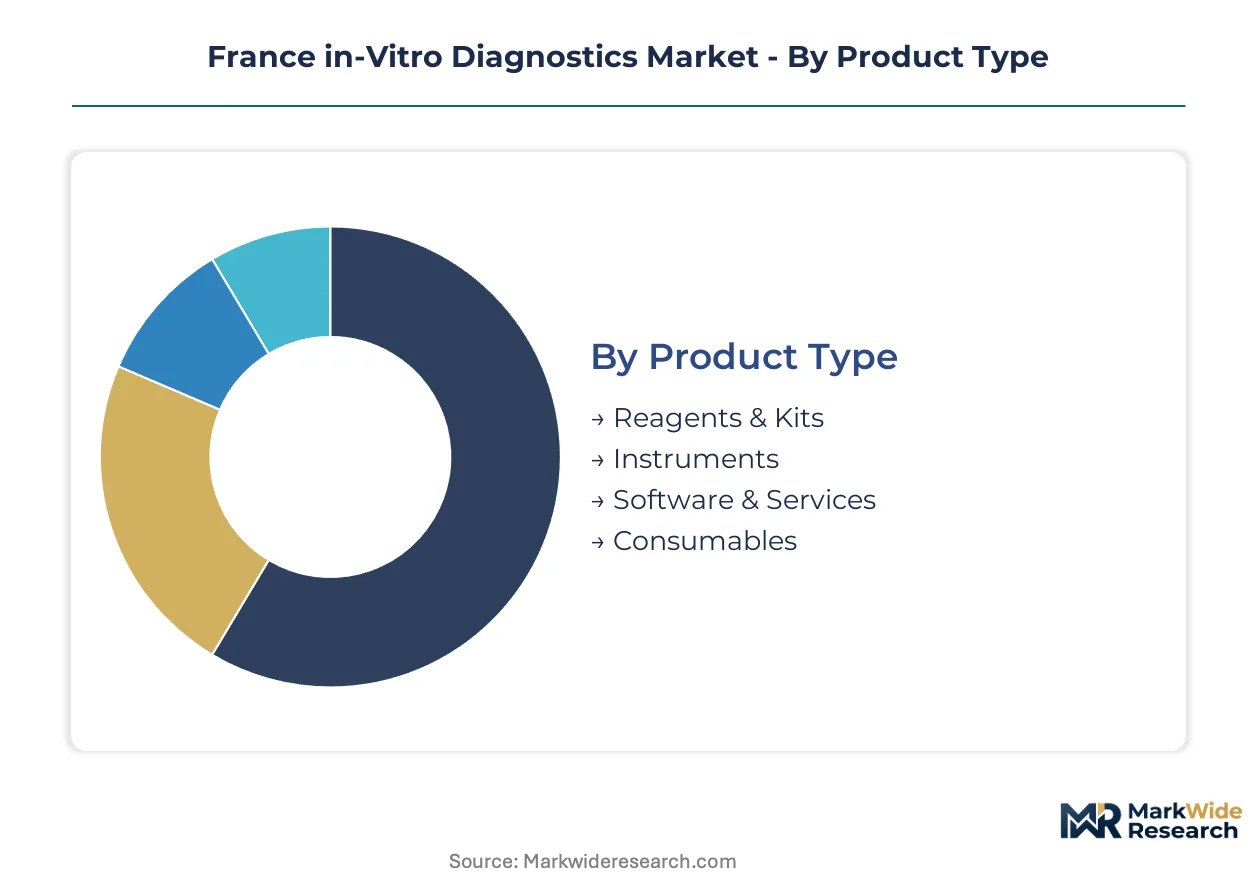
Segmentation in France's in-vitro diagnostics market reveals how procurement concentration and technology substitution are reallocating revenue across product categories. Understanding these divisions exposes where ANSM regulatory pressure and ARS tender consolidation are compressing margins versus where platform lock-in preserves pricing power.
Product Type:
Margin pools concentrate in recurring consumable revenue streams rather than capital equipment sales, with reagent lock-in driving profitability across installed instrument bases.
- Reagents & Kits:Proprietary biochemical formulations with picogram-to-nanogram sensitivity thresholds generate recurring revenue through platform-specific compatibility requirements. AP-HP network laboratories are consolidating procurement around multi-year reagent supply agreements that standardize testing menus and reduce vendor fragmentation.
- Instruments:Automated sample-to-answer systems with integrated pre-analytical processing command premium positioning in Île-de-France hospital tenders. Capital allocation competition from molecular diagnostics platforms is extending hematology analyzer replacement cycles across public sector laboratories.
- Software & Services:Laboratory information system middleware and AI-assisted pathology algorithms create service revenue attachments for academic medical centers.
- Consumables:Disposable reaction vessels, pipette tips, and sample collection devices face pricing pressure from centralized ARS procurement frameworks.
Reagents & Kits hold installed capacity. Instruments is rotating up the share rankings.
Technology:
Technology mix in France reflects a volume-to-value migration, with high-throughput legacy systems ceding ground to precision platforms that command companion diagnostic reimbursement premiums.
- Molecular Diagnostics:Nucleic acid amplification and next-generation sequencing technologies enable pathogen detection and oncogenic variant identification at single-molecule sensitivity. Regional hospital networks in Provence-Alpes-Côte d'Azur are piloting federated sequencing topologies that preserve sample proximity while maintaining quality uniformity.
- Immunoassay:Chemiluminescent and enzyme-linked immunosorbent assays dominate high-throughput protein biomarker quantification in centralized laboratories. Roche Diagnostics anchors demand through installed base expansion across AP-HP networks, leveraging antibody specificity for cardiac troponin and thyroid hormone panels.
- Clinical Chemistry:Spectrophotometric and ion-selective electrode methods maintain volume leadership across public hospital laboratories but face margin compression from LPPR pricing controls.
- Hematology:Automated cell counting and differential analysis systems are experiencing lengthened renewal cycles as facilities prioritize molecular infrastructure spending.
- Microbiology:Culture-based and rapid antigen detection methods serve antimicrobial stewardship programs in hospital-based laboratories.
Immunoassay maintains the deepest installed base. Molecular Diagnostics is climbing the fastest as precision medicine programs expand.
Application:
Application demand in France concentrates where HAS reimbursement codes align with clinical utility evidence, filtering commercial access before public funding commitment.
- Oncology:Companion diagnostic assays for targeted therapy selection command LPPR nomenclature expansion and dedicated precision medicine budgets. HAS evaluation criteria for diagnostic innovation reimbursement create parallel hurdles that shape market entry sequencing.
- Infectious Diseases:Syndromic respiratory panels and antimicrobial resistance detection address hospital-acquired infection surveillance mandates. ANSM's strengthened post-market surveillance requirements for Class C and D IVD devices elevate clinical evidence generation costs for sepsis biomarker developers.
- Cardiology:High-sensitivity troponin assays and natriuretic peptide testing support emergency department triage protocols.
- Genetic Testing:Carrier screening and pharmacogenomic panels face bioinformatics interpretation bottlenecks that constrain throughput expansion.
- Endocrinology:Diabetes monitoring and thyroid function testing maintain steady volume through chronic disease management protocols.
- Neurology:Cerebrospinal fluid biomarkers for neurodegenerative disease remain concentrated in academic medical center reference laboratories.
Infectious Diseases holds the broadest installed testing capacity. Oncology is gaining share fastest through companion diagnostic reimbursement unlocking.
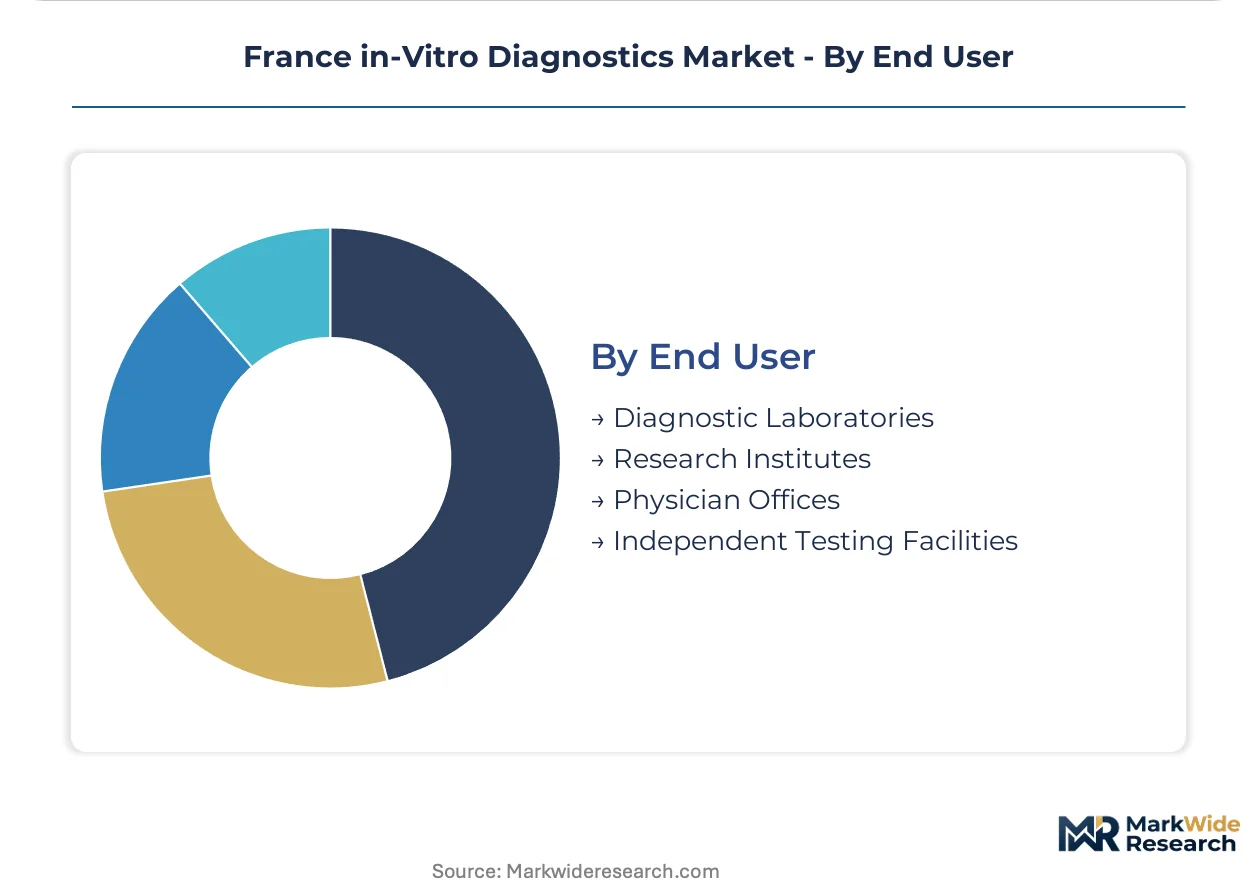
End User:
End user structure in France reflects a bifurcation between centralized high-throughput laboratories and distributed point-of-care nodes, with connectivity standards determining competitive positioning.
- Diagnostic Laboratories:Hospital-based and independent reference laboratories process the majority of complex molecular and immunoassay testing. Consolidated ARS tender frameworks are standardizing instrument specifications and reducing vendor fragmentation in public sector purchasing.
- Physician Offices:Point-of-care platforms with DMP electronic health record integration command premium positioning in regional primary care networks. Abbott Laboratories differentiates via connectivity solutions that interface directly with France's national health data infrastructure.
- Research Institutes:Academic medical center laboratories drive adoption of AI-assisted pathology algorithms and digital imaging classification systems.
- Independent Testing Facilities:Private sector laboratories compete on turnaround time and specialized test menus outside LPPR reimbursement constraints.
Diagnostic Laboratories hold the dominant installed capacity. Physician Offices is rotating up the share rankings through decentralized testing network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across French sub-regions, with Île-de-France hospital networks prioritizing automation premiums while Occitanie and Auvergne-Rhône-Alpes laboratories emphasize cost containment in decentralized testing procurement.
Île-de-France
AP-HP network laboratories drive demand for high-throughput molecular diagnostics platforms and automated sample-to-answer systems. ANSM's CE-IVDR implementation timelines compress certification windows for Class C and D devices entering this market. Paris and inner-ring hospital clusters anchor installed instrument density, with Saint-Louis and Pitié-Salpêtrière facilities piloting federated sequencing topologies for oncology panels.
Auvergne-Rhône-Alpes
Lyon-based bioMérieux manufacturing secures domestic reagent supply chains for regional hospital networks expanding precision medicine programs. HAS companion diagnostic reimbursement codes unlock public funding for targeted therapy selection assays across HCL network laboratories. The Lyon-Saint-Étienne-Grenoble corridor concentrates molecular diagnostics infrastructure investment, with Centre Léon Bérard driving adoption of AI-assisted pathology algorithms.
Provence-Alpes-Côte d'Azur
Regional ARS tender consolidation standardizes immunoassay platform specifications across Marseille and Nice hospital networks. CE-IVDR conformity assessment costs filter market participation toward established regulatory affairs scale. The Aix-Marseille-Provence metropolitan cluster pilots distributed testing nodes that preserve sample proximity for time-critical infectious disease surveillance.
Hauts-de-France
Extended hematology analyzer renewal cycles reflect capital allocation priorities shifting toward molecular diagnostics infrastructure in Lille and Amiens public laboratories. LPPR nomenclature revisions for diabetes monitoring maintain steady clinical chemistry volume through chronic disease management protocols. The Lille metropolitan area anchors cross-border procurement coordination with Belgian hospital networks.
Occitanie
Geographic access gaps in rural zones drive community pharmacy expansion of rapid diagnostic capabilities with DMP electronic health record integration. ANSM post-market surveillance requirements elevate pharmacovigilance infrastructure demands for point-of-care platform vendors. Toulouse and Montpellier academic medical centers concentrate research institute demand for next-generation sequencing workflows and digital imaging classification systems.
France in-Vitro Diagnostics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with multinational diagnostics conglomerates commanding premium positioning through proprietary reagent lock-in while mid-scale manufacturers compete on standardized platform economics. The market structure tiers into three archetypes: integrated life sciences conglomerates with full-stack molecular-to-immunoassay portfolios, specialized microbiology and infectious disease testing houses with domestic manufacturing footprints, and point-of-care connectivity specialists targeting decentralized network expansion. Dominant competitive moves include multi-year reagent supply agreements that lock in vendor relationships across extended contractual horizons, and strategic partnerships with academic medical centers for AI-assisted algorithm development.
Among France-based specialists, bioMérieux exemplifies the microbiology-focused archetype with Lyon-anchored manufacturing securing domestic supply chain continuity. Roche Diagnostics and Abbott Laboratories occupy positions as multinational conglomerates, with the former representing installed base expansion strategies across AP-HP networks and the latter exemplifying point-of-care connectivity integration with national health data infrastructure. These three entities represent distinct competitive positioning vectors: domestic manufacturing security, high-throughput centralized laboratory anchoring, and decentralized electronic health record interoperability.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| bioMérieux |
| Danaher Corporation |
| Becton, Dickinson and Company |
| QIAGEN |
| Sysmex Corporation |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day reagent lead times for Class C and D IVD devices expose how ANSM's CE-IVDR certification bottlenecks concentrate pricing power among manufacturers with established clinical evidence registries, while hospital laboratories absorb cost premiums to secure supply continuity for precision oncology panels.
Pricing Analysis
After-sales service contracts and multi-year reagent supply agreements generate lifetime value that exceeds initial instrument placement revenue by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and installed base lock-in, with ANSM's post-market surveillance requirements elevating compliance costs that compress margins in the mid-tier. Pricing pressure stems from consolidated ARS tender frameworks that standardize technical specifications across Île-de-France hospital networks. Public sector laboratories exhibit highest price sensitivity due to fixed LPPR reimbursement ceilings, while academic medical centers prioritize analytical performance over procurement cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Le Havre container terminals fluctuate with trans-Atlantic lane capacity, compressing just-in-time reagent delivery windows for Lyon-based bioMérieux manufacturing and German-sourced hematology consumables. Geographic supply concentration centers on France, Germany, and Switzerland for diagnostic enzymes and precision optics, with raw material dependencies spanning purified antibodies, fluorophores, and polymerase enzymes. Single-source vulnerability in thermostable DNA polymerase production exposes testing continuity to supplier disruption. Distribution runs through regional ARS central warehouses that consolidate procurement across hospital networks before final-mile delivery to laboratory sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's in-vitro diagnostics market sits in early-cycle expansion as LPPR nomenclature broadening unlocks public funding for companion diagnostics before precision medicine programs reach saturation penetration.
For Market Incumbents: Compound installed base advantages through multi-year reagent supply agreements that lock AP-HP and HCL network laboratories into extended contractual horizons, while accelerating clinical bioinformatics training partnerships to address personnel shortages constraining molecular diagnostics throughput. Defend against point-of-care connectivity specialists by deepening DMP electronic health record integration capabilities. For New Entrants and Emerging Players: Anchor in decentralized testing networks across rural Occitanie and Auvergne-Rhône-Alpes regions where geographic access gaps create white-space opportunities outside consolidated ARS tender coverage. Target community pharmacy rapid diagnostic expansion with platforms featuring direct DMP connectivity, leveraging streamlined CE-IVDR certification pathways for lower-risk device classes. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because reagent lock-in and platform switching costs generate durable margin pools that outlast capital equipment replacement cycles. Target acquisition candidates with AI-assisted pathology algorithm pipelines and established ANSM quality management systems. Monitor LPPR nomenclature revision velocity as the signal indicating reimbursement expansion or contraction for precision oncology testing.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | ANSM's expanded clinical evidence requirements filter market participation toward regulatory affairs scale. |
| Hospital System Partnership | AP-HP network anchoring secures multi-year reagent commitments and platform standardization. |
| Software Companion Development | DMP electronic health record integration commands premium positioning in regional ARS tenders. |
| Reimbursement Strategy | HAS companion diagnostic evaluation criteria shape commercial access before public funding commitment. |
| Backward Integration | Domestic enzyme production reduces single-source vulnerability in thermostable polymerase supply. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs directors, hospital laboratory managers, biomedical procurement officers, and GPO contracts specialists anchors the qualitative findings, while secondary validation draws from ANSM device registration databases, HAS reimbursement nomenclature filings, AP-HP tender documentation, and regional ARS procurement records. Bottom-up instrument placement and reagent consumption estimates triangulate against top-down healthcare expenditure flows.
Sensitivity analysis around LPPR revision timelines and CE-IVDR certification throughput rates tests forecast robustness across the projection horizon. Segmentation dimensions modeled include technology type, application area, end-user category, and regional hospital network cluster. CAGRs derive from logistic diffusion curves fitted to precision medicine program expansion rates and molecular platform automation adoption patterns, with inputs spanning companion diagnostic pipeline density and clinical bioinformatics workforce growth trajectories.
Material uncertainties — ANSM regulatory enforcement intensity, ARS tender consolidation pace, reagent supply disruption events — sit outside the modeled envelope. Forecasts reflect documented assumptions about reimbursement expansion continuity and certification timeline normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Cancer IVD Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
IVD Antibody Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Semen Analysis Market
Diagnostics
Blood Culture Media Market
Diagnostics
Global Alzheimers Disease Diagnostic Market