
 Veterinary Pain Management Drugs Market | 2026-2036
Veterinary Pain Management Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Pain Management Drugs Market Outlook
Long-acting injectable formulations is reconfiguring how veterinary practices manage perioperative and chronic pain, shifting dosing schedules from daily oral regimens to monthly or quarterly interventions. Zoetis leverages its biologics infrastructure to develop extended-release platforms for companion animals. Merck Animal Health sustains competitive pressure through its anesthesia-analgesia portfolio spanning large and small animal segments. Boehringer Ingelheim differentiates via its equine-focused NSAID franchise and regional veterinary education programs.
Veterinary pain management drugs comprise pharmacologically active compounds formulated for species-specific metabolism, including COX-selective inhibitors, mu-opioid receptor agonists, and voltage-gated sodium channel blockers, manufactured under GMP conditions with excipient profiles adjusted for carnivore, herbivore, or avian gastrointestinal physiology. Their primary purpose is to restore mobility, maintain feeding behavior, and extend functional life expectancy in animals suffering from trauma, degenerative joint disease, neoplastic conditions, or surgical insult. NSAIDs occupy the largest volume share due to established efficacy in osteoarthritis and post-operative protocols, while transdermal delivery systems represent the fastest-expanding administration route as owners prefer home-based application over clinic visits. Cancer pain indications command premium pricing due to limited approved alternatives and the complexity of multimodal regimens.
The FDA Center for Veterinary Medicine enforces stringent bioequivalence and target animal safety studies that extend development timelines but elevate clinical confidence in approved products. EMA guidelines on maximum residue limits shape export-oriented manufacturing decisions for companies serving European livestock and dairy markets. ISO veterinary pharmacovigilance standards are tightening post-market surveillance obligations across jurisdictions. Stakeholders must monitor evolving compounding pharmacy regulations and the entry of biosimilar monoclonal antibodies as these forces will reshape competitive dynamics and investment priorities.
Market Dynamics
The FDA's expanded labeling requirements for veterinary NSAIDs are compressing development timelines while simultaneously elevating the technical barrier for market entry, forcing manufacturers to invest in species-specific pharmacokinetic studies that smaller competitors cannot fund.
Growth Catalysts
- Pet Insurance Penetration:Rising coverage rates in the United States are extending treatment durations and enabling veterinarians to prescribe multimodal pain protocols previously constrained by owner cost sensitivity.
- EMA Maximum Residue Limits:Harmonized standards for export-oriented livestock producers are driving demand for validated analgesic regimens that satisfy European dairy and meat import requirements.
- Extended-Release Biologics:Monthly and quarterly injectable platforms are reducing clinic visit frequency while improving compliance in chronic osteoarthritis management for aging companion animals.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Sourcing of COX-selective inhibitors relies heavily on Chinese and Indian contract manufacturers, creating vulnerability to geopolitical trade disruptions.
- Target Animal Safety Study Costs:FDA Center for Veterinary Medicine mandates multi-species toxicology protocols that add substantial fixed costs before commercial approval.
- Generic Small-Molecule Substitution:Expiring patents on established NSAIDs are enabling unbranded competitors to capture price-sensitive livestock segments.
Strategic Opportunities
- Brazilian Livestock Expansion:ANVISA regulatory pathways for large-animal analgesics remain underdeveloped relative to herd size, creating first-mover potential for validated products.
- Transdermal Home Administration:Owner-applied fentanyl patches and lidocaine formulations are opening channels that bypass traditional clinic-centric distribution.
- ISO Veterinary Pharmacovigilance:Tightening post-market surveillance obligations are favoring manufacturers with established adverse event databases and quality management systems.
Industry Challenges
- Veterinary Anesthesiology Specialist Shortage:Limited residency programs in academic centers constrain the clinical workforce needed to support advanced multimodal protocols.
- Compounding Pharmacy Regulatory Friction:State-level enforcement variability creates compliance complexity for practices sourcing customized formulations from 503B facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Pain Management Drugs Market |
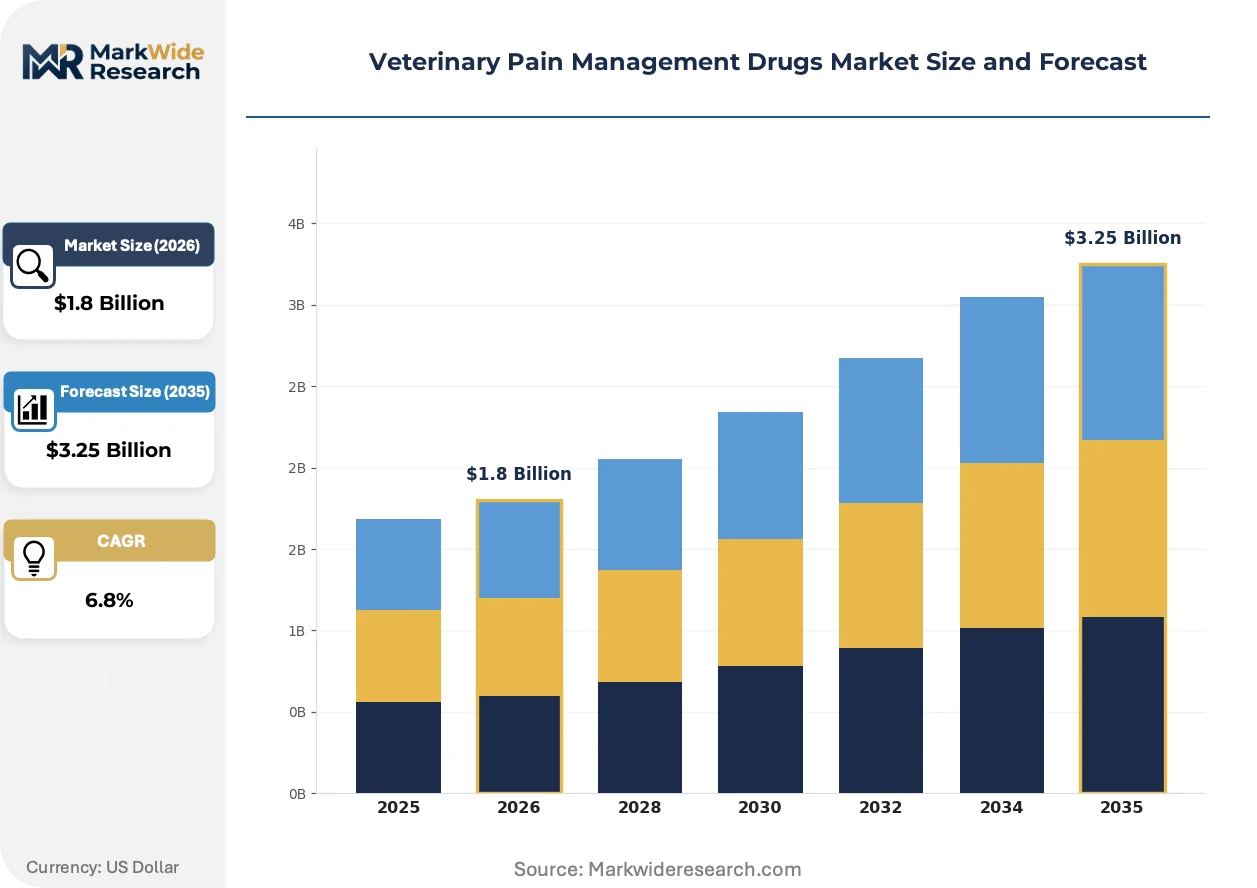
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
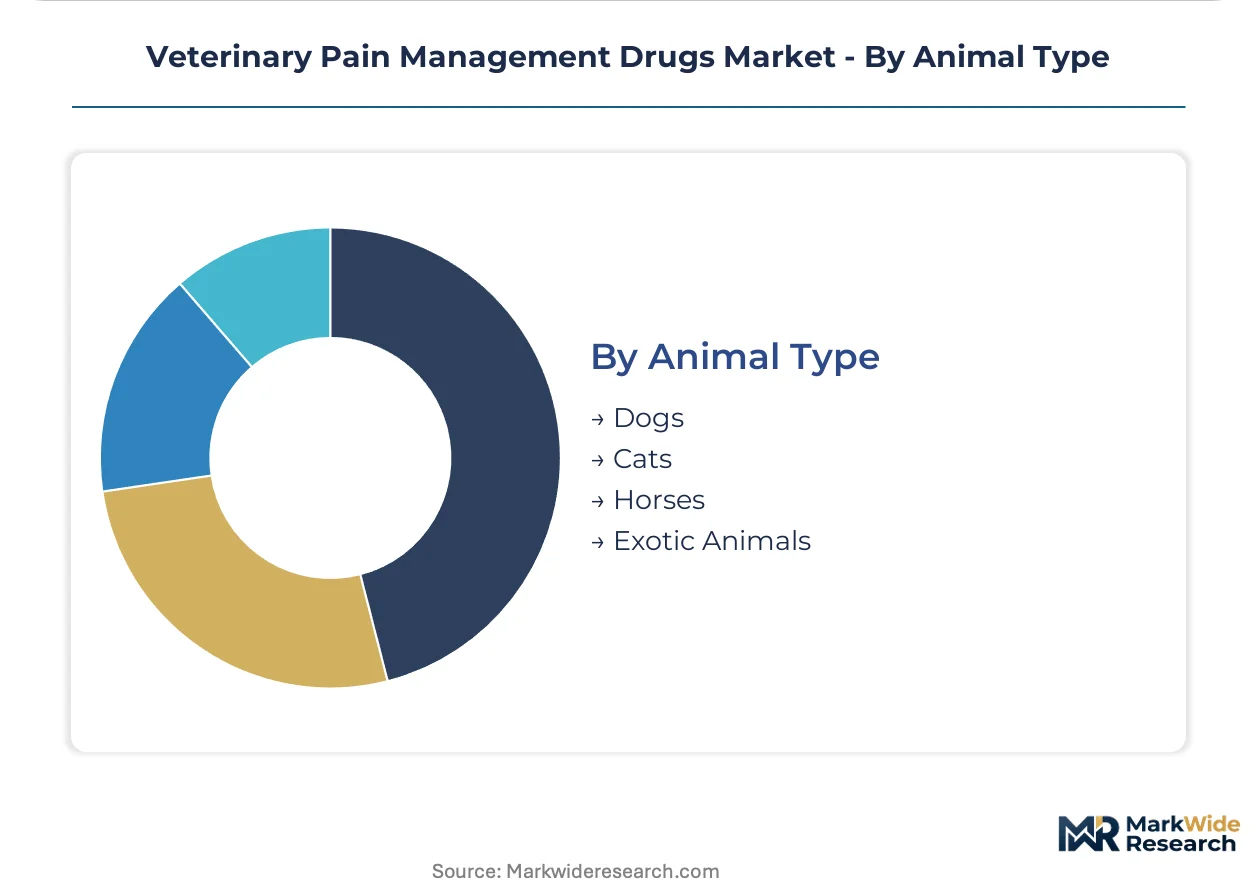
| Segmentation | Product Type: NSAIDs, Opioids, Corticosteroids, Local Anesthetics Indication: Osteoarthritis, Post-Surgical Pain, Cancer Pain, Neuropathic Pain Administration Route: Oral, Injectable, Topical, Transdermal Animal Type: Dogs, Cats, Horses, Exotic Animals |
| Companies Covered | Merck Animal Health, Vetoquinol, Zoetis, Norbrook Laboratories, Ceva Santé Animale, Boehringer Ingelheim, Dechra Pharmaceuticals, Virbac, Elanco Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Pain Management Drugs Market Strategic Shifts
Formulation science and delivery mechanisms are converging to reshape how analgesia reaches veterinary patients, with implications for compliance economics and practice workflow design.
Long-acting depot injections are collapsing the traditional daily oral dosing paradigm for chronic pain management. Specialty and emergency practices are adopting these platforms fastest, recognizing the revenue protection from reduced refill friction and the clinical benefit of steady-state plasma concentrations. The technology is collapsing the competitive advantage of established oral NSAID franchises by decoupling efficacy from owner compliance reliability.
REACH chemical registration requirements are extending to veterinary pharmaceutical excipients used in European export markets. Manufacturers must now document full substance dossiers for carrier oils and preservatives previously treated as inert, adding formulation reformulation costs. The livestock analgesic segment is responding by consolidating supplier relationships and pre-qualifying excipient sources against evolving ECHA substance evaluation criteria.
Subscription-based medication delivery is replacing episodic prescription fulfillment in companion animal practice. Direct-to-owner platforms are disintermediating traditional veterinary distributors, particularly for chronic condition maintenance therapies. This pattern is most visible in United States urban markets where telemedicine-enabled practices seek to capture recurring revenue streams independent of clinic visit volume.
Veterinary Pain Management Drugs Market Segmentation

Veterinary pain management drugs fragment across four dimensions that determine prescribing economics and development priorities. Product type and administration route drive manufacturing investment, while indication and animal type shape clinical trial design and regulatory pathway selection.
Product Type:
Cycle times vary dramatically across this category, with NSAIDs turning inventory fastest due to chronic condition maintenance dosing, while opioid formulations face extended procurement cycles from controlled-substance scheduling requirements.
- NSAIDs:COX-selective inhibitors formulated for carnivore and herbivore gastrointestinal physiology dominate perioperative and osteoarthritis protocols. Demand concentrates in United States companion animal clinics where pet insurance enables extended maintenance regimens for aging dogs.
- Opioids:Mu-opioid receptor agonists including fentanyl, morphine, and buprenorphine address severe acute and cancer pain. United States veterinary teaching hospitals drive consumption through multimodal anesthesia-analgesia protocols, though DEA scheduling creates distribution friction and inventory holding costs.
- Corticosteroids:Glucocorticoid formulations provide anti-inflammatory and immunosuppressive effects in acute flare management.
- Local Anesthetics:Voltage-gated sodium channel blockers including lidocaine and bupivacaine serve regional anesthesia and incisional infiltration applications.
NSAIDs anchors the volume base while transdermal opioid delivery systems gain share at the steepest rate.
Indication:
Pricing tiers separate acute episodic conditions from chronic maintenance indications, with cancer pain commanding premium positioning due to limited therapeutic alternatives and complex multimodal requirements.
- Osteoarthritis:Degenerative joint disease in aging companion animals generates recurring prescription volume for oral NSAIDs and emerging long-acting injectable platforms. United States urban markets with high pet insurance penetration show the strongest concentration as owners pursue extended quality-of-life regimens.
- Post-Surgical Pain:Perioperative analgesia protocols demand rapid-onset formulations with predictable duration to match procedure recovery windows. Academic veterinary medical centers in the United States establish protocol standards that cascade to general practice adoption.
- Cancer Pain:Neoplastic condition management requires escalating multimodal approaches as disease progresses, combining NSAIDs, opioids, and adjuvant therapies.
- Neuropathic Pain:Central and peripheral sensitization conditions including diabetic neuropathy and intervertebral disc disease represent emerging indications with limited approved options.
Osteoarthritis generates the largest addressable patient population while cancer pain exhibits the steepest expansion trajectory.
Administration Route:
Customer workflow preferences are shifting prescribing patterns, with home-based application displacing clinic-dependent administration for chronic maintenance therapies.
- Oral:Tablet and liquid formulations remain the default for owner-administered chronic maintenance, though compliance gaps erode efficacy in practice. United States retail pharmacy and veterinary distributor channels maintain dominant distribution positions for this route.
- Injectable:Parenteral delivery ensures bioavailability and rapid onset for perioperative and emergency applications. Specialty and emergency practices in the United States adopt long-acting depot formulations fastest, recognizing revenue protection from reduced refill friction.
- Topical:Cream, gel, and spray formulations enable localized delivery with reduced systemic exposure for surface and soft tissue conditions.
- Transdermal:Patch-based fentanyl and lidocaine systems allow owner application while bypassing gastrointestinal metabolism. Direct-to-owner subscription platforms in United States urban markets are disintermediating traditional distributor relationships for this route.
Oral administration retains the largest volume position while transdermal delivery climbs the fastest as owner convenience preferences reshape channel economics.
Animal Type:
Species-specific metabolism and physiology drive formulation differentiation, with companion animal segments supporting premium pricing and livestock applications facing cost-constrained generic substitution.
- Dogs:Canine pain management represents the largest revenue pool, driven by osteoarthritis prevalence in aging populations and willingness-to-pay among owners. United States pet insurance expansion directly benefits this segment by removing cost barriers to multimodal chronic protocols.
- Cats:Feline formulations require adjusted excipient profiles and palatability engineering due to unique hepatic glucuronidation limitations and selective feeding behavior. United States feline-exclusive practices drive demand for species-specific NSAIDs with demonstrated renal safety margins.
- Horses:Equine athletes and pleasure animals require analgesia for musculoskeletal conditions, laminitis, and post-surgical recovery. EMA maximum residue limits shape product selection for export-oriented competition and breeding operations.
- Exotic Animals:Avian, reptile, and small mammal applications demand highly specialized pharmacokinetic data and compounding expertise due to metabolic diversity.
Dogs anchor the volume base while cats gain share at the steepest rate as feline-specific formulation development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export veterinary pain management formulations to European Union livestock operations seeking EMA-compliant residue documentation. This transatlantic corridor channels premium NSAID and biologic products toward export-oriented dairy and meat producers in Germany, France, and the Netherlands.
United States
FDA Center for Veterinary Medicine enforcement of expanded NSAID labeling requirements drives domestic formulation investment. Pet insurance penetration exceeding established levels in urban coastal markets enables multimodal chronic pain protocols previously constrained by owner cost sensitivity. Greater Boston and San Diego biotech clusters host development programs for extended-release companion animal platforms.
Germany
EMA maximum residue limit compliance shapes procurement decisions for export-oriented dairy cooperatives. REACH chemical registration requirements extend to veterinary pharmaceutical excipients, forcing reformulation of carrier oils and preservatives. Baden-Württemberg's pharmaceutical manufacturing corridor concentrates GMP production facilities serving European livestock and companion animal markets.
China
NMPA oversight of veterinary drug manufacturing intensifies as domestic companion animal ownership expands in tier-one cities. Contract manufacturers in Jiangsu and Zhejiang provinces supply COX-selective inhibitor active pharmaceutical ingredients to Western formulators. Yangtze River Delta logistics hubs coordinate export shipments subject to SAMR quality system audits.
Brazil
ANVISA regulatory pathways for large-animal analgesics remain underdeveloped relative to cattle and swine herd scale. São Paulo state veterinary pharmaceutical distributors import finished formulations through Paraguayan transit corridors to circumvent documentation gaps. Minas Gerais dairy cooperatives increasingly demand validated analgesic regimens for European export qualification.
United Kingdom
Veterinary Medicines Directorate post-Brexit regulatory autonomy creates divergence from EMA guidelines for Northern Ireland trade continuity. London and Southeast England specialist referral hospitals establish multimodal anesthesia-analgesia protocols that cascade to general practice adoption. Feline-specific NSAID demand concentrates in urban practices with high owner willingness-to-pay.
Veterinary Pain Management Drugs Market Competitive Environment
Channel-controlling players compete with product-specialist players across distribution hierarchies that separate clinic-direct from retail pharmacy fulfillment. The market structure consolidates around three strategic tiers: diversified animal health conglomerates with biologics infrastructure, mid-cap pharmaceutical specialists with species-specific formulation expertise, and regional generics manufacturers serving price-constrained livestock segments. Dominant competitive moves include portfolio diversification into long-acting injectable platforms and geographic expansion through distributor acquisition in underpenetrated Latin American markets.
Among diversified animal health conglomerates, Merck Animal Health and Zoetis occupy positions exemplifying the integrated development and distribution archetype. Boehringer Ingelheim represents the European-focused specialist with equine and companion animal franchise concentration. These three entities anchor the premium tier through extended-release biologic platforms and established veterinary education relationships that shape protocol adoption.
| Leading Market Players |
|---|
| Merck Animal Health |
| Vetoquinol |
| Zoetis |
| Norbrook Laboratories |
| Ceva Santé Animale |
| Boehringer Ingelheim |
| Dechra Pharmaceuticals |
| Virbac |
| Elanco Animal Health |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Zhejiang provinces anchor COX-selective inhibitor API production, and their capacity utilization rates directly determine margin compression timelines for Western formulators seeking to secure long-term offtake agreements. FDA-mandated target animal safety studies add fixed-cost layers that compound the pricing power of manufacturers with established biologics infrastructure.
Pricing Analysis
Prior-generation oral NSAIDs compete on commodity spot pricing while extended-release injectable platforms command subscription-based premiums tied to compliance economics. Three-tier pricing structure across premium biologics, validated standard formulations, and economy generics separates Zoetis depot injections from Boehringer Ingelheim equine NSAIDs from unbranded livestock alternatives. Price differentiation hinges on FDA approval tier and species-specific pharmacokinetic documentation. Cost compression in the generic oral segment intensifies as Indian and Chinese API suppliers expand capacity. Livestock producers exhibit highest price sensitivity; United States companion animal clinics with pet insurance reimbursement show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for COX-selective inhibitor raw materials. Active pharmaceutical ingredient production concentrates in Jiangsu and Zhejiang provinces of China, with secondary sourcing from Gujarat and Hyderabad clusters in India. Finished formulation depends on carnivore-specific excipients, GMP-certified sterile manufacturing capacity, and cold-chain distribution infrastructure. Single-source vulnerability persists for extended-release biologic platforms where Zoetis and Merck Animal Health control proprietary depot technologies. Distribution runs through veterinary distributor networks in the United States, direct-to-owner subscription platforms in urban markets, and Paraguayan transit corridors serving Brazilian livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary pain management is approaching a platform-economics inflection where extended-release biologics create recurring revenue ecosystems that displace episodic prescription fulfillment. Interoperability between telemedicine-enabled practices and direct-to-owner delivery platforms is collapsing traditional distributor gatekeeper roles.
For Market Incumbents: Harden defensive moats around long-acting injectable platforms by deepening backward integration into depot formulation technologies and acquiring telemedicine infrastructure in United States urban markets. Generic small-molecule substitution in livestock segments threatens margin pools; channel control through exclusive distributor relationships in Brazil and Mexico protects pricing power.
For New Entrants and Emerging Players: Build out transdermal home administration capabilities targeting feline-specific NSAID gaps where palatability engineering and hepatic glucuronidation safety data create technical barriers. Brazilian large-animal analgesics present the most penetrable geography given ANVISA regulatory pathway underdevelopment relative to herd scale. Direct-to-owner subscription models bypass entrenched veterinary distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a chronic-disease-management play because aging companion animal demographics and pet insurance expansion create predictable recurring revenue streams independent of acute surgical volume. Acquisition targets should exhibit species-specific formulation expertise with demonstrated FDA Center for Veterinary Medicine approval track records. The signal to watch is DEA scheduling relaxation for transdermal opioid patches enabling broader home administration penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Biologic Platform Development | Zoetis leverages depot injection technology to collapse daily dosing compliance gaps in canine osteoarthritis. |
| Direct-to-Owner Subscription Launch | Telemedicine-enabled practices in United States urban markets capture recurring revenue independent of clinic visit volume. |
| Species-Specific Formulation Investment | Feline-exclusive practices demand hepatic glucuronidation-tested NSAIDs with demonstrated renal safety margins. |
| Brazilian Distributor Acquisition | ANVISA pathway gaps enable first-mover positioning in cattle and swine analgesics for European export qualification. |
| REACH Excipient Pre-Qualification | ECHA substance evaluation compliance protects European livestock market access for German dairy cooperatives. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with veterinary pharmaceutical development executives, regulatory affairs specialists at FDA Center for Veterinary Medicine, formulary directors at United States veterinary teaching hospitals, and procurement managers at Brazilian livestock cooperatives. Secondary validation drew from FDA 510(k) and NADA filings, EMA maximum residue limit documentation, ANVISA regulatory pathway records, and ISO veterinary pharmacovigilance standards. Bottom-up prescription volume modeling and top-down animal health expenditure estimates were triangulated to anchor market sizing.
Calibration against historical approval timelines and pricing elasticity observations shaped the analytical framework across the analysis window. Segmentation dimensions included product type, administration route, indication, and animal species with regional regulatory cluster overlays. CAGRs were derived from veterinarian prescribing pattern trajectories, pet insurance penetration curves, and livestock herd expansion projections. Key inputs incorporated DEA scheduling dynamics for controlled substances and REACH chemical registration cost impacts on excipient sourcing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by generic API manufacturers or telemedicine platform entrants would shift outcomes beyond modeled ranges. Regulatory acceleration at FDA or EMA, trade disruption in China-United States API corridors, and compounding pharmacy enforcement variability represent specific revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Galculus Bovis and Metronidazole Market