
 Epigenetics Drugs and Diagnostic Technologies Market | 2026-2036
Epigenetics Drugs and Diagnostic Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Epigenetics Drugs and Diagnostic Technologies Market Intelligence
The direct integration of diagnostic technologies with therapeutic development pipelines is reshaping competitive positioning among market participants. Hoffmann-La Roche leverages its dual strength in pharmaceuticals and diagnostics to offer combined solutions. Illumina dominates the sequencing technology space, which is critical for epigenetic biomarker discovery. Novartis AG competes through a robust pipeline of novel histone deacetylase inhibitors and other epigenetic modifiers targeting various cancers.
Epigenetic drugs and diagnostic technologies target reversible, heritable changes in gene expression that do not involve alterations to the DNA sequence itself. These interventions modulate mechanisms like DNA methylation and histone modification to influence cellular function, primarily for therapeutic or diagnostic purposes in complex diseases. Among product types, DNA Methylation Inhibitors and Histone Deacetylase Inhibitors constitute a major share of the therapeutics segment. The oncology therapy area represents the largest application, while diagnostic assays for biomarker identification are experiencing rapid development for early disease detection.
Market access is governed by stringent regulatory bodies, including the United States FDA and the European Medicines Agency (EMA), which require extensive clinical trial data for drug approval. In China, the NMPA's evolving guidelines for innovative therapies and companion diagnostics influence market entry strategies for multinational firms. Stakeholders must navigate the complex intellectual property landscape and forge strategic partnerships to succeed in this highly specialized field.
Market Dynamics
The convergence of diagnostic biomarker discovery with therapeutic drug development is the central force defining the market, compelling a more integrated R&D and commercialization strategy for participants. This dynamic necessitates closer collaboration between pharmaceutical and diagnostic divisions to align drug pipelines with patient stratification tools.
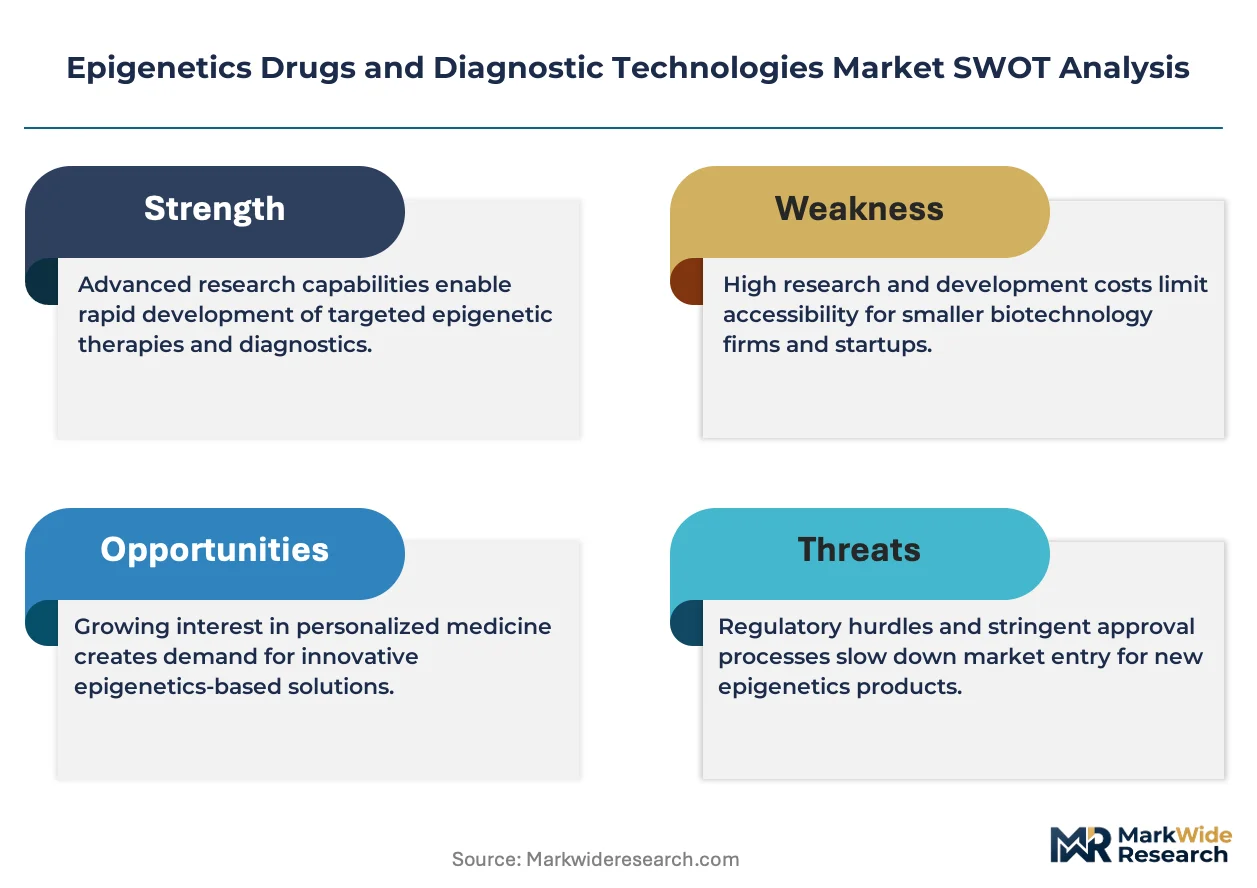
Growth Catalysts
- Regulatory Facilitation:Accelerated approval pathways, such as those offered by the United States FDA, shorten the time-to-market for novel epigenetic drugs addressing significant unmet needs in oncology.
- Advancements in Sequencing:The widespread availability of next-generation sequencing technologies provides the essential tools for identifying and validating epigenetic biomarkers, fueling diagnostic development.
- Expanding Therapeutic Pipeline:A growing pipeline of histone deacetylase inhibitors and DNA methylation inhibitors targeting a broader range of cancers is stimulating clinical research and investment.
Market Restraints
- High R&D Investment:The substantial capital required to fund long and complex clinical trials for epigenetic therapies represents a significant financial barrier for many developers.
- Biological Complexity:Incomplete understanding of the intricate off-target effects and downstream pathways of epigenetic modifiers poses a fundamental technical challenge in drug design and safety profiling.
- Reimbursement Hurdles:Securing favorable reimbursement policies from payers for high-cost epigenetic drugs and their associated diagnostic tests can be a lengthy and difficult process.
Strategic Opportunities
- Non-Oncology Indications:The application of epigenetic principles to neurodegenerative disorders, such as Alzheimer's disease, and autoimmune conditions presents a major area for therapeutic expansion.
- Companion Diagnostics Development:Creating integrated diagnostic tests to identify patient populations most likely to respond to a specific epigenetic therapy offers a path to personalized medicine.
- Asia-Pacific Market Entry:Growing healthcare expenditure and evolving regulatory frameworks in countries like China and Japan offer significant growth potential for advanced therapies.
Industry Challenges
- Bioinformatics Skill Shortage:A scarcity of trained bioinformaticians and data scientists capable of interpreting large-scale epigenomic datasets creates a critical bottleneck in both research and clinical application.
- Intellectual Property Navigation:The crowded and overlapping patent landscape for epigenetic targets and modification pathways complicates freedom-to-operate and increases the risk of litigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epigenetics Drugs and Diagnostic Technologies Market |
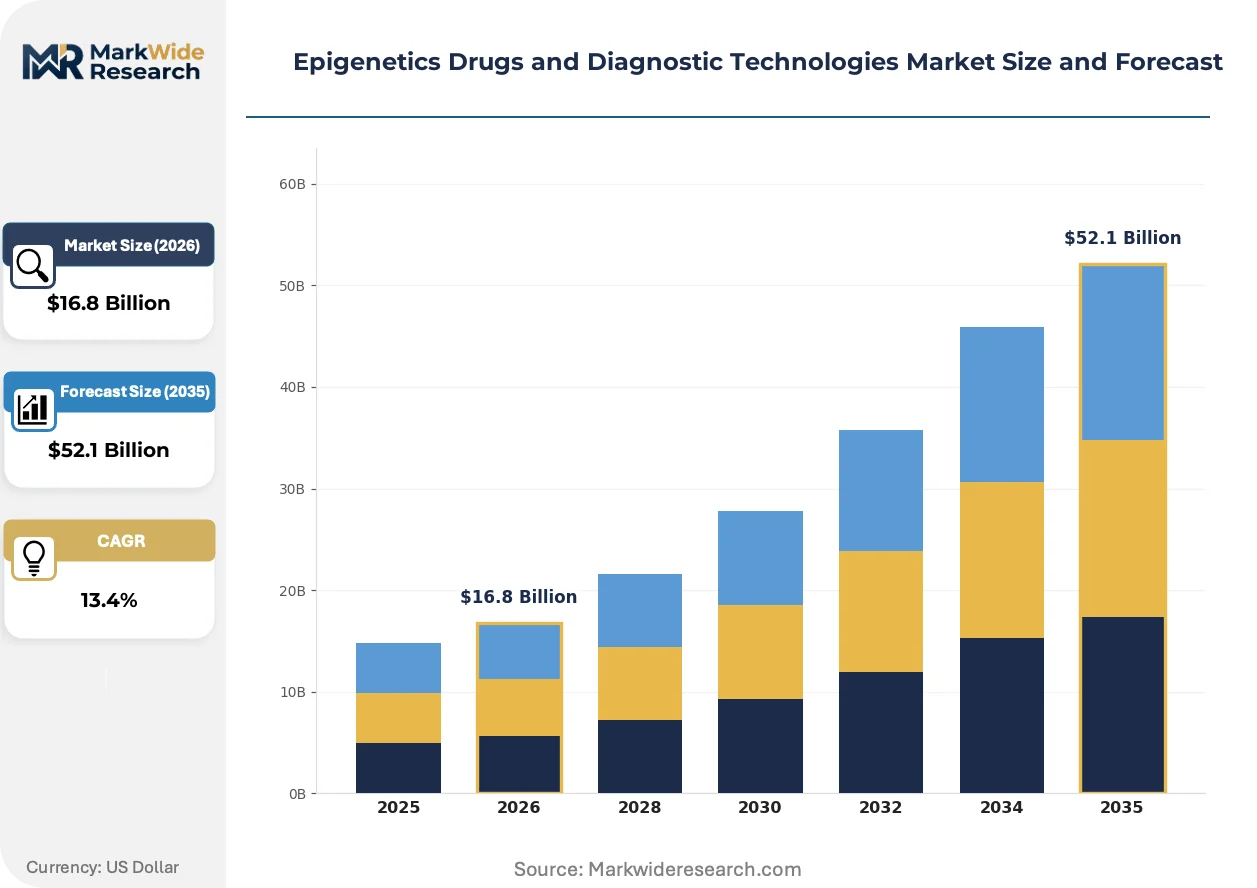
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $52.1 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Methylation Inhibitors, Histone Deacetylase Inhibitors, Histone Methyltransferase Inhibitors, Chromatin Remodeling Agents, Diagnostic Assays, Epigenetic Biomarkers Therapy Area: Oncology, Neurological Disorders, Autoimmune Diseases, Infectious Diseases, Metabolic Disorders, Rare Genetic Conditions End User: Pharmaceutical Companies, Clinical Laboratories, Research Institutes, Diagnostic Centers, Biotech Startups, Academic Institutions Delivery Mode: Oral, Injectable, Topical, Intravenous, Point-of-Care Testing, Laboratory-Based Testing |
| Companies Covered | Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., Eisai Co., Ltd., Novartis AG, Illumina, Inc., Merck KGaA, QIAGEN, Abcam Limited, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epigenetics Drugs and Diagnostic Technologies Market Strategic Shifts & Innovations
Precision medicine, underpinned by data-intensive analytics, is defining the next development phase. This evolution prioritizes molecular disease subtyping and the co-development of targeted therapies with predictive biomarkers to improve patient outcomes and demonstrate value to healthcare systems.
Single-cell epigenomic analysis provides unprecedented resolution into cellular heterogeneity within tissues like tumors. Research institutions and pharmaceutical developers adopt this technology to understand drug resistance mechanisms. This technique is digitizing the study of cell-to-cell variation, enabling the design of more precise combination therapies.
The European Medicines Agency's PRIority MEdicines (PRIME) scheme offers early, enhanced support to developers. This initiative accelerates assessment of medicines targeting an unmet medical need, benefiting innovative epigenetic drugs. The oncology segment, particularly for therapies targeting rare cancers, benefits most directly from this streamlined pathway.
A clear shift in R&D strategy is the simultaneous development of a therapeutic and its companion diagnostic. This integrated approach disrupts the traditional sequential model where diagnostics were an afterthought. The trend is most prominent in the United States oncology market, where targeted therapies increasingly require a specific biomarker test.
Epigenetics Drugs and Diagnostic Technologies Market Segmentation
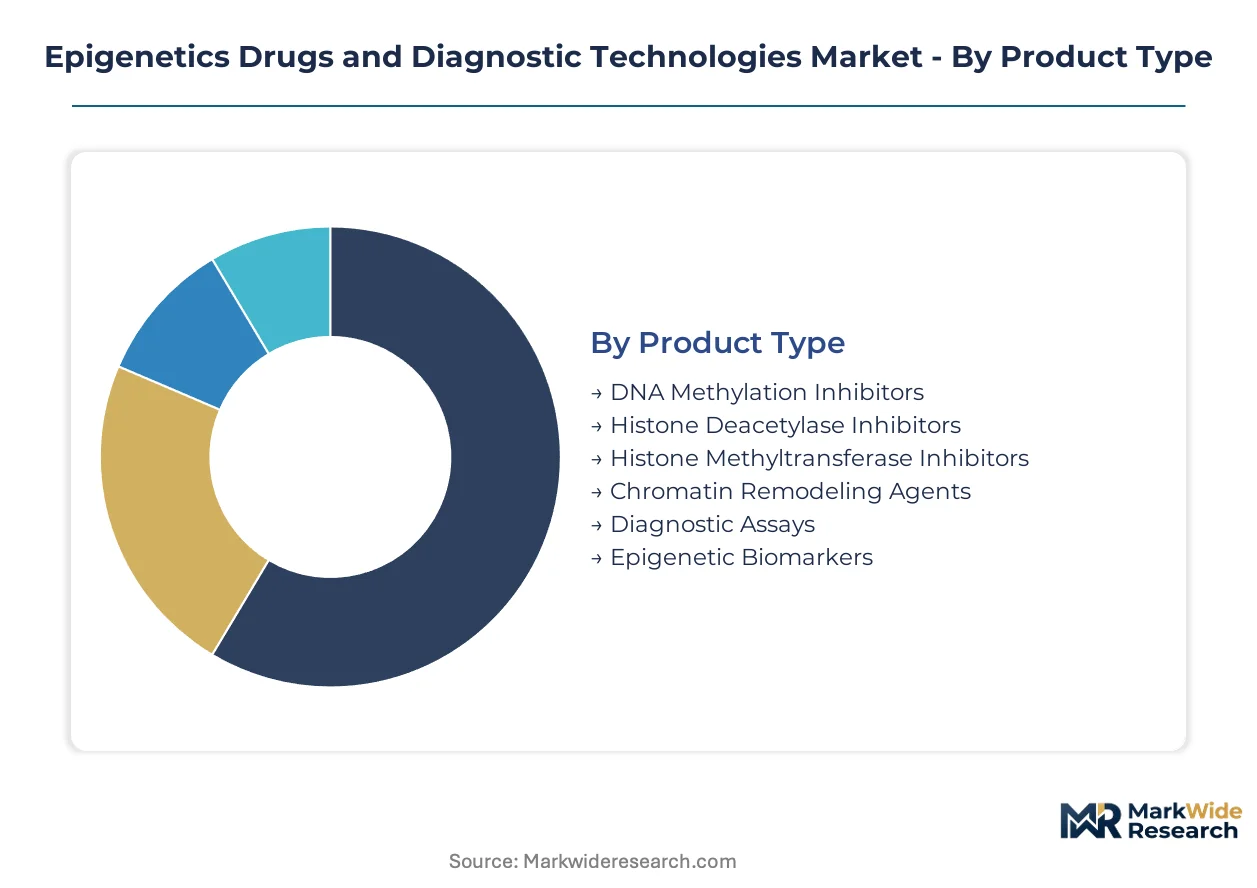
The segmentation of the Epigenetics Drugs and Diagnostic Technologies Market provides a granular understanding of the diverse product offerings and their applications across various therapeutic areas. This detailed breakdown highlights the specific mechanisms of action and the target populations benefiting from these advanced interventions.
Product Type:
The product type segmentation delineates the distinct mechanisms and applications across the epigenetics use-case spectrum.
- DNA Methylation Inhibitors:These small molecules interfere with DNA methyltransferase enzymes, leading to gene re-expression and therapeutic effects, particularly in hematological malignancies. Demand concentrates in the United States, driven by extensive clinical research and regulatory support for novel cancer therapies.
- Histone Deacetylase Inhibitors:These compounds block histone deacetylases, promoting chromatin relaxation and gene transcription, offering therapeutic potential in various cancers and neurological conditions. European markets show increasing adoption, supported by robust academic research and pharmaceutical development.
- Histone Methyltransferase Inhibitors:These agents target enzymes responsible for adding methyl groups to histones, influencing gene expression for specific therapeutic outcomes.
- Chromatin Remodeling Agents:This category includes drugs that alter chromatin structure, thereby modulating gene accessibility and activity for therapeutic benefit.
- Diagnostic Assays:These tests identify specific epigenetic modifications or biomarkers, crucial for disease detection, prognosis, and treatment selection.
- Epigenetic Biomarkers:These molecular indicators, such as specific methylation patterns, serve as predictive or prognostic tools in various disease states.
The dominant share belongs to DNA Methylation Inhibitors, while Diagnostic Assays are closing the gap fastest.
Therapy Area:
Application areas for epigenetic interventions span a wide range of complex diseases, each presenting unique therapeutic challenges.
- Oncology:Epigenetic therapies are primarily utilized in cancer treatment to reverse aberrant gene silencing and restore tumor suppressor function, particularly in leukemias and lymphomas. Demand is highest in developed economies like the United States, due to high cancer prevalence and advanced healthcare infrastructure.
- Neurological Disorders:This segment explores epigenetic modifiers for conditions like Alzheimer's and Parkinson's diseases, aiming to restore neuronal function and mitigate disease progression. Research in Japan is significantly advancing understanding of epigenetic targets for these debilitating conditions.
- Autoimmune Diseases:Epigenetic drugs are being investigated for their potential to modulate immune responses and reduce inflammation in conditions such as rheumatoid arthritis.
- Infectious Diseases:This area examines how epigenetic mechanisms can be targeted to combat viral or bacterial infections and improve host immunity.
- Metabolic Disorders:Epigenetic interventions are explored for conditions like type 2 diabetes, focusing on gene expression regulation related to metabolism.
- Rare Genetic Conditions:This segment includes the application of epigenetic therapies to correct gene expression defects in rare inherited disorders.
Oncology remains the largest application segment, with Neurological Disorders expanding most quickly.
End User:
The diverse landscape of end-users reflects the broad adoption of epigenetic technologies across research and clinical settings.
- Pharmaceutical Companies:These entities are the primary developers and manufacturers of epigenetic drugs, investing heavily in research, clinical trials, and commercialization. Their demand for diagnostic technologies supports companion diagnostic development.
- Clinical Laboratories:These facilities conduct diagnostic testing for epigenetic biomarkers, providing crucial information for patient stratification and treatment monitoring. Their role is expanding with the growth of personalized medicine.
- Research Institutes:Academic and government-funded research centers drive fundamental discoveries in epigenetics, exploring new targets and mechanisms.
- Diagnostic Centers:Specialized centers offer advanced epigenetic testing services for various diseases, supporting clinical decision-making.
- Biotech Startups:Innovative smaller firms focus on novel epigenetic targets, often collaborating with larger pharmaceutical companies for development and scale-up.
- Academic Institutions:Universities contribute significantly to basic epigenetic research and the training of future scientists and clinicians.
Pharmaceutical Companies constitute the primary end-user segment, with Biotech Startups demonstrating significant growth.
Delivery Mode:
Differentiation in delivery mode addresses varying clinical needs and diagnostic requirements for epigenetic products.
- Oral:Oral administration offers patient convenience and is a preferred route for many therapeutic epigenetic drugs, facilitating long-term treatment adherence. This mode is favored for systemic effects and ease of use in outpatient settings.
- Injectable:Injectable methods, including subcutaneous and intramuscular routes, are used for drugs requiring precise dosing or those with poor oral bioavailability. This delivery is common for biologics and certain targeted therapies in clinical practice.
- Topical:Topical applications are being explored for localized epigenetic therapies, particularly in dermatological conditions or certain types of superficial cancers.
- Intravenous:Intravenous delivery ensures rapid systemic distribution and is often employed for acute conditions or when high drug concentrations are needed.
- Point-of-Care Testing:These diagnostic methods provide rapid results at or near the patient, enabling quicker clinical decisions regarding epigenetic biomarkers.
- Laboratory-Based Testing:Traditional laboratory methods offer high sensitivity and specificity for complex epigenetic analyses, often requiring specialized equipment and expertise.
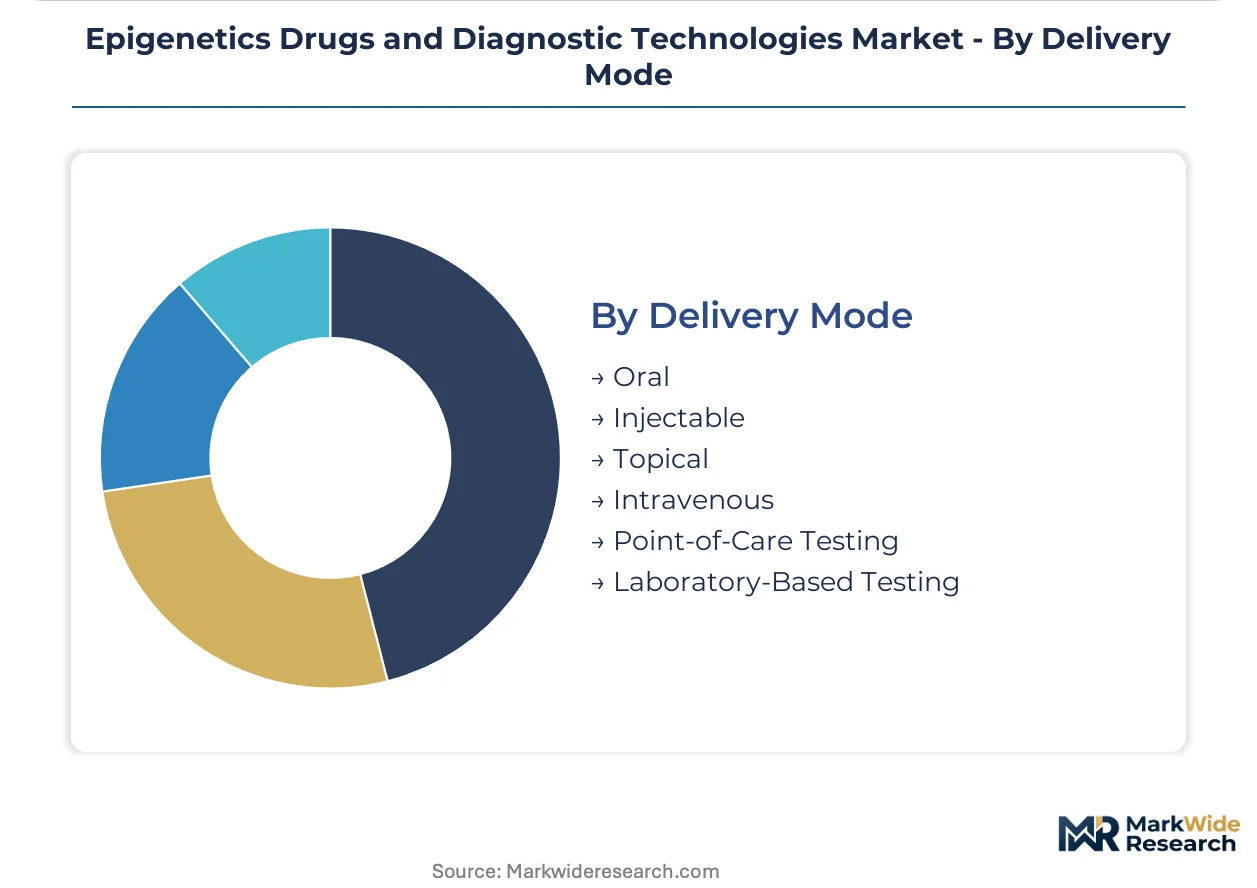
Oral formulations lead the therapeutic delivery segments, while Point-of-Care Testing is gaining considerable traction in diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive research infrastructure and high healthcare spending in developed economies underwrite significant advancements in epigenetics. These regions, particularly the United States, Germany, and Japan, drive innovation in both therapeutic development and diagnostic technologies. Emerging markets like China and India are rapidly expanding their capabilities, supported by evolving regulatory frameworks and increasing investment in advanced healthcare solutions.
United States
Strong demand for novel oncology treatments and personalized medicine approaches fuels the epigenetics market in the United States. The United States FDA's accelerated approval pathways facilitate faster market entry for innovative epigenetic drugs. Major biotech clusters like Boston and San Francisco continue to attract significant venture capital, fostering a dynamic ecosystem for epigenomic research and development.
Germany
Germany's robust academic research base and strong pharmaceutical industry support the development of histone deacetylase inhibitors and other epigenetic modifiers. The European Medicines Agency (EMA) provides regulatory oversight, ensuring high standards for drug approval. Cities like Munich and Heidelberg are renowned for their biomedical research institutes, contributing significantly to epigenetic biomarker discovery.
Japan
Advancements in neurodegenerative disorder research and a growing elderly population create specific demand for epigenetic interventions in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates drug development, emphasizing safety and efficacy for novel therapies. Tokyo and Kyoto serve as key centers for genomic and epigenomic research, driving innovation in diagnostic assays.
China
China's expanding healthcare expenditure and a large patient population drive the adoption of advanced epigenetic diagnostic technologies and drugs. The NMPA's evolving guidelines for innovative therapies influence market entry strategies for multinational firms. Shanghai and Beijing are emerging as significant hubs for biotechnology, with substantial investment in precision medicine initiatives.
India
Increasing incidence of cancer and a focus on affordable healthcare solutions stimulate interest in epigenetic drugs and diagnostics in India. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical products, aiming to streamline approval processes for essential medicines. Hyderabad and Bangalore are growing as centers for pharmaceutical manufacturing and clinical research, supporting local and international collaborations.
Epigenetics Drugs and Diagnostic Technologies Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical reagents and sequencing technologies. The market features a blend of large pharmaceutical companies, specialized diagnostic firms, and innovative biotech startups. Key strategic archetypes include integrated pharma-diagnostics providers and pure-play technology enablers. Strategic partnerships and portfolio diversification are dominant competitive moves among participants.
Within the integrated solutions archetype, Hoffmann-La Roche Ltd. and Novartis AG exemplify companies leveraging dual strengths in pharmaceuticals and diagnostics. Illumina, Inc. represents the technology enabler archetype, providing essential sequencing platforms for epigenetic biomarker discovery. These companies occupy positions across the value chain, from drug development to diagnostic assay provision, shaping the industry's direction.
| Leading Market Players |
|---|
| Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| Eisai Co., Ltd. |
| Novartis AG |
| Illumina, Inc. |
| Merck KGaA |
| QIAGEN |
| Abcam Limited |
| Promega Corporation |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly around FDA and EMA approvals, determine pricing tier spreads for novel epigenetic drugs and influence the global supply chain's specialized manufacturing footprint. This stringent oversight ensures product quality but limits market entry and concentrates production.
Pricing Analysis
Volume-discount tiering structures characterize the pricing of epigenetic diagnostic assays, while value-based pricing models apply to novel therapeutic drugs. Price differentiation stems from regulatory approval status, such as FDA clearance, and the level of customization for companion diagnostic development. Pricing softness emerges in established therapeutic compounds as competition from biosimilars increases. Pharmaceutical companies and advanced clinical centers demonstrate lower price sensitivity for innovative therapies, whereas smaller research institutes prioritize cost-effectiveness for routine assays.
Supply Chain Analysis
Upstream feedstock for epigenetic drugs and diagnostic reagents relies heavily on specialized chemical manufacturers and biotechnology suppliers. Geographic supply concentrates in China for active pharmaceutical ingredients and in the United States for advanced sequencing components. The supply chain faces single-source vulnerability for highly specialized enzymes and oligonucleotides critical for epigenetic assays. Distribution runs through direct sales channels for high-value therapeutic agents and a network of specialized distributors for diagnostic kits and research reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epigenetics market is in a cyclical recovery phase, driven by renewed investment in oncology research and accelerated regulatory pathways. This resurgence follows periods of high R&D investment and subsequent clinical trial challenges.
For Market Incumbents: Insulate core therapeutic franchises through strategic pipeline diversification into non-oncology indications, such as neurodegenerative disorders. Consolidate market share by acquiring innovative diagnostic startups to counter emerging entrant archetypes in biomarker discovery. Invest in advanced bioinformatics R&D to mitigate the talent shortage and improve target identification. Strengthen intellectual property portfolios to defend against litigation risks from overlapping patent landscapes.
For New Entrants and Emerging Players: Establish a beachhead in companion diagnostics development, focusing on integrated solutions for niche cancer indications. Target underpenetrated non-oncology segments like autoimmune diseases with novel epigenetic modifiers. Leverage academic partnerships for early-stage biomarker validation, providing a cost-effective go-to-market angle. Focus on developing platform technologies that offer superior resolution in epigenomic analysis to gain a competitive edge.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors innovative biotech startups with strong intellectual property in novel epigenetic targets. Long-term viability over a 5-10 year window is robust, supported by expanding therapeutic pipelines and diagnostic integration. An ideal acquisition target archetype would be a specialized firm with validated epigenetic biomarker assays or a unique delivery mechanism. The signal to watch is the successful completion of Phase III clinical trials for non-oncology epigenetic therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates the approval of novel epigenetic drugs for unmet medical needs in oncology and neurological disorders. |
| Platform Integration | Combines diagnostic technologies with therapeutic development, enabling personalized medicine approaches for patient stratification. |
| Pipeline Diversification | Expands the application of epigenetic modifiers beyond oncology into autoimmune and neurodegenerative conditions. |
| Strategic Partnership | Leverages complementary strengths between pharmaceutical companies and diagnostic firms for integrated product development. |
| Regulatory Approval Pathway | Utilizes accelerated programs like FDA's breakthrough designation to expedite market entry for innovative therapies. |
Research Approach
A spread of perspectives from drug development executives, regulatory affairs leads, clinical laboratory directors, and academic researchers converged on the working assumptions for this study. This approach combined extensive primary interviews with rigorous secondary validation from sources including FDA filings, EMA submissions, and scientific literature databases. Bottom-up data aggregation and top-down market sizing ensured comprehensive coverage and accuracy.
The demand-supply balance for epigenetic drugs and diagnostics formed the core of the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, therapy area, end-user, delivery mode, and regional regulatory landscapes. Compound annual growth rates were derived from historical trends and projected market dynamics. Forecast inputs included clinical trial success rates and evolving biomarker discovery technologies.
Macroeconomic conditions sit as an overlay; deviation in healthcare spending or research funding would shift the trajectory of market expansion. Forecasts reflect assumptions documented through expert consensus and historical performance. Cross-checking against national health expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Mexico Diabetes Drugs Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Vaginal Ring Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Intranasal Migraine Drugs Market