
 Glucagon-Like Peptide-1 (GLP-1) Agonists Market | 2026-2036
Glucagon-Like Peptide-1 (GLP-1) Agonists Market Size, Share, and Industry Trends Forecast 2026-2036
Glucagon-Like Peptide-1 (GLP-1) Agonists Market Foresight
The boundary between diabetes treatment and weight management is collapsing as employer health plans and direct-to-consumer channels absorb GLP-1 volumes once reserved for endocrinology practices. Novo Nordisk A/S dominates the semaglutide segment through manufacturing scale and vertical control over active pharmaceutical ingredient supply. Eli Lilly and Company differentiates via dual GIP/GLP-1 receptor agonist technology leadership. Sanofi competes through established primary care channel relationships across European reimbursement systems.
Glucagon-Like Peptide-1 (GLP-1) Agonists are incretin-mimetic biologic compounds that activate GLP-1 receptors to stimulate glucose-dependent insulin secretion, with semaglutide demonstrating 14-16% mean body weight reduction in phase 3 obesity trials. The therapy area segmentation reveals obesity management as the fastest-expanding indication pool, while type 2 diabetes retains the largest absolute prescription volume. Delivery mode innovation concentrates in pen injectors and oral tablets, where patient adherence data drives payer preference and formulary positioning.
FDA, EMA, and the EU MDR framework collectively shape GLP-1 market access through divergent requirements for cardiovascular outcome data and manufacturing inspection protocols. The EU AI Act and GDPR impose emerging constraints on real-world evidence collection methods used for post-market surveillance. Stakeholders must monitor reimbursement recalibration by Germany's G-BA and CMS coverage determinations as expanded indications strain existing pricing frameworks.
Market Dynamics
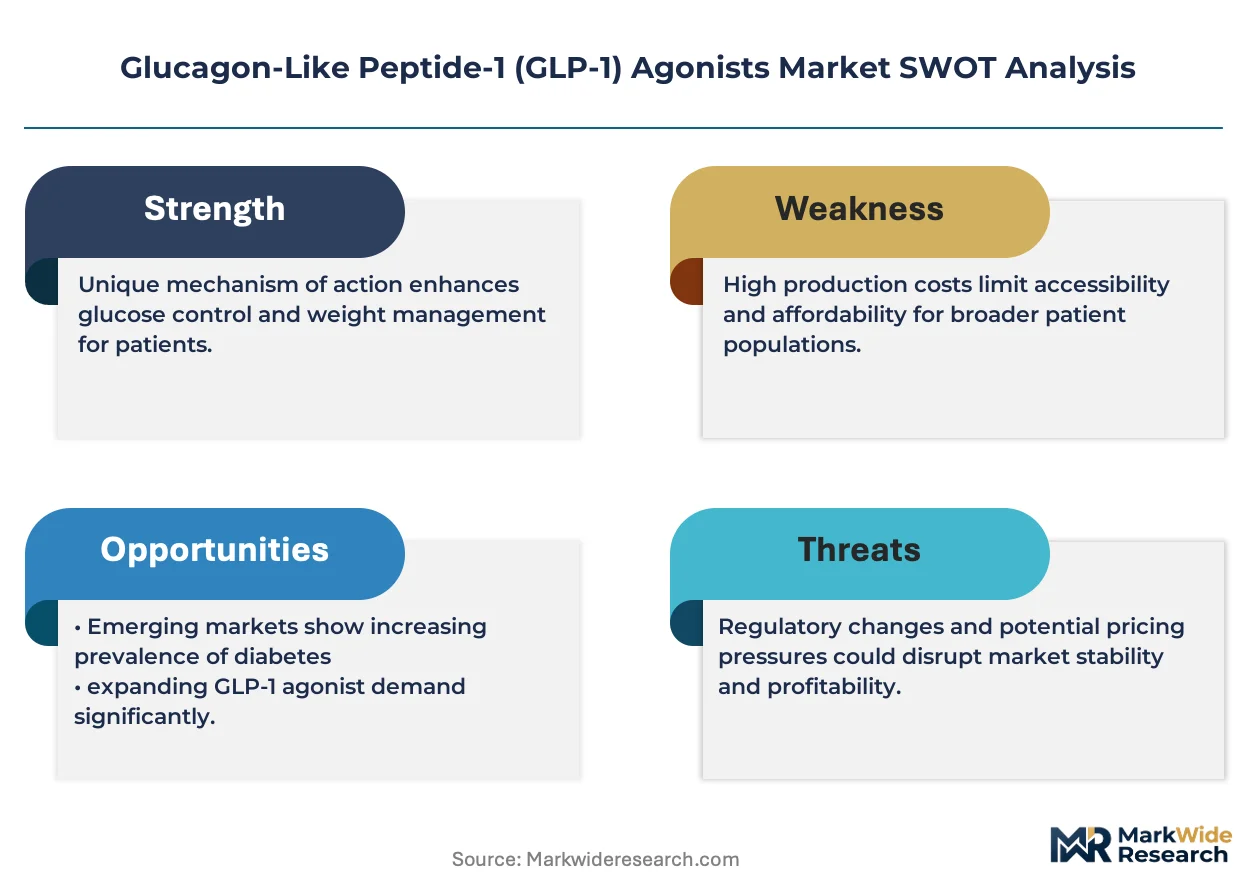
Employer health plans and direct-to-consumer channels are collapsing the historical boundary between diabetes treatment and weight management, redirecting prescription volumes away from endocrinology practices and forcing reimbursement frameworks to recalibrate around obesity indications.
Growth Catalysts
- Cardiovascular outcome data requirements:FDA and EMA accelerated review pathways compress product entry timelines for therapies demonstrating heart risk reduction, expanding addressable patient pools beyond glycemic control.
- Specialty clinic expansion:Obesity-focused medical practices in the United States are scaling GLP-1 prescribing capacity through nurse practitioner delegation and telehealth protocols.
- Active pharmaceutical ingredient supply:Captive fermentation capacity and peptide synthesis capabilities in Denmark and Ireland secure manufacturing continuity for high-volume semaglutide production.
Market Restraints
- Peptide manufacturing concentration:Fermentation-based production of GLP-1 analogs depends on a limited supplier base in Northern Europe, creating single-source vulnerability for fill-finish operations.
- Reimbursement ceiling pressure:Germany's G-BA benefit assessment protocols and CMS national coverage determinations impose pricing constraints as obesity indications strain existing therapeutic cost frameworks.
- Oral bioavailability limitations:Current tablet formulations require high peptide loads and absorption enhancers, constraining dose flexibility relative to subcutaneous delivery systems.
Strategic Opportunities
- Japanese metabolic disease market:PMDA regulatory pathways for obesity therapies remain underpenetrated relative to diabetes indications, creating first-mover positioning for indication expansion.
- Dual incretin receptor targeting:Convergence of GIP and GLP-1 agonist mechanisms enables differentiated efficacy profiles for patients with inadequate response to single-pathway therapy.
- Employer direct contracting:Self-insured corporations in the United States are establishing carve-out pharmacy arrangements for obesity management, bypassing traditional payer formularies.
Industry Challenges
- Peptide chemistry workforce scarcity:Fermentation scale-up and solid-phase synthesis expertise concentrates among specialists in Denmark and Switzerland, constraining manufacturing expansion timelines.
- Post-market surveillance complexity:EU AI Act and GDPR constraints on real-world evidence collection methods complicate pharmacovigilance for cardiovascular outcome confirmation.
- Cold chain distribution integrity:Temperature-sensitive biologics require validated logistics infrastructure that fragments across last-mile pharmacy networks in rural United States regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucagon-Like Peptide-1 (GLP-1) Agonists Market |
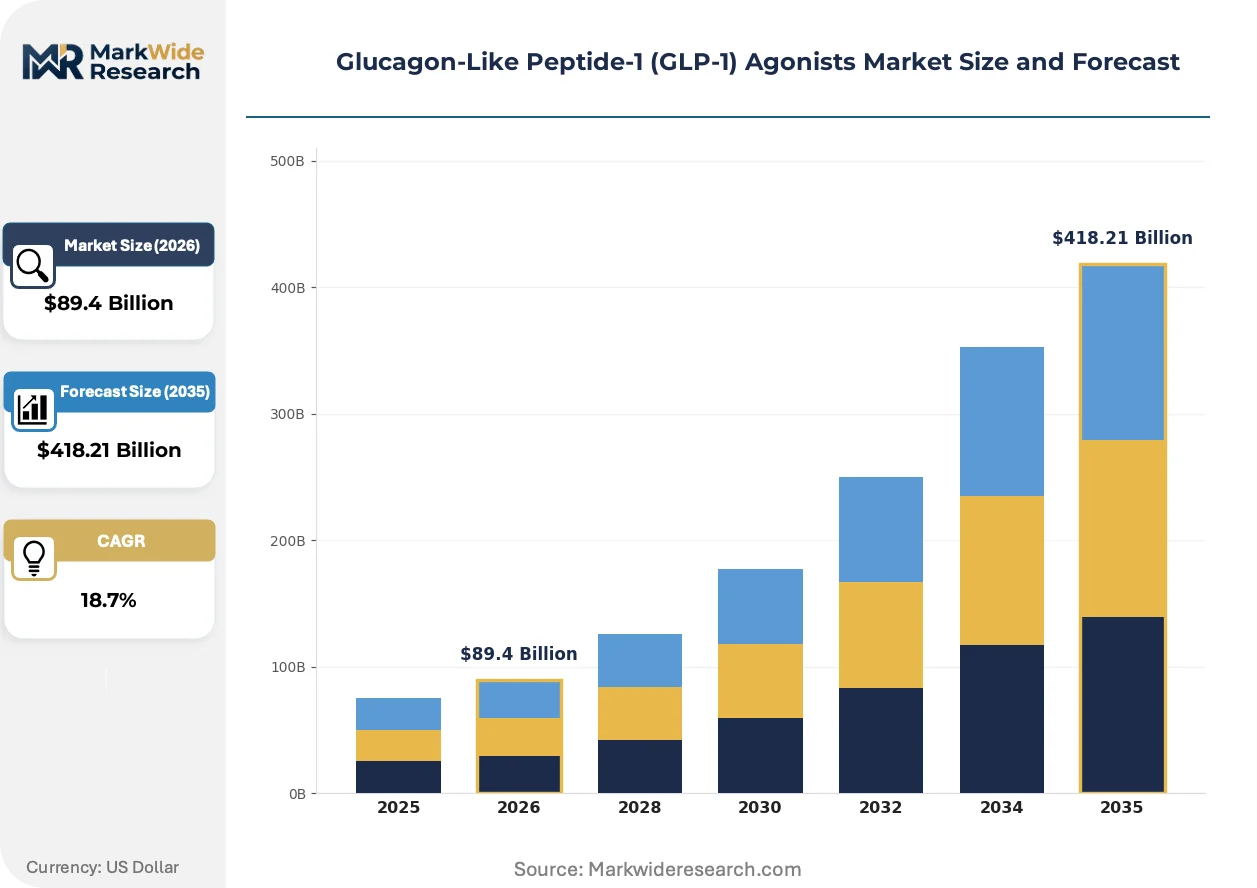
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $418.21 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exenatide, Liraglutide, Dulaglutide, Semaglutide, Albiglutide Therapy Area: Type 2 Diabetes, Obesity Management, Cardiovascular Risk Reduction, Non-Alcoholic Fatty Liver Disease End User: Specialty Clinics, Primary Care Providers, Hospitals, Diabetes Centers Delivery Mode: Subcutaneous Injection, Oral Tablets, Pen Injectors, Extended-Release Formulations |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, AstraZeneca, Pfizer Inc., Boehringer Ingelheim, Teva Pharmaceutical Industries Ltd., Glenmark Pharmaceuticals Limited, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucagon-Like Peptide-1 (GLP-1) Agonists Market Shifts & Advancements
Delivery mode innovation and regulatory data requirements are restructuring competitive positioning around patient adherence metrics and cardiovascular outcome demonstration, compressing differentiation timelines for new entrants.
Oral tablet formulations using absorption enhancer technology are decomposing the historical monopoly of pen injectors in GLP-1 therapy. Patient preference studies from United States employer health plans indicate switching intent toward non-injectable options exceeding 40% among treatment-naïve populations. This shift is decomposing reimbursement negotiating leverage for established injectable portfolios and forcing formulary managers to weight adherence data more heavily in tier placement decisions.
EMA's MDR framework and FDA's accelerated approval pathways for cardiovascular risk reduction are diverging on evidentiary standards for obesity indications. The European requirement for pre-approval outcome trials extends development timelines by 18-24 months relative to US pathways. Manufacturers are responding with parallel trial designs that satisfy both jurisdictions, increasing clinical program complexity and capital requirements.
Direct-to-consumer telehealth platforms are capturing prescription initiation for obesity management, displacing traditional endocrinology referrals in the United States. These channels unbundle diagnosis from longitudinal care, creating fragmentation in medication monitoring and side-effect management. The shift is most visible among employed populations aged 35-50, where employer-sponsored wellness programs integrate pharmacy benefit carve-outs with virtual provider networks.
Glucagon-Like Peptide-1 (GLP-1) Agonists Market Segmentation
GLP-1 agonist prescribing patterns fragment sharply across clinical settings and delivery technologies, with reimbursement pathways and patient adherence profiles determining which segments absorb volume shifts from traditional diabetes care.
Product Type:
Substitution pressure intensifies around peptide stability and dosing frequency, with once-weekly formulations displacing older twice-daily injectables in formulary negotiations.
- Semaglutide:Long-acting peptide analog with 94% sequence homology to native GLP-1 and albumin-binding half-life extension. Demand concentrates in United States employer health plans seeking cardiovascular risk reduction bundled with weight management outcomes. Manufacturing scale constraints in Denmark limit supply elasticity despite fermentation capacity expansions.
- Liraglutide:Acylated GLP-1 analog requiring daily subcutaneous administration with established pediatric obesity labeling. European reimbursement systems in Germany and France retain volume for patients with prior authorization barriers to weekly alternatives. Patent expiry timelines accelerate biosimilar development investments.
- Dulaglutide:Fusion protein construct linking GLP-1 to human Fc fragment for extended circulation.
- Exenatide:Synthetic exendin-4 derivative available in immediate and extended-release depot formulations.
- Albiglutide:Albumin-fused GLP-1 construct with reduced immunogenicity profile in comparative trials.
Semaglutide anchors the volume base while liraglutide gains share at the steepest rate in European markets with restrictive prior authorization frameworks.
Therapy Area:
Cost tier stratification separates chronic disease management from preventive metabolic intervention, with obesity indications commanding premium pricing despite overlapping molecular mechanisms.
- Obesity Management:Indication expansion beyond BMI thresholds toward metabolic syndrome clustering, with semaglutide demonstrating 14-16% mean body weight reduction in phase 3 trials. United States direct-to-consumer telehealth channels capture prescription initiation for employed populations aged 35-50, bypassing traditional endocrinology referral pathways.
- Type 2 Diabetes:Established glycemic control indication with HbA1c reduction endpoints and cardiovascular outcome trial requirements. Medicare and Medicaid formularies in the United States maintain volume concentration despite indication creep toward weight management.
- Cardiovascular Risk Reduction:FDA and EMA divergent evidentiary standards for pre-approval outcome trials.
- Non-Alcoholic Fatty Liver Disease:Emerging indication with histologic endpoint requirements and biopsy-dependent trial designs.
Type 2 diabetes anchors the volume base while obesity management climbs the fastest as employer health plans absorb prescription volumes previously channeled through diabetes centers.
End User:
Customer type stratification reflects delegation authority expansion, with nurse practitioners and telehealth protocols capturing prescription initiation previously reserved for specialist consultation.
- Specialty Clinics:Obesity-focused medical practices scaling GLP-1 prescribing capacity through protocolized nurse practitioner delegation and remote monitoring infrastructure. United States metropolitan clusters in Texas and Florida concentrate new clinic formation tied to direct-to-employer contracting arrangements.
- Primary Care Providers:Generalist physicians managing metabolic syndrome presentations with simplified dosing regimens and cardiovascular outcome data supporting prescribing confidence.
- Hospitals:Inpatient initiation for decompensated diabetes with transition-of-care protocols to outpatient settings.
- Diabetes Centers:Academic medical center-affiliated programs with endocrinology fellowship training and clinical trial access.
Specialty clinics anchor the volume base while primary care providers expand most quickly as simplified dosing protocols reduce specialist dependency.
Delivery Mode:
Supply concentration in pen injector manufacturing creates differentiation opportunities for oral formulations targeting injection-averse patient populations.
- Pen Injectors:Multi-dose disposable devices with dose-titration click mechanisms and hidden-needle designs reducing injection anxiety. Patient adherence data from United States pharmacy benefit managers demonstrates superior persistence versus vial-and-syringe alternatives, driving formulary tier preference.
- Oral Tablets:Semaglutide absorption enhancer technology using sodium N-[8-(2-hydroxybenzoyl)amino] caprylate to enable gastric permeation. Patient preference studies indicate switching intent exceeding 40% among treatment-naïve populations in employer-sponsored wellness programs.
- Subcutaneous Injection:Vial-based administration requiring syringe drawing and angle-controlled delivery technique.
- Extended-Release Formulations:Polymeric microsphere depot technologies enabling monthly or quarterly dosing intervals.
Pen injectors anchor the volume base while oral tablets gain share at the steepest rate as adherence data reshapes payer tier placement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain logistics infrastructure underwrites Northern Europe's role in temperature-sensitive biologics distribution, connecting Danish fermentation facilities to German and French pharmacy networks.
United States
Employer-sponsored wellness programs and direct-to-consumer telehealth platforms absorb prescription volumes for obesity management. FDA accelerated approval pathways for cardiovascular outcome data compress product entry timelines. Texas and Florida metropolitan clusters concentrate specialty clinic formation tied to employer carve-out pharmacy arrangements.
Germany
G-BA benefit assessment protocols impose pricing constraints as obesity indications strain therapeutic cost frameworks. EMA MDR framework requirements for pre-approval outcome trials extend development timelines. The Rhine-Ruhr region anchors distribution networks serving statutory health insurance formularies across Western Europe.
Japan
PMDA regulatory pathways for obesity therapies remain underpenetrated relative to diabetes indications. METI industrial policy supports domestic peptide manufacturing capacity expansion. The Kanto region around Tokyo concentrates metabolic disease research institutions and clinical trial sites.
Denmark
Captive fermentation capacity and peptide synthesis capabilities secure manufacturing continuity for high-volume semaglutide production. EU AI Act constraints on real-world evidence collection complicate post-market surveillance. The Copenhagen-Kalundborg corridor anchors active pharmaceutical ingredient supply chains serving global fill-finish operations.
United Kingdom
NICE technology appraisal processes determine reimbursement access for GLP-1 therapies within the National Health Service. MHRA post-Brexit regulatory divergence creates parallel submission requirements. The Greater London area concentrates obesity-focused private medical practices and direct-pay prescription channels.
Glucagon-Like Peptide-1 (GLP-1) Agonists Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and channel access dimensions. The market structure consolidates around vertically integrated fermentation specialists and diversified pharmaceutical conglomerates with primary care reach. Three archetypes dominate: captive API producers with Danish or Irish manufacturing bases, dual-incretin technology developers, and primary care channel specialists leveraging European reimbursement relationships. Competitive moves concentrate on manufacturing capacity expansion and indication expansion through cardiovascular outcome trials.
Within the captive production archetype, Novo Nordisk A/S and Eli Lilly and Company exemplify contrasting scale strategies. Novo Nordisk A/S occupies a position anchored to Northern European fermentation infrastructure. Eli Lilly and Company represents the diversified conglomerate model with dual GIP/GLP-1 receptor technology positioning. Sanofi sits within the primary care channel specialist tier, leveraging established relationships across European reimbursement systems.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Pfizer Inc. |
| Boehringer Ingelheim |
| Teva Pharmaceutical Industries Ltd. |
| Glenmark Pharmaceuticals Limited |
| Amgen |
| Others |
Supply & Pricing Matrix
Ninety-day fermentation cycle times for peptide active pharmaceutical ingredients create inventory positions that directly translate into pricing leverage for Danish and Irish manufacturing clusters serving global fill-finish networks. This lead-time rigidity concentrates contract negotiation power among vertically integrated producers while exposing buyers to allocation risk during demand surges.
Pricing Analysis
Volume-discount tiering structures separate employer-sponsored carve-out arrangements from statutory health insurance formularies and direct-to-consumer telehealth channels. Price differentiation reflects cardiovascular outcome data availability and manufacturing scale rather than molecular novelty alone. Cost compression in European reimbursement systems intensifies as Germany's G-BA recalibrates benefit assessments for obesity indications. Self-insured corporations in the United States demonstrate lowest price sensitivity due to bundled wellness program budgets, while Medicaid formularies face strict prior authorization constraints.
Supply Chain Analysis
Just-in-time inventory strategies dominate among United States specialty clinic networks, while strategic stockpiling characterizes Japanese and German distributor arrangements for temperature-sensitive biologics. Geographic supply concentration centers on Denmark for fermentation-based peptide synthesis and Ireland for fill-finish operations, with secondary capacity emerging in Switzerland. Raw material dependencies include recombinant yeast strains, chromatography resins, and borosilicate glass for pen injector cartridges. Single-source vulnerability in Northern European fermentation capacity creates structural exposure to regulatory inspection delays. Distribution runs through validated cold chain networks connecting Copenhagen-Kalundborg production corridors to regional pharmacy hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where cardiovascular outcome trial requirements and manufacturing inspection protocols create switching costs that protect incumbent positions against rapid displacement.
For Market Incumbents: Compound manufacturing scale advantages through captive fermentation capacity additions in Denmark and backward integration into peptide synthesis raw materials. Threats from dual-incretin receptor competitors and oral bioavailability innovations demand accelerated cardiovascular outcome data generation to maintain formulary tier preference. Channel control through direct-to-employer contracting arrangements represents the critical defensive lever against telehealth platform disintermediation. For New Entrants and Emerging Players: Post-market surveillance data services present a service-layer gap where incumbents under-serve European pharmacovigilance requirements under EU AI Act constraints. White-space targets include Japanese obesity indication expansion and real-world evidence collection platforms for cardiovascular outcome confirmation. Employer-sponsored wellness programs in Texas and Florida metropolitan clusters offer the most penetrable geography, with nurse practitioner delegation protocols enabling rapid prescribing capacity deployment. For Investors and Strategic Acquirers: Long-term, this sits as a manufacturing-moat play because fermentation expertise and regulatory inspection history compound defensively over decades rather than quarters. Acquisition targets should concentrate on peptide chemistry workforce specialists in Switzerland and Denmark, or dual-incretin technology platforms with differentiated receptor binding profiles. The signal to watch is CMS national coverage determination recalibration for obesity indications, which would trigger reimbursement tier restructuring across employer and public payer segments.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | FDA and EMA accelerated review pathways compress product entry timelines for heart risk reduction therapies. |
| Manufacturing Scale-Up in Northern Europe | Captive fermentation capacity in Denmark secures supply continuity for high-volume semaglutide production. |
| Dual Incretin Receptor Technology Development | Convergence of GIP and GLP-1 mechanisms enables differentiated efficacy for inadequate single-pathway responders. |
| Direct-to-Employer Contracting Arrangement | Self-insured corporations establish carve-out pharmacy agreements bypassing traditional payer formularies. |
| Oral Formulation Absorption Enhancer Investment | Sodium N-[8-(2-hydroxybenzoyl)amino] caprylate technology decomposes pen injector market dominance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases through structured interviews with drug development executives, regulatory affairs leads, payer access specialists, and hospital procurement managers. Bottom-up prescription volume modeling triangulates against top-down market sizing derived from manufacturing capacity disclosures and import-export trade flows.
Segmentation dimensions modeled include therapy area stratification, delivery mode technology, end-user clinical setting, and regional regulatory cluster across the projection horizon. CAGRs derive from patient population epidemiology, indication expansion timelines, and reimbursement pathway probability-weighting. Forecast inputs incorporate cardiovascular outcome trial readout schedules and manufacturing capacity expansion announcements from Danish and Irish production facilities.
Underlying assumptions cover FDA and EMA regulatory pathway convergence, with deviation risk concentrated in CMS national coverage determination recalibration and EU AI Act enforcement patterns for real-world evidence collection. Revision becomes warranted when employer-sponsored wellness program adoption crosses threshold penetration in United States metropolitan clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Global Meningitis Vaccine Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Adapalene Market