
 RAS-Acting Agents Market | 2026-2036
RAS-Acting Agents Market Size, Share, and Industry Trends Forecast 2026-2036
RAS-Acting Agents Market Analytics
Targeted protein degradation is fragmenting the traditional small-molecule paradigm for RAS inhibition, forcing developers to rebuild discovery platforms around molecular glue and PROTAC architectures. Merck & Co. leverages its oncology infrastructure to advance combination regimens pairing RAS inhibitors with checkpoint blockade. Bristol-Myers Squibb anchors its position through deep investment in covalent KRAS inhibitor chemistry. Novartis competes by extending its radioligand therapy expertise toward RAS-driven tumor targeting.
RAS-acting agents comprise therapeutic modalities designed to interrupt oncogenic signaling through direct binding to mutant RAS proteins, indirect suppression of downstream effectors such as MEK or PI3K, or disruption of protein-protein interactions essential for RAS membrane localization; covalent inhibitors of the KRAS G12C mutant exemplify the direct approach, achieving sustained target engagement through irreversible binding to the switched-II pocket. Small molecules occupy the mature commercial tier, with KRAS G12C inhibitors generating the majority of near-term revenue. Monoclonal antibodies represent the fastest-growing segment, as bispecific formats against RAS-effector interfaces advance through early clinical stages. Peptide therapies concentrate margin pools in niche indications where oral bioavailability constraints prove less limiting.
FDA breakthrough therapy and fast track designations compress development timelines for RAS-targeted drugs, while EMA's PRIME scheme accelerates European access assessments. The FDA's Project Optimus is reshaping dose-selection paradigms for these agents, pushing developers toward pharmacodynamically guided regimens rather than maximum tolerated dose strategies. Stakeholders must monitor emerging resistance mechanisms, including secondary KRAS mutations and compensatory pathway activation, as these will determine the durability of first-generation inhibitors and the urgency of next-wave combination approaches.

Market Dynamics
Targeted protein degradation architectures are fragmenting the established small-molecule paradigm for RAS inhibition, forcing pharmaceutical developers to rebuild discovery platforms around molecular glue and PROTAC chemistries rather than conventional covalent binding strategies.
Growth Catalysts
- FDA Project Optimus:The initiative mandates pharmacodynamically guided dose-selection for oncology agents, replacing maximum tolerated dose strategies with biomarker-driven regimens that accelerate clinical validation of RAS inhibitors.
- Academic medical centers:NCI-designated cancer centers in the United States drive early adoption of KRAS G12C inhibitors through investigator-initiated trials and expanded access programs that generate real-world efficacy data.
- Dual radioligand-covalent inhibitor platforms:Convergence of targeted radiotherapy with direct RAS binding enables simultaneous tumor visualization and therapeutic intervention, compressing diagnostic-therapeutic timelines for solid malignancies.
Market Restraints
- Secondary resistance mutations:Tumor evolution generates compensatory KRAS alterations and parallel pathway activation that erode durability of first-generation G12C inhibitors, necessitating costly combination development.
- Peptide bioavailability constraints:Oral delivery limitations for macrocyclic RAS binders restrict administration to intravenous or subcutaneous routes, narrowing addressable patient populations relative to small-molecule alternatives.
- Membrane localization complexity:RAS proteins require post-translational modification and proper subcellular trafficking for oncogenic function, creating formulation challenges that extend preclinical timelines for indirect targeting approaches.
Strategic Opportunities
- Undruggable mutant expansion:KRAS G12D and G12V mutations, prevalent in pancreatic and colorectal adenocarcinomas, lack approved targeted therapies and represent substantial unmet need for next-generation allosteric inhibitors.
- Checkpoint blockade pairing:Immunotherapy combination regimens with RAS inhibitors exploit tumor antigen release from targeted cell death, creating synergistic efficacy signals that differentiate pipeline assets.
- Japan's Sakigake designation:The PMDA's early approval pathway for innovative pharmaceuticals compresses review timelines for first-in-class RAS agents, enabling accelerated commercialization in the world's third-largest oncology market.
Industry Challenges
- Cryo-EM structural biology capacity:Rational design of RAS-effector disruptors demands high-resolution protein complex visualization that exceeds available academic and contract research infrastructure.
- Companion diagnostic co-development:Parallel validation of tissue-based and circulating tumor DNA assays for mutant allele detection introduces regulatory coordination complexity and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RAS-Acting Agents Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Monoclonal Antibodies, Peptide Therapies, Combination Therapies End User: Pharmaceutical Companies, Research Institutions, Hospitals, Specialty Clinics Therapy Area: Cancer, Cardiovascular Disorders, Autoimmune Diseases, Infectious Diseases Administration Route: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb Company, Novartis AG, Daiichi Sankyo Company Limited, Boehringer Ingelheim GmbH, Pfizer Inc., Sanofi S.A., Johnson & Johnson, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RAS-Acting Agents Market Evolving Landscape
Biopharmaceutical innovation in RAS targeting is converging on three vectors: degradation chemistry displacing occupancy-driven pharmacology, regulatory frameworks rewarding biomarker-enriched trial designs, and prescriber behavior shifting toward molecularly stratified treatment sequences.
Degrader technologies are migrating from exploratory academic programs into pharmaceutical pipelines with measurable velocity. Molecular glue and heterobifunctional PROTAC architectures enable catalytic target elimination rather than sustained binding occupancy, fundamentally altering the dose-response relationship for RAS inhibition. Bristol-Myers Squibb and AstraZeneca have established dedicated discovery units pursuing this modality, attracted by the potential to address mutant alleles lacking druggable pockets.
EMA's PRIME scheme and FDA breakthrough therapy designation are compressing development timelines for RAS-targeted agents by enabling rolling review and accelerated assessment procedures. These regulatory pathways reward sponsors that integrate biomarker stratification into pivotal trial designs, shifting competitive advantage toward developers with diagnostic co-development capabilities. European access assessments now routinely incorporate early health technology evaluation, forcing parallel payer engagement alongside scientific advice.
Oncology prescribing patterns are shifting toward molecularly sequenced regimens that position RAS inhibitors earlier in treatment algorithms. Academic medical centers in the United States increasingly mandate next-generation sequencing profiling at diagnosis, identifying actionable mutations before chemotherapy exposure and redirecting patients toward targeted trials. This behavioral change compresses the window for commercial penetration of first-generation agents before resistance mechanisms emerge.
RAS-Acting Agents Market Segmentation
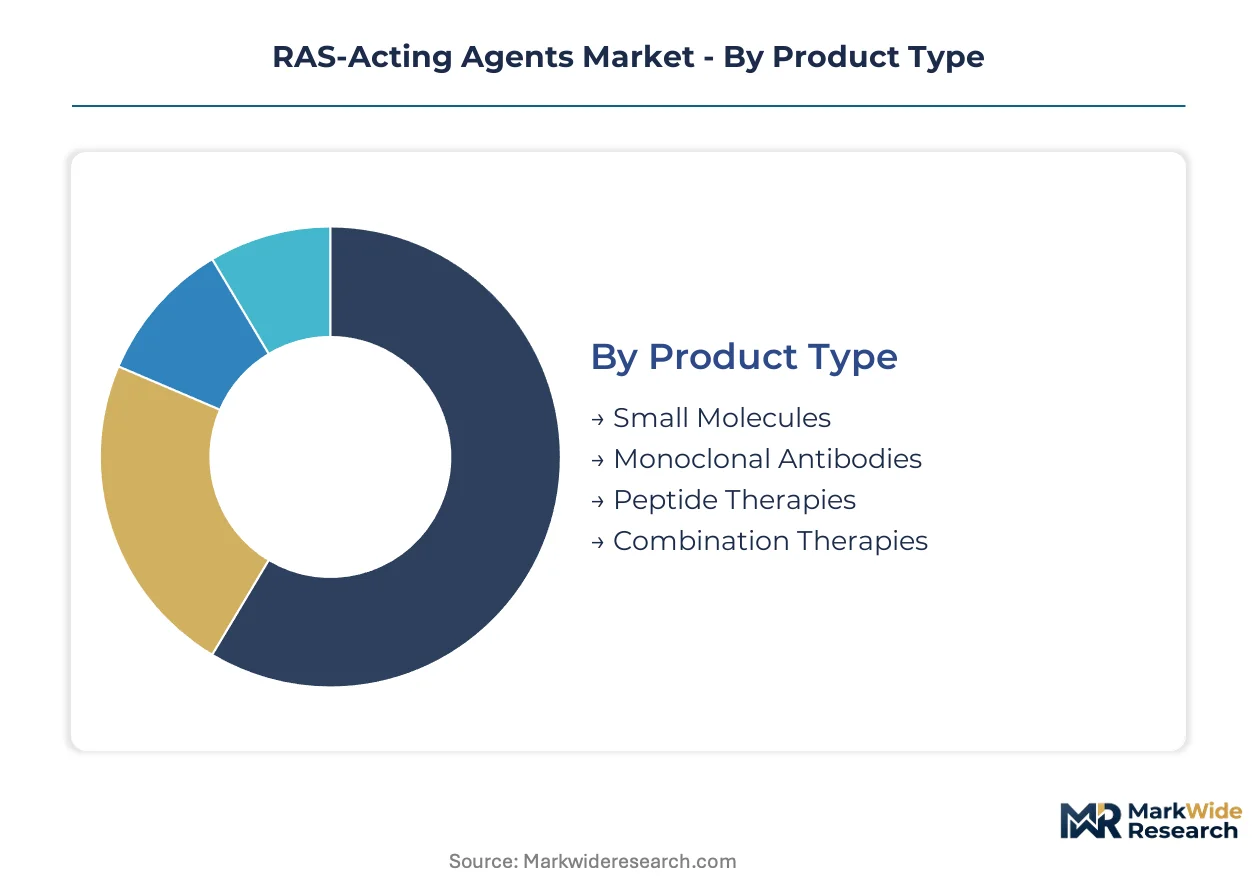
Segmentation in the RAS-acting agents market reveals how therapeutic modality, delivery setting, and disease application shape investment priorities and regulatory pathways. Distinct commercial dynamics govern each dimension, from the manufacturing scale of small molecules to the specialized infrastructure required for monoclonal antibody production.
Product Type:
Therapeutic modality determines manufacturing complexity, regulatory scrutiny intensity, and prescriber familiarity with dosing protocols.
- Small Molecules:Covalent inhibitors targeting the KRAS G12C switched-II pocket achieve sustained target engagement through irreversible binding. Demand concentrates in United States academic medical centers where oral bioavailability supports outpatient administration and expanded access programs generate real-world evidence.
- Monoclonal Antibodies:Bispecific formats against RAS-effector interfaces require sophisticated cell culture production and cold-chain distribution. The steepest expansion runs through this segment as developers advance candidates through early clinical stages with potential for broader mutant allele coverage.
- Peptide Therapies:Macrocyclic RAS binders face oral delivery constraints that restrict administration to parenteral routes.
- Combination Therapies:Regimens pairing RAS inhibitors with checkpoint blockade or downstream pathway suppression demand complex clinical trial designs.
Small molecules command the established base. The steepest expansion runs through monoclonal antibodies.
End User:
Customer type shapes procurement scale, regulatory engagement depth, and post-market surveillance obligations.
- Pharmaceutical Companies:Integrated developers pursuing RAS-targeted portfolios require bulk active pharmaceutical ingredient supply and dedicated formulation capacity for global trial networks. Bristol-Myers Squibb and AstraZeneca anchor demand through expanding oncology pipelines.
- Research Institutions:NCI-designated cancer centers drive early adoption through investigator-initiated trials that generate mechanistic insights and resistance data. United States concentration reflects NIH funding density and tissue banking infrastructure.
- Hospitals:Tertiary care centers with embedded molecular tumor boards increasingly mandate next-generation sequencing at diagnosis.
- Specialty Clinics:Community oncology practices with limited pathology integration face access barriers to biomarker-directed therapy.
Pharmaceutical companies absorb the majority of pre-commercial supply. The steepest expansion runs through research institutions.
Therapy Area:
Disease application determines addressable patient population, competitive intensity, and payer reimbursement dynamics.
- Cancer:Solid tumors with KRAS mutations—particularly non-small cell lung cancer, colorectal adenocarcinoma, and pancreatic cancer—represent the primary commercial focus. FDA breakthrough therapy designations compress development timelines for oncologic indications.
- Cardiovascular Disorders:RAS pathway involvement in cardiac hypertrophy and fibrosis creates exploratory opportunities outside oncology, though clinical validation remains preliminary.
- Autoimmune Diseases:Aberrant RAS signaling in T-cell activation supports preclinical investigation for inflammatory conditions.
- Infectious Diseases:Pathogen manipulation of host RAS pathways presents niche targeting opportunities with limited current pipeline activity.
Cancer dominates commercial investment. The steepest expansion runs through cardiovascular disorders as mechanistic understanding deepens.
Administration Route:
Delivery mechanism dictates formulation development timelines, patient compliance profiles, and healthcare setting requirements.
- Oral:Small-molecule inhibitors with adequate bioavailability enable outpatient management and reduce infusion center burden. United States demand favors oral agents where pharmacy benefit structures support take-home dispensing.
- Intravenous:Monoclonal antibodies and peptide therapies requiring precise dosing control concentrate in hospital-based infusion centers with nursing supervision.
- Subcutaneous:Alternative parenteral delivery for peptides and certain biologics offers patient convenience advantages over intravenous administration.
- Topical:Localized RAS inhibition for dermatologic applications remains exploratory with minimal current development activity.
Oral administration commands the established base. The steepest expansion runs through subcutaneous delivery as formulation technology advances.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical developers export RAS-targeted oncology compounds to European and Asian clinical trial networks, establishing trans-Atlantic and trans-Pacific supply corridors that concentrate commercialization expertise in North American headquarters while distributing manufacturing scale across contract partners in Germany and Japan.
United States
FDA breakthrough therapy designations compress development timelines for KRAS G12C inhibitors, while NCI-designated cancer centers in Boston and Houston drive early adoption through investigator-initiated trials. The NIH's National Cancer Institute funds academic research partnerships that generate mechanistic resistance data. Maryland's I-270 biotech corridor hosts multiple developers advancing covalent inhibitor chemistry toward regulatory submission.
Germany
EMA's PRIME scheme accelerates European access assessments for RAS-targeted agents entering the German market, where statutory health insurance funds negotiate reimbursement for oncology innovations. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices, coordinates parallel scientific advice with EMA. Heidelberg and Munich anchor clinical research activity through comprehensive cancer centers integrated with university hospital networks.
Japan
PMDA's Sakigake designation compresses review timelines for first-in-class RAS agents, enabling accelerated commercialization in the world's third-largest oncology market. The Ministry of Health, Labour and Welfare oversees reimbursement pricing negotiations that determine commercial viability. Tokyo and Osaka concentrate pharmaceutical R&D infrastructure, with the Kanto region hosting multiple developers pursuing combination regimens with checkpoint blockade.
United Kingdom
The Medicines and Healthcare products Regulatory Agency's innovative licensing pathway supports early access schemes for RAS inhibitors targeting unmet oncologic need. NHS England's Cancer Drugs Fund provides provisional reimbursement pending final cost-effectiveness determinations by NICE. The Golden Triangle linking London, Cambridge, and Oxford hosts biotechnology clusters advancing protein degradation architectures for previously undruggable RAS mutants.
Switzerland
Swissmedic's streamlined assessment procedures attract developers seeking rapid European market authorization for RAS-targeted therapies. The country's mandatory health insurance system ensures broad patient access to innovative oncology treatments. Basel and Zurich concentrate pharmaceutical headquarters and contract research organizations that support global clinical development programs through specialized biomarker analysis capabilities.
RAS-Acting Agents Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Large integrated pharmaceutical companies with established oncology infrastructure anchor the premium tier through direct sales forces and hospital system relationships. Mid-scale biotechnology firms occupy the innovation tier, advancing novel modalities such as molecular glue degraders and bispecific antibodies. Contract research and manufacturing organizations serve the enabling tier, providing specialized capabilities in covalent chemistry and radioligand conjugation. Dominant competitive moves include strategic partnerships combining diagnostic co-development with therapeutic assets, and geographic expansion into Japan's Sakigake pathway.
Within the integrated pharmaceutical tier, Merck & Co., Inc. and Bristol-Myers Squibb Company occupy positions representing distinct strategic archetypes. Merck exemplifies the checkpoint blockade combination approach, leveraging existing immuno-oncology infrastructure to advance RAS inhibitor pairings. Bristol-Myers Squibb represents deep covalent chemistry investment, anchoring discovery efforts around irreversible KRAS binding modalities. Novartis AG sits within the radioligand convergence archetype, extending targeted radiotherapy expertise toward RAS-driven tumor applications.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Daiichi Sankyo Company Limited |
| Boehringer Ingelheim GmbH |
| Pfizer Inc. |
| Sanofi S.A. |
| Johnson & Johnson |
| AstraZeneca plc |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient synthesis for covalent KRAS inhibitors concentrates in Switzerland and Germany, where contract manufacturers command premium pricing for GMP-certified batches that flow into Bristol-Myers Squibb and Novartis clinical supply chains. This upstream concentration places margin capture with specialized CDMOs rather than finished-dose marketers, compressing downstream pricing flexibility for developers racing to expand G12C inhibitor access.
Pricing Analysis
First-generation KRAS G12C inhibitors trade at substantial discounts to next-generation allosteric agents targeting G12D and G12V mutations still in Phase II development. The dominant model is value-based pricing tethered to progression-free survival benchmarks in biomarker-selected populations, with FDA breakthrough designation status enabling premium tiers. Price differentiation hinges on companion diagnostic bundling and orphan-drug exclusivity windows. Cost compression in the small-molecule tier is intensifying as sotorasib and adagrasib compete for formulary placement, while academic medical centers with 340B pricing access exhibit the sharpest price sensitivity.
Supply Chain Analysis
Upstream feedstock for RAS inhibitor manufacturing draws from Chinese suppliers of specialized heterocyclic intermediates, Indian producers of high-purity solvents, and German fine-chemical houses for chiral building blocks. Key dependencies include palladium catalysts for cross-coupling reactions, fluorinated reagents for switched-II pocket optimization, and isotopically labeled precursors for radioligand conjugation. Single-source vulnerability runs through Chinese intermediate suppliers subject to export licensing requirements. Distribution runs through cold-chain logistics partners serving NCI-designated cancer centers and hospital-based specialty pharmacies.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryo-EM structural biology capacity for RAS-effector complex visualization remains bottlenecked at fewer than a dozen academic facilities worldwide, creating acute scarcity for rational degrader design capabilities that will determine next-wave competitive positioning.
For Market Incumbents: Pre-empt resistance-driven revenue erosion by accelerating combination trial timelines pairing G12C inhibitors with SHP2 or SOS1 suppressors before second-generation agents reach market. Secure captive cryo-EM capacity through exclusive academic partnerships or strategic CRO alliances to defend discovery velocity against molecular glue specialists. Prioritize companion diagnostic co-development with Foundation Medicine or Guardant Health to lock biomarker-defined patient access. For New Entrants and Emerging Players: Build out peptide-macrocycle platforms for intravenous administration in pancreatic cancer, where oral bioavailability constraints matter less and G12D mutation prevalence creates addressable white space. Target Japan's Sakigake pathway for accelerated first-in-class approval, leveraging PMDA's compressed review timelines to establish commercial foothold before US/EU entrants secure reimbursement. Lead with radioligand theranostic positioning to differentiate from crowded covalent inhibitor field. For Investors and Strategic Acquirers: Capital is best deployed toward platform-stage biotechnology firms with validated PROTAC ternary complex formation against RAS mutants lacking druggable pockets, where technical de-risking has occurred but commercial scale remains unbuilt. Long-term viability over the coming decade hinges on pipeline breadth across G12D, G12V, and Q61H alleles rather than single-mutation concentration. Watch for FDA Project Optimus dose-optimization readouts as inflection indicators for regulatory receptivity to pharmacodynamically guided development.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates biomarker-enriched pivotal studies at NCI-designated cancer centers. |
| Regulatory Approval Pathway | EMA PRIME and FDA breakthrough designations compress development-to-commercialization timelines. |
| Manufacturing Scale-Up | GMP capacity expansion in Basel and Heidelberg secures clinical supply for global trial networks. |
| Pipeline Diversification | G12D and G12V allosteric programs address pancreatic and colorectal unmet need. |
| Strategic Partnership | Diagnostic co-development with liquid biopsy platforms locks companion test access. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation were cross-referenced to anchor volume and value estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by therapeutic modality, administration route, mutation subtype, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical oncology adoption patterns and biomarker penetration trajectories. Forecast inputs incorporated investigator-initiated trial enrollment velocity, resistance mechanism emergence timelines, and companion diagnostic co-approval probabilities.
Stress conditions across reimbursement denial rates, biosimilar entry timing, and radioligand manufacturing yield were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway success and biomarker test adoption. Material shifts in FDA Project Optimus implementation scope or EMA parallel assessment procedures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Advanced Therapy Medicinal Products CDMO Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Josamycin Market