
 Galculus Bovis and Metronidazole Market | 2026-2036
Galculus Bovis and Metronidazole Market Size, Share, and Industry Trends Forecast 2026-2036
Galculus Bovis and Metronidazole Market Insights
Pharmaceutical-grade bovis extract specification is unwinding legacy commodity supply chains into higher-margin therapeutic channels. Bayer AG leverages its veterinary division's R&D intensity to dominate premium tablet formulations. Sunflower Pharmaceutical Group anchors regional distribution across Chinese livestock provinces with backward integration into raw material sourcing.
Galculus Bovis and Metronidazole denotes a compounded veterinary antimicrobial combining dried bovine gallstone extract with the nitroimidazole antibiotic metronidazole, typically standardized to 0.2-0.5% bilirubin content and 20-40% metronidazole by weight for oral or parenteral administration against anaerobic bacterial and protozoal infections in bovine and companion animals. Tablets capture the largest revenue pool due to dosing convenience in farm settings, while injectable formulations represent the fastest-growing segment driven by surgical prophylaxis protocols in intensive dairy operations. Extended-release formulation technology concentrates margin capture among manufacturers with captive pharmaceutical engineering capabilities.
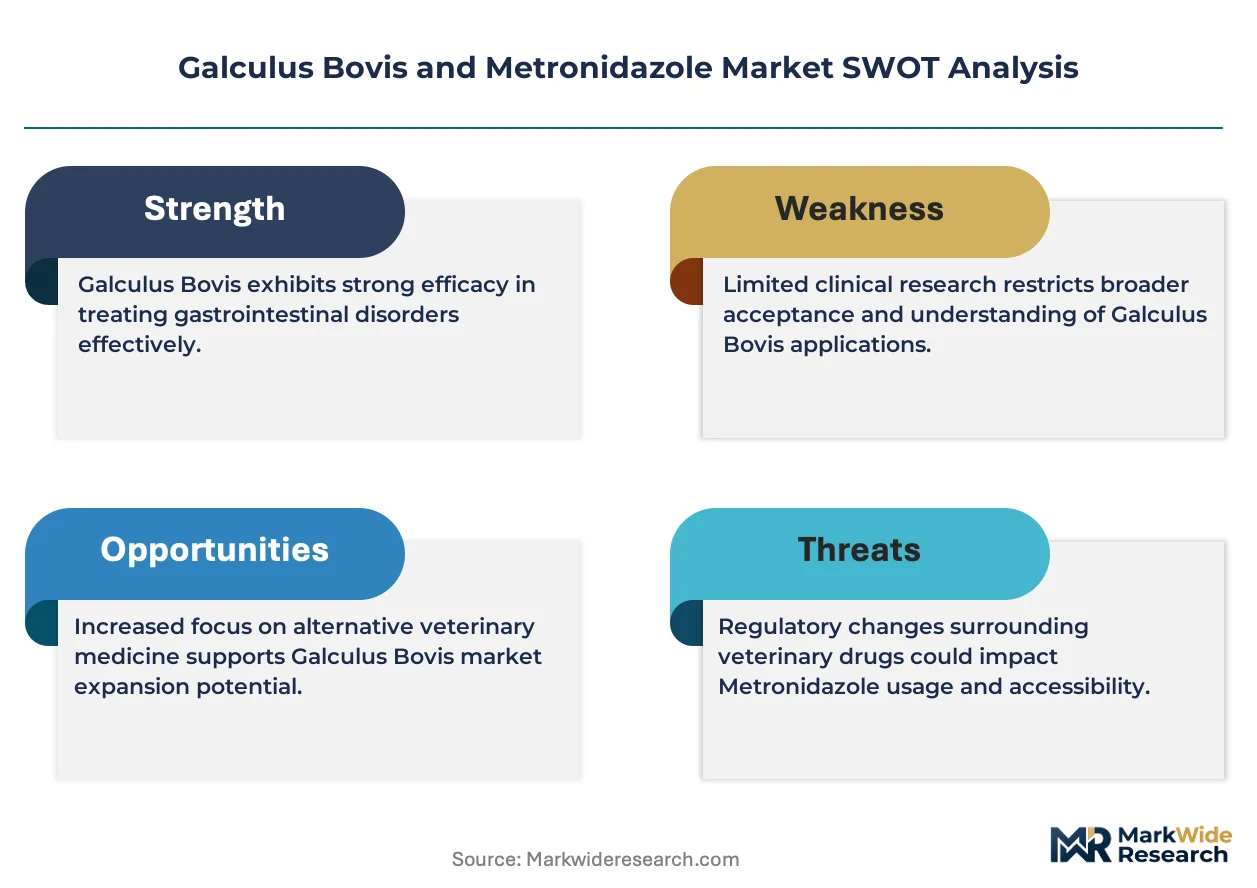
China's NMPA veterinary drug registration requirements and the EU's EMA VMP Regulation shape product approval timelines and residue limit compliance across export-oriented supply chains. India's CDSCO and the US FDA Center for Veterinary Medicine impose divergent stability testing and bioequivalence standards that fragment formulation strategies. Stakeholders must monitor regulatory divergence between major veterinary drug jurisdictions when allocating manufacturing capacity across conventional and extended-release product lines.
Market Dynamics
China's NMPA tightened veterinary drug residue standards in 2023 are compressing formulation approval timelines and forcing manufacturers to revalidate extended-release tablet specifications across East Asian supply chains.
Growth Catalysts
- Intensive dairy operations:Surgical prophylaxis protocols in East Asian livestock markets are accelerating demand for injectable formulations with standardized bilirubin content.
- EU EMA VMP Regulation:Export-oriented manufacturers are upgrading residue limit compliance infrastructure to capture premium pricing in European veterinary channels.
- Extended-release engineering:Captive pharmaceutical formulation capabilities are concentrating margin capture among integrated producers with backward raw material control.
Market Restraints
- Bovine gallstone supply volatility:Raw material sourcing concentrates in specific Chinese provinces, exposing manufacturers to regional livestock disease outbreaks and export quota fluctuations.
- Divergent bioequivalence standards:India's CDSCO and the US FDA Center for Veterinary Medicine impose incompatible stability testing protocols that fragment global formulation strategies.
- Generic metronidazole substitution:Uncompounded nitroimidazole antibiotics threaten pricing power in cost-sensitive farm settings across emerging economies.
Strategic Opportunities
- Vietnam livestock modernization:Underpenetrated veterinary clinic networks in Mekong Delta provinces present first-mover positioning for tablet distribution partnerships.
- Companion animal pivot:Small-animal veterinary practices in urban China are adopting compounded antimicrobials for anaerobic infections previously untreated in household pets.
- ISO 17025 laboratory certification:Third-party testing accreditation is opening contract manufacturing opportunities for mid-scale producers lacking in-house quality infrastructure.
Industry Challenges
- Pharmaceutical engineering talent scarcity:Extended-release formulation expertise concentrates among retiring specialists in legacy Chinese state-owned enterprises.
- Multi-jurisdiction registration synchronization:Simultaneous NMPA, EMA, and FDA approval timelines create working capital intensity for product launch pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galculus Bovis and Metronidazole Market |
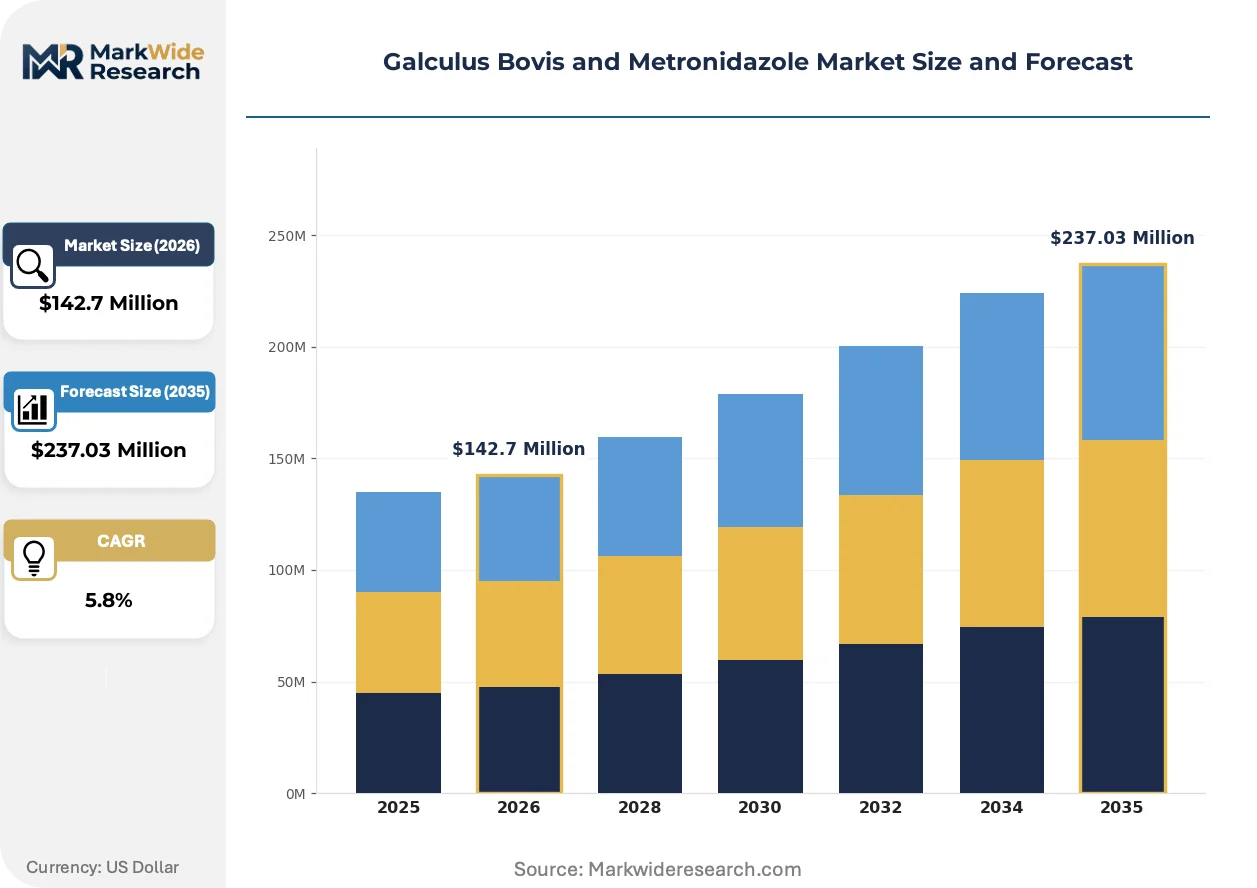
| Market Size in 2026 | $142.7 Million |
| Market Size in 2035 | $237.03 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable, Oral Suspension, Topical End User: Veterinary Clinics, Animal Shelters, Farms, Research Laboratories Application: Infectious Diseases, Gastrointestinal Conditions, Skin Infections, Surgical Prophylaxis Formulation: Conventional, Extended Release, Powder, Liquid |
| Companies Covered | Bayer AG, Novartis International AG, Pfizer Inc., Renhe Pharmacy, Merck & Co., Inc., GlaxoSmithKline plc, Abbott Laboratories, Sunflower Pharmaceutical Group, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galculus Bovis and Metronidazole Market Trends and Innovations
Formulation technology is bifurcating between premium extended-release engineering and commodity generic production, with regulatory compliance costs determining competitive positioning across veterinary antimicrobial supply chains.
Lipid-based sustained-release matrix technology is displacing conventional hydrophilic polymer binders in tablet manufacturing. Intensive dairy operators in Hebei and Shandong provinces are adopting these formulations for post-surgical prophylaxis protocols. The shift is compressing margins for manufacturers lacking captive lipid excipient sourcing capabilities.
REACH-compliant bilirubin extraction processes are mandating solvent substitution in raw material processing. European export-oriented suppliers are retrofitting extraction facilities to eliminate chlorinated hydrocarbon residues. Tablet formulations destined for EU veterinary channels now require additional purification stages that extend production cycles.
Direct-to-clinic distribution platforms are consolidating procurement decisions previously fragmented among provincial veterinary wholesalers. Large-scale livestock operations in China's central plains are consolidating antimicrobial purchasing through digital procurement interfaces. This channel shift is most visible in Henan province, where integrated pork producers now contract directly with tablet manufacturers for annual volume commitments.
Galculus Bovis and Metronidazole Market Segmentation
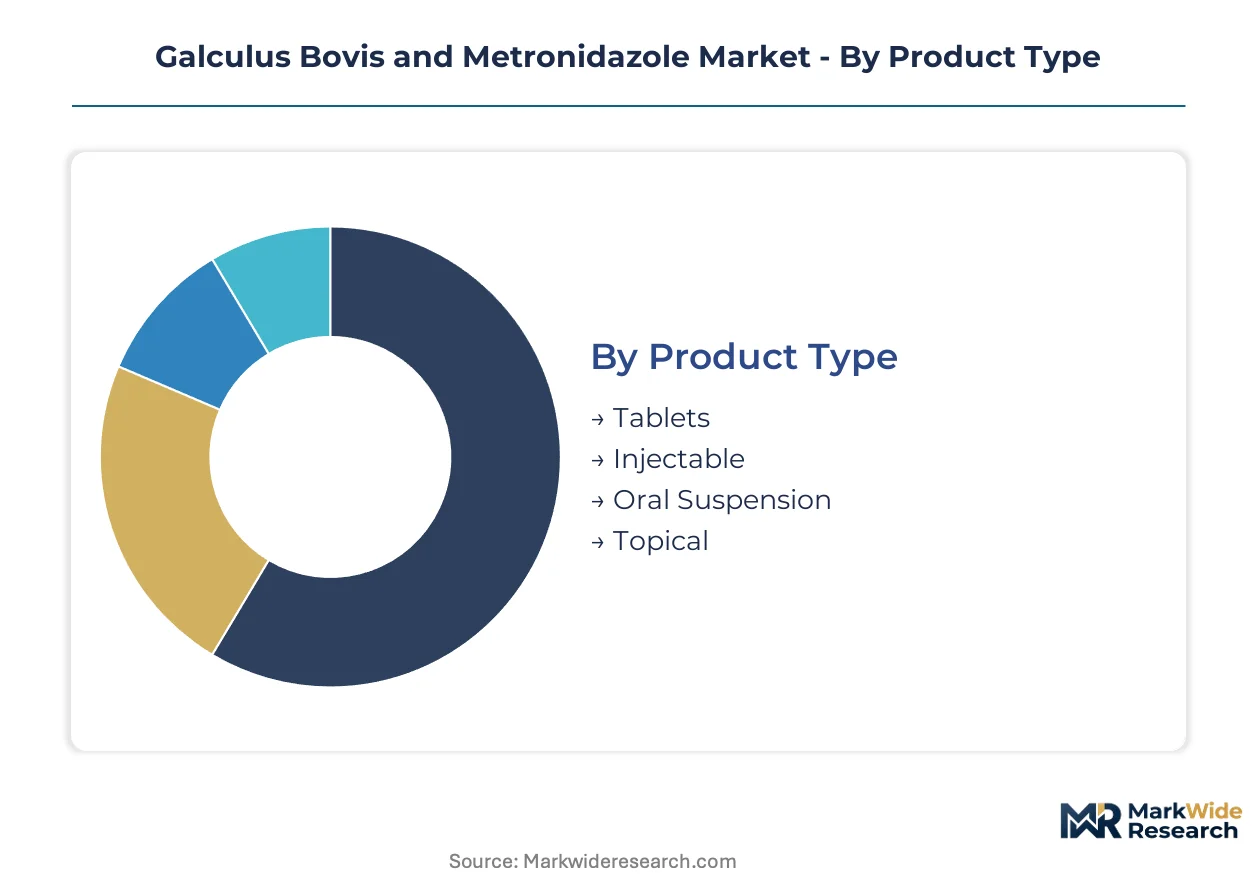
Formulation technology and channel access determine margin capture in this compounded veterinary antimicrobial market. Product type and end-user concentration shape working capital requirements and regulatory compliance burdens across supply chains.
Product Type:
Margin pools concentrate in formulations that reduce dosing frequency and labor costs for intensive livestock operations.
- Tablets:Solid oral dosage forms standardized to 0.2-0.5% bilirubin content and 20-40% metronidazole by weight. Demand clusters in Hebei and Shandong province dairy cooperatives where farm staff prefer shelf-stable inventory with minimal preparation steps. Bayer AG's veterinary division captures premium positioning through bilayer extended-release engineering.
- Injectable:Parenteral solutions requiring sterile manufacturing infrastructure and cold-chain distribution. Surgical prophylaxis protocols in intensive dairy operations across Vietnam's Mekong Delta are accelerating uptake where post-operative infection control justifies higher unit economics.
- Oral Suspension:Liquid formulations for juvenile or compromised animals unable to tolerate solid dosing. Sunflower Pharmaceutical Group anchors regional distribution through provincial veterinary wholesaler networks.
- Topical:Dermal preparations for localized skin infections with limited systemic absorption. Niche positioning in companion animal clinics for anaerobic wound management.
The dominant share belongs to Tablets, while Injectable is closing the gap fastest.
End User:
Procurement consolidation is shifting volume toward direct manufacturer relationships and away from fragmented distributor tiers.
- Veterinary Clinics:Licensed practitioners administering compounded antimicrobials under diagnostic supervision. Urban China's small-animal practices are expanding anaerobic infection treatment protocols for household pets previously left untreated.
- Farms:Large-scale livestock operations with in-house veterinary staff managing herd-level antimicrobial programs. Henan province integrated pork producers now contract directly with tablet manufacturers for annual volume commitments.
- Animal Shelters:Non-profit and municipal facilities with cost-constrained formularies. Procurement concentrates through cooperative purchasing agreements.
- Research Laboratories:Academic and contract research organizations requiring GMP-compliant batches for pharmacokinetic studies. ISO 17025 certification requirements limit supplier qualification.
Farms command the largest procurement volumes, though Veterinary Clinics are expanding their share through companion animal service diversification.
Application:
Therapeutic indication determines regulatory residue limit stringency and withdrawal period specifications.
- Infectious Diseases:Systemic anaerobic bacterial and protozoal infections requiring full therapeutic courses. China's NMPA tightened residue standards are compressing approval timelines for manufacturers targeting food-animal channels.
- Surgical Prophylaxis:Pre- and post-operative antimicrobial coverage in dairy and swine operations. EU EMA VMP Regulation compliance upgrades are forcing residue limit infrastructure investments among export-oriented suppliers.
- Gastrointestinal Conditions:Enteric infections with shorter withdrawal requirements than systemic indications. Formulation stability under gastric pH conditions drives specification differences.
- Skin Infections:Localized dermal anaerobic infections with topical or parenteral administration routes. Limited systemic absorption reduces residue monitoring burden.
Infectious Diseases retains the broadest label coverage, while Surgical Prophylaxis is climbing the fastest on dairy operation expansion.
Formulation:
Engineering sophistication separates premium pricing tiers from commodity competition.
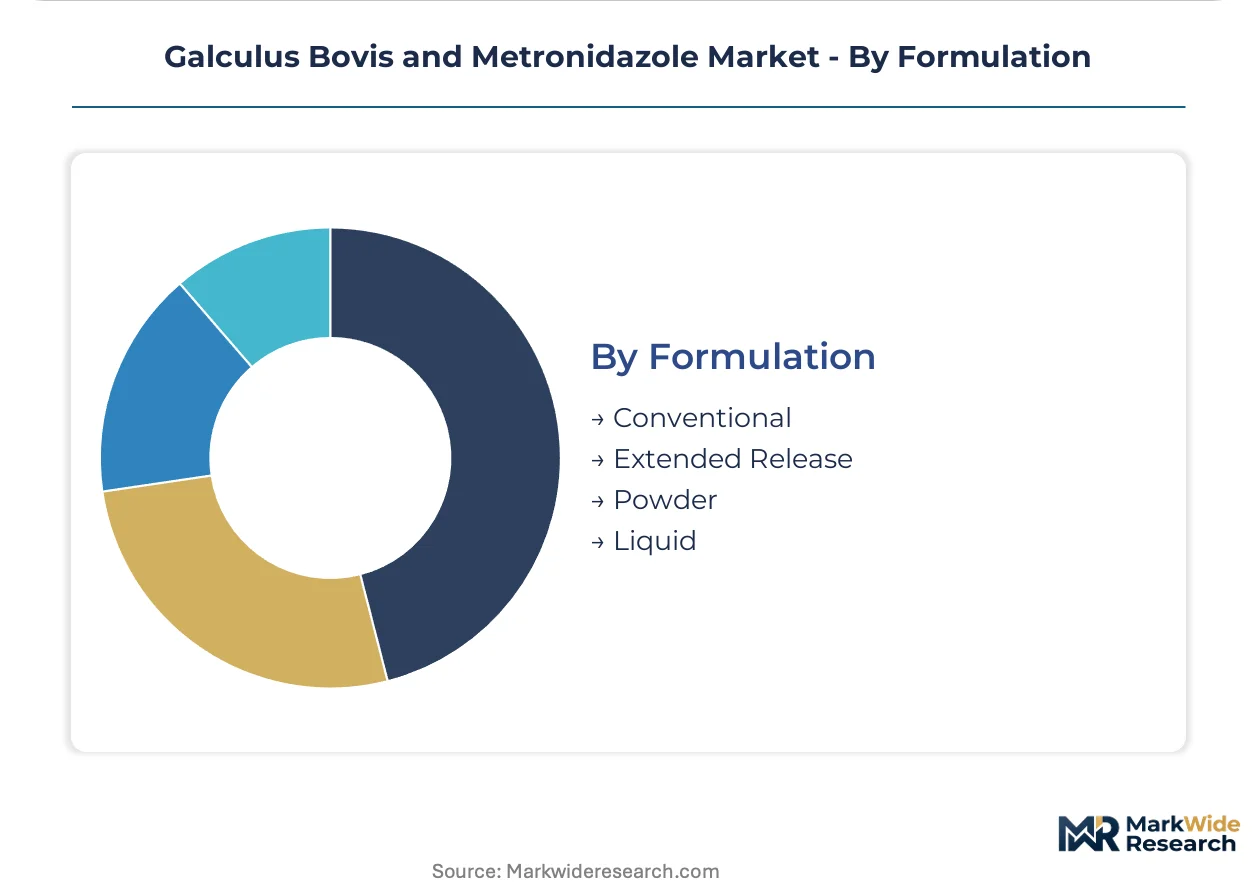
- Extended Release:Lipid-based sustained-release matrix technology displacing conventional hydrophilic polymer binders. Captive pharmaceutical engineering capabilities concentrate margin capture among integrated producers with backward raw material control.
- Conventional:Immediate-release tablets and solutions with established bioequivalence profiles. Generic metronidazole substitution threatens pricing power in cost-sensitive farm settings.
- Powder:Bulk active ingredient blends for on-farm compounding or feed premix integration. Regulatory fragmentation between NMPA and FDA stability testing standards fragments manufacturing strategies.
- Liquid:Ready-to-use solutions and reconstitutable suspensions with shorter shelf lives than solid forms. Cold-chain requirements limit distribution radius.
Extended Release commands the steepest pricing premium, while Conventional formulations face the sharpest generic pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers face divergent residue standards across destination markets, forcing dual-track compliance investments. China's NMPA veterinary drug registrations dominate raw material sourcing, while EU EMA VMP Regulation compliance gates premium European channel access.
China
Hebei and Shandong province dairy cooperatives drive tablet consumption through intensive livestock expansion. NMPA tightened veterinary drug residue standards in 2023 compress formulation approval timelines. Sunflower Pharmaceutical Group anchors distribution across central plains provinces with backward integration into gallstone raw material sourcing.
Germany
Bayer AG's veterinary division leverages R&D intensity to capture premium tablet formulations for EU dairy operations. REACH-compliant bilirubin extraction processes mandate solvent substitution in raw material processing. Bavarian pharmaceutical engineering clusters concentrate extended-release formulation expertise among integrated producers.
United States
FDA Center for Veterinary Medicine bioequivalence standards fragment global formulation strategies for export-bound manufacturers. Large-scale livestock operations in Midwest dairy belts consolidate procurement through direct manufacturer relationships. Generic metronidazole substitution threatens pricing power in cost-sensitive farm settings.
Vietnam
Mekong Delta intensive dairy operations accelerate injectable formulation uptake for surgical prophylaxis protocols. Underpenetrated veterinary clinic networks present first-mover positioning for tablet distribution partnerships. Ho Chi Minh City logistics hubs consolidate cold-chain distribution for parenteral solutions.
India
CDSCO stability testing protocols impose incompatible requirements with FDA and NMPA standards, fragmenting manufacturing strategies. Gujarat and Maharashtra pharmaceutical clusters produce conventional formulations for domestic cost-sensitive markets. Generic metronidazole producers threaten compounded antimicrobial pricing power across emerging economy farm settings.
Galculus Bovis and Metronidazole Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology tiers, creating a bifurcated structure where premium extended-release engineering concentrates among integrated players while commodity production fragments across regional fabricators. Public pharmaceutical conglomerates leverage captive R&D infrastructure to dominate tablet registrations in regulated markets. Private Chinese specialists anchor raw material sourcing and provincial distribution. Dominant competitive moves include backward integration into gallstone extraction and multi-jurisdiction registration synchronization for export market access.
Within the integrated pharmaceutical tier, Bayer AG exemplifies premium formulation positioning through veterinary division R&D intensity. Sunflower Pharmaceutical Group occupies a regional specialist archetype with backward control over Chinese raw material provinces. Among diversified healthcare conglomerates, Pfizer Inc. and Novartis International AG represent scale-driven portfolios where veterinary antimicrobials sit within broader animal health divisions. Merck & Co., Inc. anchors a research-intensive position alongside GlaxoSmithKline plc in compliance-heavy regulated markets. These five entities collectively illustrate the competitive spectrum from captive raw material control to multi-therapeutic portfolio breadth.
| Leading Market Players |
|---|
| Bayer AG |
| Novartis International AG |
| Pfizer Inc. |
| Renhe Pharmacy |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Sunflower Pharmaceutical Group |
| Sanofi S.A. |
| Others |
Pricing and Supply Chain Analysis
Lipid-based sustained-release matrix technology displacing conventional hydrophilic polymer binders simultaneously redraws procurement geography toward captive excipient producers and compresses margins for manufacturers lacking in-house formulation engineering. This substitution dynamic concentrates pricing power among integrated players while fragmenting commodity tablet producers across cost-sensitive farm channels.
Pricing Analysis
Large-scale livestock operations anchor a three-tier pricing structure across premium, standard, and economy levels, with extended-release bilayer tablets commanding substantial premiums over immediate-release formulations. Price differentiation rests on bilirubin content certification and captive raw material sourcing, with Bayer AG's veterinary division capturing top-tier positioning. Cost compression in conventional tablets is intensifying because generic metronidazole substitution threatens compounded antimicrobial pricing power. Smallholder dairy cooperatives in Hebei province exhibit highest price sensitivity, while integrated pork producers in Henan province prioritize dosing convenience over unit cost.
Supply Chain Analysis
Strategic stockpiling of bovine gallstone raw materials dominates procurement behavior among tablet manufacturers exposed to regional livestock disease outbreaks in specific Chinese provinces. Supply concentrates in Hebei and Shandong provinces for raw material extraction, with secondary processing clusters in Bavaria and Gujarat. The supply chain draws from bovine gallstone harvests, pharmaceutical-grade metronidazole API, and lipid excipient inputs. Single-source vulnerability in gallstone sourcing exposes manufacturers to NMPA export quota fluctuations. Distribution runs through direct-to-clinic digital platforms consolidating procurement decisions previously fragmented among provincial veterinary wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as surgical prophylaxis protocols penetrate Vietnam's Mekong Delta dairy operations and companion animal clinics across urban China adopt anaerobic infection treatments previously untreated in household pets.
For Market Incumbents: Shield extended-release formulation margins by deepening backward integration into gallstone extraction provinces before retiring state-owned enterprise specialists exit. Accelerate multi-jurisdiction registration synchronization across NMPA, EMA, and FDA timelines to preempt generic metronidazole substitution in export-oriented channels. Prioritize ISO 17025 laboratory certification investments to capture contract manufacturing opportunities from mid-scale producers lacking in-house quality infrastructure. For New Entrants and Emerging Players: Companion animal service gaps in urban Chinese veterinary clinics offer white-space positioning where incumbents under-serve small-animal anaerobic infection protocols. Mekong Delta tablet distribution partnerships present first-mover access as intensive dairy operations consolidate procurement. Target direct-to-clinic digital procurement interfaces bypassing fragmented provincial wholesaler networks as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a penetration-phase inflection that favors acquisition of regional specialists with captive gallstone sourcing and extended-release engineering capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than commodity production scale. Watch NMPA residue standard tightening velocity as the signal indicating margin compression timing for non-integrated manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gallstone Sourcing | Captive raw material control insulates margin capture from NMPA export quota volatility. |
| Multi-Jurisdiction Registration Synchronization | Simultaneous NMPA, EMA, and FDA approvals unlock premium European and North American veterinary channels. |
| Extended-Release Formulation Engineering | Lipid-based matrix technology commands pricing premiums in intensive dairy surgical prophylaxis protocols. |
| ISO 17025 Laboratory Certification | Third-party testing accreditation opens contract manufacturing for quality-constrained mid-scale producers. |
| Direct-to-Clinic Digital Distribution | Procurement platform consolidation captures volume commitments from Henan province integrated livestock operations. |
Research Methodology
Cross-validation between primary interviews with veterinary pharmaceutical executives, regulatory affairs specialists, and livestock procurement managers and secondary sources including NMPA veterinary drug registration databases, EMA VMP Regulation filings, and customs trade data anchors the qualitative findings. Bottom-up demand modeling across tablet, injectable, oral suspension, and topical formulation segments triangulates with top-down market sizing from manufacturer capacity disclosures and provincial veterinary wholesaler volume estimates.
Sensitivity analysis around bilirubin content standardization timelines and metronidazole API cost trajectories informs the analytical framework across the projection horizon. Segmentation dimensions include product type, end-user concentration, therapeutic application, and formulation technology tier. CAGRs derive from weighted average growth assumptions across intensive dairy expansion corridors, companion animal clinic penetration curves, and regulatory approval pipeline velocities. Key inputs capture NMPA residue limit compliance costs and REACH-compliant extraction facility retrofit requirements.
Forecasts assume regulatory continuity in China's NMPA, the EU's EMA, and the US FDA veterinary medicine frameworks; material policy shifts would require re-modeling. Specific risk factors include bovine gallstone supply disruption from regional livestock disease outbreaks and divergent bioequivalence standard harmonization failures. Revision becomes warranted when generic metronidazole substitution rates in cost-sensitive farm settings cross thresholds that compromise compounded antimicrobial pricing power.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Compounding Chemotherapy Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Anti-Obesity Drugs Market