
 Veterinary Pain Management Market | 2026-2036
Veterinary Pain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Pain Management Market Intelligence
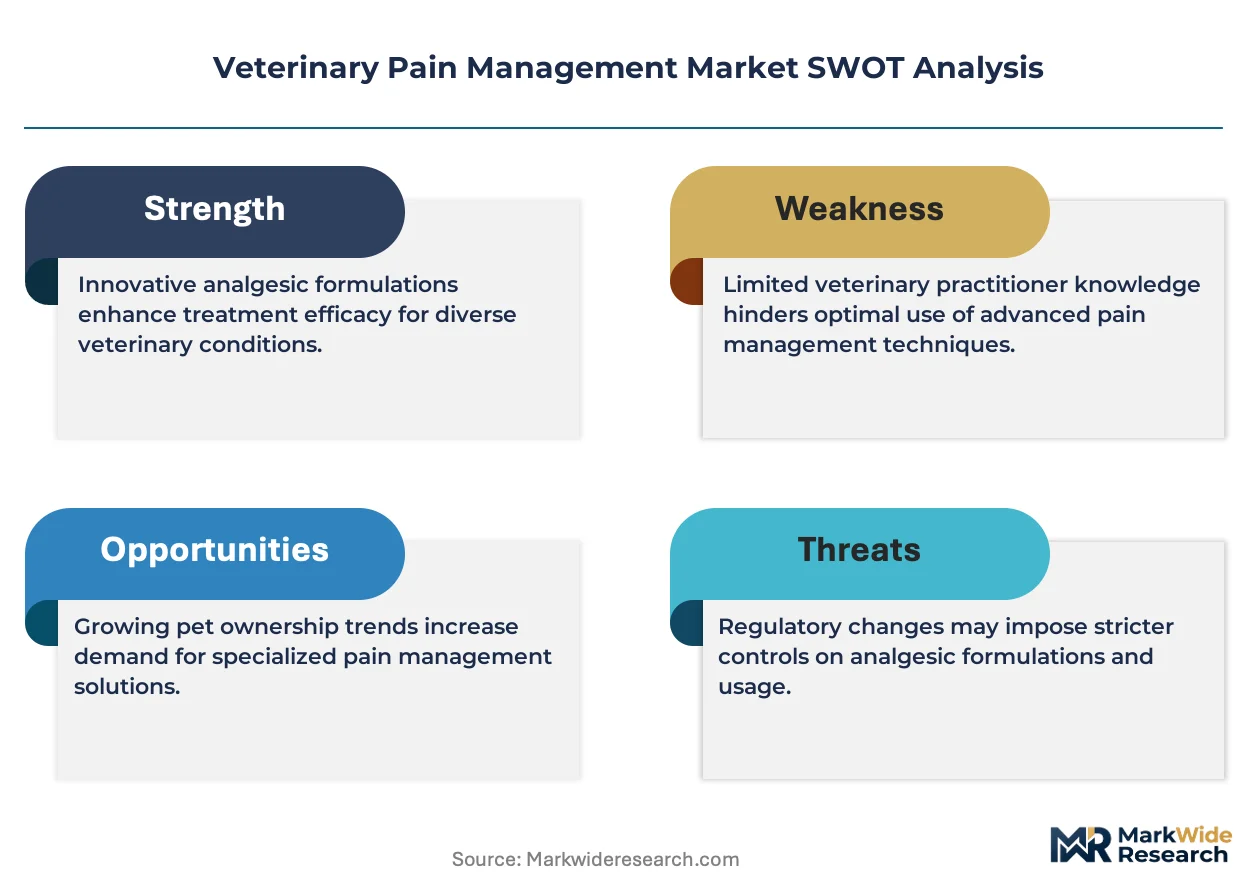
North American pharmaceutical manufacturing capacity for veterinary analgesics is expanding as specialty chemical producers scale active ingredient output for companion animal therapeutics. Zoetis leverages its integrated research platforms to sustain leadership in monoclonal antibody pain therapies for osteoarthritis in dogs. Boehringer Ingelheim International GmbH anchors its position through deep veterinary channel relationships across European and Asia-Pacific markets. Dechra Pharmaceuticals specializes in niche analgesic formulations for exotic and production animals, occupying segments where larger competitors maintain limited presence.
Veterinary pain management encompasses pharmacological and non-pharmacological interventions designed to alleviate nociceptive and neuropathic pain in companion, livestock, and exotic species, with formulations typically requiring species-specific metabolism profiles, palatability engineering, and precise dosing matrices calibrated by body weight and physiological status. The primary commercial purpose centers on improving postoperative recovery trajectories, extending functional mobility in geriatric animals, and supporting welfare standards in agricultural operations. Injectable delivery modes dominate acute surgical settings where rapid onset and bioavailability control matter most, while oral formulations capture chronic pain management regimens where owner compliance determines therapeutic adherence. Adjunct therapies including laser therapy and regenerative medicine represent the fastest-expanding product category as clinics seek opioid-sparing multimodal protocols.
FDA Center for Veterinary Medicine oversight shapes approval pathways for new molecular entities, while EMA guidelines under the Veterinary Medicines Regulation harmonize market access across European Union member states. The EPA additionally regulates topical and transdermal formulations with environmental discharge considerations. Stakeholders must monitor evolving opioid scheduling decisions and species-specific withdrawal period requirements that will determine portfolio prioritization and geographic licensing strategies.
Market Dynamics
Multimodal analgesia protocols are compressing the therapeutic window for single-mechanism drugs as companion animal hospitals demand opioid-sparing regimens that layer NSAIDs, monoclonal antibodies, and adjunct therapies into integrated pain management stacks.
Growth Catalysts
- FDA Center for Veterinary Medicine opioid-sparing guidelines:Accelerated approval pathways for non-narcotic analgesics are redirecting R&D investment toward monoclonal antibody platforms and extended-release NSAID formulations.
- Pet insurance penetration in the United States, Germany, and Japan:Reimbursement coverage for specialist referral procedures and chronic pain management is expanding addressable spend per patient episode.
- Laser therapy and regenerative medicine:Adjunct modalities are capturing clinic capital expenditure as physical rehabilitation services differentiate specialty practices from primary care competitors.
Market Restraints
- Active ingredient supply concentration:Specialty chemical production of veterinary-grade API clusters in India and China, creating single-source vulnerability for European and North American formulators.
- Species-specific metabolism engineering costs:Feline hepatic glucuronidation deficiencies and canine cytochrome P450 polymorphisms force redundant safety and efficacy trials across species lines.
- Environmental discharge regulations:EPA restrictions on topical NSAID runoff from agricultural operations limit transdermal formulation deployment in livestock segments.
Strategic Opportunities
- Exotic animal specialty practices:Avian, reptile, and small mammal analgesia remains underpenetrated by large pharmaceutical portfolios, creating white space for niche formulation development.
- EMA Veterinary Medicines Regulation harmonization:Centralized marketing authorization procedures are reducing regulatory duplication costs for multi-country European launches.
- Telemedicine-integrated chronic pain monitoring:Remote gait analysis and owner-reported outcome measures are enabling subscription-based pain management adherence programs.
Industry Challenges
- Veterinary anesthesiologist workforce scarcity:Board-certified specialist density concentrates in metropolitan referral hospitals, limiting protocol standardization in general practice settings.
- Multispecies pharmacovigilance database construction:Adverse event reporting systems must capture signal detection across divergent physiologies without human medical infrastructure templates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Pain Management Market |
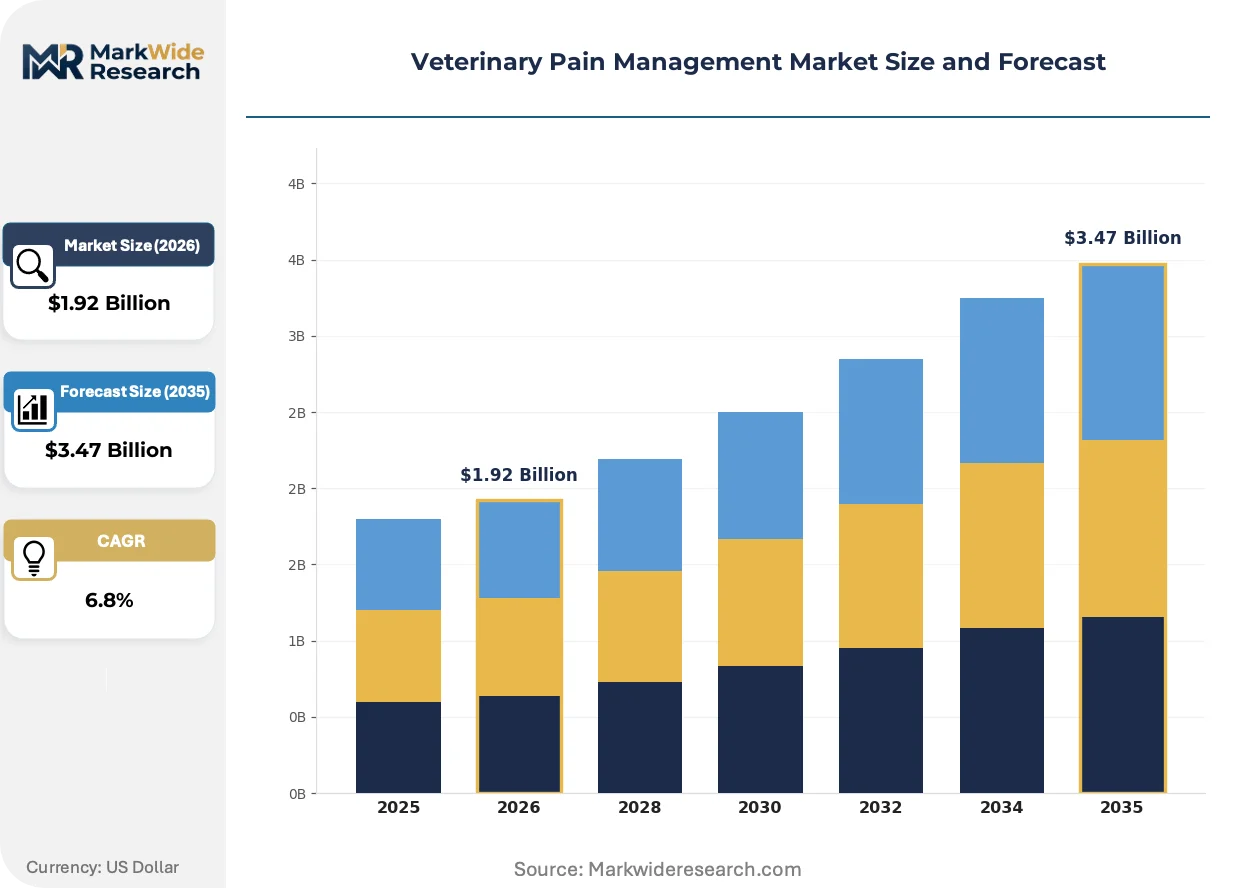
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Opioids, Anesthetics, Adjunct Therapies Application: Post-Surgical Care, Chronic Pain Management, Acute Pain Relief, Palliative Care Delivery Mode: Oral, Injectable, Topical, Transdermal End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Homecare |
| Companies Covered | Zoetis, Boehringer Ingelheim International GmbH, Elanco Animal Health Incorporated, Merck & Co., Inc., Ceva Santé Animale, Vetoquinol, Dechra Pharmaceuticals, Norbrook Laboratories Limited, Chanelle Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Pain Management Market Strategic Shifts & Innovations
Biologic pain therapeutics are compressing the dominance of small-molecule NSAIDs as monoclonal antibodies targeting nerve growth factor demonstrate superior duration and gastrointestinal safety profiles in canine osteoarthritis.
Monoclonal antibody therapies against nerve growth factor are consolidating the chronic pain management segment by delivering monthly dosing intervals that improve owner compliance compared to daily oral NSAID regimens. Specialty and emergency hospitals in the United States and Japan are adopting these platforms as first-line therapy for geriatric canine mobility cases. The technology is consolidating manufacturer competitive position around integrated biologics manufacturing rather than commodity chemical synthesis.
EMA Veterinary Medicines Regulation centralized procedures are compressing time-to-market variance across European Union member states by replacing national mutual recognition with single-assessment pathways. German and French regulators are aligning pharmacovigilance requirements, reducing duplicate post-market surveillance obligations for multi-territory holders. Injectable biologics with complex cold-chain requirements are capturing disproportionate benefit from harmonized batch release protocols.
Subscription-based pain management programs are displacing episodic transaction models as telemedicine platforms enable remote monitoring of chronic conditions between physical examinations. United States specialty practices are bundling monoclonal antibody administration with gait analysis and rehabilitation therapy into monthly membership tiers. This shift concentrates patient lifetime value in vertically integrated service platforms rather than dispersed pharmacy and clinic relationships.
Veterinary Pain Management Market Segmentation
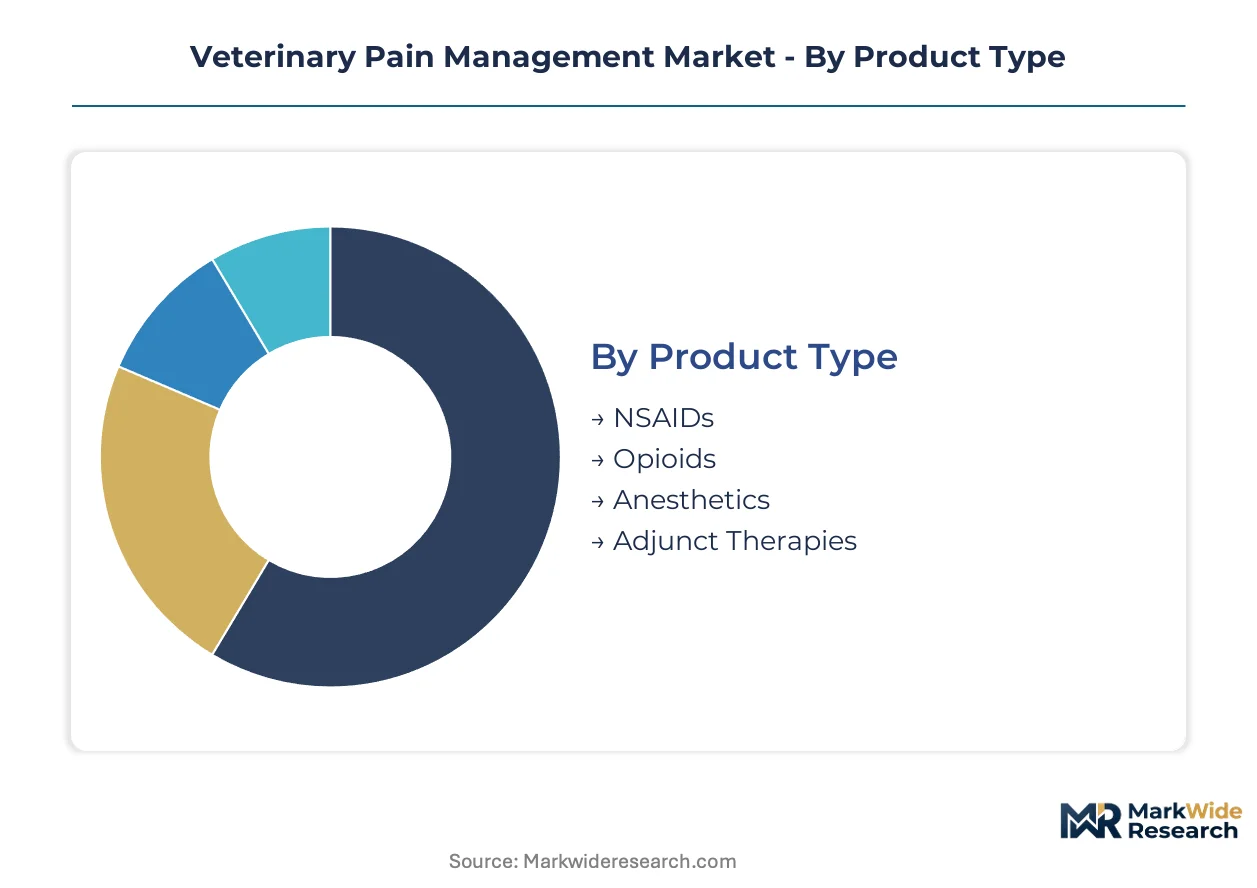
Segmentation in veterinary pain management reveals distinct technology-sensitivity and reimbursement profiles across product categories. Clinicians select modalities based on species metabolism, procedure acuity, and owner compliance capacity.
Product Type:
Volume concentration sits with mature small-molecule formulations, while premium capture belongs to biologics and specialty compounds.
- NSAIDs:Carprofen, meloxicam, and firocoxib formulations dominate chronic osteoarthritis management in canine and feline patients. Demand concentrates in United States companion animal practices where pet insurance reimbursement covers long-term oral administration. Manufacturing capacity clusters with specialty chemical producers in India supplying API to North American and European formulators.
- Opioids:Morphine, hydromorphone, and buprenorphine serve acute perioperative pain control in surgical settings. Deployment concentrates in specialty and emergency hospitals across Germany and Japan where anesthesiologist oversight enables controlled substance protocols. Regulatory scheduling under FDA and DEA frameworks constrains outpatient dispensing.
- Anesthetics:Local and general anesthetic agents enable procedural pain prevention rather than reactive treatment.
- Adjunct Therapies:Laser therapy, acupuncture, and regenerative medicine represent the fastest-expanding category as clinics build multimodal, opioid-sparing protocols.
Mature deployment sits with NSAIDs. Newer deployment is concentrated in Adjunct Therapies.
Application:
Procedure-based segmentation aligns purchasing decisions with reimbursement codes and hospital credentialing requirements.
- Post-Surgical Care:Multimodal analgesia protocols layer injectable NSAIDs, local anesthetics, and opioids to accelerate recovery trajectories in orthopedic and soft-tissue procedures. Demand concentrates in United States specialty referral hospitals where board-certified surgeons mandate standardized pain scoring.
- Chronic Pain Management:Long-term osteoarthritis and neuropathic pain regimens require sustained-release formulations and monoclonal antibody platforms. Japanese and German markets lead adoption due to geriatric pet demographics and specialist density enabling protocol complexity.
- Acute Pain Relief:Trauma and interventional procedures drive short-acting, rapid-onset formulation demand.
- Palliative Care:End-of-life pain control emphasizes quality-of-life metrics and owner-reported outcome measures.
Established revenue capture sits with Post-Surgical Care. Steepest expansion trajectory belongs to Chronic Pain Management.
Delivery Mode:
Compliance engineering and bioavailability requirements shape formulation selection across species lines.
- Injectable:Parenteral routes dominate surgical settings where rapid onset and precise dosing control matter most. United States emergency and specialty hospitals maintain refrigerated inventory of opioid and NSAID injectables for immediate perioperative deployment.
- Oral:Palatability-engineered chewables and liquids capture chronic regimens where owner adherence determines outcomes. Feline formulations face heightened glucuronidation constraints requiring species-specific metabolism testing.
- Topical:Transdermal NSAIDs and local anesthetic creams serve wound management and localized musculoskeletal conditions.
- Transdermal:Fentanyl patches and emerging iontophoretic systems enable continuous delivery in hospitalized patients.
Volume leadership rests with Injectable. Oral climbs fastest as monoclonal antibody platforms extend dosing intervals.
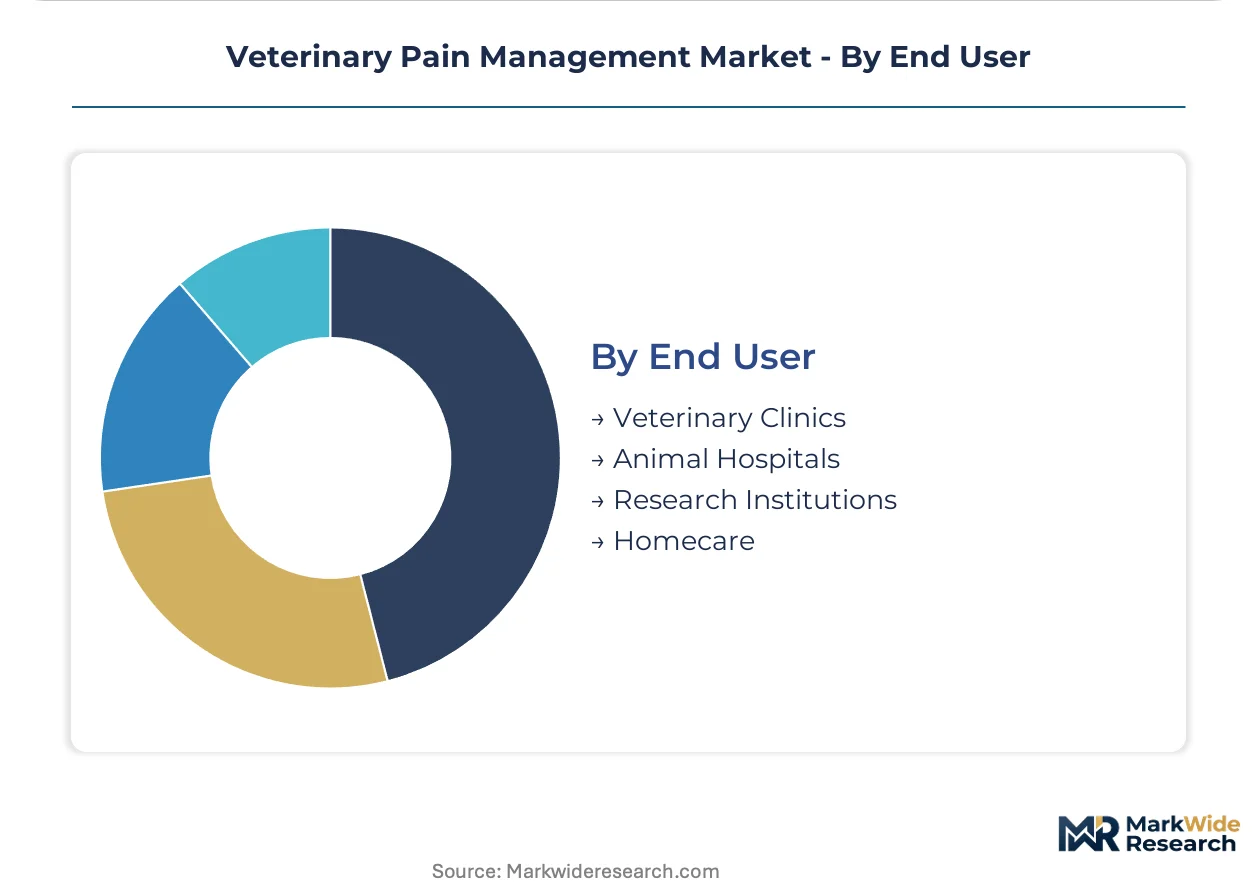
End User:
Capital intensity and credentialing depth create tiered purchasing authority across practice types.
- Veterinary Clinics:Primary care settings manage routine procedures and chronic pain monitoring with limited pharmacy inventory. United States general practices concentrate NSAID dispensing for osteoarthritis maintenance.
- Animal Hospitals:Specialty and emergency institutions command multimodal protocol budgets including biologics, advanced imaging, and rehabilitation services. German university hospitals and Japanese referral centers lead monoclonal antibody adoption.
- Research Institutions:Academic and pharmaceutical research facilities drive preclinical pharmacokinetic studies.
- Homecare:Owner-administered oral and transdermal regimens expand as telemedicine platforms enable remote monitoring.
Established infrastructure sits with Animal Hospitals. Homecare gains share fastest through subscription-based chronic pain programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical production of veterinary-grade active pharmaceutical ingredients clusters in Gujarat and Maharashtra, supplying formulators across North America and Europe with NSAID and anesthetic precursors.
United States
Pet insurance reimbursement for specialist referral procedures and chronic pain management expands addressable spend per patient episode. FDA Center for Veterinary Medicine opioid-sparing guidelines accelerate monoclonal antibody platform approvals. Greater Boston and Research Triangle Park host concentrated biologics manufacturing for canine osteoarthritis therapeutics.
Germany
Geriatric pet demographics and high specialist veterinarian density drive adoption of multimodal analgesia protocols. EMA Veterinary Medicines Regulation centralized procedures harmonize batch release protocols across EU member states. Munich and Leipzig anchor pharmaceutical formulation clusters serving Central European companion animal hospitals.
Japan
Aging pet populations and advanced veterinary credentialing systems sustain demand for extended-release NSAID and monoclonal antibody regimens. PMDA guidelines align with FDA on nerve growth factor inhibitor safety evaluations. Tokyo and Osaka metropolitan areas concentrate specialty emergency hospitals with biologics cold-chain infrastructure.
United Kingdom
Veterinary specialist referral networks and pet insurance penetration support premium analgesic formulation uptake. Veterinary Medicines Directorate enforces pharmacovigilance requirements for multispecies adverse event reporting. Cambridge and Oxford corridor hosts preclinical pharmacokinetic research facilities.
Australia
Livestock export welfare standards and companion animal specialty practice expansion drive analgesic demand. TGA veterinary medicines framework regulates topical NSAID environmental discharge for agricultural operations. Sydney and Melbourne veterinary schools anchor clinical trial networks for species-specific metabolism studies.
Veterinary Pain Management Market Key Industry Players
Global majors compete with regional champions across regulatory submission capacity and veterinary channel depth. Market structure consolidates around integrated biologics manufacturers and specialty chemical formulators with multispecies pharmacovigilance databases. Three archetypes dominate: human-health pharmaceutical divisions with veterinary spinouts, dedicated animal health multinationals, and niche exotic-animal specialists. Competitive moves concentrate on biologics manufacturing capacity expansion and EMA centralized marketing authorization partnerships.
Among dedicated animal health multinationals, Zoetis, Boehringer Ingelheim International GmbH, and Dechra Pharmaceuticals exemplify differentiated positioning archetypes. Zoetis occupies the integrated biologics manufacturing tier with nerve growth factor monoclonal antibody platforms. Boehringer Ingelheim International GmbH anchors the European-Asia-Pacific channel depth archetype through veterinary relationship networks. Dechra Pharmaceuticals represents the niche formulation specialist archetype focused on exotic and production animal segments where larger competitors maintain limited presence.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim International GmbH |
| Elanco Animal Health Incorporated |
| Merck & Co., Inc. |
| Ceva Santé Animale |
| Vetoquinol |
| Dechra Pharmaceuticals |
| Norbrook Laboratories Limited |
| Chanelle Pharma |
| Others |
Cost & Logistics Intelligence
Specialty chemical price indices for veterinary-grade NSAID precursors cascade through formulation tiers, compressing margins for generic manufacturers while biologics manufacturers capture premium positioning through cold-chain service bundling.
Pricing Analysis
Service bundling separates premium biologics from commodity formulations, with monoclonal antibody platforms including refrigeration monitoring, dosing training, and outcome tracking while oral NSAIDs sell unbundled. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA Center for Veterinary Medicine-approved biologics commanding substantial premiums over compounded alternatives. Cost compression in generic NSAID segments is intensifying because Indian API oversupply is flooding spot markets. Primary care veterinary clinics exhibit highest price sensitivity, while specialty animal hospitals prioritize efficacy duration over per-dose cost.
Supply Chain Analysis
Veterinary-grade active pharmaceutical ingredient certification gates entry, with FDA Center for Veterinary Medicine and EMA Veterinary Medicines Regulation compliance requirements filtering out commodity chemical producers. Manufacturing concentration clusters in India, China, and Germany, with Gujarat and Maharashtra anchoring NSAID precursor synthesis while German facilities handle final formulation and batch release. Raw material dependencies center on specialized fermentation media for biologics, high-purity solvents for injectables, and palatability excipients for oral formulations. Single-source vulnerability in Indian API production creates structural risk for North American formulators. Distribution runs through veterinary distributor networks and direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active pharmaceutical ingredient fermentation capacity constraints prop biologics pricing, with specialty manufacturing slots booked years forward insulating premium tiers from generic erosion.
For Market Incumbents: Extend monoclonal antibody platform lifecycles through companion diagnostic development and outcome-based contracting with specialty hospital networks. Backward integration into veterinary-grade API production mitigates Indian supply concentration risk. Certification investment in EMA centralized marketing authorization procedures defends European market access against emerging biologics competitors. For New Entrants and Emerging Players: Launch via exotic animal specialty practices where large pharmaceutical portfolios maintain limited presence, exploiting underserved avian and reptile analgesia demand. Target telemedicine-integrated chronic pain monitoring platforms as the most penetrable delivery channel, bundling remote gait analysis with subscription-based medication adherence programs. White space concentrates in feline-specific formulation development, where glucuronidation deficiencies force species-tailored metabolism engineering that incumbent NSAID portfolios underaddress. For Investors and Strategic Acquirers: Distressed-cycle entries favor niche formulation specialists with exotic animal regulatory dossiers in European markets, where EMA harmonization is compressing multi-country launch costs for acquirers with centralized authorization infrastructure. Long-term viability favors platforms with biologics manufacturing capabilities and cold-chain logistics control. The inflection signal to watch is FDA scheduling decisions on nerve growth factor inhibitors, which would reshape competitive positioning between monoclonal antibodies and small-molecule alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Biologics Manufacturing Scale-Up | Captures monoclonal antibody demand from FDA opioid-sparing guidelines. |
| EMA Centralized Marketing Authorization | Reduces regulatory duplication costs for multi-country European launches. |
| Exotic Animal Formulation Development | Opens underpenetrated segments where large competitors maintain limited presence. |
| Telemedicine Platform Integration | Enables subscription-based chronic pain monitoring between physical examinations. |
| Veterinary-Grade API Backward Integration | Mitigates single-source vulnerability from Indian specialty chemical concentration. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews validating against veterinary pharmaceutical distribution channels. Conversations with veterinary formulary directors, specialty hospital procurement managers, regulatory affairs leads at animal health divisions, and companion animal practice owners informed demand-side assumptions. FDA Center for Veterinary Medicine approval databases, EMA centralized procedure registers, and Indian pharmaceutical export statistics provided supply-side calibration. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Granularity-level modeling distinguished product type, application, delivery mode, and end user dimensions across national markets, with species-specific metabolism profiles and regulatory cluster alignment as cross-cutting variables. CAGRs derived from procedure volume growth, pet insurance penetration trajectories, and biologics adoption curve analysis. Forecast inputs incorporated veterinary specialist workforce density, cold-chain infrastructure expansion, and EMA harmonization implementation timelines.
Regulatory approval delays, API supply disruptions, and monoclonal antibody safety signal detection are the dominant revision risks to projection assumptions. Forecasts reflect documented assumptions regarding pet insurance reimbursement expansion and specialist referral network development. A model refresh is warranted upon material change in FDA opioid scheduling decisions or EMA centralized procedure processing times.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
United States Veterinary Healthcare Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market