
 Spain OTC Drugs Market | 2026-2036
Spain OTC Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Spain OTC Drugs Market Insights
Multi-sourcing from regional API suppliers is decoupling Spanish OTC manufacturers from sole dependence on Asian feedstock. Pfizer sustains formulation leadership through captive tablet production at its Alcobendas facility. Bayer anchors shelf presence in Iberian retail pharmacy chains with broad analgesic and dermatological portfolios. Almirall specializes in respiratory OTC lines tailored to Mediterranean allergy profiles.
Spain OTC drugs comprise non-prescription pharmaceutical preparations containing active ingredients at dosages deemed safe for unsupervised consumer use, typically manufactured through direct compression or fluid-bed granulation processes for oral solid and liquid delivery. These products serve primary commercial purposes of symptom relief, disease prevention, and self-managed chronic condition support without clinician intervention. Pain relief formulations dominate pharmacy counter sales due to high frequency of musculoskeletal complaints among Spain's aging demographic. Online retail channels represent the fastest-growing distribution vector as digital pharmacy licenses proliferate under AEMPS oversight. Digestive health segments occupy concentrated margin pools in supermarket and convenience store placements where impulse purchasing drives volume.
AEMPS governs OTC classification, labeling, and advertising standards through Spain's national medicines law, while the EU MDR and Falsified Medicines Directive impose serialization and safety-feature requirements on all packaged consumer pharmaceuticals. BIS-equivalent quality certifications and CE-marked medical devices create parallel compliance layers for borderline OTC products. Stakeholders must monitor AEMPS reclassification rulings and EU-wide harmonization proposals that could abruptly expand or contract eligible OTC ingredient lists.
Market Dynamics
AEMPS reclassification rulings are accelerating prescription-to-OTC switches, compressing approval timelines and expanding self-medication categories faster than manufacturing capacity can adapt. This regulatory momentum is restructuring competitive positioning around formulation agility and regional API sourcing.
Growth Catalysts
- Streamlined AEMPS Pathways:Spain's national medicines regulator has reduced reclassification review periods, enabling faster market entry for switched analgesics and respiratory products.
- Mediterranean Allergy Prevalence:Pollen concentration patterns across Valencia and Catalonia sustain year-round demand for antihistamine and decongestant formulations.
- Digital Pharmacy Licensing:AEMPS oversight of online retail channels is expanding distribution reach beyond traditional community pharmacy counters.
Market Restraints
- API Import Concentration:Spanish manufacturers remain exposed to Asian feedstock volatility despite regional multi-sourcing efforts, creating margin pressure during supply shocks.
- EU MDR Serialization Costs:Falsified Medicines Directive compliance requires capital-intensive packaging line upgrades for track-and-trace implementation.
- Herbal Supplement Substitution:Plant-based wellness products are capturing symptom-relief occasions previously served by synthetic OTC actives.
Strategic Opportunities
- Andalusian Pharmacy Deserts:Rural provinces with sparse healthcare infrastructure present untapped demand for remote consultation-linked OTC delivery models.
- CE-Marked Device Convergence:Borderline products combining pharmaceutical actives with medical device delivery mechanisms open margin-rich positioning.
- Supermarket Channel Expansion:Digestive health and vitamin segments are securing shelf space in Mercadona and Carrefour hypermarkets beyond pharmacy exclusivity.
Industry Challenges
- Formulation Talent Scarcity:Fluid-bed granulation and direct compression specialists command premium wages as Alcobendas and Barcelona facilities compete for limited labor pools.
- Legacy ERP Integration:Batch record digitization for AEMPS audit trails requires costly middleware deployment across family-owned regional manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain OTC Drugs Market |
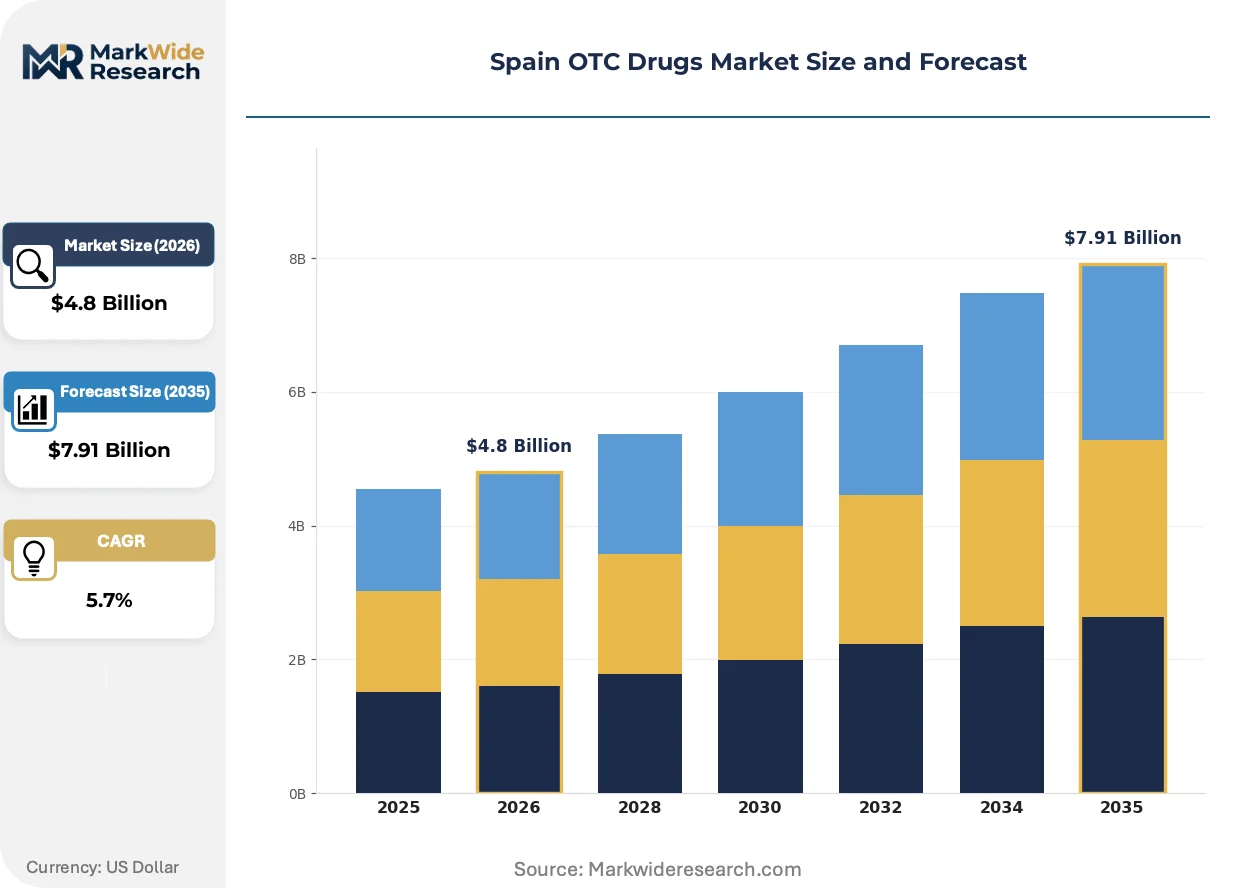
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relief, Cough & Cold, Allergy Medications, Digestive Health Distribution Channel: Pharmacies, Supermarkets, Online Retail, Convenience Stores End User: Adults, Children, Seniors, Caregivers Formulation: Tablets, Liquid, Capsules, Topical |
| Companies Covered | Reckitt Benckiser Group PLC, Pfizer Inc., GlaxoSmithKline PLC, Almirall, Cinfa, Bayer, Johnson and Johnson, Faes Farma, Sanofi SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain OTC Drugs Market Trends and Innovations
Smart packaging and connected health devices are embedding compliance tracking into OTC consumption patterns. These innovations are reshaping how Spanish consumers interact with self-medication products and how regulators verify safe usage.
Near-field communication (NFC)-enabled blister packs are converging with smartphone applications to deliver dosing reminders and interaction warnings directly to patients. Community pharmacies in Madrid are piloting these systems for polypharmacy populations. The technology is converging with AEMPS digital health initiatives to create verifiable adherence records for reclassification submissions.
EU MDR safety-feature mandates are forcing redesign of secondary packaging across all consumer pharmaceutical lines. Tamper-evident seals and unique identifiers now accompany every OTC unit distributed in Spanish retail channels. Analgesic and dermatological portfolios face the steepest compliance cost curves due to high SKU fragmentation.
Subscription-based replenishment models are displacing episodic pharmacy visits for chronic condition management. Digital-native consumers in Barcelona and Valencia are adopting auto-delivery for allergy and digestive health regimens. This behavioral shift concentrates purchasing power with platform operators rather than traditional pharmacy chains.
Spain OTC Drugs Market Segmentation
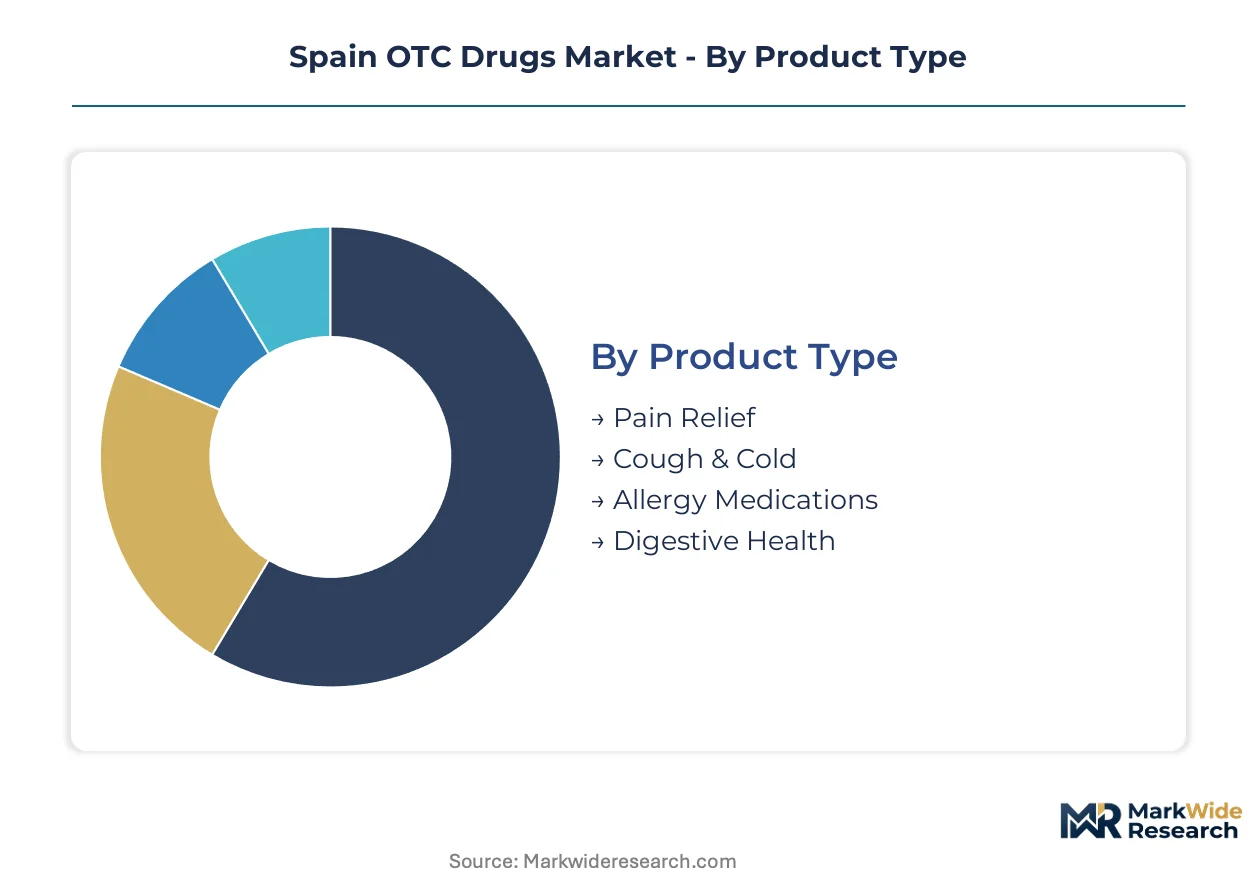
OTC drug segmentation in Spain reveals distinct demand patterns across therapeutic categories and purchase occasions. AEMPS classification rules and channel regulations fragment competitive dynamics differently across each dimension. Manufacturers must align formulation investments with the specific compliance and distribution requirements governing each segment.
Product Type:
Pain relief formulations command premium shelf positioning and highest pharmacy counter turnover, while allergy and digestive segments split between prescription-anchored and impulse-purchase channels.
- Pain Relief:Analgesic tablets and topical formulations containing ibuprofen, paracetamol, and diclofenac dominate Madrid and Barcelona pharmacy sales. Musculoskeletal complaints among Spain's aging demographic sustain year-round demand with limited seasonal fluctuation.
- Cough & Cold:Decongestant and expectorant combinations face concentrated Q4 demand spikes across Catalonia and northern provinces. AEMPS seasonal reclassification reviews periodically restrict pseudoephedrine-containing formulations.
- Allergy Medications:Antihistamine tablets and nasal sprays calibrated to Mediterranean pollen profiles capture Valencia and Andalusia consumers. Almirall and regional specialists tailor SKU mixes to olive and cypress sensitization patterns.
- Digestive Health:Antacids, laxatives, and probiotic formulations occupy supermarket and convenience store placements where Mercadona and Carrefour drive impulse purchasing.
Mature deployment sits with Pain Relief. Newer deployment is concentrated in Digestive Health as supermarket channel expansion accelerates.
Distribution Channel:
Channel selection determines regulatory burden, pricing autonomy, and patient interaction depth for OTC marketers in Spain.
- Pharmacies:AEMPS-licensed community pharmacies remain the mandatory first point of sale for Schedule II OTC products and all pharmacy-only medicines. Pharmacist consultation requirements in Madrid and Barcelona urban clusters sustain higher per-transaction values.
- Supermarkets:Mercadona, Carrefour, and El Corte Inglés hypermarkets stock General Sales List products including vitamins, mineral supplements, and basic analgesics. Shelf space negotiations favor suppliers with consolidated logistics and promotional budgets.
- Online Retail:AEMPS-authorized digital pharmacies are climbing the fastest as COFEPRIS-aligned licensing frameworks mature. Auto-replenishment subscriptions for chronic condition management concentrate purchasing power with platform operators.
- Convenience Stores:Petrol station and urban convenience formats stock limited digestive health and basic pain relief SKUs for emergency purchase occasions.
Volume concentration favors Pharmacies. Margin expansion is strongest in Online Retail.
End User:
Demographic targeting shapes dosing formulation, packaging design, and regulatory submission pathways under AEMPS pediatric and geriatric guidelines.
- Adults:Standard-dose tablets and capsules constitute the baseline formulation for working-age self-medicators. AEMPS monograph compliance for adult populations streamlines approval timelines relative to pediatric submissions.
- Children:Liquid suspensions and weight-calibrated dosing devices require dedicated stability testing and taste masking. Pediatric indications face extended AEMPS review periods and stricter labeling requirements.
- Seniors:Polypharmacy populations in Galicia and Castile-León drive demand for adherence packaging and drug interaction warnings. NFC-enabled blister packs are piloting in Madrid community pharmacies for this cohort.
- Caregivers:Institutional purchasers and family caregivers prioritize bulk formats and clear administration instructions for dependent populations.
Regulatory complexity peaks with Children. Purchasing frequency is highest among Seniors.
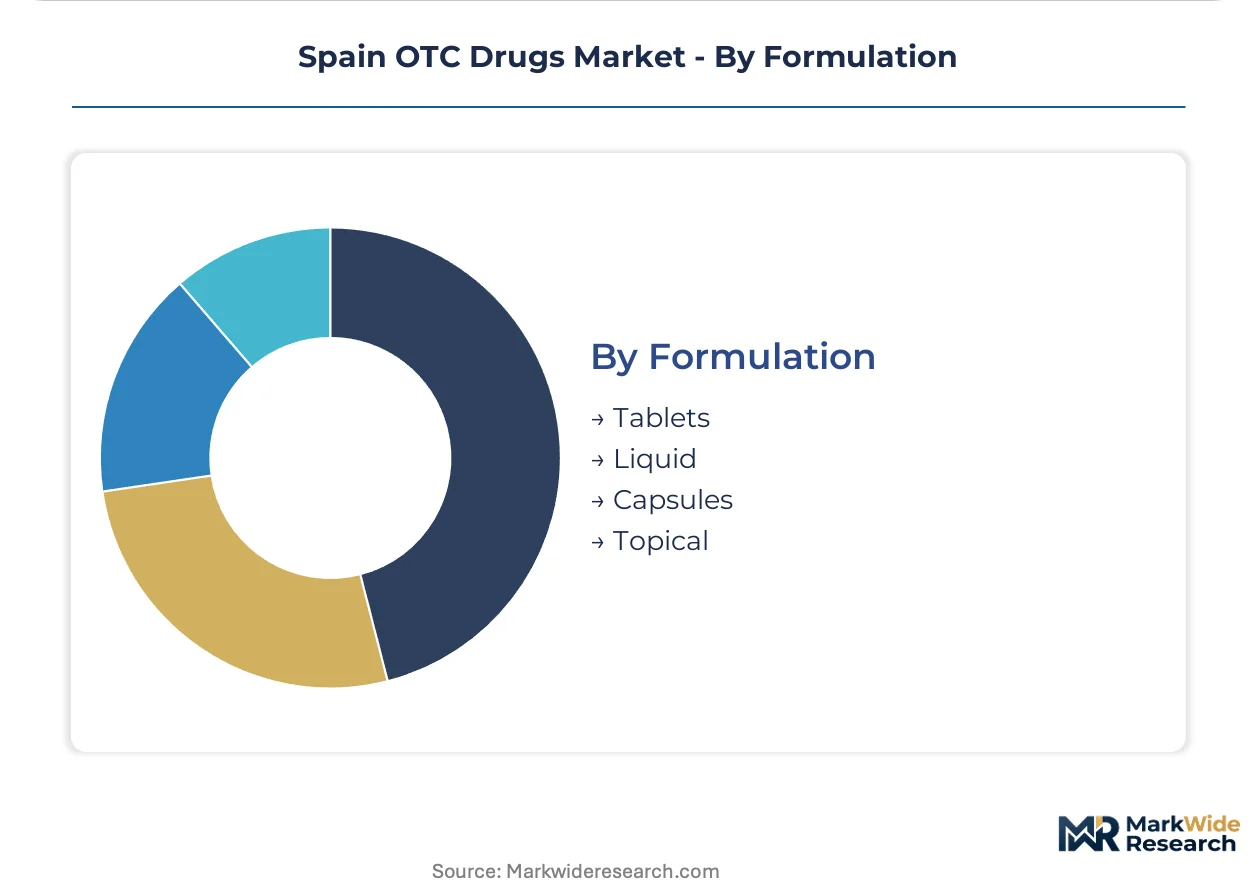
Formulation:
Manufacturing technology selection determines capital intensity, bioavailability profiles, and competitive differentiation in Spanish OTC production.
- Tablets:Direct compression and fluid-bed granulation processes dominate Alcobendas and Barcelona manufacturing clusters. Pfizer's captive tablet production sustains cost advantages in high-volume analgesic categories.
- Liquid:Suspensions and solutions require dedicated bottling lines and preservative stability validation. Pediatric and geriatric segments drive formulation demand for swallowing-difficult populations.
- Capsules:Hard gelatin and HPMC capsules offer taste masking and modified release options for proton pump inhibitors and respiratory actives. Regional API sourcing challenges affect gelatin supply security.
- Topical:Gels, creams, and transdermal patches for pain relief and dermatological applications command premium positioning. EU MDR safety-feature mandates impose serialization costs on low-unit-value formats.
Scale economies concentrate in Tablets. Technical differentiation is expanding fastest in Topical as device-drug combinations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy counter density and AEMPS licensing patterns concentrate OTC consumption in Spain's major metropolitan corridors. Regional manufacturing clusters in Madrid and Barcelona anchor formulation supply, while southern provinces present distribution infrastructure gaps.
Madrid
Community pharmacy saturation in the capital region sustains the highest per-capita OTC transaction frequency nationwide. AEMPS headquarters proximity accelerates reclassification petition processing for manufacturers headquartered locally. Alcobendas hosts captive tablet production facilities serving Iberian distribution networks.
Catalonia
Barcelona's dense urban pharmacy network captures concentrated demand for allergy and respiratory formulations calibrated to Mediterranean pollen profiles. Catalan regional health authority coordination with AEMPS streamlines pediatric indication approvals. Manufacturing specialists in the metropolitan area concentrate on fluid-bed granulation for antihistamine tablets.
Andalusia
Pharmacy deserts across rural Jaén and Córdoba provinces create last-mile delivery challenges for OTC replenishment. Regional government telehealth initiatives are testing remote consultation-linked prescription services that extend to switched OTC categories. Seville anchors wholesale distribution corridors serving Extremadura border zones.
Valencia
Olive and cypress pollen concentration patterns in the Levante region sustain year-round antihistamine demand distinct from northern seasonal peaks. AEMPS-aligned digital pharmacy licenses are proliferating fastest here, expanding online retail channel penetration. Local formulation specialists tailor nasal spray portfolios to regional sensitization profiles.
Basque Country
Industrial pharmacy automation suppliers in Bilbao and San Sebastián are exporting packaging line upgrades to AEMPS-compliant facilities nationwide. The region's legacy chemical manufacturing base supports regional API sourcing initiatives reducing Asian feedstock dependence. Gipuzkoa facilities specialize in high-speed tablet compression equipment for OTC scale production.
Spain OTC Drugs Market Competitive Landscape
Prescription-to-OTC switch petitions dominate the current landscape as manufacturers race to exploit streamlined AEMPS pathways. The market exhibits tiered consolidation with multinational pharmaceutical groups commanding pharmacy shelf space alongside regional Spanish specialists. Three archetypes prevail: global diversified majors with captive manufacturing, Iberian-focused mid-caps with respiratory specialization, and private-label suppliers serving supermarket channels. Portfolio diversification and regional API sourcing partnerships constitute the dominant competitive moves reshaping positioning.
Among global diversified majors, Pfizer Inc. and Bayer occupy positions exemplifying formulation leadership through integrated manufacturing scale. Almirall represents the regional specialist archetype, with its corporate identity signaling Catalan-rooted respiratory expertise. Reckitt Benckiser Group PLC anchors the consumer health platform model, its structure reflecting UK-based over-the-counter heritage applied to Iberian retail pharmacy networks. These three patterns—integrated pharmaceutical manufacturing, regional therapeutic specialization, and consumer health platform distribution—capture the competitive vectors currently dividing market influence.
| Leading Market Players |
|---|
| Reckitt Benckiser Group PLC |
| Pfizer Inc. |
| GlaxoSmithKline PLC |
| Almirall |
| Cinfa |
| Bayer |
| Johnson and Johnson |
| Faes Farma |
| Sanofi SA |
| Others |
Pricing and Supply Chain Analysis
Fluid-bed granulation automation across Alcobendas and Barcelona manufacturing clusters simultaneously compresses unit production costs and concentrates formulation capability among capital-intensive operators. This technology transition feeds pricing power upstream to equipment-integrated manufacturers while squeezing margin at regional API-dependent competitors.
Pricing Analysis
Service bundling separates AEMPS compliance consulting from pure product supply, with full regulatory support packages commanding 15-25% premiums over unbundled tablet supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and pediatric indication coverage. Cost compression in economy analgesics is intensifying because Mercadona and Carrefour hypermarkets leverage consolidated procurement volumes. Price-sensitive supermarket channels drive the steepest discounting, while pharmacy-exclusive respiratory lines sustain premium positioning through AEMPS consultation requirements.
Supply Chain Analysis
Regional distribution centers in Madrid, Barcelona, and Seville anchor hub-and-spoke patterns that extend AEMPS-tracked inventory to pharmacy deserts across Jaén and Córdoba provinces. API sourcing draws from India, China, and emerging Spanish regional suppliers for ibuprofen, paracetamol, and antihistamine actives. Single-source vulnerability concentrates in gelatin capsule supply from European rendering facilities. Distribution runs through wholesale cooperatives serving AEMPS-licensed community pharmacies, with direct-to-pharmacy models gaining share among multinational manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU MDR serialization mandates is forcing sub-scale regional manufacturers toward exit or acquisition, as capital-intensive compliance upgrades exceed returns for family-owned operators below 50 million unit annual volume.
For Market Incumbents: To counter API feedstock volatility from Asian suppliers, Pfizer and Bayer should deepen captive tablet production at Alcobendas while securing backward integration into regional paracetamol synthesis partnerships. Channel control through exclusive pharmacy distribution agreements for respiratory lines provides defensive moats against supermarket private-label encroachment. For New Entrants and Emerging Players: Begin with digital pharmacy platform partnerships targeting allergy subscription replenishment in Valencia and Barcelona, where AEMPS licensing proliferation outpaces incumbent platform coverage. White-space concentration sits with NFC-enabled adherence packaging for Madrid's polypharmacy senior population, an application where formulation agility trumps manufacturing scale. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to consumer health platforms seeking Iberian respiratory specialization, with IPO viability limited to integrated manufacturers above 200 million unit capacity. Target acquisition archetypes include Catalan fluid-bed granulation specialists with AEMPS pediatric approval track records. The inflection signal to monitor is AEMPS reclassification volume for prescription-to-OTC switches, which would abruptly expand addressable categories for formulation-ready acquirers.| Strategic Initiative | Industry Significance |
|---|---|
| Prescription-to-OTC Switch Petition | AEMPS streamlined pathways compress approval timelines for switched analgesics and respiratory products. |
| Regional API Sourcing Partnership | Multi-sourcing from Basque Country chemical manufacturers reduces Asian feedstock dependence for ibuprofen actives. |
| Digital Pharmacy License Acquisition | AEMPS-authorized platforms in Valencia extend distribution reach beyond traditional community pharmacy counters. |
| NFC-Enabled Packaging Pilot | Smart blister packs for Madrid polypharmacy populations create verifiable adherence records for reclassification submissions. |
| Supermarket Channel Expansion | Mercadona and Carrefour shelf space for digestive health SKUs captures impulse purchasing outside pharmacy exclusivity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with AEMPS regulatory affairs leads, pharmacy procurement managers at Madrid hospital systems, formulation directors at Alcobendas manufacturing facilities, and category buyers at Mercadona and Carrefour. AEMPS reclassification rulings, EU MDR compliance databases, and Spanish pharmaceutical customs declarations provided triangulation points. Bottom-up SKU-level volume estimates and top-down therapeutic category spend analysis were reconciled across independent calculation paths.
Data-stream reconciliation combined patient population projections, AEMPS licensing growth trajectories, and channel shift patterns across the analysis window. Segmentation modeling spanned product type, distribution channel, end-user demographic, and formulation technology dimensions. CAGRs were derived from least-squares trend fitting of historical volume data adjusted for AEMPS regulatory inflection points. Forecast inputs included Mediterranean pollen concentration indices for allergy demand and digital pharmacy license issuance rates for channel shift velocity.
Underlying measurement precision varies by segment; pharmacy transaction data carries tighter precision than online retail estimates where platform operators withhold granular disclosure. Forecasts reflect assumptions regarding AEMPS reclassification momentum and EU-wide harmonization timelines. Periodic stress-testing of base assumptions is recommended given regulatory pathway volatility and API supply disruption potential.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Global Fluorouracil (5FU) Market