
 Peptic Ulcer Drugs Market | 2026-2036
Peptic Ulcer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Peptic Ulcer Drugs Market Intelligence
Generic bioequivalence standards for proton pump inhibitors is collapsing the premium pricing once held by originator molecules. Pfizer leverages its manufacturing scale to sustain volume leadership in off-patent omeprazole formulations. Takeda Pharmaceutical anchors its position through specialized lansoprazole delivery technologies that differentiate against commodity substitutes.
Peptic ulcer drugs comprise pharmaceutical agents that modulate gastric acid secretion, neutralize existing acid, or eradicate Helicobacter pylori infection through targeted antimicrobial action, with proton pump inhibitors achieving irreversible H+/K+ ATPase inhibition at the parietal cell canaliculus to maintain intragastric pH above four for twelve to sixteen hours. These agents serve the primary commercial purpose of healing mucosal defects, preventing recurrence, and reducing ulcer-related complications across acute and maintenance therapy settings. Proton pump inhibitors command the dominant margin pool due to superior healing rates and extended patent protection histories, while H2-receptor antagonists occupy a shrinking but stable niche in renal-impaired populations where drug interactions require avoidance. Antimicrobials within triple and quadruple therapy regimens represent the fastest-growing structural segment as clarithromycin resistance patterns force bismuth-based and rifabutin-containing protocol adoption.
The FDA governs bioequivalence requirements for abbreviated new drug applications, while the EMA oversees centralized marketing authorization for fixed-dose combination therapies across European member states, and the WHO Essential Medicines List inclusion shapes procurement priorities in low-income health systems. These frameworks collectively determine which formulations gain formulary placement, how generic substitution proceeds, and where manufacturers must invest in pediatric or geriatric extension studies. Stakeholders must monitor clarithromycin resistance surveillance data and corresponding guideline revisions to anticipate which antimicrobial components will retain reimbursement eligibility in first-line eradication protocols.
Market Dynamics
Hospital formulary committees are consolidating procurement around fixed-dose combination therapies for H. pylori eradication, compressing margins for single-molecule suppliers while rewarding manufacturers with integrated antimicrobial portfolios. This purchasing concentration is reshaping competitive positioning across the proton pump inhibitor landscape.
Growth Catalysts
- Medicare Part B expansion:Outpatient ulcer management reimbursement protocols in the United States are extending coverage duration for maintenance proton pump inhibitor therapy, pulling volume through retail pharmacy channels.
- Clarithromycin resistance surveillance:Updated WHO treatment guidelines are mandating bismuth-based quadruple therapy as first-line protocol, stimulating demand for bismuth subsalicylate formulations in low-income health systems.
- Dual-release delivery technologies:Specialized lansoprazole formulations with modified-release kinetics are capturing formulary slots in Japan where gastric pH control duration determines reimbursement tiers.
Market Restraints
- API supply concentration:Omeprazole active pharmaceutical ingredient production clusters in select Indian manufacturing zones, exposing finished dose formulators to single-source disruption risk.
- FDA bioequivalence compression:Abbreviated new drug application standards for generic proton pump inhibitors are collapsing premium pricing architectures that originator molecules once commanded.
- H2-receptor antagonist substitution:Ranitidine withdrawal from multiple markets has redirected stable maintenance therapy demand toward famotidine, constraining proton pump inhibitor volume in renal-impaired populations.
Strategic Opportunities
- Pediatric extension studies:EMA marketing authorization pathways for granule formulations in children under twelve remain underexploited, offering first-mover advantage for taste-masked delivery technologies.
- Rifabutin-containing protocols:Clarithromycin-resistant strain prevalence is opening reimbursement eligibility for rifabutin-based triple therapy in tertiary care centers across Germany and France.
- Direct-to-clinic distribution:Hospital system purchasing cooperatives in the United States are bypassing wholesale intermediaries for high-volume H. pylori eradication kits, rewarding logistics-integrated manufacturers.
Industry Challenges
- Antimicrobial stewardship compliance:Hospital pharmacy and therapeutics committees require enhanced documentation for clarithromycin prescribing, extending sales cycle duration for combination therapy suppliers.
- Legacy formulation integration:Geriatric extension studies for existing proton pump inhibitor portfolios demand bioequivalence bridging trials that strain clinical development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptic Ulcer Drugs Market |
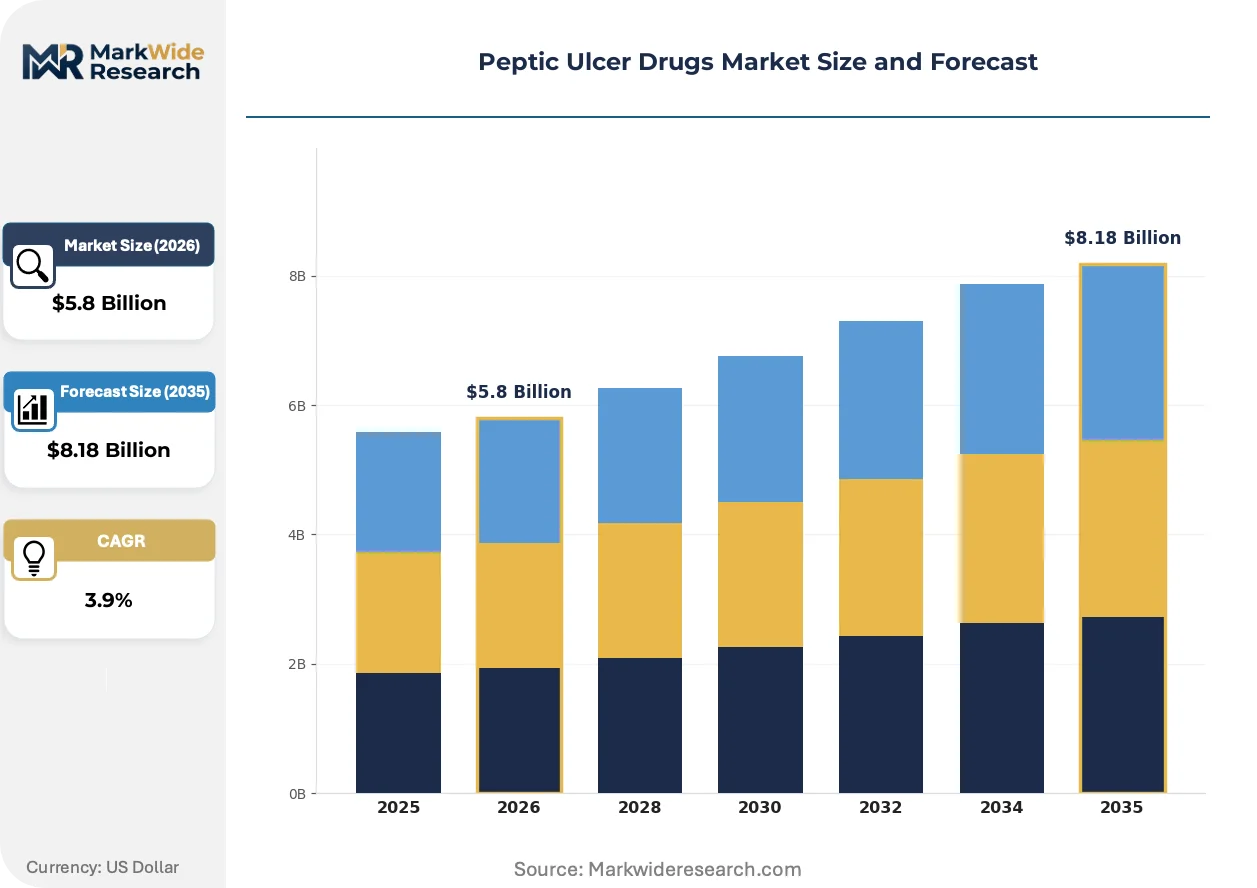
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Pump Inhibitors, H2-Receptor Antagonists, Antacids, Mucosal Protectants, Antimicrobials Therapy Area: Gastric Ulcer, Duodenal Ulcer, Stress Ulcer, Zollinger-Ellison Syndrome, Helicobacter pylori Infection End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Diagnostic Laboratories, Community Health Centers Delivery Mode: Oral Tablets, Oral Suspensions, Injectable Formulations, Capsules, Effervescent Tablets |
| Companies Covered | AstraZeneca, Pfizer, Takeda Pharmaceutical, Novartis AG, Boehringer Ingelheim, Abbott Laboratories, Zydus Lifesciences, Sanofi, Viatris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptic Ulcer Drugs Market Strategic Shifts & Innovations
Peptic ulcer drug development is pivoting toward precision eradication protocols as resistance surveillance data forces real-time guideline adaptation. Manufacturers are repositioning around biomarker-guided therapy selection and localized manufacturing to secure formulary access.
Potassium-competitive acid blockers are fragmenting the chronic therapy segment through rapid onset kinetics that challenge conventional proton pump inhibitor dominance. South Korean and Japanese hospital systems are adopting these agents for acute bleeding control where intragastric pH elevation speed determines clinical outcomes. This mechanism is fragmenting maintenance therapy market share previously captured by irreversible H+/K+ ATPase inhibitors.
REACH compliance requirements for residual solvent limits in fixed-dose combination manufacturing are forcing European contract manufacturers to retool extraction and purification workflows. The industrial consequence is extended batch release timelines for bismuth-containing quadruple therapies. German and Italian formulation sites are responding by qualifying alternative solvent systems that maintain antimicrobial stability while meeting ECHA thresholds.
Hospital purchasing cooperatives are consolidating antimicrobial procurement around single-source suppliers who guarantee resistance surveillance data sharing. The traditional pharmaceutical distributor channel is losing share to direct manufacturer agreements in the United States where Medicare accountable care organizations demand cost-per-eradication metrics. This concentration is most visible in Midwestern and Southeastern health system alliances where integrated delivery networks cover multiple states.
Peptic Ulcer Drugs Market Segmentation
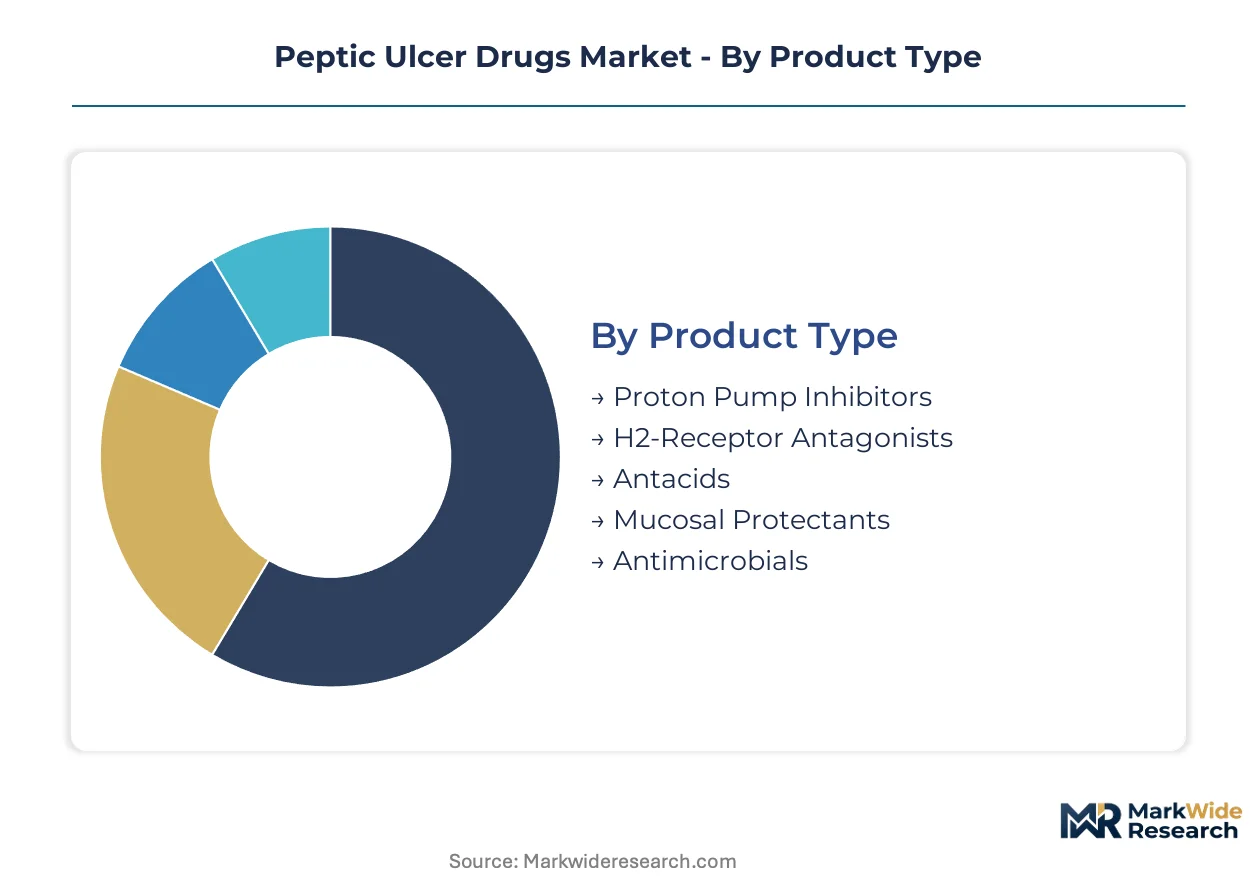
Peptic ulcer drug segmentation reveals how margin pools concentrate around mechanism-of-action differentiation and procurement channel consolidation. Understanding these divides exposes where pricing power persists versus where commoditization pressures dominate.
Product Type:
Margin concentration tracks directly with patent protection duration and bioequivalence barriers, creating stark profitability tiers across mechanism classes.
- Proton Pump Inhibitors:Irreversible H+/K+ ATPase inhibitors at the parietal cell canaliculus sustain intragastric pH above four for twelve to sixteen hours. Hospital procurement in the United States concentrates around Medicare Part B reimbursed maintenance therapy, though FDA bioequivalence standards for generics compress originator premiums.
- Antimicrobials:Clarithromycin, amoxicillin, metronidazole, and bismuth compounds target Helicobacter pylori eradication in combination protocols. Demand is accelerating fastest in low-income health systems where WHO Essential Medicines List inclusion shapes procurement toward bismuth-based quadruple therapy as first-line standard.
- H2-Receptor Antagonists:Competitive histamine H2 receptor blockers serve renal-impaired populations requiring drug interaction avoidance.
- Antacids:Acid-neutralizing aluminum and magnesium hydroxide formulations occupy over-the-counter channels with minimal prescription reimbursement.
- Mucosal Protectants:Sucralfate and bismuth subsalicylate create protective barriers at ulcer sites.
The dominant share belongs to Proton Pump Inhibitors, while Antimicrobials are closing the gap fastest.
Therapy Area:
Revenue distribution correlates with chronicity of treatment duration and complication risk stratification across ulcer etiologies.
- Helicobacter pylori Infection:Eradication protocols require multi-drug combinations over fourteen days with resistance surveillance driving regimen selection. German and French tertiary care centers are expanding rifabutin-based triple therapy reimbursement as clarithromycin resistance thresholds trigger protocol switches.
- Gastric Ulcer:Mucosal defects in the stomach lining demand prolonged acid suppression with healing rates determining formulary placement. Japan's reimbursement tiers favor dual-release delivery technologies that extend gastric pH control duration.
- Duodenal Ulcer:Proximal small intestine lesions respond to shorter treatment courses.
- Stress Ulcer:ICU prophylaxis in mechanically ventilated patients drives injectable formulation demand.
- Zollinger-Ellison Syndrome:Gastrinoma-driven hypersecretion requires high-dose continuous therapy.
Helicobacter pylori Infection commands the largest addressable population, though Gastric Ulcer generates higher per-patient revenue through extended maintenance.
End User:
Purchasing concentration patterns determine whether manufacturers capture value through direct contracts or distributor intermediaries.
- Hospitals:Formulary committees consolidate procurement around fixed-dose combination kits for H. pylori eradication, bypassing wholesale channels through purchasing cooperatives. Midwestern and Southeastern United States health system alliances now demand cost-per-eradication metrics from single-source suppliers.
- Specialty Clinics:Gastroenterology-focused outpatient settings prioritize rapid symptom resolution.
- Ambulatory Surgery Centers:Pre-operative prophylaxis drives short-course utilization.
- Diagnostic Laboratories:Resistance testing integration influences antimicrobial selection.
- Community Health Centers:Federally qualified sites in the United States rely on Medicare reimbursement expansion for outpatient ulcer management.
Hospitals retain procurement volume leadership, while Specialty Clinics are expanding fastest as care shifts toward outpatient settings.
Delivery Mode:
Technology differentiation in release kinetics creates reimbursement tier separation in regulated markets.
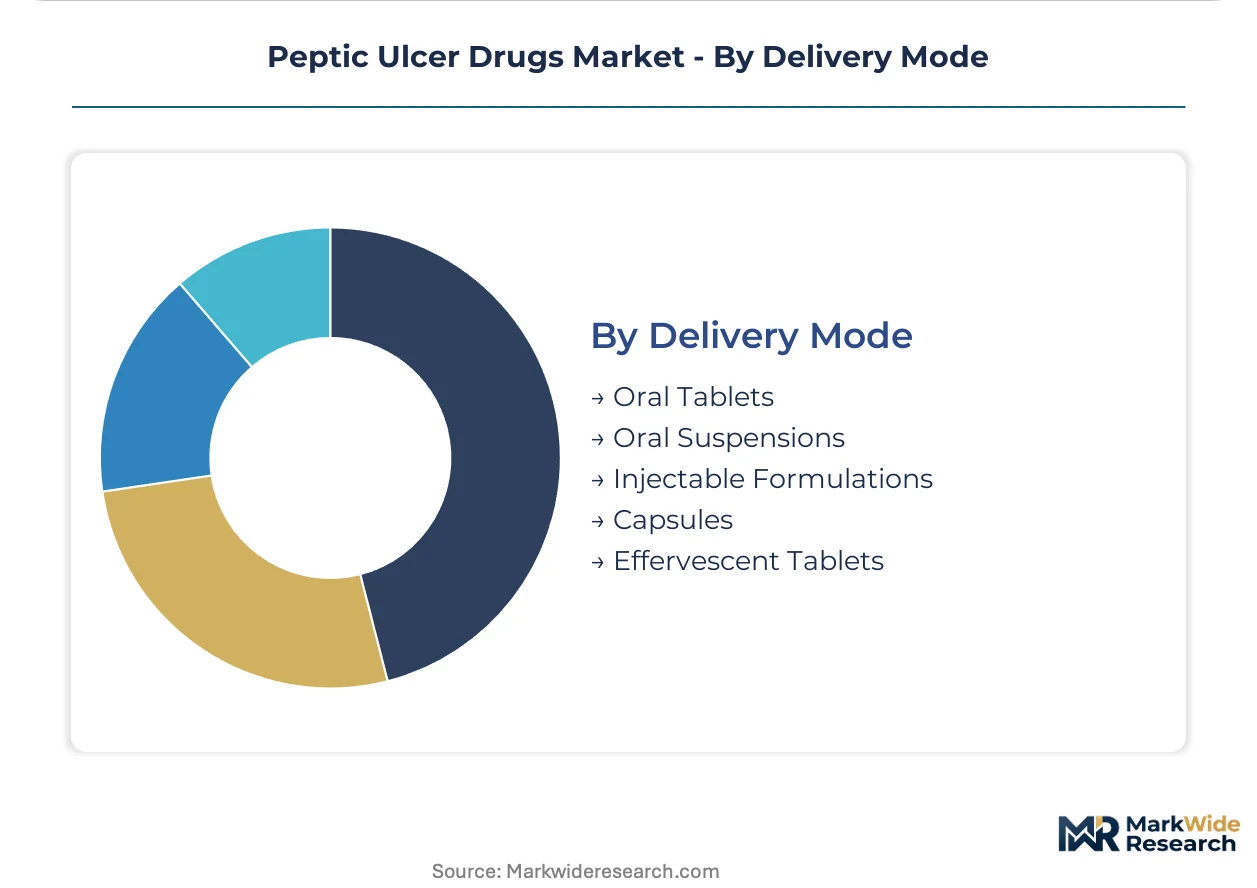
- Oral Tablets:Immediate and modified-release formulations dominate maintenance therapy with bioequivalence standards determining generic substitutability. EMA marketing authorization pathways for granule formulations in children under twelve remain underexploited.
- Capsules:Enteric-coated and dual-release technologies protect acid-labile compounds.
- Injectable Formulations:Intravenous proton pump inhibitors serve acute bleeding control where rapid intragastric pH elevation determines clinical outcomes in South Korean and Japanese hospital systems.
- Oral Suspensions:Liquid alternatives address dysphagia and pediatric populations.
- Effervescent Tablets:Rapid dissolution formats compete in over-the-counter antacid segments.
Oral Tablets maintain volume dominance, though Injectable Formulations are gaining share fastest in acute care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for omeprazole active pharmaceutical ingredient shapes trade flows across finished dose markets. United States purchasing cooperatives source heavily from Indian manufacturing zones. European formulation sites face REACH compliance costs that alter regional sourcing patterns.
United States
Medicare Part B reimbursement expansion for outpatient ulcer management pulls volume through retail pharmacy channels. FDA bioequivalence guidance for generic proton pump inhibitors compresses originator pricing premiums. Midwestern and Southeastern health system alliances consolidate procurement around fixed-dose combination kits for H. pylori eradication.
Germany
Hospital pharmacy and therapeutics committees mandate enhanced documentation for clarithromycin prescribing, extending sales cycles for combination therapy suppliers. EMA centralized marketing authorization pathways govern fixed-dose combination therapies. Bavarian tertiary care centers expand rifabutin-based triple therapy reimbursement as resistance thresholds trigger protocol switches.
Japan
Dual-release delivery technologies capture formulary slots where gastric pH control duration determines reimbursement tiers. METI industrial standards shape domestic manufacturing requirements. Kanto region hospital systems adopt potassium-competitive acid blockers for acute bleeding control where intragastric pH elevation speed determines clinical outcomes.
India
Omeprazole active pharmaceutical ingredient production clusters in select manufacturing zones, exposing finished dose formulators to single-source disruption risk. CDSCO oversight governs abbreviated new drug application standards. Gujarat and Maharashtra formulation sites supply export markets across low-income health systems where WHO Essential Medicines List inclusion shapes procurement priorities.
Peptic Ulcer Drugs Market Key Industry Players
Listed leaders compete with private specialists across manufacturing scale and delivery technology differentiation. The market structure concentrates around originator molecules with extended patent histories and commodity generic suppliers facing bioequivalence compression. Three archetypes dominate: multinational pharmaceutical conglomerates with integrated antimicrobial portfolios, specialized delivery technology developers, and high-volume generic manufacturers. Competitive moves center on pediatric extension studies for EMA marketing authorization and direct-to-clinic distribution partnerships bypassing wholesale intermediaries.
Among originator-tier developers, AstraZeneca and Takeda Pharmaceutical occupy positions anchored in specialized formulation capabilities. Pfizer exemplifies the scale-driven archetype through manufacturing volume leadership in off-patent omeprazole formulations. These three entities represent contrasting strategic postures across premium delivery technologies, commodity volume production, and integrated portfolio breadth.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer |
| Takeda Pharmaceutical |
| Novartis AG |
| Boehringer Ingelheim |
| Abbott Laboratories |
| Zydus Lifesciences |
| Sanofi |
| Viatris |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Indian API manufacturers and United States purchasing cooperatives lock in omeprazole supply access while compressing price visibility for finished dose formulators. These contracts tether hospital procurement budgets to single-source manufacturing zones in Gujarat and Maharashtra, amplifying disruption risk across the value chain.
Pricing Analysis
Hospital formulary buyers anchor a contract-based pricing structure that rewards integrated antimicrobial portfolios over single-molecule suppliers. Three-tier pricing structure across originator-branded, authorized-generic, and commodity-substitute levels reflects FDA bioequivalence tiering and delivery technology differentiation. Cost compression in off-patent proton pump inhibitor segments is intensifying because Medicare Part B reimbursement expansion pulls volume toward lowest-bid procurement. Community health centers exhibit highest price sensitivity due to federally qualified site budget constraints, while specialty gastroenterology clinics retain lowest sensitivity where rapid symptom resolution commands premium positioning.
Supply Chain Analysis
Strategic stockpile preferences dominate hospital purchasing cooperative behavior, with Midwestern and Southeastern United States health system alliances maintaining ninety-day bismuth subsalicylate buffers against clarithromycin protocol switches. Omeprazole active pharmaceutical ingredient production clusters in India, China, and select Italian manufacturing zones, drawing from benzimidazole precursor chemistries and enteric coating polymer feedstocks. Single-source vulnerability in Gujarat-based API output exposes finished dose formulators to regulatory inspection-triggered supply interruptions. Distribution runs through direct-to-clinic channels bypassing wholesale intermediaries, with logistics-integrated manufacturers capturing hospital system purchasing cooperative contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peptic ulcer drug development sits in early-cycle expansion as clarithromycin resistance surveillance forces real-time guideline adaptation and bismuth-based quadruple therapy adoption accelerates across low-income health systems.
For Market Incumbents: Shield market position by deepening backward integration into bismuth compound manufacturing and securing EMA marketing authorization for pediatric granule formulations before competitor entry. Potassium-competitive acid blockers from South Korean and Japanese developers threaten irreversible proton pump inhibitor maintenance share, demanding counter-investment in dual-release delivery technologies that extend gastric pH control duration. Capacity reservation agreements with Indian API suppliers reduce single-source exposure. For New Entrants and Emerging Players: Taste-masked pediatric formulation development for children under twelve represents an underexploited service-layer gap where EMA pathways remain uncontested by incumbent granule portfolios. Direct-to-clinic distribution partnerships with United States hospital purchasing cooperatives offer the most penetrable channel structure, bypassing wholesale margin extraction through logistics integration. Rifabutin-based triple therapy reimbursement expansion in German and French tertiary care centers provides a specialized go-to-market anchor against commodity proton pump inhibitor competition. For Investors and Strategic Acquirers: Specialized delivery technology developers with proprietary dual-release lansoprazole platforms and existing Japanese reimbursement tier positioning present the most attractive acquisition target archetype for portfolio differentiation. Long-term viability hinges on antimicrobial stewardship compliance capabilities and resistance surveillance data sharing infrastructure. Watch clarithromycin resistance threshold crossings in WHO treatment guideline revisions as the signal indicating rifabutin protocol reimbursement acceleration and corresponding portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Extension Studies | EMA marketing authorization for granule formulations in children under twelve unlocks uncontested formulary slots. |
| Direct-to-Clinic Distribution | Hospital purchasing cooperative partnerships in the United States bypass wholesale intermediaries and capture volume leadership. |
| Backward Integration into API | In-house omeprazole active pharmaceutical ingredient production insulates against Indian manufacturing zone disruption risk. |
| Resistance Surveillance Infrastructure | Data-sharing agreements with hospital pharmacy and therapeutics committees secure clarithromycin protocol eligibility. |
| Potassium-Competitive Acid Blocker Development | Rapid onset kinetics challenge conventional proton pump inhibitor dominance in acute bleeding control segments. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital formulary directors, gastroenterology clinic procurement managers, pharmaceutical regulatory affairs leads, and antimicrobial stewardship committee chairs. Secondary validation drew from FDA abbreviated new drug application filings, EMA centralized marketing authorization submissions, WHO Essential Medicines List revision documentation, and Medicare Part B reimbursement protocol updates. Bottom-up volume modeling across mechanism-of-action segments and top-down value triangulation against purchasing cooperative contract values ensured cross-verification.
Across the analysis window, the forecasting framework modeled proton pump inhibitor, antimicrobial, H2-receptor antagonist, and mucosal protectant segments by therapy area, end user channel, and delivery mode technology tier. CAGRs were derived from Medicare reimbursement expansion trajectories, clarithromycin resistance surveillance trend projections, and hospital procurement consolidation patterns. Treatment line positioning and regional regulatory cluster differentiation shaped patient population accessibility assumptions.
Forecasts assume regulatory continuity in FDA bioequivalence standards and EMA REACH compliance thresholds; material policy shifts would require re-modeling. Revision becomes warranted when clarithromycin resistance prevalence crosses protocol switch thresholds in WHO treatment guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Sinus Therapeutic Drugs Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market