
 Differentiated Thyroid Cancer Therapeutics Market | 2026-2036
Differentiated Thyroid Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Differentiated Thyroid Cancer Therapeutics Market Outlook
North American biopharma manufacturing is recalibrating capacity toward radiopharmaceutical and kinase inhibitor production for thyroid malignancies. Sanofi leverages its radioligand infrastructure to secure supply chain continuity for iodine-based therapies across hospital networks. Novartis sustains broad oncology portfolio depth, competing across multiple solid tumor indications including differentiated thyroid cancer. Eisai anchors its presence through targeted agent development, specializing in kinase inhibition mechanisms for radioiodine-refractory populations.
Differentiated thyroid cancer therapeutics encompass systemic treatments for papillary, follicular, and Hürthle cell carcinomas, including radioactive iodine-131 for remnant ablation, tyrosine kinase inhibitors blocking VEGFR/RET signaling pathways, and monoclonal antibodies targeting tumor microenvironment modulation. These agents serve to reduce recurrence following thyroidectomy, control locoregional progression, and extend progression-free survival in metastatic disease. Tyrosine kinase inhibitors represent the fastest-expanding category as resistance to radioactive iodine drives salvage therapy demand, while intravenous delivery modes retain dominance in hospital-based administration despite oral convenience advantages. Oncology centers capture the deepest margin pools due to bundled reimbursement for infused biologics and required monitoring protocols.
FDA orphan drug incentives and EMA's PRIME designation accelerate clinical development timelines for novel agents in rare thyroid malignancy subsets, compressing the path from Phase I to conditional approval. REACH compliance requirements in Europe constrain radiopharmaceutical manufacturing site selection, favoring centralized production with dedicated isotope supply agreements. Japan's PMDA Sakigake framework creates parallel fast-track entry for breakthrough kinase inhibitors. Stakeholders must monitor regulatory divergence across FDA, EMA, and PMDA regarding progression-free survival endpoints versus overall survival requirements for full approval conversion.
Market Dynamics
Radioactive iodine resistance among metastatic patients is compressing first-line treatment windows and accelerating salvage therapy sequencing across oncology networks.
Growth Catalysts
- Orphan Drug Incentives:FDA's expedited review pathway compresses development timelines for kinase inhibitors targeting radioiodine-refractory disease, drawing venture funding toward rare thyroid malignancy subsets.
- Radiopharmaceutical Infrastructure:Hospital networks in the United States are expanding cyclotron capacity and isotope handling capabilities to support iodine-131 ablation protocols.
- Biomarker Stratification:RET and NTRK fusion testing is overtaking histology-only staging, enabling precision patient selection for targeted systemic therapy enrollment.
Market Restraints
- Molybdenum-99 Supply Concentration:Five aging reactors in Canada, the Netherlands, and South Africa produce the majority of medical isotope precursors, creating vulnerability to unplanned outages.
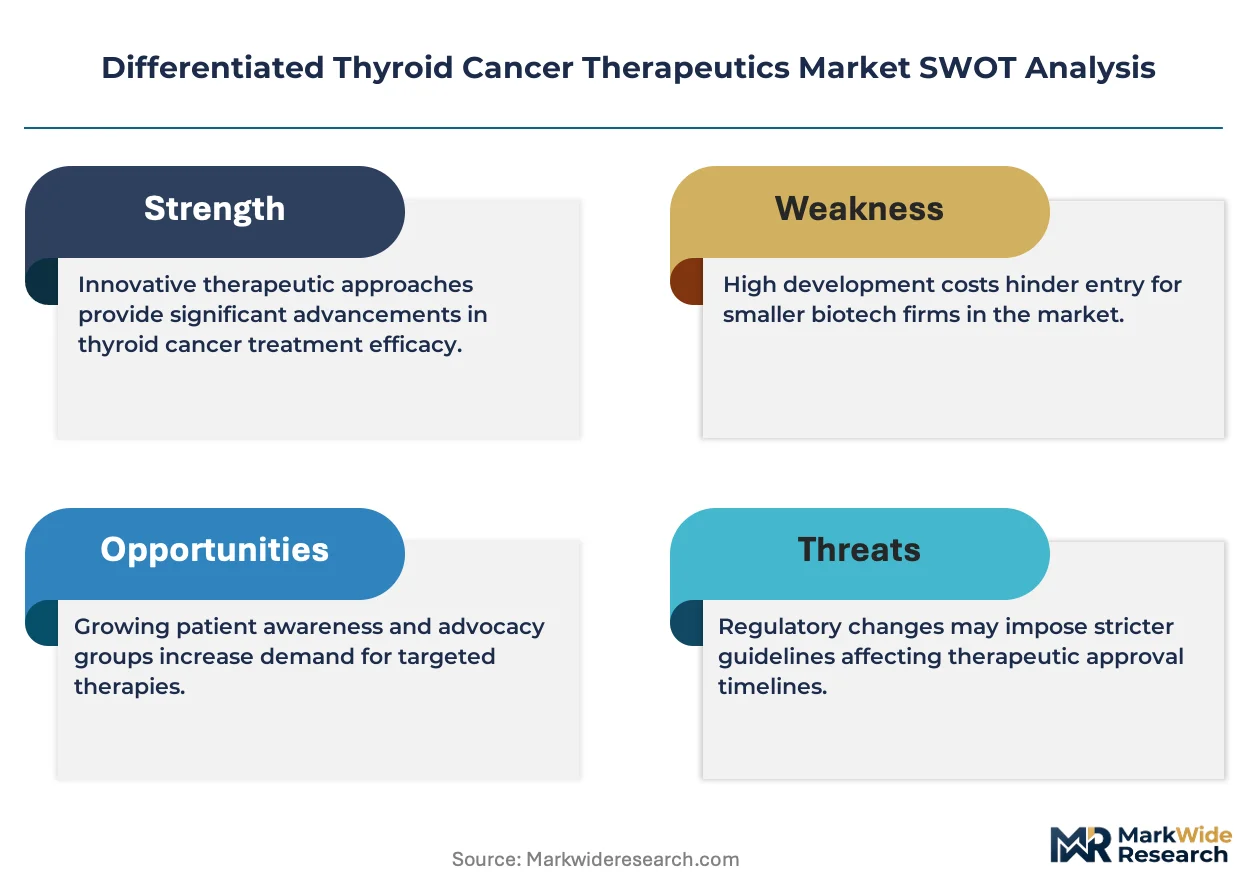
- REACH Compliance Burden:ECHA's radiopharmaceutical manufacturing site requirements constrain European production location flexibility, elevating capital costs for iodine-based therapy suppliers.
- Oral TKI Substitution Pressure:Convenience-driven patient preference for outpatient kinase inhibitor regimens threatens hospital-based infusion revenue pools supporting radioactive iodine programs.
Strategic Opportunities
- Japan's Sakigake Fast-Track:PMDA's breakthrough designation framework offers parallel market entry for novel RET inhibitors ahead of Western regulatory timelines.
- Combination Regimen White Space:Sequencing immunotherapy with targeted agents in anaplastic transformation represents an unaddressed mechanistic pathway with limited current trial activity.
- Direct-to-Patient Distribution:Specialty pharmacy channels are capturing oral TKI dispensing from hospital outpatient departments, enabling margin capture through risk evaluation and mitigation strategy programs.
Industry Challenges
- Radioisotope Handling Certification:Nuclear medicine technologist training programs face capacity constraints, extending staffing timelines for expanded iodine-131 therapy suites.
- Progression-Free Survival Endpoint Disputes:Divergent FDA, EMA, and PMDA evidentiary standards for full approval conversion complicate Phase III trial design and regulatory submission sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Differentiated Thyroid Cancer Therapeutics Market |
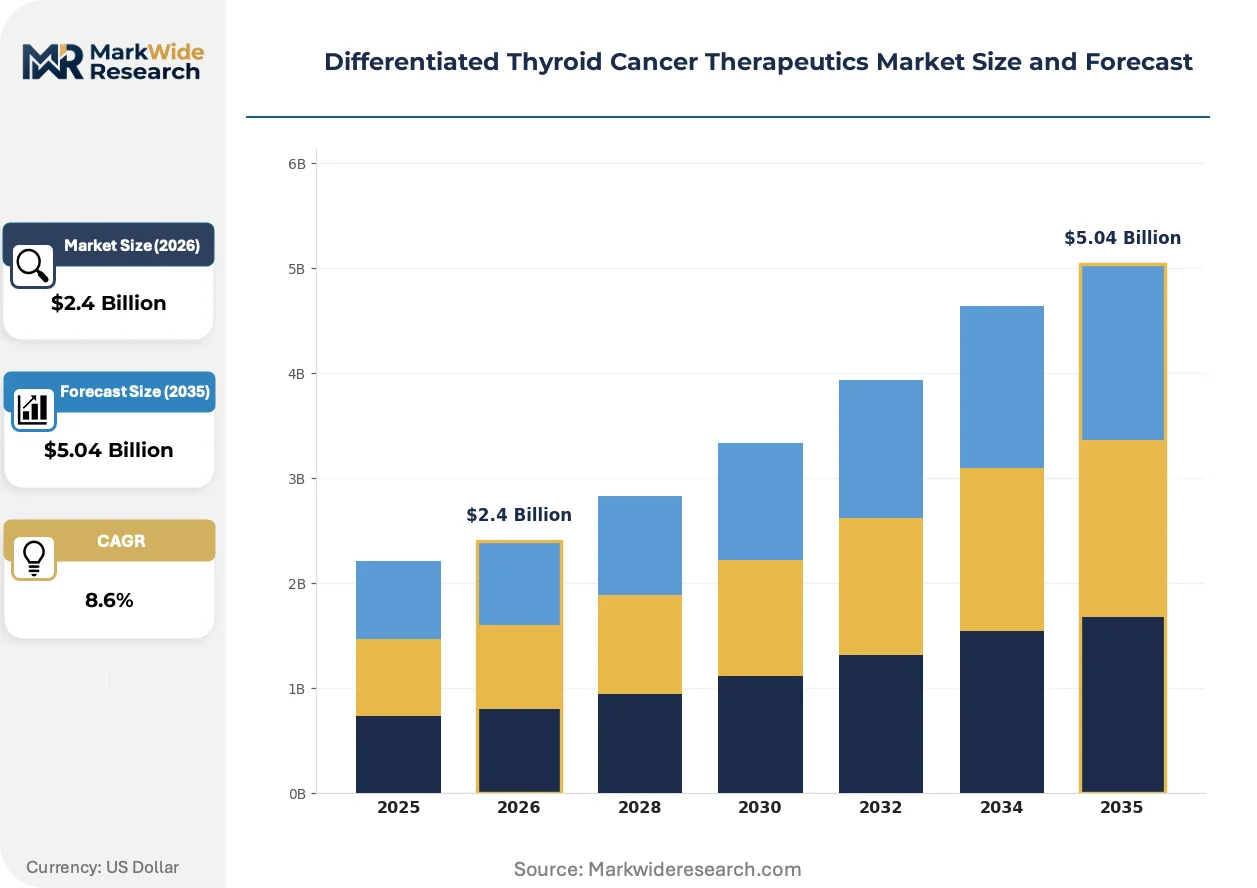
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
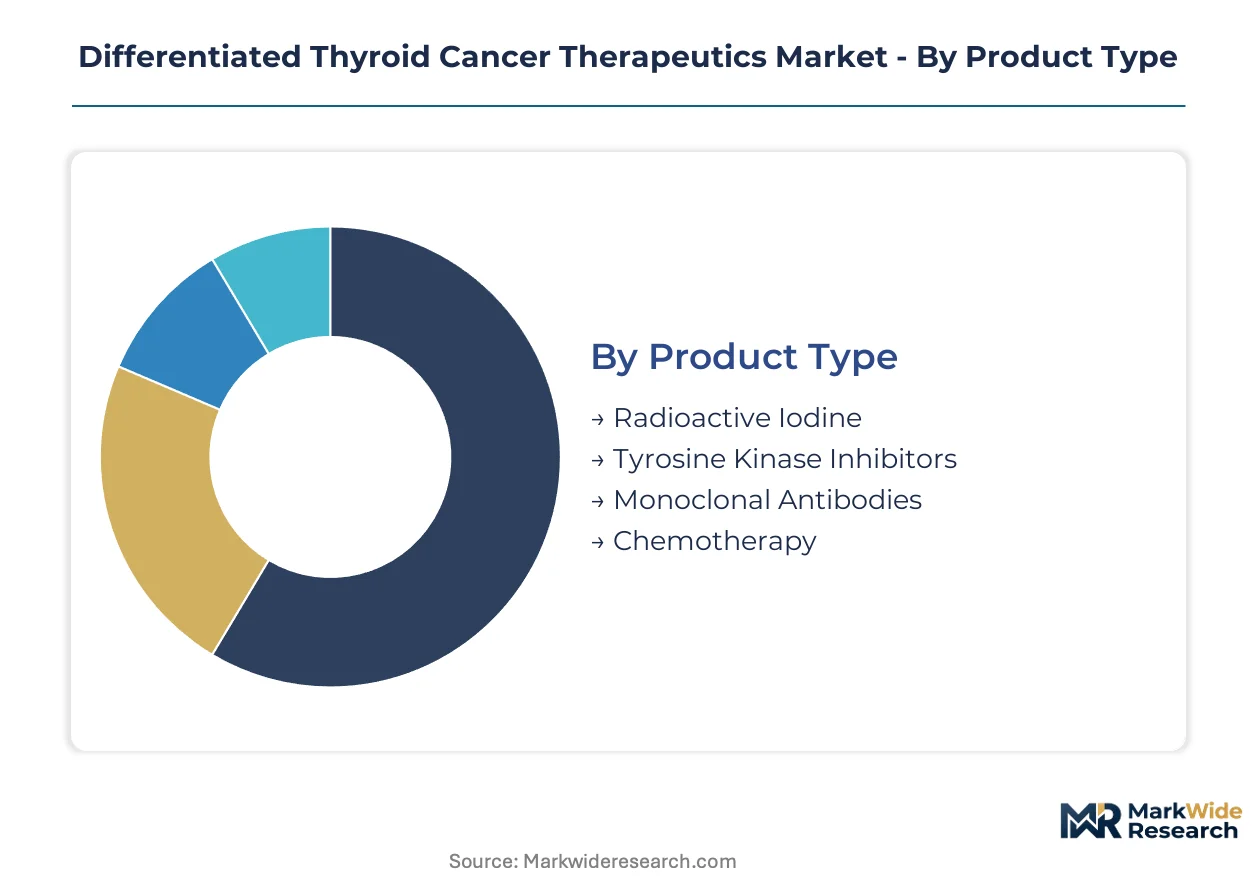
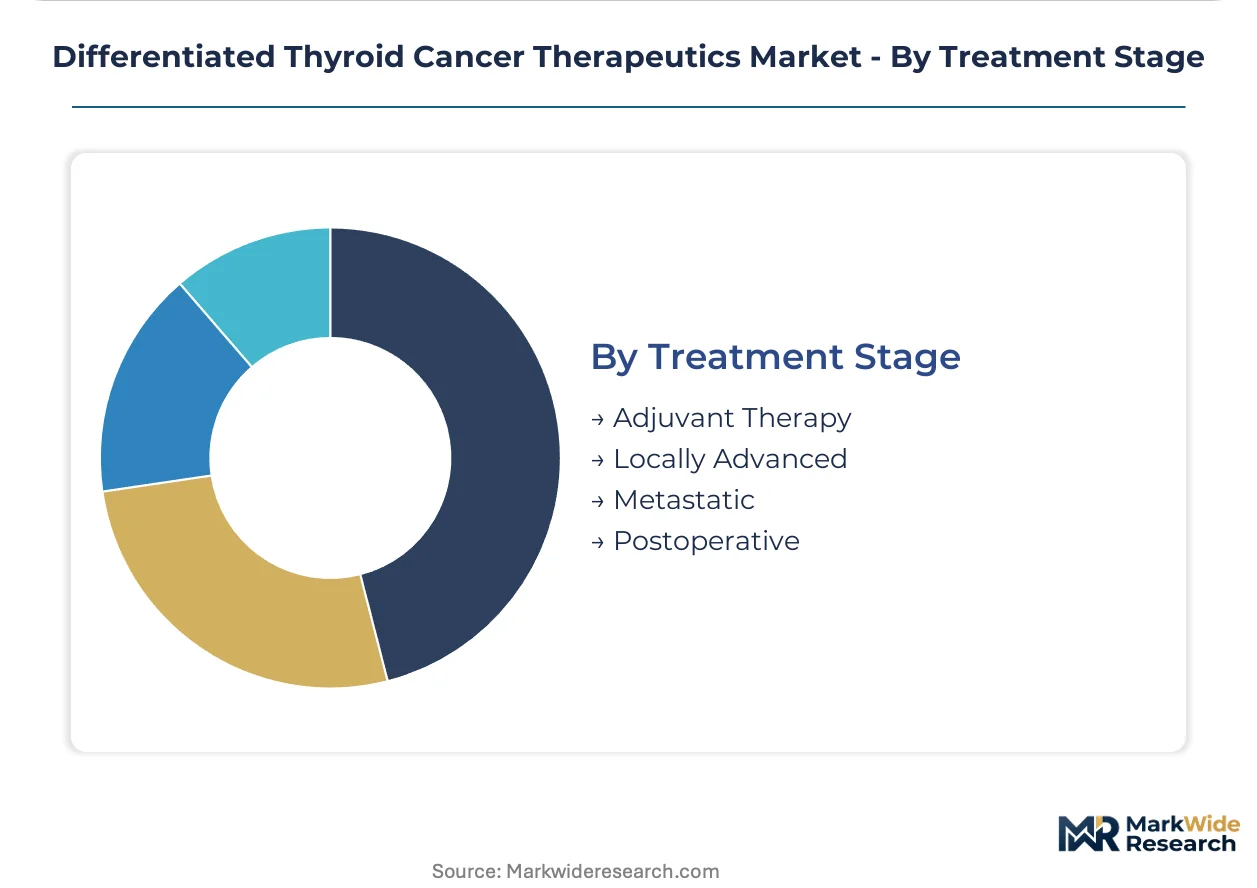
| Segmentation | Product Type: Radioactive Iodine, Tyrosine Kinase Inhibitors, Monoclonal Antibodies, Chemotherapy Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Oncology Centers, Outpatient Clinics, Research Institutions Treatment Stage: Adjuvant Therapy, Locally Advanced, Metastatic, Postoperative |
| Companies Covered | Sanofi, Novartis, Bayer, Blueprint Medicines, Genentech, Eisai, Curium Pharma, Loxo Oncology, Exelixis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Differentiated Thyroid Cancer Therapeutics Market Strategic Shifts
Mechanistic understanding of resistance pathways is fragmenting the historical radioactive iodine monolith into segmented salvage therapy sequences, reshaping both clinical trial design and commercial infrastructure requirements.
Selective RET inhibitors are overtaking multikinase VEGFR blockers as the mechanistic preference for fusion-positive disease, with academic medical centers prioritizing genomic stratification ahead of empirical tyrosine kinase inhibitor initiation. Patient advocacy networks are demanding front-line biomarker testing, compressing the interval between diagnosis and targeted therapy assignment. This molecular triage is compressing the addressable population for empirical sorafenib or lenvatinib prescribing.
EMA's PRIME designation pathway is accelerating conditional marketing authorization timelines for novel agents in rare thyroid malignancy subsets, compressing the evidentiary gap between Phase I activity signals and reimbursed access. Sponsors are structuring rolling review submissions to exploit this regulatory velocity. European reference pricing systems are responding with early cost-effectiveness assessments that condition full reimbursement on confirmatory overall survival data.
Hospital outpatient departments are losing oral kinase inhibitor dispensing volumes to contracted specialty pharmacies with integrated risk management capabilities. Payers are mandating these channel shifts through narrow network pharmacy carve-outs. The United States exhibits the most pronounced channel migration, though European hospital pharmacy retention remains stronger due to national health system procurement centralization.
Differentiated Thyroid Cancer Therapeutics Market Segmentation
Precision in therapeutic segmentation determines capital allocation across manufacturing infrastructure, regulatory submission pathways, and reimbursement negotiation strategies. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Capital intensity peaks with radiopharmaceutical production, where dedicated isotope handling facilities and cyclotron networks demand nine-figure infrastructure commitments.
- Radioactive Iodine:Iodine-131 formulations require specialized cleanroom suites and nuclear medicine technologist certification programs. Demand concentrates in United States hospital networks where bundled reimbursement supports ablation protocols, though molybdenum-99 supply fragility constrains capacity expansion.
- Tyrosine Kinase Inhibitors:Small-molecule kinase inhibitors targeting VEGFR/RET signaling pathways command premium pricing in radioiodine-refractory populations. Oncology centers in the United States drive off-label utilization ahead of formal indication expansion, with oral bioavailability enabling outpatient dispensing migration.
- Monoclonal Antibodies:Biologic manufacturing requires mammalian cell culture capacity with extended development timelines.
- Chemotherapy:Genericized cytotoxic agents compete on cost in salvage sequencing.
Most installed capacity flows through radioactive iodine production. Expansion is steepest in tyrosine kinase inhibitors.
Delivery Mode:
Route of administration dictates site-of-care economics and reimbursement capture, with infused therapies anchoring hospital revenue pools against oral convenience pressures.
- Intravenous:Infusion-dependent biologics and radiopharmaceuticals require hospital-based administration with specialized handling protocols. Oncology centers capture bundled payments for supervised delivery, though staffing certification bottlenecks constrain suite expansion timelines.
- Oral:Kinase inhibitor tablets enable outpatient dispensing through specialty pharmacy channels. Patient preference for convenience accelerates volume migration away from hospital outpatient departments in the United States, compressing traditional infusion revenue streams.
- Subcutaneous:Limited current application in thyroid malignancy protocols.
- Intramuscular:Minimal penetration in differentiated thyroid cancer treatment algorithms.
Hospital infrastructure investment concentrates on intravenous delivery suites. Patient channel preferences are shifting fastest toward oral administration.
End User:
Customer type determines procurement sophistication and pricing leverage, with consolidated oncology networks extracting volume discounts unavailable to fragmented outpatient settings.
- Hospitals:Integrated delivery networks maintain radiopharmaceutical handling licenses and nuclear medicine departments. Academic medical centers in the United States prioritize biomarker stratification protocols, anchoring demand for precision therapy enrollment.
- Oncology Centers:Dedicated cancer facilities capture deepest margin pools through bundled infusion reimbursement and required monitoring protocols. Consolidated purchasing across multi-site networks enables formulary tier placement negotiations.
- Outpatient Clinics:Limited to oral therapy dispensing with restricted access to isotope-based protocols.
- Research Institutions:Phase I/II trial sites drive early adoption of novel kinase inhibitors.
Procurement volume concentrates through hospital networks. Oncology centers are gaining share fastest in oral therapy management.
Treatment Stage:
Disease progression anchoring determines therapy sequencing and duration economics, with metastatic populations offering extended treatment windows against curative-intent adjuvant protocols.
- Adjuvant Therapy:Post-thyroidectomy radioactive iodine ablation targets remnant tissue elimination. United States protocols emphasize recurrence risk stratification, with intermediate-risk patients representing the addressable population for extended adjuvant kinase inhibitor trials.
- Metastatic:Distant disease mandates systemic salvage therapy with progression-free survival as the primary endpoint. Radioiodine-refractory status accelerates targeted agent sequencing, with RET fusion testing guiding selective inhibitor assignment.
- Locally Advanced:Unresectable locoregional disease requires neoadjuvant or definitive systemic approaches.
- Postoperative:Surveillance protocols with levothyroxine suppression dominate low-risk populations.
Clinical trial infrastructure concentrates on metastatic populations. Adjuvant therapy expansion is climbing the fastest with biomarker-driven enrollment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping radiopharmaceutical production location decisions, with manufacturers migrating capacity toward jurisdictions offering streamlined isotope handling certification and orphan drug incentive alignment. The cost-of-compliance gap between FDA-administered United States protocols and EMA REACH frameworks is driving site selection toward North American hospital network partnerships.
United States
Oncology centers in the United States drive off-label utilization of next-generation kinase inhibitors for radioiodine-refractory populations. FDA's orphan drug designation pathway compresses development timelines for novel agents targeting rare thyroid malignancy subsets. Academic medical centers in Boston and Houston prioritize biomarker stratification protocols, anchoring demand for precision therapy enrollment and RET fusion testing infrastructure.
Germany
German hospital networks maintain concentrated radiopharmaceutical handling capabilities amid ECHA REACH compliance requirements that constrain manufacturing site flexibility. EMA's PRIME designation accelerates conditional marketing authorization timelines for novel kinase inhibitors. The Rhine-Ruhr industrial corridor hosts specialized cleanroom facilities serving iodine-131 ablation protocols across consolidated purchasing networks.
Japan
PMDA's Sakigake breakthrough designation framework offers parallel fast-track entry for novel RET inhibitors ahead of Western regulatory timelines. METI coordinates national isotope supply security initiatives addressing molybdenum-99 import dependency. Tokyo and Osaka anchor clinical trial infrastructure for differentiated thyroid cancer targeted therapy development, with academic medical centers driving genomic stratification adoption.
Switzerland
Swissmedic maintains stringent radiopharmaceutical manufacturing standards that favor established producers with dedicated isotope supply agreements. The Basel pharmaceutical cluster concentrates kinase inhibitor development expertise, leveraging proximity to European reference pricing systems. Swiss hospital networks capture premium reimbursement for precision therapy protocols through bundled payment structures.
India
CDSCO's accelerated approval pathways for orphan indications are attracting contract manufacturing investment for oral tyrosine kinase inhibitor production. The country's national pharmaceutical regulator harmonizes with ICH guidelines to streamline clinical trial initiation. Hyderabad and Ahmedabad host active pharmaceutical ingredient facilities supplying global TKI programs, with Maharashtra-based oncology centers expanding biomarker testing capabilities.
Differentiated Thyroid Cancer Therapeutics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue selective kinase inhibition mechanisms and radioligand infrastructure specialization. The vendor base stratifies across three maturity tiers: diversified pharmaceutical conglomerates with broad oncology portfolios, mid-cap biotech specialists concentrating on rare malignancy subsets, and radiopharmaceutical pure-plays with captive isotope supply agreements. Dominant competitive moves include strategic partnerships securing cyclotron network access and portfolio diversification into combination regimen development.
Within the diversified pharmaceutical tier, Sanofi leverages radioligand infrastructure across hospital networks, while Novartis sustains oncology portfolio depth competing across multiple solid tumor indications. Eisai anchors presence through targeted agent development specializing in kinase inhibition mechanisms. These three exemplify distinct strategic archetypes: isotope supply chain integration, broad indication diversification, and mechanism-focused specialization respectively.
| Leading Market Players |
|---|
| Sanofi |
| Novartis |
| Bayer |
| Blueprint Medicines |
| Genentech |
| Eisai |
| Curium Pharma |
| Loxo Oncology |
| Exelixis |
| Others |
Value Chain & Pricing Dynamics
Orphan drug designation tiers bifurcate the market into premium kinase inhibitors commanding formulary placement and commoditized radioactive iodine protocols facing reimbursement compression, with each tier demanding distinct manufacturing footprints and distribution certifications. FDA fast-track premiums sustain pricing power for RET-selective agents in the United States, while EMA REACH compliance costs elevate European radiopharmaceutical production thresholds and consolidate supply among incumbent isotope handlers.
Pricing Analysis
Hospital outpatient markup layers anchor pricing for infused radiopharmaceuticals, with oncology centers capturing bundled reimbursement premiums that oral kinase inhibitors cannot replicate through specialty pharmacy channels. Price differentiation rests on biomarker stratification status and orphan drug exclusivity duration, with RET fusion-positive indications sustaining premium positioning against empirical VEGFR blockade. Pricing pressure intensifies in the radioactive iodine segment as molybdenum-99 supply fragility elevates production costs without corresponding reimbursement adjustment. Academic medical centers exhibit lowest price sensitivity due to research funding offsets, while community oncology networks face constrained formulary budgets.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor radiopharmaceutical cold-chain logistics, with hub-and-spoke patterns radiating from cyclotron-equipped hospital networks to satellite infusion suites. Active pharmaceutical ingredient production draws from India and China for oral tyrosine kinase inhibitor tablet manufacturing, while isotope precursor dependence rests on aging reactors in Canada, the Netherlands, and South Africa. Single-source vulnerability in molybdenum-99 supply concentrates risk exposure for iodine-131 therapy continuity. Distribution runs through hospital pharmacy procurement for infused agents and contracted specialty pharmacy networks for oral regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The differentiated thyroid cancer therapeutics market compounds value through successive regulatory designations, with FDA orphan drug incentives and EMA PRIME pathways accelerating development timelines and sustaining pricing premiums for mechanistically novel agents.
For Market Incumbents: Deploy biomarker stratification infrastructure to defend formulary position against multikinase VEGFR commoditization, while securing captive isotope supply agreements to mitigate molybdenum-99 outage exposure. Incumbent radiopharmaceutical producers must expand cyclotron network partnerships before emerging entrants capture hospital licensing capacity. Threat substitution from oral TKI convenience demands infusion-suite service bundling to retain hospital revenue capture. For New Entrants and Emerging Players: Capture combination regimen white space in anaplastic transformation sequencing, where immunotherapy-targeted agent pairing remains clinically unaddressed and trial infrastructure is sparse. Japan's Sakigake fast-track offers parallel regulatory entry ahead of Western timelines for RET-selective mechanisms. Go-to-market positioning through academic medical center biomarker testing protocols enables precision patient identification and payer value demonstration. For Investors and Strategic Acquirers: Consolidation pressure builds where radioligand infrastructure scarcity intersects with kinase inhibitor pipeline maturity, favoring targets with dual manufacturing capabilities. Long-term viability hinges on portfolio diversification across salvage therapy sequences rather than single-mechanism dependence. Watch for progression-free survival endpoint disputes resolving across FDA, EMA, and PMDA as the signal for regulatory submission sequencing clarity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA PRIME designation compresses conditional marketing authorization timelines for rare thyroid malignancy subsets. |
| Manufacturing Scale-Up | Cyclotron capacity expansion in United States hospital networks secures isotope handling certification pipelines. |
| Pipeline Diversification | RET and NTRK fusion inhibitor development reduces empirical VEGFR blockade exposure. |
| Hospital System Partnership | Academic medical center alliances anchor biomarker stratification protocol adoption and precision enrollment. |
| Licensing Agreement | Isotope supply contracts with Canadian and European reactor operators mitigate molybdenum-99 concentration risk. |
Study Parameters
Coverage spans the United States, Germany, Japan, Switzerland, and India, with primary inputs from each market's regulatory and clinical stakeholder base. Drug development executives, regulatory affairs leads, formulary directors at oncology centers, and hospital procurement managers provided qualitative intelligence through structured interviews. Secondary validation drew from FDA orphan drug filings, EMA PRIME designation records, ClinicalTrials.gov protocol registries, and national formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Granularity-level modeling distinguished treatment stage, product type, delivery mode, and end user segments across the projection horizon, with regional regulatory clusters treated as distinct forecast strata. CAGRs were derived from therapy sequencing pattern analysis and salvage therapy penetration assumptions. Forecast inputs incorporated biomarker testing adoption curves, radioiodine-refractory population incidence, and orphan drug exclusivity expiration schedules.
Regulatory pathway divergence, isotope supply disruption, and biomarker stratification velocity are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Anastrozole Tablets Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Acetylcholine Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Australia Schizophrenia Drugs Market