
 Fucosidosis Therapeutics Market | 2026-2036
Fucosidosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Fucosidosis Therapeutics Market Foresight
Recombinant enzyme manufacturing is realigning cost structures for fucosidosis drug supply. Protalix BioTherapeutics, Inc. leverages plant-cell expression systems to sustain yield advantages in enzyme replacement production. JCR Pharmaceuticals Co., Ltd. anchors Asian distribution through its lysosomal storage disorder franchise. Orchard Therapeutics plc competes on autologous ex vivo gene therapy expertise.
Fucosidosis therapeutics address alpha-L-fucosidase deficiency, a rare autosomal recessive lysosomal storage disorder characterized by glycosphingolipid and oligosaccharide accumulation in tissues, with treatments designed to restore enzymatic activity or modify disease substrate burden. Enzyme replacement therapy dominates current revenue as the most clinically validated modality, while gene therapy represents the fastest-growing segment driven by durable correction potential in early-intervention pediatric populations. Intravenous delivery maintains the largest installed base, though intrathecal administration is gaining traction for neurological manifestation targeting where blood-brain barrier penetration limits systemic dosing efficacy.
FDA orphan drug designation and EMA PRIME eligibility shape clinical development economics by granting protocol assistance, fee waivers, and market exclusivity incentives for fucosidosis programs. The EU AI Act and GDPR impose data governance requirements on gene therapy patient registries and real-world evidence collection platforms. Stakeholders must monitor regulatory convergence between FDA and EMA on gene therapy manufacturing standards and long-term follow-up obligations.
Market Dynamics
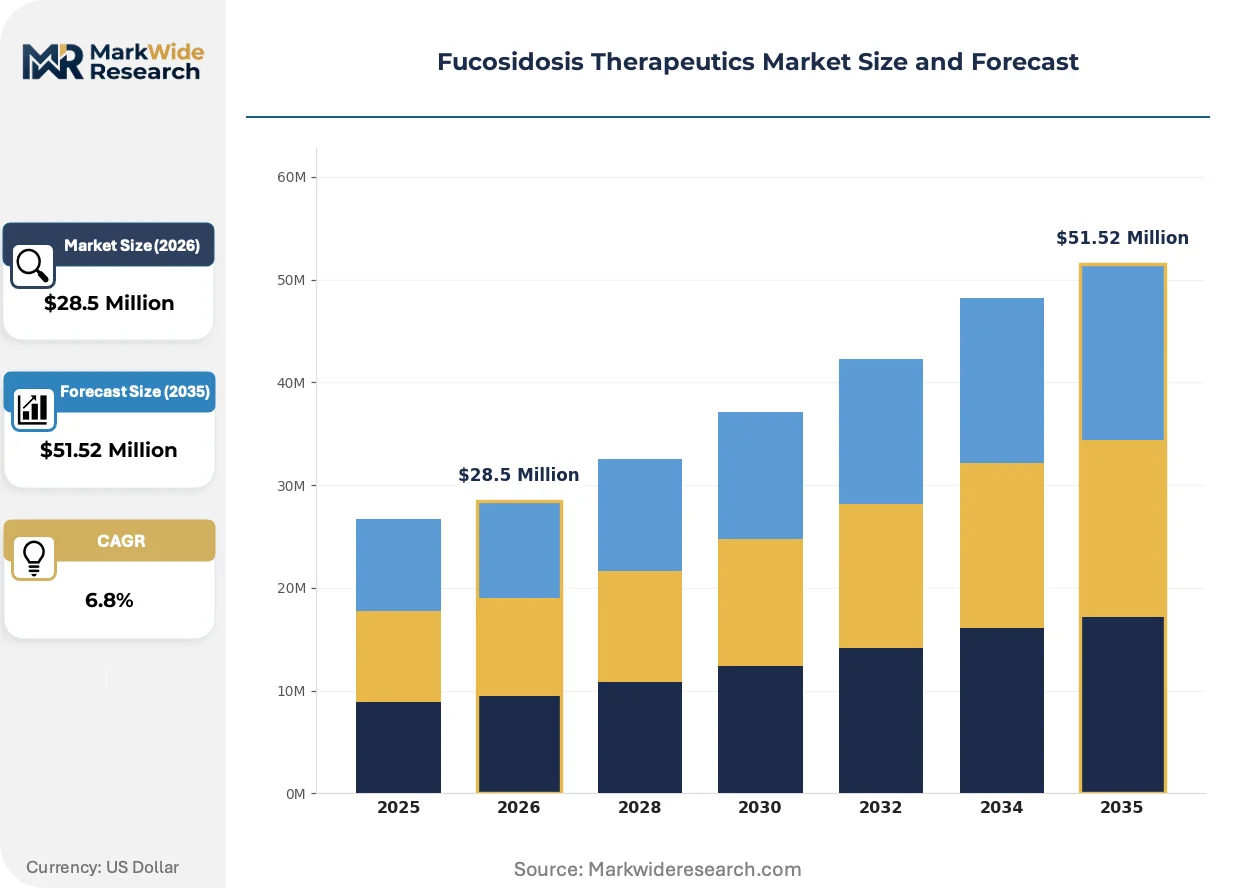
Gene therapy manufacturing scale-up is compressing development timelines for fucosidosis treatments, while FDA and EMA convergence on long-term follow-up protocols reshapes clinical trial economics for rare lysosomal storage disorders.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity and tax credits for clinical trial expenditures incentivize biotech investment in ultra-rare enzyme deficiencies. Pediatric metabolic centers expand screening capacity.
- EMA PRIME Designation:Accelerated assessment pathways and enhanced regulatory dialogue reduce time-to-market for innovative therapies addressing unmet medical need in fucosidosis.
- Next-generation sequencing:Expanded newborn screening panels in tertiary care hospitals enable presymptomatic identification, shifting treatment initiation to earlier disease stages with improved efficacy potential.
Market Restraints
- Recombinant enzyme production costs:Mammalian cell culture systems require expensive media components and extensive purification, limiting manufacturing flexibility for low-volume rare disease indications.
- Centralized gene therapy manufacturing:Autologous ex vivo processing depends on a handful of GMP-compliant facilities in the United States and Germany, creating supply vulnerability and logistics complexity.
- Blood-brain barrier penetration:Systemic enzyme replacement fails to address neurological manifestations, constraining therapeutic efficacy in progressive neurodegenerative disease forms.
Strategic Opportunities
- Intravenous-to-intrathecal delivery transition:Direct CNS administration protocols open addressable market expansion for neurological indication subsets previously deemed untreatable.
- Japan's Sakigake designation:Priority review and dedicated consultation pathways attract sponsor investment for early-entry gene therapy development in Asia-Pacific.
- Real-world evidence integration:Patient registry platforms capturing long-term outcomes data support label expansion and reimbursement negotiations with health technology assessment bodies.
Industry Challenges
- Gene therapy vector manufacturing expertise:Lentiviral and AAV production requires specialized bioprocess engineering talent scarce in conventional pharmaceutical operations.
- Cross-border clinical trial coordination:Divergent national requirements for gene therapy long-term follow-up create administrative burden and patient tracking complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fucosidosis Therapeutics Market |
| Market Size in 2026 | $28.5 Million |
| Market Size in 2035 | $51.52 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Substrate Reduction Therapy, Gene Therapy, Symptomatic Treatment Application: Neurological Manifestations, Skeletal Abnormalities, Respiratory Complications, Cardiovascular Involvement End User: Specialty Clinics, Pediatric Centers, Research Institutions, Home Care Providers Delivery Mode: Intravenous, Oral, Intrathecal, Subcutaneous |
| Companies Covered | Merck KGaA, JCR Pharmaceuticals Co., Ltd., Orchard Therapeutics plc, Protalix BioTherapeutics, Inc., Magenta Therapeutics, Evotec SE, Jasper Therapeutics, Inc., Hemogenyx Pharmaceuticals plc, Garuda Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fucosidosis Therapeutics Market Shifts & Advancements
Manufacturing platform diversification and regulatory science advancement are converging to reshape competitive economics in rare disease therapeutics, with particular pressure on traditional enzyme replacement paradigms.
Plant-cell expression systems are decentralizing recombinant protein production economics. Protalix BioTherapeutics leverages carrot-cell bioreactors to achieve higher yields at reduced capital intensity compared to mammalian platforms. Biotech sponsors evaluating manufacturing partnerships increasingly prioritize this technology for lysosomal enzyme programs.
EMA's evolving stance on gene therapy comparability protocols is forcing sponsors to invest earlier in analytical method development. The regulator's draft guidelines on post-approval manufacturing changes require extensive characterization data, extending validation timelines. European developers are responding by embedding quality-by-design principles into early-phase CMC strategies.
Pediatric treatment centers are consolidating procurement decisions through specialized metabolic disease networks. Individual hospital pharmacy committees cede purchasing authority to centralized formulary committees at academic medical centers in the United States and Germany. This concentration shifts negotiating leverage toward integrated delivery networks with gene therapy administration capabilities.
Fucosidosis Therapeutics Market Segmentation
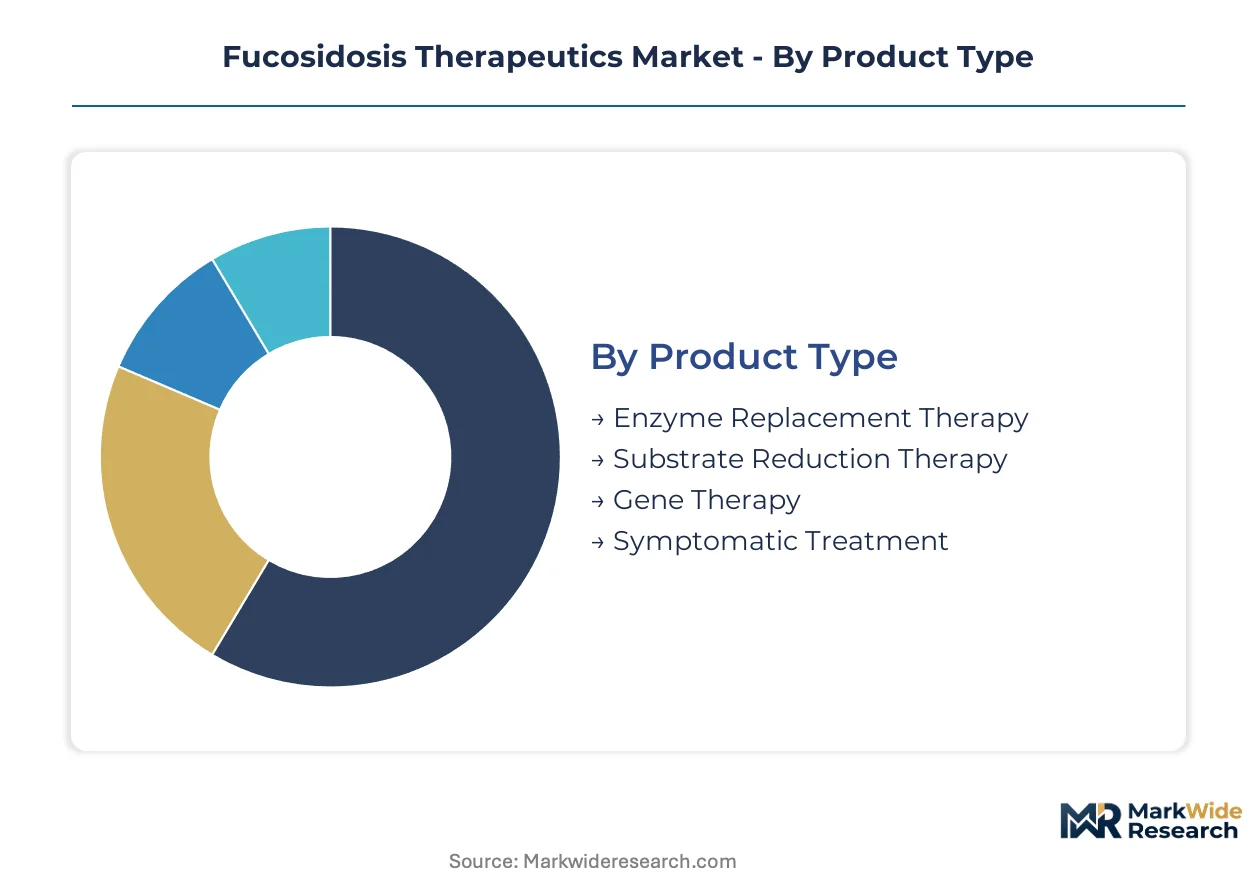
Therapeutic modality selection in fucosidosis hinges on disease stage, organ system involvement, and blood-brain barrier penetration requirements. Segmentation reveals how treatment pathways diverge between systemic enzyme replacement and targeted CNS interventions.
Product Type:
Enzyme replacement functions as a standalone systemic intervention, while gene therapy embeds within specialized pediatric metabolic centers requiring integrated manufacturing and administration infrastructure.
- Enzyme Replacement Therapy:Recombinant alpha-L-fucosidase administered intravenously to clear accumulated glycosphingolipids from peripheral tissues. Demand concentrates in tertiary pediatric centers across the United States and Germany where lysosomal storage disorder networks maintain infusion capacity and specialized nursing protocols.
- Gene Therapy:Autologous ex vivo lentiviral vector approaches delivering functional FUCA1 gene copies to hematopoietic stem cells. Clinical programs at academic medical centers in Boston and London are driving protocol development for early-intervention pediatric cohorts with the strongest durable correction potential.
- Substrate Reduction Therapy:Small-molecule inhibitors targeting glycosphingolipid synthesis pathways as adjunctive or bridge therapy.
- Symptomatic Treatment:Supportive care modalities addressing seizures, respiratory insufficiency, and skeletal complications without modifying disease progression.
Enzyme replacement leads volumes today; gene therapy is gaining share fastest.
Application:
Manifestation-driven segmentation reflects the organ-specific pathology of fucosidosis, with neurological involvement commanding premium pricing due to unmet need and administration complexity.
- Neurological Manifestations:Progressive neurodegeneration including intellectual disability, seizures, and motor deterioration arising from CNS substrate accumulation. Pediatric neurology departments at institutions in Philadelphia and Munich are expanding intrathecal delivery programs to address blood-brain barrier limitations of systemic therapy.
- Skeletal Abnormalities:Dysostosis multiplex and joint contractures from bone marrow and connective tissue storage. Orthopedic surgery units in Toronto and Sydney are developing multidisciplinary protocols combining enzyme therapy with skeletal surveillance.
- Respiratory Complications:Recurrent infections and restrictive lung disease from thoracic skeletal changes and tissue infiltration.
- Cardiovascular Involvement:Valvular thickening and cardiomyopathy from glycosphingolipid deposition in cardiac tissues.
Neurological applications command the highest per-patient expenditure; skeletal indications show steadiest enrollment growth.
End User:
Site-of-care decisions balance clinical complexity against reimbursement incentives, with high-acuity gene therapy concentrating at academic hubs while maintenance enzyme therapy disperses toward community settings.
- Pediatric Centers:Integrated metabolic disease programs combining genetics, neurology, and orthopedics for comprehensive fucosidosis management. Major children's hospitals in Chicago and Paris anchor regional referral networks with newborn screening follow-up capacity.
- Specialty Clinics:Lysosomal storage disorder-focused outpatient facilities handling stable patients on maintenance enzyme regimens.
- Research Institutions:Academic medical centers conducting gene therapy trials and longitudinal natural history studies.
- Home Care Providers:Infusion nursing services enabling subcutaneous or intravenous enzyme administration outside hospital settings.
Pediatric centers dominate patient volume; home care channels are expanding most quickly as infusion protocols standardize.
Delivery Mode:
Route selection determines tissue distribution, with intravenous maintaining broad applicability while intrathecal addresses the CNS compartment that systemic dosing cannot reach.
- Intravenous:Established administration pathway for enzyme replacement with decades of clinical validation and payer familiarity. Hospital infusion centers in Cleveland and Hamburg process the highest patient volumes through standardized scheduling and pharmacy compounding relationships.
- Intrathecal:Direct cerebrospinal fluid delivery via lumbar puncture or intraventricular reservoir for CNS-targeted therapy. Neurosurgery and anesthesia collaboration requirements limit deployment to quaternary centers in New York and Zurich with specialized procedural expertise.
- Oral:Substrate reduction therapy and supportive medications avoiding parenteral administration burden.
- Subcutaneous:Emerging enzyme delivery alternative under investigation for reduced infusion center dependency.
Intravenous administration retains the largest installed base; intrathecal protocols are climbing the fastest as neurological indication development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors gene therapy development for lysosomal storage disorders, drawing pediatric metabolic specialists and vector manufacturing investment. The United States and Germany concentrate reimbursement infrastructure for rare disease therapeutics.
United States
FDA orphan drug tax credits and seven-year exclusivity provisions incentivize biotech sponsors to pursue fucosidosis programs through accelerated approval pathways. The National Institutes of Health maintains a dedicated lysosomal storage disease research consortium. Philadelphia's Children's Hospital anchors intrathecal delivery protocol development for neurological manifestation targeting.
Germany
EMA PRIME designation and national disease management programs for rare metabolic disorders expand treatment access for pediatric populations. The country's statutory health insurance system reimburses gene therapy through outcome-based agreements negotiated at the federal level. Munich's university hospitals coordinate a southern German referral network for enzyme replacement therapy administration.
Japan
PMDA Sakigake priority review pathways compress regulatory timelines for innovative therapies addressing ultra-rare enzyme deficiencies. The Ministry of Health, Labour and Welfare maintains a designated orphan drug subsidy program covering 70 percent of treatment costs. Tokyo's National Center for Child Health and Development leads newborn screening expansion for lysosomal storage disorders.
United Kingdom
NICE technology appraisals and NHS England's specialized commissioning framework determine access to high-cost gene therapies for metabolic diseases. The UK Rare Diseases Framework mandates coordinated care pathways across regional genetics networks. London's Great Ormond Street Hospital hosts a national fucosidosis natural history study capturing longitudinal outcomes data.
Switzerland
Swissmedic's expedited access pathway and federal orphan drug reimbursement provisions attract clinical trial investment for pediatric rare diseases. The country's mandatory health insurance system includes a distinct category for innovative high-cost therapeutics. Basel's pharmaceutical cluster houses contract manufacturing organizations specializing in lentiviral vector production for gene therapy programs.
Fucosidosis Therapeutics Market Competitive Landscape
Strategic partnerships dominate the current landscape as enzyme manufacturers seek vector production capabilities and gene therapy developers secure distribution networks. The market structures around three distinct tiers: large-cap diversified pharmaceutical companies with rare disease franchises, mid-cap biotechnology firms specializing in lysosomal storage disorders, and emerging gene therapy platforms built on academic spinout technology. Two strategic archetypes predominate: plant-cell expression specialists competing on manufacturing cost structure, and autologous ex vivo gene therapy developers competing on durable correction claims. Capacity expansion and regulatory science investment constitute the dominant competitive moves.
Within the plant-cell expression archetype, Protalix BioTherapeutics, Inc. occupies a position representing alternative bioprocess platforms for recombinant enzyme supply. Among gene therapy developers, Orchard Therapeutics plc exemplifies the autologous ex vivo lentiviral approach targeting hematopoietic stem cell modification. JCR Pharmaceuticals Co., Ltd. anchors the Asia-Pacific distribution specialist tier, representing regional commercialization capabilities for lysosomal storage disorder therapeutics.
| Leading Market Players |
|---|
| Merck KGaA |
| JCR Pharmaceuticals Co., Ltd. |
| Orchard Therapeutics plc |
| Protalix BioTherapeutics, Inc. |
| Magenta Therapeutics |
| Evotec SE |
| Jasper Therapeutics, Inc. |
| Hemogenyx Pharmaceuticals plc |
| Garuda Therapeutics |
| Others |
Supply & Pricing Matrix
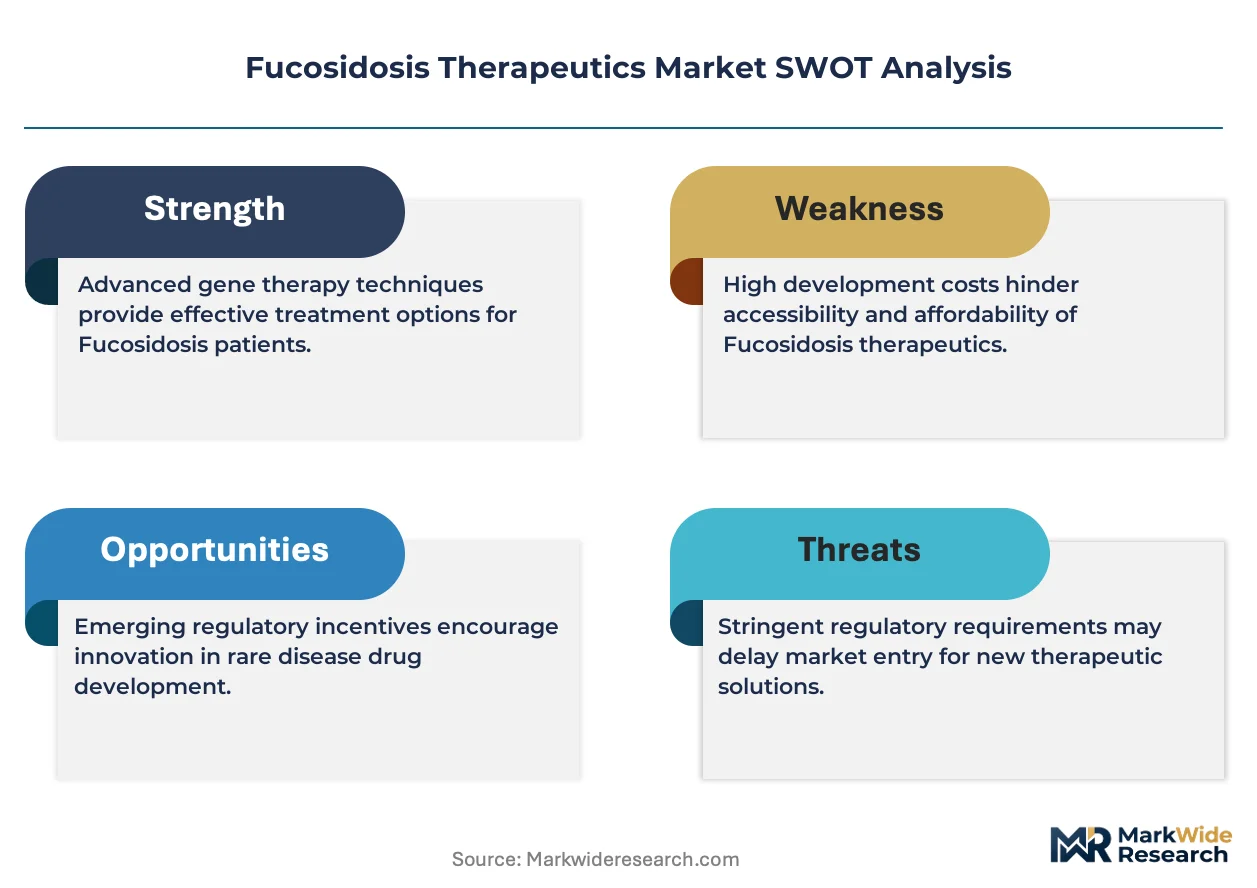
Recombinant enzyme production costs cascade through fucosidosis therapeutics pricing tiers, with mammalian cell culture media expenses and GMP facility overhead concentrating margin pressure on manufacturers serving low-volume rare disease populations before reaching academic medical center procurement committees.
Pricing Analysis
Input-cost pass-through from specialized bioreactor operations and lentiviral vector manufacturing compresses margins for gene therapy developers while sustaining premium positioning for neurological indication subsets. Three-tier pricing structure across gene therapy, intrathecal enzyme replacement, and standard intravenous infusion reflects administration complexity and blood-brain barrier penetration requirements. Cost compression in intravenous enzyme replacement intensifies as plant-cell expression platforms achieve yield parity at reduced capital intensity. Pediatric metabolic centers exhibit highest price sensitivity due to bundled reimbursement constraints, while quaternary academic hubs with gene therapy administration capabilities demonstrate lowest sensitivity for curative modality access.
Supply Chain Analysis
Single-source vulnerability sits with United States and German GMP-compliant facilities for autologous ex vivo gene therapy processing, creating logistical complexity for cross-border patient sample transport. Raw material dependencies span fetal bovine serum for mammalian culture, specialized chromatography resins for enzyme purification, and plasmid DNA for lentiviral vector backbone production. Tariff exposure on temperature-controlled biologics logistics amplifies supply risk for Asia-Pacific patient access. Distribution runs through centralized pharmacy compounding at academic medical centers with specialized metabolic disease nursing protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fucosidosis therapeutics offer margin expansion potential as plant-cell expression platforms compress manufacturing costs and neurological indication development commands premium pricing tiers previously inaccessible to systemic therapy.
For Market Incumbents: Anticipate displacement pressure from autologous gene therapy developers by securing lentiviral vector manufacturing partnerships or in-house production capabilities before FDA long-term follow-up protocols harden competitive moats. Backward integration into hematopoietic stem cell collection and cryopreservation services defends position against emerging platform competitors targeting integrated care delivery. For New Entrants and Emerging Players: Begin with intrathecal delivery protocol development for neurological manifestation subsets where blood-brain barrier limitations have constrained incumbent enzyme replacement efficacy. Japan's Sakigake priority review pathway offers the most penetrable regulatory geography for early gene therapy market entry. A go-to-market angle anchored to real-world evidence generation through patient registry partnerships accelerates reimbursement negotiations with health technology assessment bodies. For Investors and Strategic Acquirers: Consolidation pressure builds where gene therapy manufacturing expertise concentrates in a handful of academic spinout platforms with scarce bioprocess engineering talent. Long-term viability favors developers with demonstrated durable correction in early-intervention pediatric cohorts and established relationships with specialized metabolic disease networks. The signal to watch is EMA draft guideline finalization on post-approval manufacturing changes, which will extend validation timelines and favor incumbents with embedded quality-by-design CMC strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Plant-cell bioreactor deployment at Protalix compresses capital intensity for enzyme supply. |
| Regulatory Approval Pathway | FDA orphan drug tax credits and seven-year exclusivity incentivize ultra-rare disease program pursuit. |
| Clinical Trial Advancement | Intrathecal delivery protocols at Philadelphia's Children's Hospital address blood-brain barrier limitations. |
| Licensing Agreement | Vector manufacturing partnerships enable gene therapy developers to secure GMP capacity without facility construction. |
| Pipeline Diversification | Substrate reduction therapy adjuncts expand addressable population to pre-symptomatic screening-identified patients. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads at FDA and EMA, hospital formulary directors, and payer access specialists grounded qualitative insights, cross-referenced against FDA orphan drug filings, EMA PRIME designation records, ClinicalTrials.gov protocol registries, and specialized metabolic disease network procurement databases. Bottom-up patient volume modeling and top-down therapeutic modality revenue triangulation validated segmentation outputs.
Market size and growth trajectory outputs across the projection horizon reflect disaggregated modeling by therapeutic modality, delivery route, manifestation type, and regional regulatory cluster. CAGRs were derived from patient identification rate projections, treatment initiation assumptions, and pricing evolution by intervention complexity. Forecast inputs incorporated newborn screening expansion timelines, gene therapy manufacturing capacity buildout schedules, and intrathecal protocol adoption curves at quaternary pediatric centers.
Caveats apply where regulatory divergence on gene therapy long-term follow-up obligations, vector manufacturing supply constraints, or reimbursement policy shifts for curative versus chronic therapies could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Global Basal Insulin Market