
 Veterinary CT Imaging Market | 2026-2036
Veterinary CT Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary CT Imaging Market Intelligence
Buyer concentration among multi-site veterinary specialty groups is hardening as private equity-backed platforms consolidate emergency and referral hospitals across metropolitan corridors. GE Healthcare leverages its installed base of human radiology systems to cross-sell veterinary-configured platforms, while Siemens Healthineers sustains R&D intensity in low-dose helical protocols purpose-built for small-animal anatomy. Canon Medical Systems anchors its position through dedicated veterinary sales channels that bypass general imaging distribution.
Veterinary CT imaging deploys X-ray computed tomography with sub-millimeter slice resolution and specialized reconstruction algorithms adapted for non-human skeletal and soft-tissue morphology, enabling precise oncologic staging, orthopedic planning, and trauma assessment in companion and equine patients. Helical CT systems dominate installed value due to their throughput advantage in high-volume emergency settings, while cone beam CT segments capture margin pools in dental and maxillofacial applications where lower radiation dose and compact footprint matter. Mobile CT units represent the fastest-expanding configuration as leasing models and teleradiology partnerships reduce capital barriers for independent practices.
FDA 510(k) premarket notification requirements govern veterinary CT device clearance in the United States, while the EU MDR and CE marking framework enforce post-market surveillance and clinical evidence standards across European Economic Area states. Japan's PMDA maintains distinct pharmaceutical and medical device approval tracks that foreign manufacturers must navigate for market access. Stakeholders should monitor evolving reimbursement codes for advanced veterinary diagnostics and anticipate regulatory convergence pressures as human and veterinary imaging safety standards draw closer.
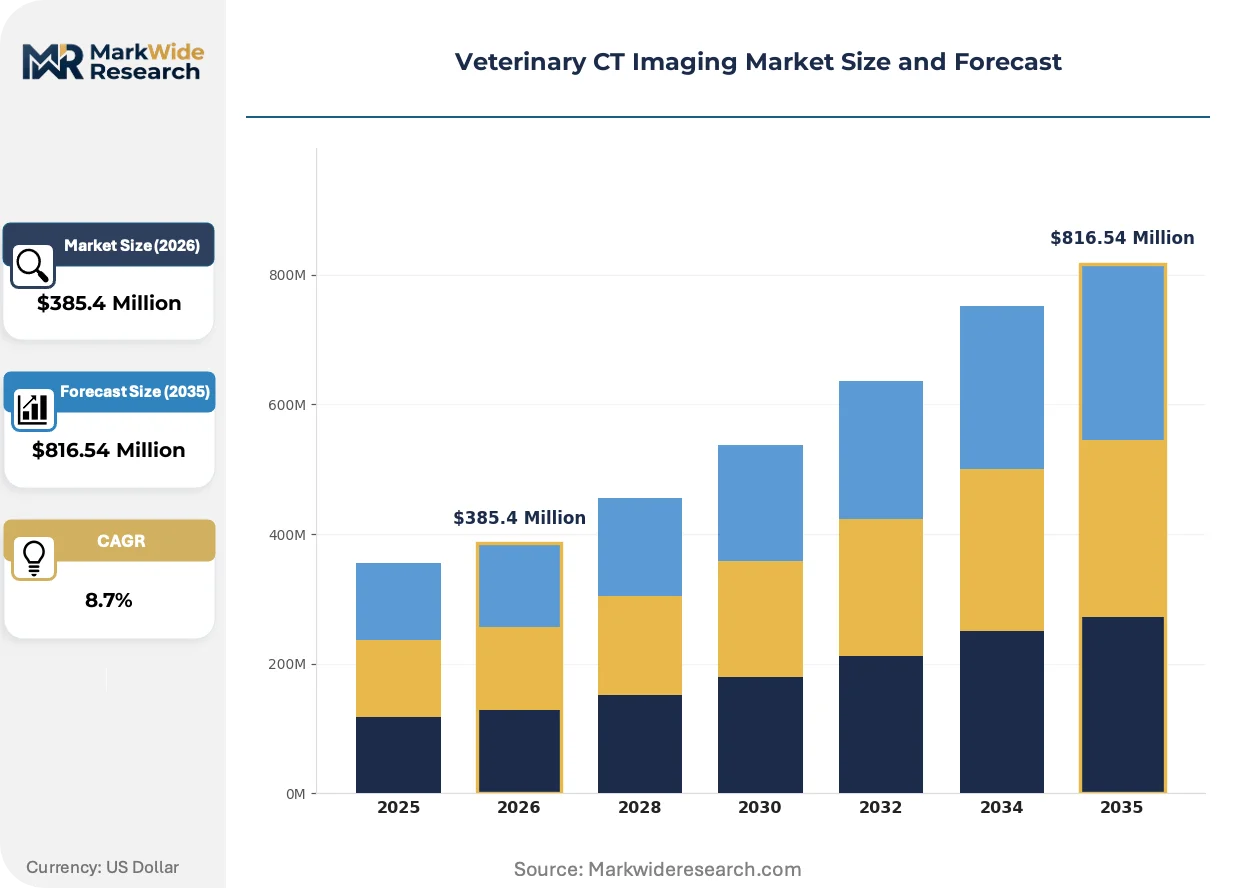
Market Dynamics
Private equity consolidation of multi-site veterinary specialty groups is compressing vendor negotiation cycles and privileging suppliers with national service networks over regional distributors.
Growth Catalysts
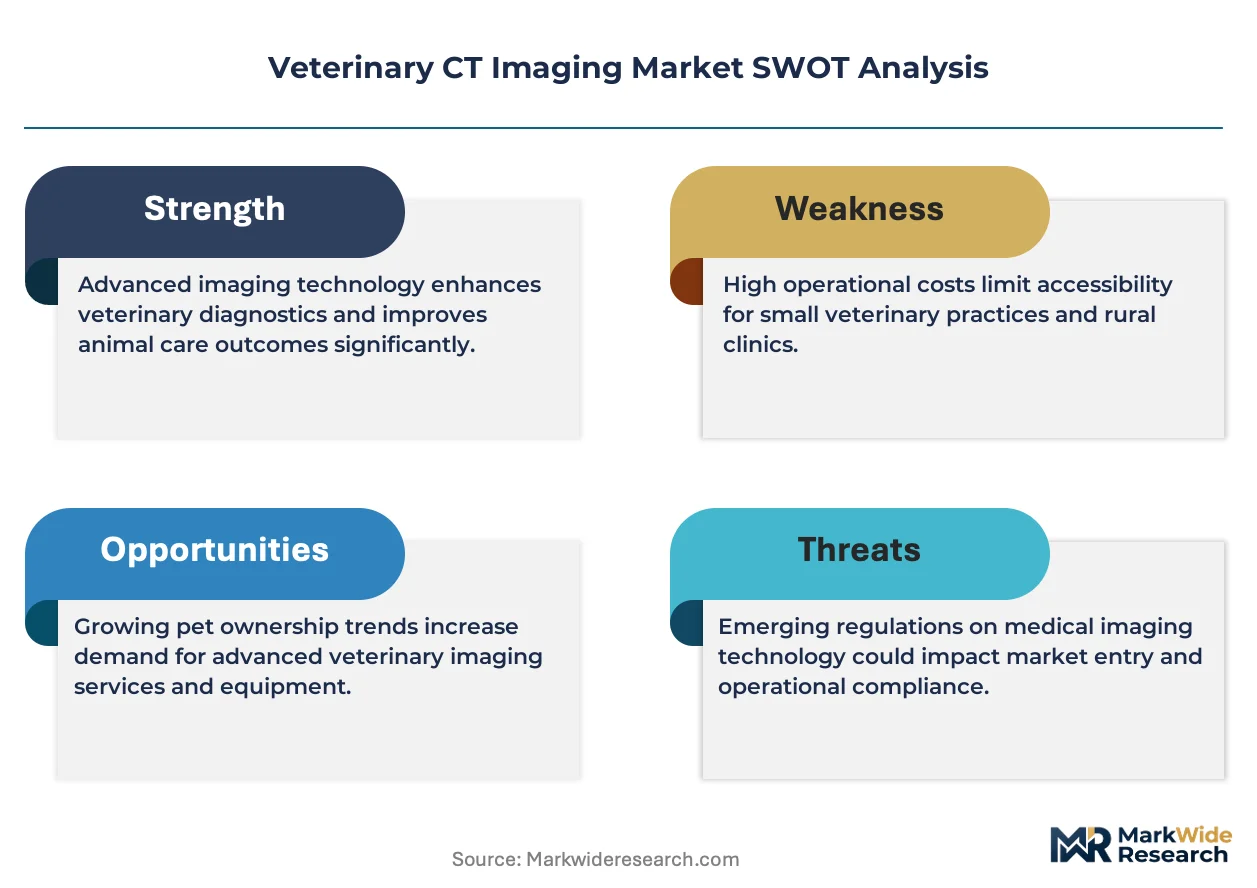
- Pet insurance penetration:Rising policy coverage in the United States and Germany expands the addressable client base for advanced diagnostic procedures previously constrained by out-of-pocket cost sensitivity.
- FDA 510(k) pathway streamlining:Expedited premarket notification for veterinary-configured devices accelerates product commercialization timelines relative to human-equivalent approvals.
- Helical CT throughput advantages:Emergency and trauma centers in high-volume metropolitan corridors prioritize sub-minute scan protocols to maximize equipment utilization rates.
Market Restraints
- Capital intensity of CT suites:Shielding requirements, HVAC specifications, and electrical infrastructure impose six-figure facility modification costs beyond equipment acquisition.
- Isotope supply concentration:Molybdenum-99 production for contrast agents clusters in aging reactors in Canada and the Netherlands, creating vulnerability to unplanned maintenance outages.
- Radiation dose optimization ceilings:ALARA principles for small-animal anatomy hit physical limits where further exposure reduction compromises diagnostic image quality.
Strategic Opportunities
- Mobile CT leasing models:Teleradiology partnerships with independent practices in secondary US metropolitan areas bypass capital barriers for equipment access.
- Equine sports medicine expansion:Thoroughbred racing and show-jumping circuits in Kentucky and Florida generate demand for weight-bearing limb imaging protocols.
- EU MDR clinical evidence requirements:Post-market surveillance mandates create service revenue streams for manufacturers offering compliance documentation support.
Industry Challenges
- Veterinary radiologist scarcity:Board-certified diagnostic imaging specialists command premium compensation, constraining teleradiology platform scaling.
- Legacy PACS integration friction:DICOM conformance variations between installed hospital information systems and new CT platforms extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary CT Imaging Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical CT, Cone Beam CT, Flat Panel CT, Mobile CT End User: Veterinary Clinics, Animal Hospitals, Research Institutes, Pet Owners Technology: Multislice Detection, Image Reconstruction, Scanning Technique, Software Integration Application: Diagnosis, Treatment Planning, Surgical Guidance, Imaging Research |
| Companies Covered | Koninklijke Philips, Animage, Siemens Healthineers, SOUND, Hallmarq Veterinary Imaging, GE Healthcare, Epica International, Fujifilm Holdings, Canon Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary CT Imaging Market Strategic Shifts & Innovations
Artificial intelligence reconstruction algorithms and cone beam architectures are redrawing the boundary between premium and mid-tier equipment categories.
Deep learning-based iterative reconstruction is consolidating the performance gap between entry-level and premium CT platforms. Independent companion animal hospitals in the United States and Germany are adopting AI-enhanced systems at replacement cycle points previously reserved for human-grade refurbished equipment. This compression is eroding the historical 40-50% price-performance stratification that protected premium vendor margins.
EU MDR post-market surveillance requirements are tightening clinical evidence standards for veterinary diagnostic devices marketed in European Economic Area states. Manufacturers must now maintain systematic vigilance data and periodic safety update reports that parallel human device obligations. Small-animal oncology applications face the steepest compliance burden due to the therapeutic consequence of staging accuracy.
Subscription-based equipment access is displacing traditional capital purchase models among independent veterinary practices. Leasing arrangements bundled with remote maintenance and teleradiology interpretation are capturing mid-market volume previously lost to referral hospital networks. This shift is most pronounced in Texas, Florida, and California where practice ownership fragmentation persists despite corporate consolidation in coastal metropolitan corridors.
Veterinary CT Imaging Market Segmentation
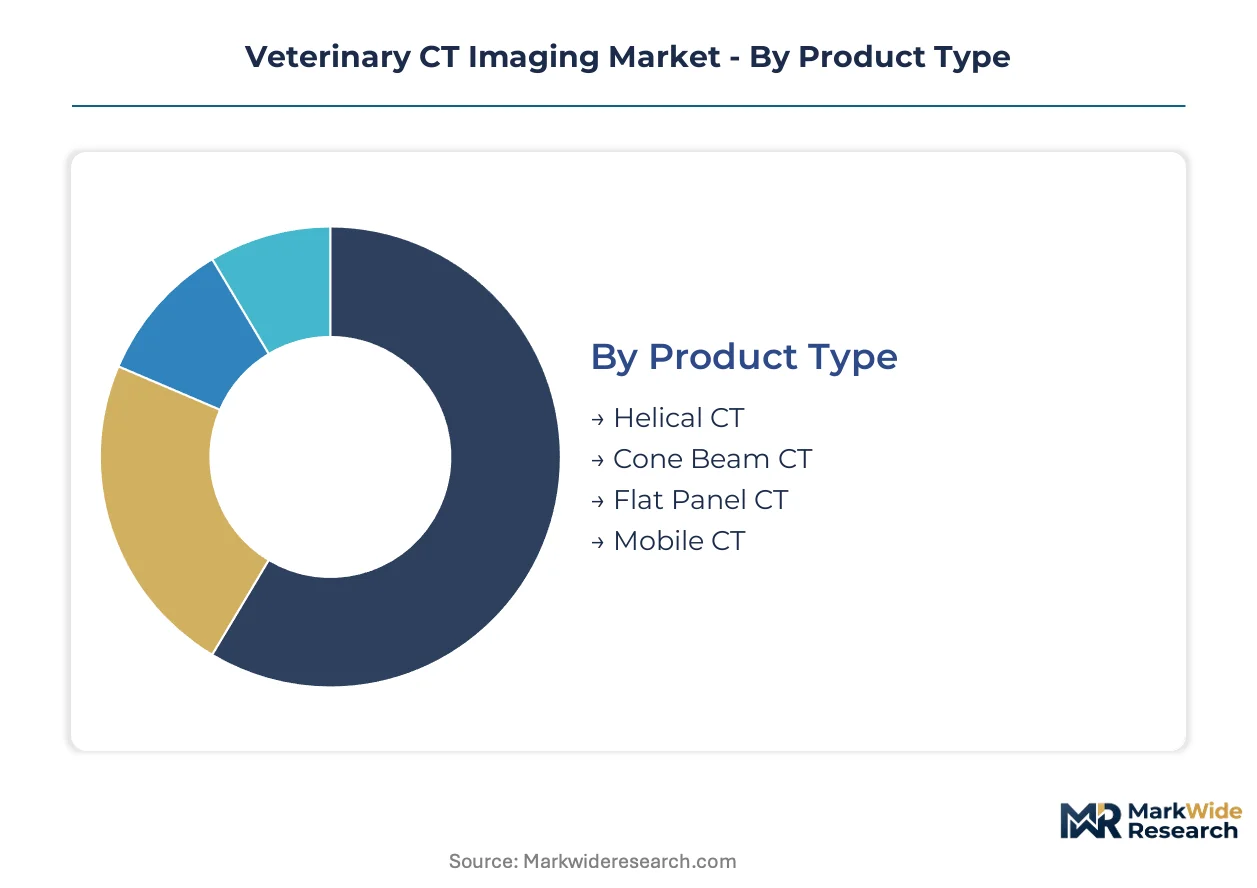
Veterinary CT imaging segments diverge sharply in capital requirements, throughput economics, and clinical workflow integration. Replacement cycles and upgrade pathways vary by configuration, with mobile and cone beam systems disrupting traditional helical dominance in independent practice settings.
Product Type:
Upgrade timelines for veterinary CT platforms compress where AI reconstruction and low-dose protocols narrow the performance gap between mid-tier and premium configurations.
- Helical CT:Continuous gantry rotation with slip-ring technology enables sub-minute whole-body acquisitions. Emergency and trauma centers in high-volume metropolitan corridors prioritize these systems for throughput maximization. Shielding requirements and HVAC specifications impose six-figure facility modifications beyond equipment acquisition.
- Cone Beam CT:Flat-panel detector arrays capture volumetric data with lower radiation exposure and compact footprint. Dental and maxillofacial applications in companion animal practices concentrate demand where anatomical focus outweighs full-body coverage needs.
- Flat Panel CT:Solid-state detector technology eliminates image intensifier degradation pathways.
- Mobile CT:Leasing models bundled with teleradiology interpretation bypass capital barriers for independent practices in secondary metropolitan areas.
Helical CT sits at the top of the volume ranking, with mobile CT climbing the fastest.
End User:
Procurement authority concentrates differently across customer types, with multi-site specialty groups leveraging scale against fragmented independent practice demand.
- Veterinary Clinics:Independent companion animal practices in the United States and Germany face capital constraints that subscription-based equipment access increasingly addresses. Teleradiology partnerships reduce the need for on-site radiologist staffing.
- Animal Hospitals:Private equity-backed referral networks consolidate emergency and specialty capacity across metropolitan corridors. These platforms negotiate national service agreements privileging vendors with coast-to-coast maintenance infrastructure.
- Research Institutes:Academic veterinary medical centers require FDA 510(k) cleared devices for translational oncology protocols.
- Pet Owners:Direct-to-consumer imaging access remains negligible outside equine sports medicine contexts.
Animal hospitals command the largest installed base, while veterinary clinics are gaining share fastest through leasing penetration.
Technology:
Software and algorithmic differentiation now rivals hardware specifications in vendor competitive positioning.
- Multislice Detection:Detector array configurations from 16-slice to 128-slice determine spatial resolution and temporal coverage trade-offs. Oncology staging applications in United States specialty networks drive specification requirements.
- Image Reconstruction:Deep learning-based iterative reconstruction algorithms compress the performance gap between entry-level and premium platforms. Independent practices adopt AI-enhanced systems at replacement cycles previously reserved for refurbished human-grade equipment.
- Scanning Technique:Protocol libraries for small-animal anatomy reduce operator dependence.
- Software Integration:DICOM conformance with legacy PACS infrastructure extends deployment timelines where hospital information system variations create integration friction.
Image reconstruction commands the steepest R&D investment trajectory, with software integration generating the most implementation delays.
Application:
Clinical utility expands from diagnostic confirmation toward interventional guidance as real-time imaging protocols mature.
- Diagnosis:Oncologic staging and orthopedic assessment constitute the procedural backbone for installed CT capacity. Small-animal oncology faces the steepest EU MDR compliance burden due to therapeutic consequence of staging accuracy.
- Treatment Planning:Radiation therapy simulation and surgical approach mapping require sub-millimeter spatial fidelity. Equine sports medicine circuits in Kentucky and Florida generate specialized demand for weight-bearing limb imaging protocols.
- Surgical Guidance:Intraoperative CT integration remains limited by anesthesia workflow constraints.
- Imaging Research:Translational studies require regulatory documentation exceeding clinical practice standards.
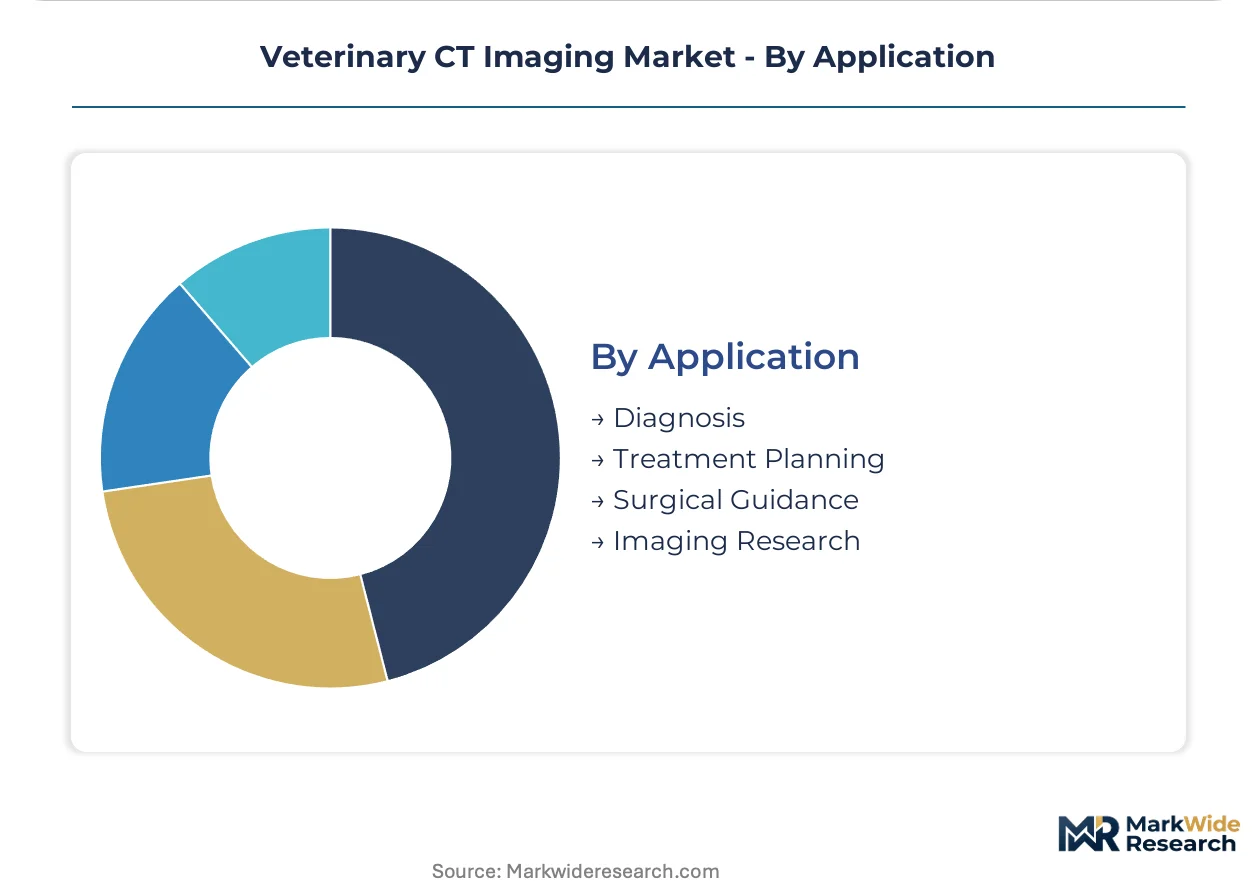
Diagnosis retains the dominant procedure volume, with treatment planning expanding most quickly through radiation oncology integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's veterinary CT infrastructure outpaces France in installed base density, while Japan's regulatory pathway complexity exceeds both European and North American benchmarks. These disparities shape how manufacturers prioritize service networks and certification investments across major demand centers.
United States
Private equity-backed specialty hospital networks in Texas and Florida drive concentrated procurement volume for helical CT platforms. FDA 510(k) premarket notification requirements govern device clearance timelines, with veterinary-configured approvals typically outpacing human-equivalent pathways. The Kentucky equine corridor generates specialized demand for weight-bearing limb imaging protocols at thoroughbred racing facilities.
Germany
Companion animal insurance penetration in Bavaria and North Rhine-Westphalia expands the addressable client base for advanced oncologic staging procedures. EU MDR post-market surveillance mandates enforce clinical evidence standards that parallel human device obligations. The Munich-Stuttgart veterinary specialty corridor consolidates diagnostic capacity through multi-site referral platforms negotiating national service agreements.
Japan
PMDA maintains distinct pharmaceutical and medical device approval tracks that foreign manufacturers must navigate for market access. The Tokyo-Osaka metropolitan axis concentrates high-volume emergency and trauma centers prioritizing sub-minute scan protocols. Kansai region academic veterinary medical centers require regulatory documentation exceeding clinical practice standards for translational oncology protocols.
United Kingdom
Corporate consolidation of emergency and referral hospitals across the London-Southeast corridor compresses vendor negotiation cycles. The country's national pharmaceutical regulator enforces device vigilance requirements aligned with EU MDR frameworks despite post-Brexit regulatory divergence. Greater Manchester and West Midlands independent practices increasingly adopt mobile CT leasing bundled with teleradiology interpretation.
Australia
TGA oversight of veterinary diagnostic equipment imports creates compliance documentation requirements for offshore manufacturers. New South Wales and Victoria host the densest concentrations of specialty referral networks outside North America and Western Europe. Brisbane-Gold Coast equine sports medicine circuits generate regional demand for portable imaging configurations at show-jumping and racing venues.
Veterinary CT Imaging Market Key Industry Players
North American producers anchor one tier; European specialists hold differentiated positions through dedicated veterinary sales channels. The vendor base organizes around three strategic archetypes: diversified medical imaging conglomerates leveraging human radiology installed bases, pure-play veterinary equipment specialists, and regional fabricators serving price-sensitive independent practices. Competitive maneuvering concentrates on M&A consolidation of multi-site service networks and technology licensing for AI reconstruction algorithms.
Among diversified imaging conglomerates, Koninklijke Philips, Siemens Healthineers, and GE Healthcare exemplify the cross-market leverage archetype. These entities occupy positions where human radiology platform architectures transfer to veterinary-configured variants with modified reconstruction protocols. Canon Medical Systems and Fujifilm Holdings sit within a mid-tier specialization vector, while Hallmarq Veterinary Imaging and Animage represent the pure-play veterinary focus archetype with dedicated species-specific engineering.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Animage |
| Siemens Healthineers |
| SOUND |
| Hallmarq Veterinary Imaging |
| GE Healthcare |
| Epica International |
| Fujifilm Holdings |
| Canon Medical Systems |
| Others |
Cost & Logistics Intelligence
Private equity-backed multi-site veterinary specialty groups concentrate procurement authority and impose subscription-based equipment access models that compress vendor margins. This buyer consolidation privileges suppliers with national service networks while squeezing regional distributors through volume-based pricing negotiations.
Pricing Analysis
Capacity additions in the United States and Germany are reshaping price floors for mid-tier helical CT platforms as AI reconstruction narrows performance gaps. Three-tier pricing structure across premium, standard, and economy levels stratifies by slice count, reconstruction algorithm sophistication, and after-sales service bundling. Cost compression in the standard tier intensifies because independent practices increasingly lease refurbished human-grade systems reconfigured for veterinary use. Independent companion animal clinics in secondary metropolitan areas exhibit the highest price sensitivity, while corporate specialty hospital networks prioritize throughput specifications over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Illinois, Texas, and California operate hub-and-spoke patterns that feed independent veterinary practices and multi-site hospital networks. Detector array fabrication concentrates in Japan, Germany, and the United States, while gantry assembly and system integration anchor in China and Mexico. Molybdenum-99 for contrast agents draws from aging reactors in Canada and the Netherlands, creating single-source vulnerability to unplanned maintenance outages. Distribution runs through manufacturer-direct service engineers for premium installations and veterinary-specific distributors for mid-market cone beam and mobile configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany exceed FDA 510(k) pathway expenses in the United States by substantial margins, rewarding manufacturers with dual-certification capabilities.
For Market Incumbents: Anticipate margin compression from AI-enabled reconstruction algorithms that erode historical performance premiums between equipment tiers. Defensive consolidation moves include acquiring teleradiology platforms to capture recurring service revenue and deepening backward integration into detector array sourcing to offset isotope supply volatility. Channel control through exclusive national service agreements with corporate hospital networks remains the critical lever.
For New Entrants and Emerging Players: Independent equine sports medicine practices in Kentucky and Florida represent the most penetrable buyer archetype, underserved by incumbent veterinary-configured platforms. White-space targets include portable cone beam systems for weight-bearing limb imaging at racing venues and subscription-based mobile CT leasing in Texas metropolitan corridors. A veterinary-exclusive sales channel bypassing general imaging distribution accelerates market access.
For Investors and Strategic Acquirers: Private equity platforms consolidating emergency and referral hospitals are the most active acquirer in this space, creating rollup opportunities for equipment financing and teleradiology services. Long-term viability hinges on exposure to pet insurance penetration trajectories and regulatory convergence between human and veterinary imaging standards. Monitor FDA guidance document releases for veterinary AI-enabled devices as the inflection indicator for algorithmic reconstruction valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Teleradiology Platform Acquisition | Captures recurring interpretation revenue from independent practices lacking on-site radiologist staffing. |
| EU MDR Compliance Documentation Service | Generates service revenue streams from manufacturers facing post-market surveillance mandates in Germany. |
| Mobile CT Leasing Program Expansion | Penetrates price-sensitive independent clinics in Texas and Florida through subscription-based equipment access. |
| AI Reconstruction Algorithm Licensing | Compresses performance gaps between mid-tier and premium platforms, eroding historical vendor margin protection. |
| Equine Sports Medicine Protocol Development | Addresses specialized demand from thoroughbred racing circuits in Kentucky requiring weight-bearing limb imaging. |
Research Approach
Bottom-up veterinary clinic and animal hospital modeling reconciled against top-down imaging equipment shipment tracking forms the analytical core of this study. Primary interviews with veterinary radiologists, biomedical engineers at specialty hospital networks, GPO contracts managers, and teleradiology platform executives combined with secondary validation against FDA 510(k) filings, EU MDR vigilance databases, hospital procurement records, and pet insurance penetration statistics. Triangulation across these sources ensures dimensional consistency between demand-side procedure volumes and supply-side installation data.
Input-output matrices map detector array configurations, reconstruction algorithm capabilities, and end-user facility types across the projection horizon. Segmentation dimensions include product type, end-user category, technology tier, and application with geographic regulatory clusters. CAGRs derive from equipment replacement cycle analysis, insurance penetration elasticity estimates, and specialty hospital consolidation trajectories. Forecast inputs incorporate isotope supply reliability indices and AI reconstruction adoption curves specific to small-animal oncology staging protocols.
Inputs from veterinary hospital procurement databases and equipment manufacturer service records were available through the study window; gaps in independent practice leasing contract terms introduce uncertainty bands around mobile CT penetration assumptions. Forecasts reflect documented assumptions regarding pet insurance expansion, regulatory pathway timelines, and specialty network consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Cardiac Imaging Software Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Medical Image Exchange System Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market