
 Argentina Magnetic Resonance Imaging (MRI) Market | 2026-2036
Argentina Magnetic Resonance Imaging (MRI) Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Magnetic Resonance Imaging (MRI) Market Analysis
Service-based MRI access through managed maintenance contracts and software-defined imaging upgrades is shifting how Argentine hospitals acquire capability without full capital outlay. Siemens Healthineers leverages its regional service infrastructure to sustain long-term equipment relationships across public health networks. GE Healthcare anchors its position through localized technical support and financing structures tailored to Argentine procurement cycles. Koninklijke Philips competes by extending advanced coil technologies and remote diagnostic connectivity to mid-tier facilities.
Magnetic Resonance Imaging deploys superconducting magnets generating field strengths from 0.2 to 7.0 Tesla, paired with radiofrequency coils and gradient systems to produce high-resolution tomographic images of soft tissue, neurological structures, and vascular systems without ionizing radiation. Closed MRI systems occupy the dominant installed base in Argentina's hospital sector due to superior signal-to-noise ratios for neurological and oncological diagnostics. High-Field MRI technology leads the technology segment with established clinical validation, while Hybrid Imaging Systems represent the fastest-growing category as facilities pursue combined anatomical and functional assessment capabilities.
Argentina's national medical device regulator, ANMAT, enforces registration and quality standards for imported imaging equipment, while the Superintendency of Health Services oversees reimbursement frameworks that shape hospital purchasing decisions. The country's central bank and trade authorities influence equipment import costs through foreign exchange and tariff policies that directly affect MRI system affordability. Stakeholders must monitor regulatory harmonization with MERCOSUR technical standards and evolving public-sector tender mechanisms to anticipate procurement windows and compliance requirements.
Market Dynamics
Argentina's MRI market is being fundamentally restructured by the federal government's push to decentralize diagnostic capacity from Buenos Aires to provincial health networks, forcing equipment vendors to reconfigure service architectures and financing models.
Growth Catalysts
- ANMAT streamlined registration pathways:The national medical device regulator has accelerated approval timelines for MRI systems bearing prior FDA or CE certification, reducing market entry friction for imported equipment.
- Neurology departments:Tertiary hospitals in Córdoba and Mendoza provinces are expanding dedicated neuroimaging units, generating concentrated demand for high-field systems with advanced diffusion tensor imaging capabilities.
- Helium conservation technologies:Closed-loop cryogenic systems are reducing operational dependency on imported liquid helium, a critical input subject to Argentina's foreign exchange restrictions.
Market Restraints
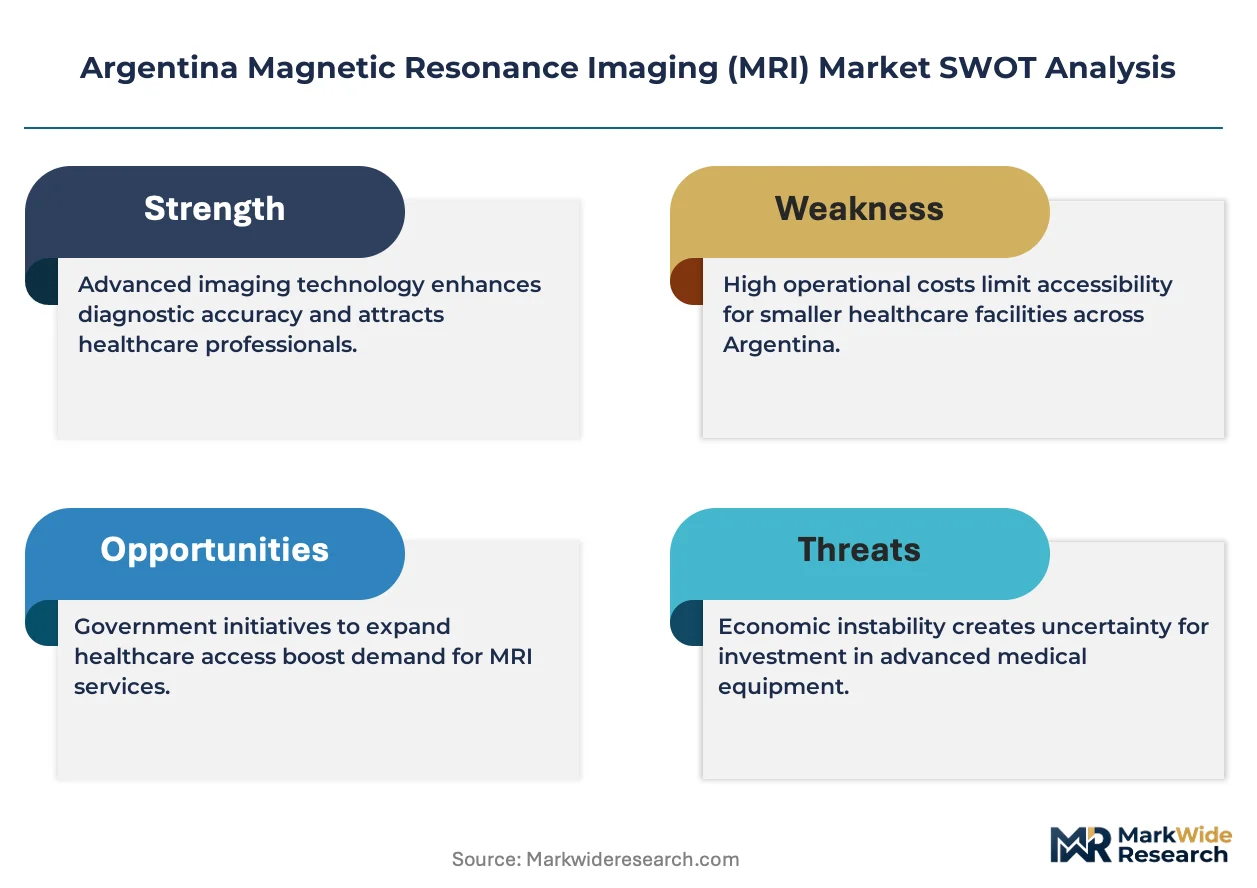
- Import cost volatility:Central bank foreign exchange rationing and tariff fluctuations create unpredictable landed costs for superconducting magnets and gradient coils sourced from European and Asian suppliers.
- Technical workforce scarcity:Argentina produces fewer than forty certified MRI technicians annually, creating persistent bottlenecks for system commissioning and routine maintenance across provincial installations.
- Reimbursement compression:The Superintendency of Health Services has frozen MRI procedure tariffs in real terms since 2019, squeezing hospital capital recovery timelines.
Strategic Opportunities
- Patagonian health corridors:Oil and mining company health plans in Santa Cruz and Chubut provinces are funding private diagnostic centers, creating demand for mobile MRI units capable of remote operation.
- Hybrid PET-MRI convergence:Oncology networks are piloting combined anatomical-functional imaging protocols, opening procurement channels for integrated systems previously absent in Argentine radiotherapy planning.
- Public-private equipment leasing:Provincial governments are experimenting with operational lease structures that transfer obsolescence risk to vendors while preserving public balance sheet capacity.
Industry Challenges
- Biomedical engineer certification delays:ANMAT's technical file review process for field service personnel averages fourteen months, extending vendor deployment timelines for new installations.
- Legacy PACS integration:Public hospitals operate fragmented picture archiving systems from multiple decades, complicating connectivity for AI-enabled reconstruction software and remote diagnostic platforms.
- Helium supply chain fragility:A single domestic supplier controls liquid helium distribution, creating single-point vulnerability for magnet cooldown maintenance and quench recovery operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Magnetic Resonance Imaging (MRI) Market |
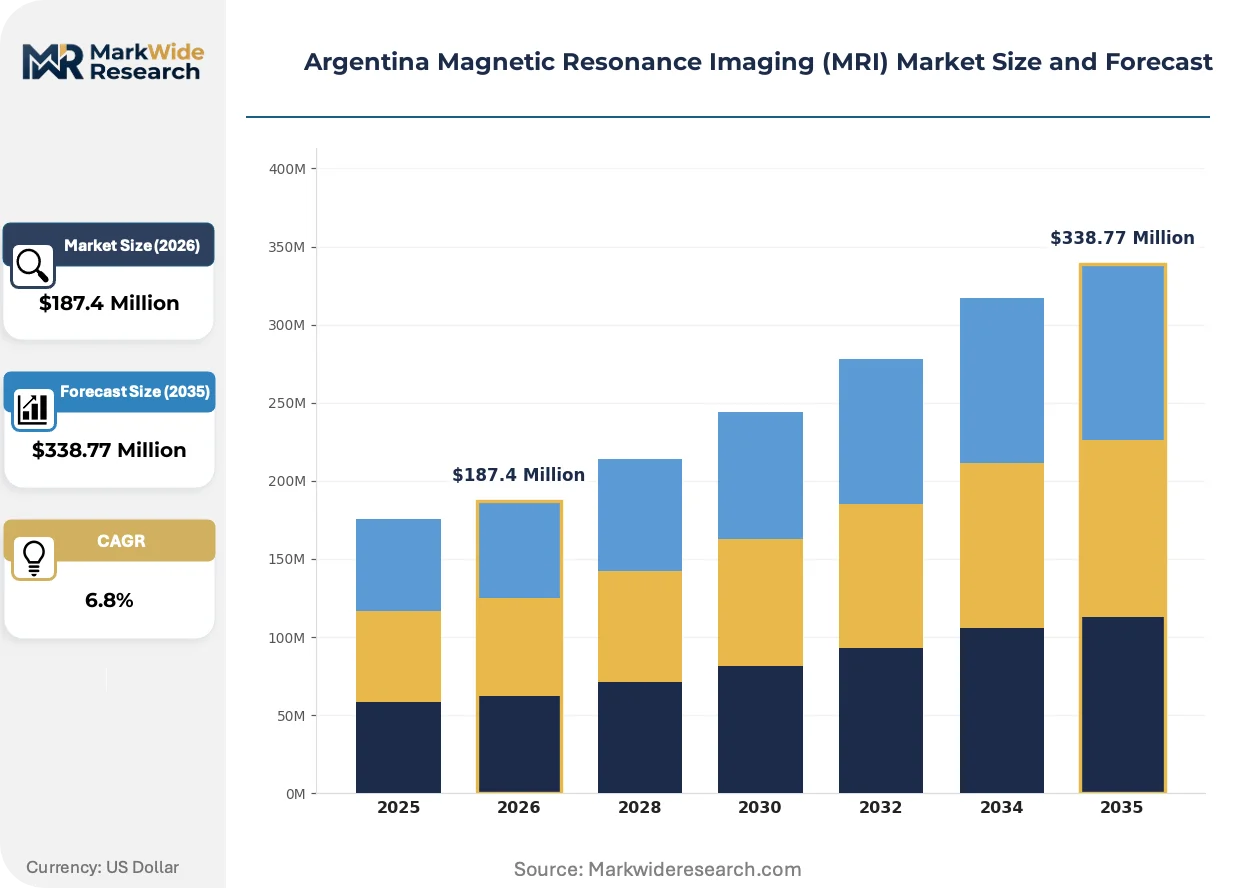
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Diagnostic Centers, Research Institutions, Specialty Clinics Technology: High-Field MRI, Low-Field MRI, Ultra-High-Field MRI, Hybrid Imaging Systems Application: Neurology, Oncology, Cardiovascular, Musculoskeletal |
| Companies Covered | Canon Medical Systems, Esaote SpA, Siemens Healthineers, Hologic Inc., Hitachi Medical Systems, GE Healthcare, Fujifilm Holdings Corporation, Mindray Medical International Limited, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Magnetic Resonance Imaging (MRI) Market Emerging Trajectories
Software-defined imaging architectures are displacing hardware-centric upgrade cycles, allowing Argentine facilities to extend system lifespans through computational rather than capital investment. This shift is compressing traditional replacement timelines and reshaping vendor revenue models toward recurring service streams.
Artificial intelligence reconstruction algorithms are expanding into routine clinical workflows across Buenos Aires metropolitan hospitals. These tools reduce scan duration by reconstructing diagnostic-quality images from accelerated acquisition protocols. Radiology departments are adopting them to manage patient throughput constraints without proportional magnet capacity expansion, fundamentally altering throughput economics for high-field installations.
ANMAT's alignment with MERCOSUR technical standards is harmonizing equipment certification requirements across the Southern Cone trade bloc. Argentine manufacturers and importers now face unified testing protocols rather than country-specific dossiers. This regulatory convergence is accelerating product registration for MRI systems already cleared in Brazil, reducing time-to-market for vendors with established ANVISA approvals.
Hospital purchasing committees are unbundling equipment acquisition from long-term service contracts, treating maintenance and software subscriptions as separately negotiable line items. This procurement fragmentation is pressuring vendor margins on initial system sales while intensifying competition for recurring revenue streams. The pattern is most pronounced in Córdoba's public hospital network, where tender specifications now explicitly separate capital and operational expenditure categories.
Argentina Magnetic Resonance Imaging (MRI) Market Segmentation
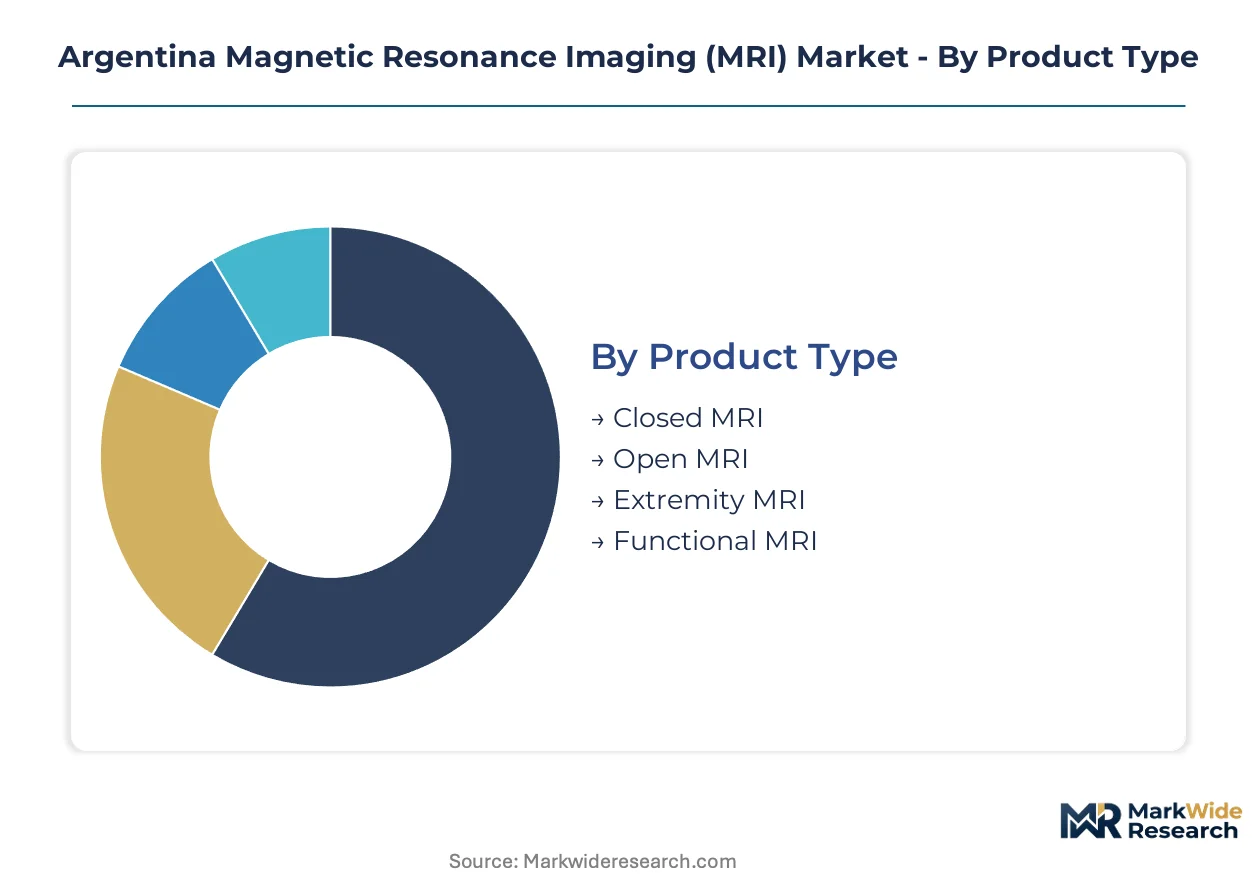
Argentina's MRI market segments reveal distinct procurement patterns across public health networks and private diagnostic chains. Understanding these divisions helps vendors align product portfolios with ANMAT regulatory pathways and provincial reimbursement frameworks.
Product Type:
Hospital purchasing committees differentiate systems by patient throughput capacity and anatomical coverage requirements.
- Closed MRI:Cylindrical bore designs with superconducting magnets generate field strengths above 1.5 Tesla for high-resolution neurological and oncological imaging. Buenos Aires and Córdoba provinces concentrate demand where tertiary hospitals prioritize signal-to-noise ratios for complex diagnostics.
- Open MRI:C-shaped or double-doughnut magnet configurations eliminate enclosed bore constraints for claustrophobic or bariatric patients. Pediatric facilities in Mendoza and Santa Fe provinces favor these systems for sedation-free scanning protocols.
- Extremity MRI:Dedicated limb-imaging systems with compact footprints target orthopedic clinics and sports medicine centers.
- Functional MRI:Blood-oxygen-level-dependent imaging capabilities support neurosurgical planning and psychiatric research applications.
Closed MRI leads volumes today; Functional MRI is gaining share fastest.
End User:
Capital availability and reimbursement structures create sharp purchasing behavior differences across facility types.
- Hospitals:Public sector institutions dominate installed base with centralized procurement through provincial health ministries. ANMAT registration compliance and long-term service contracts shape vendor selection in Buenos Aires metropolitan networks.
- Diagnostic Centers:Private imaging chains prioritize scan throughput economics and rapid patient turnaround. Oil company health plans in Patagonia fund mobile-capable installations for remote workforce coverage.
- Research Institutions:University hospitals and CONICET-affiliated centers acquire specialized sequences for clinical trial protocols.
- Specialty Clinics:Cardiology and orthopedic focused practices seek compact systems with dedicated coils.
Hospitals absorb the majority of system shipments; Diagnostic Centers are expanding most quickly.
Technology:
Field strength selection reflects clinical validation requirements and operational cost tradeoffs in Argentina's foreign exchange constrained environment.
- High-Field MRI:1.5 to 3.0 Tesla systems with established clinical evidence base anchor neurology and oncology workflows. Córdoba's expanding neuroimaging units generate concentrated procurement for diffusion tensor imaging capabilities.
- Low-Field MRI:Permanent magnet or resistive designs below 0.5 Tesla reduce helium dependency and infrastructure requirements. Provincial hospitals with unreliable power grids favor these systems for operational resilience.
- Ultra-High-Field MRI:7.0 Tesla research-dominant platforms support spectroscopy and high-resolution cortical mapping.
- Hybrid Imaging Systems:PET-MRI convergence enables combined anatomical-functional assessment for radiotherapy planning. Oncology networks pilot integrated protocols previously absent in Argentine treatment centers.
High-Field MRI maintains installed base dominance; Hybrid Imaging Systems show steepest expansion trajectory.
Application:
Reimbursement tariff structures and disease prevalence patterns determine departmental investment priorities.
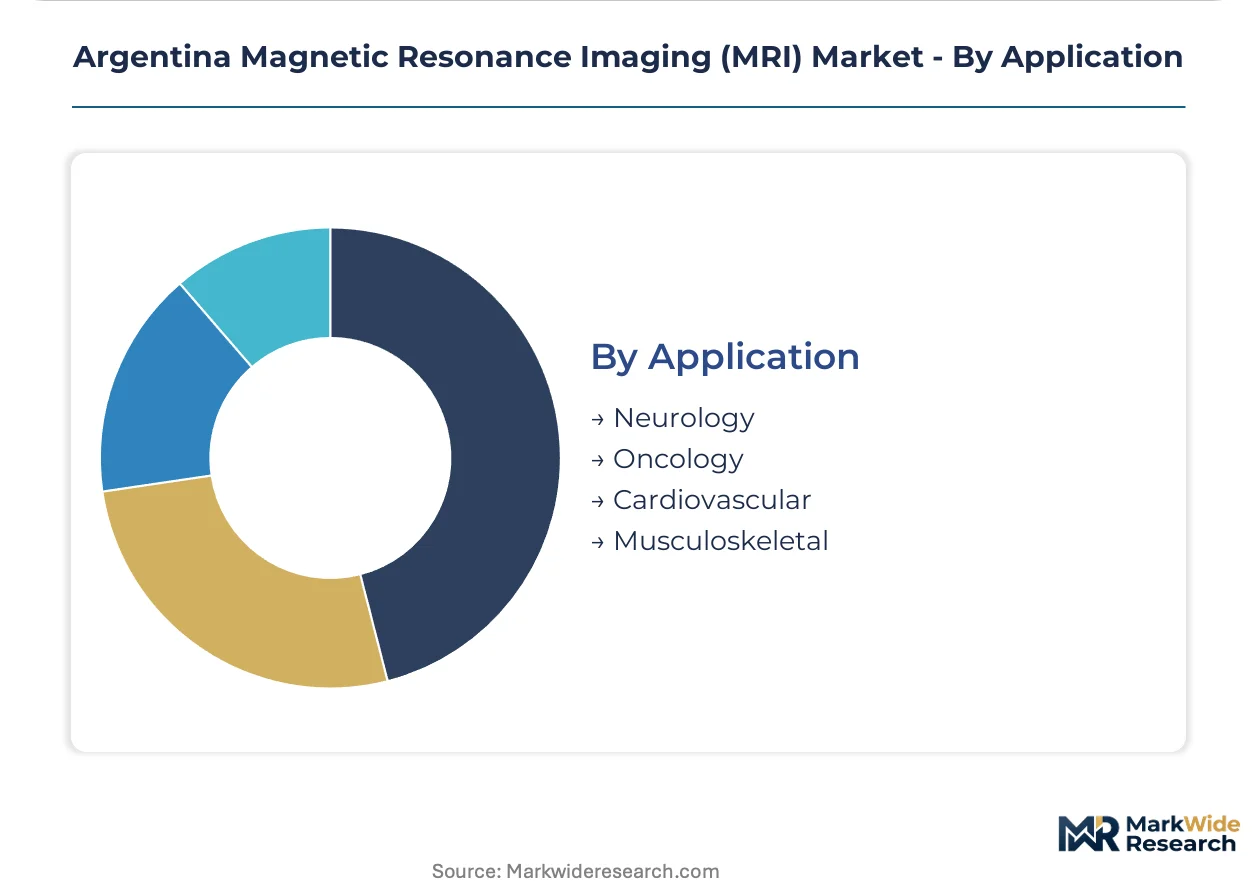
- Neurology:Cerebrovascular, demyelinating disease, and neuro-oncology indications drive high-field system utilization. Tertiary hospitals in Mendoza province dedicate expanding floor space to dedicated neuroimaging units.
- Oncology:Staging and treatment response monitoring generate repeat scan demand across public and private networks. PET-MRI hybrid protocols are penetrating radiotherapy planning workflows in Buenos Aires cancer centers.
- Cardiovascular:Stress perfusion and viability imaging applications require specialized sequences and gating hardware.
- Musculoskeletal:Sports medicine and rheumatology practices concentrate in urban private diagnostic chains.
Neurology commands the largest procedure volume; Oncology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where MRI equipment vendors concentrate service infrastructure, with cost-of-compliance gaps between federal and provincial health systems driving localization strategies across Argentina's decentralized procurement landscape.
Buenos Aires Province
Tertiary hospitals in La Plata and Mar del Plata generate concentrated demand for high-field neurological imaging systems. ANMAT registration requirements for imported superconducting magnets create compliance bottlenecks that favor vendors with established local technical files. The Buenos Aires metropolitan corridor anchors Argentina's largest installed base of closed MRI systems.
Córdoba Province
Expanding neuroimaging units at Hospital Privado Universitario and public sector institutions drive procurement for diffusion tensor imaging capabilities. Provincial health ministry tenders now separate capital expenditure from operational service contracts. The Córdoba-Gran Córdoba cluster concentrates the fastest-growing segment of functional MRI installations.
Mendoza Province
Pediatric facilities favor open MRI configurations for sedation-free scanning protocols, creating distinct procurement patterns from tertiary centers. The Superintendency of Health Services oversees reimbursement frameworks that shape departmental investment priorities. Mendoza city's oncology networks are piloting hybrid PET-MRI protocols for radiotherapy planning.
Santa Cruz Province
Oil company health plans fund private diagnostic centers serving remote workforce populations, generating demand for mobile MRI units with autonomous operation capabilities. Provincial infrastructure constraints favor systems with reduced helium dependency and power resilience specifications. The Patagonian health corridor represents Argentina's most specialized mobile imaging deployment zone.
Argentina Magnetic Resonance Imaging (MRI) Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated equipment-service bundling dominating public hospital procurement while unbundled offerings penetrate private diagnostic chains. The vendor landscape exhibits moderate consolidation around three multinational imaging conglomerates with established ANMAT registration histories. Two strategic archetypes predominate: full-stack platform vendors with captive financing arms, and regional service specialists leveraging third-party equipment relationships. Competitive positioning hinges on M&A activity targeting provincial service networks and technology licensing arrangements for AI-enabled reconstruction software.
Among the multinational platform vendors, Siemens Healthineers, GE Healthcare, and Koninklijke Philips occupy positions as archetypal integrated-system providers with established Argentine service infrastructures. These entities exemplify the full-stack model through localized technical support capabilities and long-term equipment relationships across public health networks. Regional specialists including Canon Medical Systems and Esaote SpA represent alternative positioning vectors focused on coil technology differentiation and mid-tier facility penetration. Hitachi Medical Systems and Fujifilm Holdings Corporation sit within the technology-licensing tier, emphasizing software-defined imaging architectures that extend system lifespans without full capital replacement cycles.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Esaote SpA |
| Siemens Healthineers |
| Hologic Inc. |
| Hitachi Medical Systems |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Mindray Medical International Limited |
| Koninklijke Philips |
| Others |
Supply Flow & Price Mechanics
Liquid helium spot price volatility cascades through Argentina's MRI supply chain, compressing margins on high-field superconducting systems while amplifying price premiums for closed-loop cryogenic architectures that reduce operational dependency on imported coolant.
Pricing Analysis
Distributor markups on imported gradient coils and radiofrequency assemblies stratify final system costs across three performance tiers. Pricing separates premium 3.0 Tesla configurations with advanced diffusion tensor capabilities from standard 1.5 Tesla workhorses and economy-focused low-field permanent magnet designs. Cost compression in the mid-tier segment is intensifying because provincial health ministries now unbundle equipment acquisition from long-term service contracts. Public hospital purchasing committees exhibit highest price sensitivity, while private diagnostic chains in Patagonia prioritize mobile capability over capital expenditure minimization.
Supply Chain Analysis
Superconducting wire supply rests on Japanese and European specialty metal producers, with niobium-titanium alloy fabrication concentrated in Germany and Japan. Gradient coil assemblies draw from Chinese electromagnetic component manufacturers, while helium recovery systems source from United States cryogenic engineering specialists. Single-source vulnerability pervades liquid helium distribution, where one domestic supplier controls national logistics. Distribution runs through authorized service depots in Buenos Aires and Córdoba that manage spare parts inventory and field engineer deployment across provincial hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's MRI market represents a late-cycle quality story as provincial health networks shift procurement criteria toward systems with validated AI reconstruction algorithms and remote diagnostic connectivity. This specification upgrade favors vendors with software-defined imaging roadmaps over hardware-centric competitors.
For Market Incumbents: Deploy captive financing arms to capture public-private equipment leasing experiments in Córdoba and Mendoza provinces. Siemens Healthineers and GE Healthcare should deepen backward integration into helium conservation technologies to offset single-supplier distribution risk. Philips must accelerate ANMAT registration for advanced coil configurations before regional competitors exploit streamlined MERCOSUR harmonization pathways.
For New Entrants and Emerging Players: Mid-tier facilities in Santa Fe and Tucumán provinces present the most penetrable buyer archetype, underserved by incumbent service infrastructure. Mobile MRI units for oil company health plans in Patagonia offer white-space expansion with lower competitive density. A software-only entry strategy—selling AI reconstruction licenses to extend legacy system lifespans—circumvents capital-intensive equipment manufacturing barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional service specialists possessing established ANMAT technical files and provincial hospital relationships. Long-term viability hinges on recurring revenue streams from maintenance contracts rather than episodic system sales. Watch helium price normalization and ANMAT field engineer certification timelines as inflection indicators for operational margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium Conservation Technology Licensing | Reduces dependency on Argentina's single liquid helium distributor for magnet maintenance. |
| AI Reconstruction Algorithm Development | Enables Buenos Aires hospitals to increase patient throughput without proportional magnet capacity expansion. |
| Provincial Service Network Acquisition | Captures recurring maintenance revenue from Córdoba's unbundled procurement tender structure. |
| Mobile MRI Platform Engineering | Addresses Patagonian oil company health plan demand for remote workforce diagnostic coverage. |
| ANMAT-MERCOSUR Harmonization Investment | Accelerates product registration for systems already cleared by Brazil's ANVISA regulator. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineers, provincial health ministry procurement officers, and GPO contracts managers with secondary validation against ANMAT registration databases, Superintendency of Health Services reimbursement tariff filings, and MERCOSUR technical standard harmonization documents. Bottom-up system shipment tracking across Buenos Aires, Córdoba, Mendoza, and Santa Cruz provinces was triangulated against top-down market sizing derived from import customs records and vendor service infrastructure expansion patterns.
Historical reference periods anchored volume and value projections across the modeling period, with CAGRs derived from segmented growth rate analysis across product type, technology tier, end-user facility category, and application area. Segmentation dimensions modeled include field strength classification, system mobility configuration, ownership structure, and provincial reimbursement framework cluster. Forecast inputs incorporated ANMAT approval timeline trajectories, provincial health budget allocation patterns, and helium supply chain stability indicators.
Underlying measurement precision varies by segment; high-field closed MRI installations in Buenos Aires metropolitan networks carry tighter precision than emerging hybrid PET-MRI pilots or mobile deployments in Patagonia. Forecasts reflect documented assumptions regarding regulatory harmonization pace and public procurement cycle timing. Central bank foreign exchange rationing, ANMAT field engineer certification delays, and helium price volatility warrant ongoing watch as forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Japan Mammography Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market