
 Europe MRI (Magnetic Resonance Imaging) Market | 2026-2036
Europe MRI (Magnetic Resonance Imaging) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe MRI (Magnetic Resonance Imaging) Market Intelligence
The shift towards managed equipment service contracts and leasing models is reconfiguring market access for European healthcare providers with constrained capital budgets. Siemens Healthineers leverages its extensive service network and financing arm to dominate these long-term partnership agreements. Koninklijke Philips competes on integrated diagnostic solutions, bundling advanced imaging hardware with its proprietary informatics platforms. GE Healthcare differentiates through its focus on AI-powered workflow enhancements and pioneering high-field strength 3.0T systems.
Magnetic Resonance Imaging is a non-invasive medical imaging technique using strong magnetic fields and radio waves to generate detailed images of organs and tissues. System performance is defined by magnetic field strength, measured in Tesla, with 1.5T and 3.0T being clinical standards in Europe. While high-field closed MRI systems constitute the largest product segment, wide bore MRI systems are gaining adoption for patient comfort. Neurology and musculoskeletal applications represent the highest volume procedures for diagnostic imaging centers.
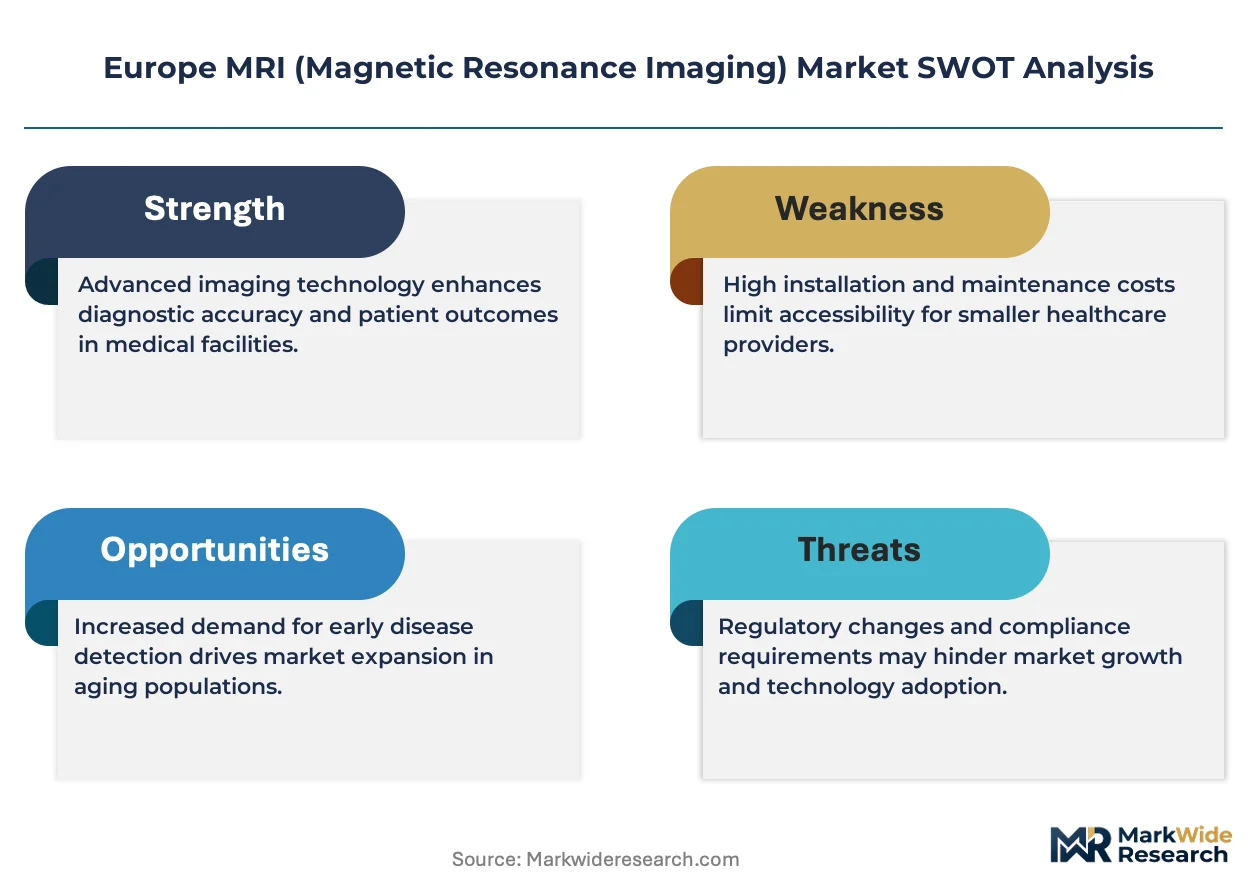
The EU's Medical Device Regulation (MDR 2017/745) imposes stringent clinical evidence and post-market surveillance requirements on MRI manufacturers. The General Data Protection Regulation (GDPR) dictates strict rules for handling and storing sensitive patient imaging data. Integrating AI-driven analytics while ensuring compliance with Europe's data privacy frameworks will define the next generation of MRI platforms.
Market Dynamics
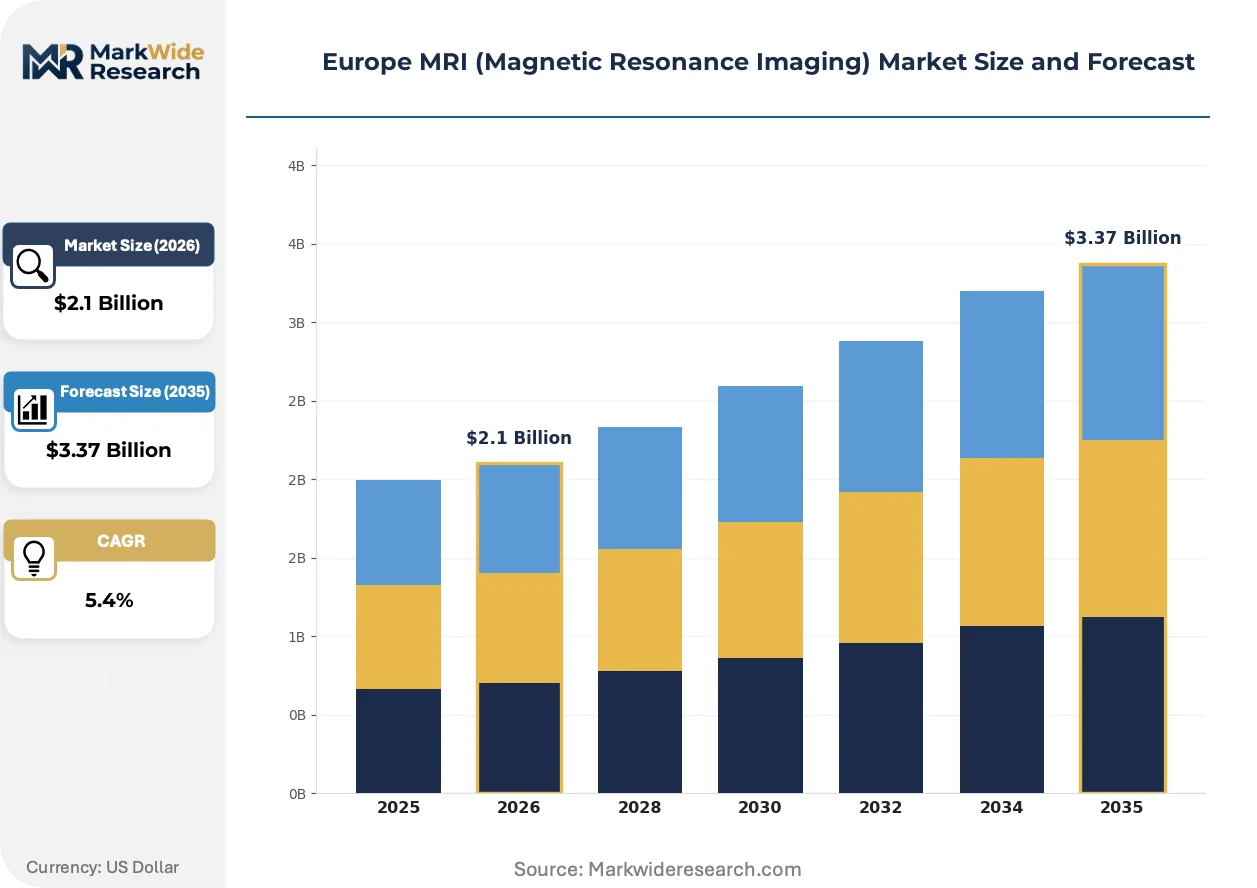
The European MRI market's evolution is governed by the dual pressures of advancing clinical requirements and stringent regulatory oversight. The EU's Medical Device Regulation (MDR) is a central force, compelling manufacturers to provide deeper clinical evidence for system efficacy.
Growth Catalysts
- Oncology Applications:The expanding use of MRI for detailed tumor staging, characterization, and treatment response monitoring in oncology is a significant driver, particularly for high-field strength systems in hospital settings across the European Union.
- Healthcare Infrastructure Modernization:National health system initiatives, especially in Germany and France, are funding the replacement of aging diagnostic imaging fleets with modern 1.5T and 3.0T MRI systems to improve diagnostic accuracy and patient throughput.
- Demographic Shifts:Europe's aging population is increasing the prevalence of neurological and musculoskeletal conditions, sustaining high procedural volumes for diagnostic imaging centers specializing in these areas and driving demand for systems with enhanced patient comfort features.
Market Restraints
- High Capital Costs:The substantial upfront investment required for high-field 3.0T MRI systems and associated site preparation presents a significant financial barrier for smaller hospitals and independent diagnostic centers with constrained capital budgets.
- Liquid Helium Dependency:MRI system operation relies on liquid helium for cooling superconducting magnets. Price volatility and supply chain vulnerabilities for this finite resource create operational cost uncertainties for healthcare providers across Europe.
- Patient-Specific Limitations:The confined space of closed-bore MRI systems can induce claustrophobia and is unsuitable for some bariatric patients, restricting procedural eligibility and necessitating referrals to less common, specialized wide-bore or open systems.
Strategic Opportunities
- AI and Analytics Integration:There is a significant opportunity in developing MRI platforms that embed AI-driven analytics for automated image interpretation and workflow optimization, provided these systems can ensure full compliance with the EU's GDPR.
- Expansion in Eastern Europe:As healthcare spending and infrastructure improve in Eastern European nations, there is a clear opportunity for market entry and expansion by offering cost-effective 1.5T systems tailored to regional needs.
- Functional MRI (fMRI):The growing adoption of fMRI for pre-surgical brain mapping in neuro-oncology and its application in cognitive neuroscience research represents a high-value niche for advanced 3.0T systems and specialized software.
Industry Challenges
- Specialized Talent Shortage:A deficit of radiologists and medical physicists trained to operate advanced MRI systems and interpret data from AI-enhanced imaging techniques limits the full utilization of next-generation equipment in European hospitals.
- Regulatory Compliance Burden:Manufacturers face significant operational challenges in navigating the complex and costly process of generating the extensive clinical evidence and post-market surveillance data required by the EU's Medical Device Regulation (MDR 2017/745).
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe MRI (Magnetic Resonance Imaging) Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Wide Bore MRI, Upright MRI, Portable MRI Application: Neurology, Musculoskeletal, Cardiovascular, Oncology, Abdominal Imaging, Pediatric Imaging End User: Hospitals, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Research Laboratories Deployment: In-House Installation, Mobile Units, Cloud-Based Image Analysis, Teleradiology Services |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Canon Medical Systems Corporation, Fujifilm Corporation, Esaote SpA, Bruker Corporation, Fonar Corporation, Aurora Imaging Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe MRI (Magnetic Resonance Imaging) Market Strategic Shifts & Innovations
The convergence of advanced hardware engineering and sophisticated software intelligence defines the current innovation cycle in the European MRI market. This is driven by clinical demands for faster, more precise diagnostics and the regulatory imperative to demonstrate improved patient outcomes.
AI-powered image reconstruction is a key software innovation that significantly reduces scan acquisition times while enhancing image clarity. Hospitals and high-volume diagnostic centers are rapidly adopting these algorithms to increase patient throughput and manage growing procedure backlogs. This technology is collapsing the traditional trade-off between scan speed and diagnostic image quality, a long-standing limitation in magnetic resonance imaging.
Europe's regulatory framework, specifically the EU Medical Device Regulation (MDR 2017/745), imposes stricter requirements for clinical evidence and post-market follow-up. This directive elevates the burden of proof for manufacturers, demanding robust data to validate any claims of improved performance or new clinical applications. The high-field 3.0T MRI segment is particularly affected, as innovation cycles slow to accommodate more extensive clinical trials.
A fundamental shift in equipment acquisition is underway, with healthcare providers moving away from direct capital purchases toward managed equipment service (MES) contracts. This trend replaces one-time transactional sales with long-term partnerships that bundle the MRI system with maintenance, software upgrades, and ongoing support. This model is most prominent in public healthcare systems like those in the United Kingdom and Scandinavia.
Europe MRI (Magnetic Resonance Imaging) Market Segmentation
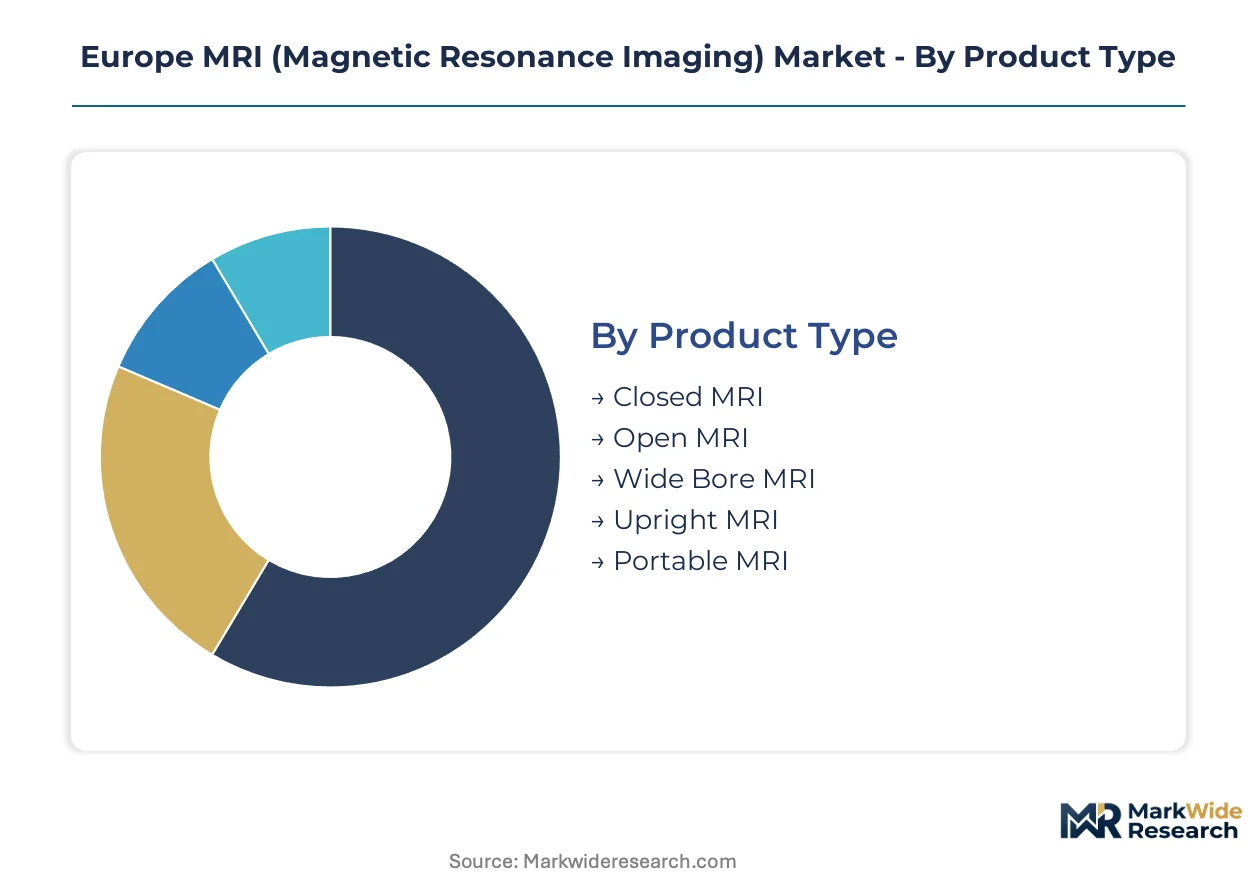
The European MRI market segments reflect diverse technological capabilities and varied clinical applications. Understanding these distinctions is crucial for identifying areas of concentrated demand and emerging growth opportunities. The market structure enables providers to tailor solutions to specific healthcare needs across the region.
Product Type:
The product type segmentation reveals a spectrum from mature, established systems to emerging, patient-centric designs.
- Closed MRI:These systems feature a cylindrical bore, generating high-resolution images with powerful magnetic fields, typically 1.5T or 3.0T. Demand concentrates in hospital settings across Germany and France, driven by the need for diagnostic accuracy in complex cases.
- Open MRI:These systems offer a more open design, reducing claustrophobia for patients but often operating at lower field strengths.
- Wide Bore MRI:Featuring a wider opening than traditional closed systems, these units enhance patient comfort and accommodate bariatric individuals. Adoption is expanding in diagnostic imaging centers across the UK and Scandinavia, addressing patient-specific limitations.
- Upright MRI:These specialized systems allow patients to be scanned in weight-bearing positions, useful for musculoskeletal conditions.
- Portable MRI:Compact and movable systems offer flexibility for point-of-care diagnostics, particularly in emergency or remote settings.
Closed MRI retains volume leadership; Wide Bore MRI holds the steepest expansion curve.
Application:
Application segments are defined by the primary clinical use cases, reflecting the diverse diagnostic needs of European healthcare. Each application demands specific imaging protocols and software capabilities for optimal outcomes.
- Neurology:This segment involves imaging the brain, spine, and nervous system for conditions like stroke, tumors, and degenerative diseases. High procedural volumes in diagnostic imaging centers across Europe underscore its importance for precise diagnosis.
- Musculoskeletal:MRI is extensively used to visualize joints, soft tissues, and bones, aiding in the diagnosis of injuries and inflammatory conditions.
- Cardiovascular:Cardiac MRI provides detailed images of the heart and blood vessels, crucial for assessing heart function and detecting abnormalities.
- Oncology:MRI plays a critical role in tumor detection, staging, and monitoring treatment response across various cancer types. The expanding use of high-field strength systems in hospital settings drives demand for enhanced tumor characterization.
- Abdominal Imaging:This application focuses on organs within the abdomen, including the liver, kidneys, and pancreas, for diagnostic assessment.
- Pediatric Imaging:Specialized MRI protocols cater to children, minimizing scan times and often utilizing sedation for accurate, non-invasive diagnostics.
Neurology procedures maintain high volumes, while oncology applications are gaining share fastest due to advancing diagnostic capabilities.
End User:
End-user segmentation highlights the primary healthcare facilities utilizing MRI systems, each with distinct capital budget constraints and patient throughput requirements.
- Hospitals:These institutions represent the largest end-user segment, acquiring advanced MRI systems for a broad range of diagnostic and interventional procedures. Public healthcare systems in the UK and Germany frequently modernize their fleets to enhance diagnostic accuracy.
- Diagnostic Imaging Centers:These specialized facilities focus on high-volume imaging services, prioritizing efficiency and patient comfort. They frequently adopt wide-bore systems and AI-powered workflow enhancements to manage growing procedure backlogs across Europe.
- Ambulatory Surgical Centers:These centers typically focus on outpatient procedures, utilizing MRI for pre-surgical planning and post-operative assessment.
- Research Laboratories:Academic and pharmaceutical research facilities employ MRI for advanced studies, including functional MRI and drug development.
Hospitals remain the dominant end-user segment, with diagnostic imaging centers demonstrating robust expansion in patient services.
Deployment:
Deployment methods reflect evolving operational models, from traditional on-site installations to digitally driven, remote service provisions that optimize resource utilization.
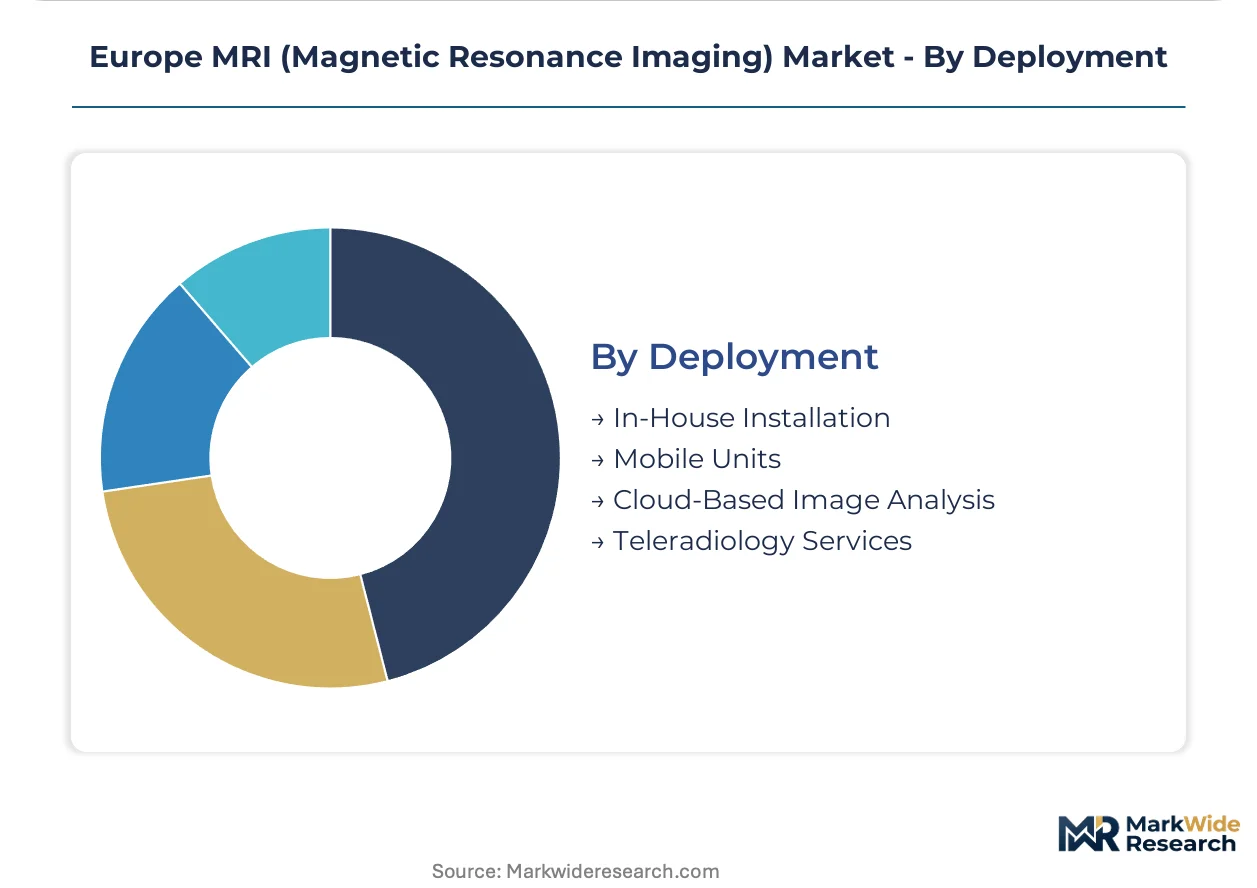
- In-House Installation:This traditional model involves permanent MRI system placement within a healthcare facility, requiring significant site preparation. It remains the primary deployment for high-field systems in major European hospitals, ensuring immediate access to diagnostics.
- Mobile Units:These self-contained MRI systems on trailers provide diagnostic services to remote areas or during facility renovations.
- Cloud-Based Image Analysis:This deployment leverages cloud infrastructure for image storage, processing, and AI-driven interpretation, enhancing accessibility and collaboration. Compliance with GDPR is paramount for its expanding adoption across European healthcare networks.
- Teleradiology Services:Remote interpretation of MRI scans by radiologists, enabling specialized expertise to be accessed irrespective of geographical location.
In-house installations lead in volume, while cloud-based image analysis solutions show significant potential for efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European MRI market's trajectory is significantly influenced by regulatory frameworks and national healthcare investment initiatives. The EU's Medical Device Regulation (MDR) sets high standards for clinical evidence, impacting product development and market entry across member states. National health system modernization programs are also driving substantial equipment upgrades.
Germany
Germany's demand for MRI systems stems from its robust healthcare infrastructure modernization and a strong focus on oncology applications. The national health system initiatives actively fund the replacement of aging diagnostic fleets. Bavaria, a hub for medical technology, sees significant investment in R&D and manufacturing of advanced MRI systems.
France
France is modernizing its diagnostic imaging fleets, with a particular emphasis on neurological applications and high-field strength systems. National policies encourage the adoption of advanced medical devices to improve diagnostic accuracy. The Greater Paris region's major hospitals are actively upgrading to 3.0T MRI systems, enhancing their diagnostic capabilities.
United Kingdom
The United Kingdom's market for MRI systems is shaped by the prevalence of managed equipment service contracts and a need for patient-centric features like wide bore systems. The National Health Service (NHS) procurement policies prioritize value-based care and operational efficiency. Diagnostic imaging centers in London and the Southeast are expanding services to manage patient backlogs.
Sweden
Sweden experiences sustained demand for MRI systems due to its aging population and the resulting increase in musculoskeletal conditions. National health technology assessment (HTA) frameworks guide the adoption of new medical imaging technologies. Research institutions in the Stockholm region are increasingly adopting fMRI for advanced cognitive neuroscience studies.
Europe MRI (Magnetic Resonance Imaging) Market Key Industry Players
Channel-controlling players compete with product-specialist players, shaping the European MRI market structure. The market exhibits a concentrated core of large, integrated diagnostic solution providers alongside a fragmented periphery of niche technology specialists. Key strategic archetypes include comprehensive system manufacturers, AI-focused innovators, and managed service providers. Dominant competitive moves involve strategic partnerships for software integration and the expansion of managed equipment service contracts.
Integrated diagnostic solution providers such as Siemens Healthineers and Koninklijke Philips exemplify the market's focus on long-term partnership agreements and bundled informatics platforms. These companies leverage their extensive service networks and financing arms to secure significant market access in European healthcare. GE Healthcare, another prominent player, represents the drive towards AI-powered workflow enhancements and pioneering high-field strength systems, differentiating its offerings through advanced technological capabilities.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Canon Medical Systems Corporation |
| Fujifilm Corporation |
| Esaote SpA |
| Bruker Corporation |
| Fonar Corporation |
| Aurora Imaging Technology |
| Others |
Cost & Logistics Intelligence
Liquid helium supply, a critical input for superconducting magnets, concentrates margin pools upstream, impacting operational costs for European healthcare providers. This dependency on a finite resource creates specific vulnerabilities for MRI system operators.
Pricing Analysis
Certification level, particularly CE marking and MDR compliance, creates the primary spread in MRI system pricing. Long-term managed equipment service contracts represent the dominant pricing model, bundling hardware with maintenance and software. Integration with advanced informatics platforms and after-sales support further differentiate pricing across manufacturers. Pricing pressure stems from constrained capital budgets within public healthcare systems. Smaller diagnostic centers exhibit the highest price sensitivity, while major university hospitals prioritize advanced capabilities over upfront cost.
Supply Chain Analysis
Upstream feedstock for MRI systems relies heavily on global liquid helium production and specialized electronic components from Asia and Europe. Raw material dependencies include superconducting wire and rare earth elements for powerful magnets. Commodity price volatility for liquid helium presents a significant structural risk for operational budgets. Direct sales and managed equipment service contracts from major OEMs to hospitals and diagnostic centers define the dominant downstream distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe MRI market operates as a defensive-moat story, primarily due to the significant regulatory entrenchment imposed by the EU's Medical Device Regulation.
For Market Incumbents: Entrench existing market share by deepening managed equipment service contracts with public healthcare systems. Invest heavily in AI integration for image reconstruction and workflow optimization to counter emerging AI-focused innovators. Prioritize R&D in advanced 3.0T systems and ensure robust MDR compliance to maintain competitive differentiation against regulatory shifts.
For New Entrants and Emerging Players: Pursue white-space opportunities in Eastern European nations by offering cost-effective 1.5T MRI systems tailored to regional needs. Target specialized software solutions for functional MRI in neuro-oncology research, a high-value niche. Partner with local distributors to gain rapid market access and build regional service capabilities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with niche AI software developers and specialized component manufacturers within the MRI ecosystem. This market offers stable, defensive characteristics with high barriers to entry over the next decade. Acquisition targets should focus on companies enhancing workflow efficiency or expanding patient comfort features. Consolidation in the diagnostic imaging center market is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Image Reconstruction Development | This enhances diagnostic speed and image clarity, addressing hospital throughput challenges. |
| MDR Compliance Investment | Ensuring adherence to EU regulations provides a competitive advantage and market access. |
| Managed Equipment Service Expansion | This secures long-term revenue streams and addresses capital budget constraints for healthcare providers. |
| Wide Bore System Portfolio Enhancement | Improving patient comfort expands procedural eligibility and caters to diverse patient populations. |
| Strategic Partnership for Informatics | Integrating advanced software platforms optimizes diagnostic workflows and data management for clinicians. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this study. The analysis incorporates insights from radiologists, hospital procurement managers, medical physicists, and MRI manufacturers' R&D leads. Secondary validation draws from EU medical device databases, national health system reports, clinical trial registries, and company annual reports, employing both bottom-up and top-down triangulation.
The analytical framework models market dynamics across the analysis window, calibrating volume and value outputs through a triangulated approach. Segmentation dimensions include product type, application, end-user, deployment model, and magnetic field strength. Compound annual growth rates are derived through historical trend analysis and future growth projections, incorporating healthcare spending trends, regulatory changes, and technological advancements as key inputs.
Sensitivities concentrate around potential supply chain disruptions, particularly for liquid helium, and significant shifts in European healthcare policy. Forecasts reflect documented assumptions regarding market evolution. Cross-checking against external benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
Italy Computed Tomography Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market