
 Global Anesthesia Gases Market | 2026-2036
Global Anesthesia Gases Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anesthesia Gases Market Foresight
India's pharmaceutical manufacturing corridor is reconfiguring supply dynamics for generic volatile anesthetics. AbbVie Inc. leverages its integrated production network to sustain cost leadership in isoflurane supply. Fresenius SE & Co. KGaA anchors European demand through specialized hospital gas distribution infrastructure. Linde plc competes on bulk medical gas logistics, controlling cylinder refill cycles across multiple continents.
Anesthesia gases comprise pharmacologically active volatile and gaseous compounds administered via inhalation to induce reversible loss of consciousness, with sevoflurane and desflurane requiring precise vaporizer delivery at controlled partial pressures between 0.5 and 8 percent. These agents serve as the foundation for balanced general anesthesia in operating rooms, intensive care units, and emergency settings where intravenous induction proves impractical. Nitrous oxide maintains stable demand in dental applications, while sevoflurane captures preference in pediatric cases due to its favorable hemodynamic profile. The liquid form dominates hospital procurement because vaporizer compatibility simplifies pharmacy inventory management and reduces handling complexity.
The U.S. FDA enforces Current Good Manufacturing Practice standards for volatile anesthetic purity, while the EU's REACH framework governs chemical registration and occupational exposure limits for halogenated ethers. India's CDSCO mandates batch testing protocols for imported anesthesia gases, shaping how foreign suppliers structure local partnerships and quality documentation. Stakeholders must monitor evolving pharmacovigilance requirements for greenhouse gas potency disclosures, as environmental regulators in major markets weigh anesthetic atmospheric impact against clinical necessity.
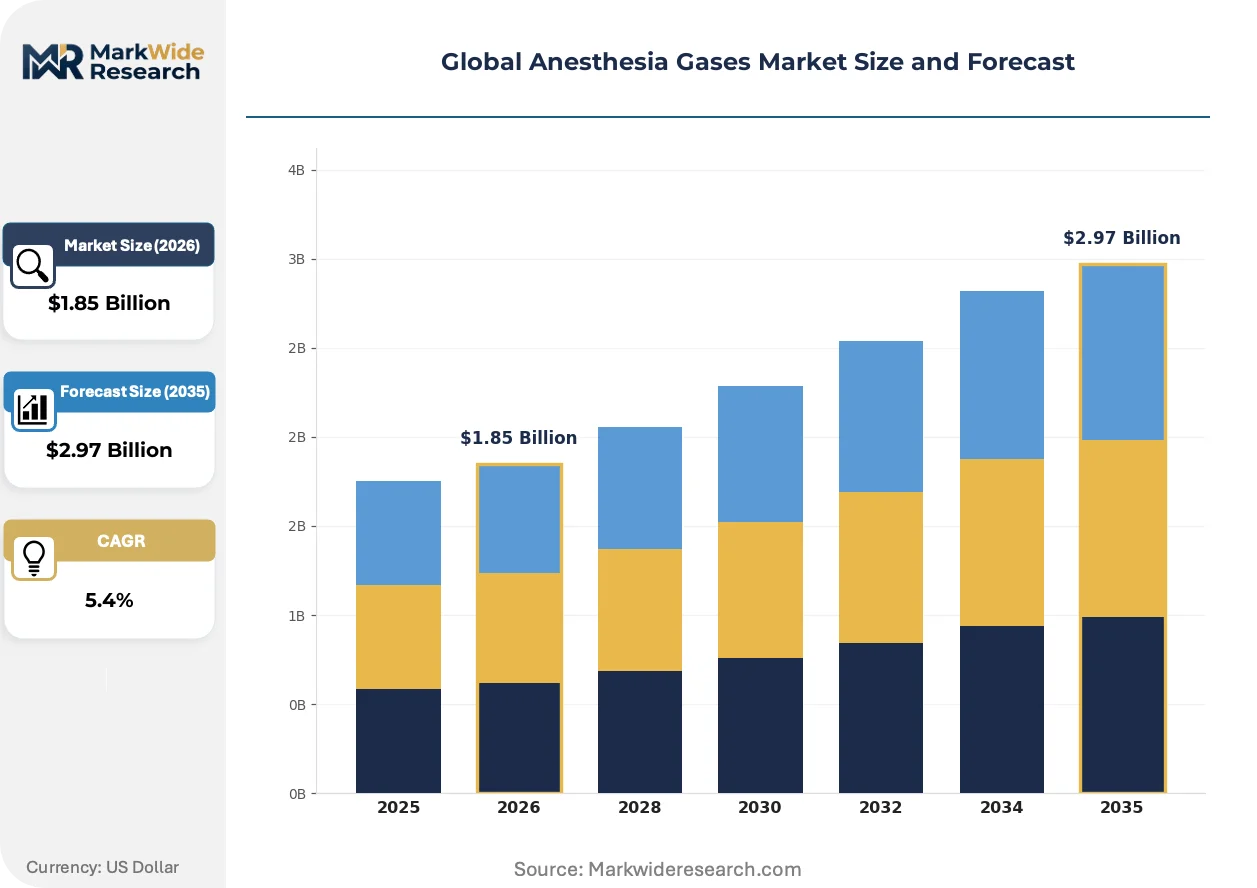
Market Dynamics
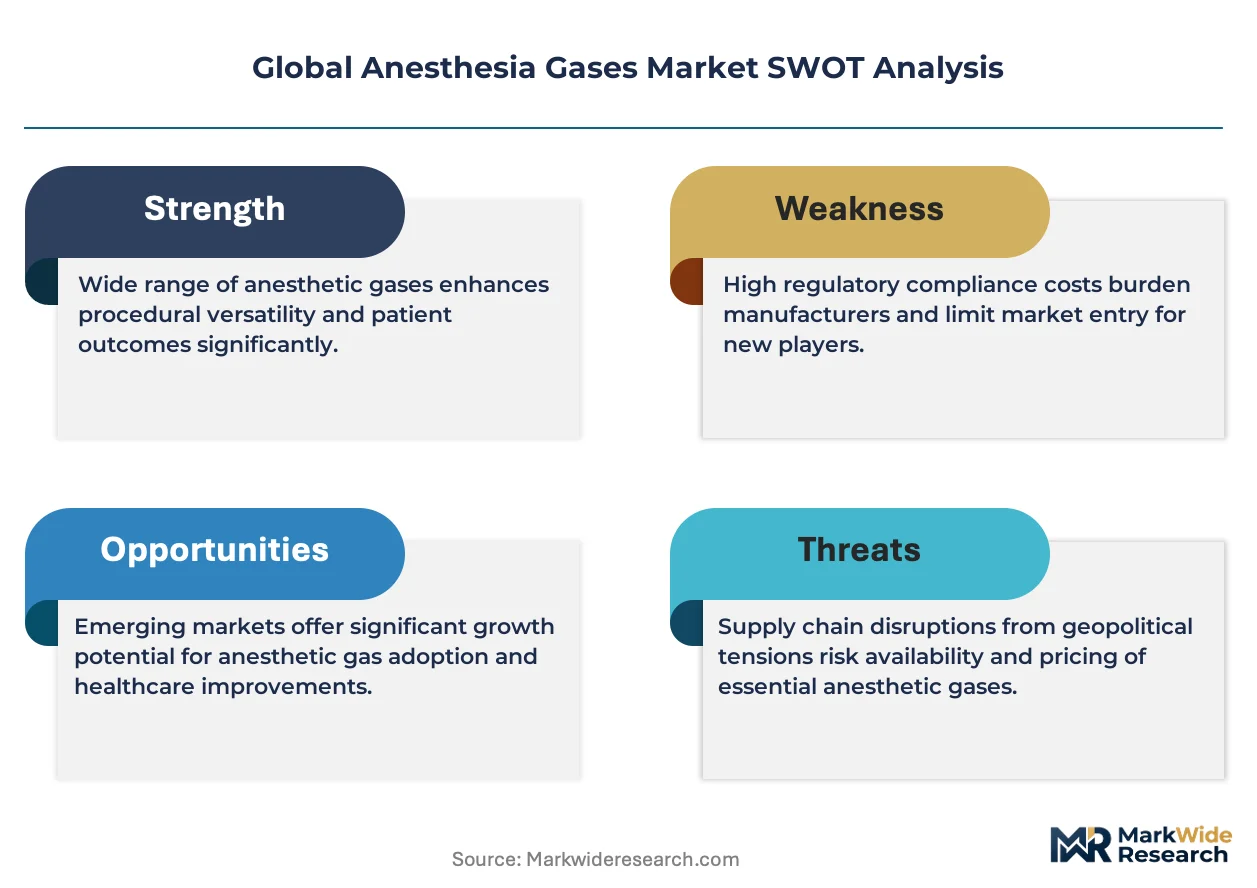
Hospital infrastructure build-outs in India are compressing procurement cycles for anesthesia delivery systems, while the U.S. FDA's updated purity standards are forcing manufacturers to reconfigure volatile anesthetic compound specifications across their production networks.
Growth Catalysts
- CDSCO batch testing mandates:India's pharmaceutical regulator requires rigorous quality documentation for imported anesthesia gases, compelling foreign suppliers to establish local partnerships and expand manufacturing footprints within the subcontinent.
- Ambulatory surgical center expansion:Outpatient facilities across the United States are scaling sevoflurane and desflurane utilization for same-day procedures, creating concentrated demand for portable vaporizer systems.
- Halogenated ether vaporizer technology:Precision delivery systems capable of maintaining 0.5 to 8 percent partial pressures are enabling safer pediatric anesthesia administration and expanding addressable surgical populations.
Market Restraints
- Fluorinated raw material concentration:Specialty chemical precursors for sevoflurane synthesis concentrate among a limited set of European and East Asian suppliers, exposing manufacturers to input cost volatility and allocation risk.
- Greenhouse gas potency disclosure requirements:Environmental regulators in major markets are weighing anesthetic atmospheric impact against clinical necessity, creating compliance friction for high-global-warming-potential agents like desflurane.
- Nitrous oxide substitution pressure:Dental and minor surgical settings are gradually pivoting toward intravenous sedation protocols and regional anesthesia techniques, eroding stable demand for nitrous oxide inhalation systems.
Strategic Opportunities
- India's government-funded surgical access programs:Public health initiatives targeting rural hospital infrastructure are accelerating procurement of integrated anesthesia workstations and bulk medical gas distribution systems.
- REACH framework occupational exposure governance:The EU's chemical registration regime is tightening workplace monitoring requirements for halogenated ethers, creating demand for closed-circuit scavenging systems and real-time gas detection instrumentation.
- Tele-anesthesia and remote monitoring convergence:Integration of vaporizer telemetry with centralized monitoring platforms is enabling specialist oversight across distributed surgical networks, particularly valuable for ambulatory and rural deployment models.
Industry Challenges
- Certified biomedical engineering talent scarcity:Maintenance of precision vaporizer calibration and gas analyzer validation requires specialized technicians, with training pipelines failing to match installation growth rates in emerging markets.
- Legacy system integration complexity:Hospital groups seeking to upgrade anesthesia delivery platforms face costly retrofit requirements for existing gas pipeline infrastructure and operating room ventilation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anesthesia Gases Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Gas Type: Nitrous Oxide, Isoflurane, Sevoflurane, Desflurane, Halothane Application: Surgical Procedures, Dental Procedures, Diagnostic Imaging, Emergency Medicine, Pain Management End User: Hospitals, Ambulatory Surgical Centers, Dental Clinics, Diagnostic Centers, Emergency Care Units Form: Liquid, Gas, Vapor, Mixture |
| Companies Covered | AbbVie Inc., Baxter International Inc., Fresenius SE & Co. KGaA, Drägerwerk AG & Co. KGaA, GE Healthcare, Mindray Medical International Limited, Piramal Enterprises Ltd., Linde plc, Air Liquide S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anesthesia Gases Market Shifts & Advancements
Digital integration of anesthesia workstations with hospital information systems is compressing documentation burden while enabling real-time decision support, fundamentally altering how perioperative teams manage volatile agent administration.
Closed-loop anesthesia delivery systems incorporating bispectral index monitoring and automated vaporizer control are digitizing depth-of-anesthesia management. Academic medical centers in Germany and the United States are piloting these platforms for complex cardiac and neurosurgical cases. The technology is digitizing pharmacokinetic modeling, reducing agent consumption variability and enabling standardized protocols across surgical subspecialties.
The EU F-Gas Regulation is phasing down hydrofluorocarbon production quotas, directly constraining desflurane supply availability and forcing manufacturers to evaluate alternative synthesis pathways or agent portfolio rebalancing. European hospital purchasing consortia are responding by negotiating multi-year sevoflurane supply commitments and investing in low-flow anesthesia techniques that minimize total agent consumption per procedure.
Consolidated procurement through regional anesthesia equipment leasing consortia is displacing traditional capital purchase models for vaporizer systems and gas delivery infrastructure. Large integrated delivery networks in the United States are unbundling equipment acquisition from maintenance and consumable supply, shifting toward per-procedure pricing arrangements that align vendor incentives with utilization efficiency. This restructuring is most visible in California and Texas, where health system mergers have created bargaining leverage for standardized fleet deployments.
Global Anesthesia Gases Market Segmentation
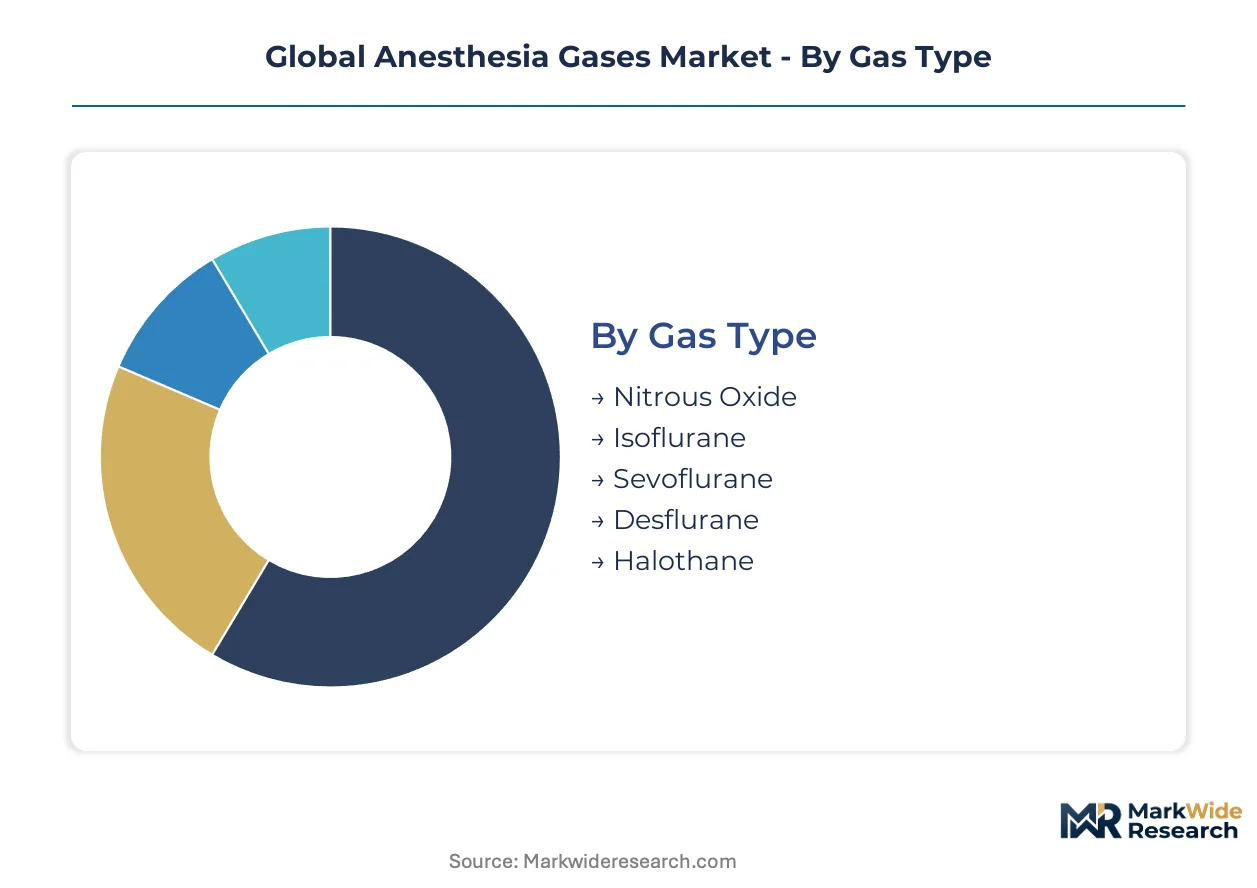
Anesthesia gases segment across pharmacological, clinical, and logistical dimensions that determine procurement patterns and margin structures. Understanding these divisions reveals where formulation investments concentrate versus where commodity competition dominates.
Gas Type:
Sevoflurane and desflurane turn over fastest in hospital formularies due to vaporizer compatibility and shorter washout profiles, while halothane lingers in legacy installations with minimal replacement velocity.
- Sevoflurane:A fluorinated methyl isopropyl ether with blood-gas solubility of 0.65 enables rapid induction and emergence. Pediatric surgical suites in the United States and Germany favor this agent for its minimal airway irritation and cardiovascular stability during induction.
- Desflurane:This highly volatile agent requires heated vaporizers to maintain controlled delivery at 22.8 degrees Celsius boiling point. Cardiac surgery centers value its low tissue solubility for neurosurgical cases demanding precise depth control and rapid emergence protocols.
- Isoflurane:Halogenated ether with pungent odor profile limits mask induction acceptance. Veterinary applications and cost-sensitive hospital systems in India sustain residual demand for this mature compound.
- Nitrous Oxide:Inorganic oxide administered via cylinder delivery maintains stable demand in dental anesthesia and labor analgesia despite environmental scrutiny over greenhouse gas potency.
- Halothane:Brominated alkane with hepatotoxicity concerns has retreated to limited pediatric applications in resource-constrained settings where vaporizer infrastructure supports no alternative.
Sevoflurane dominates installed base across developed hospital systems. Desflurane is where expansion concentrates in ambulatory surgical centers seeking rapid turnover efficiency.
Application:
Cost tiers separate capital-intensive surgical anesthesia from commoditized diagnostic support, with emergency medicine commanding premium pricing for reliability guarantees.
- Surgical Procedures:General anesthesia for major operations requires balanced technique combining volatile agents with intravenous adjuncts. Academic medical centers in Japan and the United States drive protocol standardization through anesthesia information management systems.
- Emergency Medicine:Rapid sequence intubation protocols in trauma bays demand immediate availability of inhalational agents when intravenous access proves impossible. Military field hospitals and civilian disaster response units prioritize portable vaporizer systems for this indication.
- Dental Procedures:Conscious sedation for oral surgery relies on nitrous oxide-oxygen mixtures administered via nasal hood. Regulatory pressure from environmental agencies is compressing utilization in European dental practices.
- Diagnostic Imaging:Pediatric MRI and CT procedures require motion control through brief general anesthesia. Children's hospitals invest in dedicated anesthesia teams for radiology suites to manage throughput and safety.
- Pain Management:Chronic pain interventions occasionally employ nitrous oxide for procedural sedation. Palliative care units in Australia and Canada explore low-dose inhalational techniques for refractory pain.
Surgical procedures anchor revenue concentration. Emergency medicine represents the fastest-growing trajectory as pre-hospital anesthesia capabilities expand.
End User:
Customer type determines contract structure, with integrated delivery networks extracting volume discounts unavailable to independent surgical centers.
- Hospitals:Tertiary care institutions with captive pharmacy operations manage anesthesia gas procurement through centralized materials management. Operating room committees in Germany and France standardize vaporizer fleets across surgical departments.
- Ambulatory Surgical Centers:Freestanding facilities prioritize sevoflurane for same-day discharge protocols. United States outpatient surgery growth is concentrating demand for portable delivery systems with minimal infrastructure requirements.
- Dental Clinics:Small-practice settings rely on cylinder-based nitrous oxide delivery with scavenging systems. Occupational exposure regulations in California and Texas shape equipment specifications.
- Diagnostic Centers:Imaging facilities without full surgical capabilities contract anesthesia services or employ nurse-administered sedation. India's expanding diagnostic infrastructure is creating procurement opportunities for basic delivery systems.
- Emergency Care Units:Hospital emergency departments and standalone urgent care facilities maintain anesthesia readiness for airway management. Pre-hospital services in the United Kingdom and Australia are piloting advanced paramedic anesthesia programs.
Hospitals dominate installed base. Ambulatory surgical centers are gaining share fastest as surgical migration accelerates.
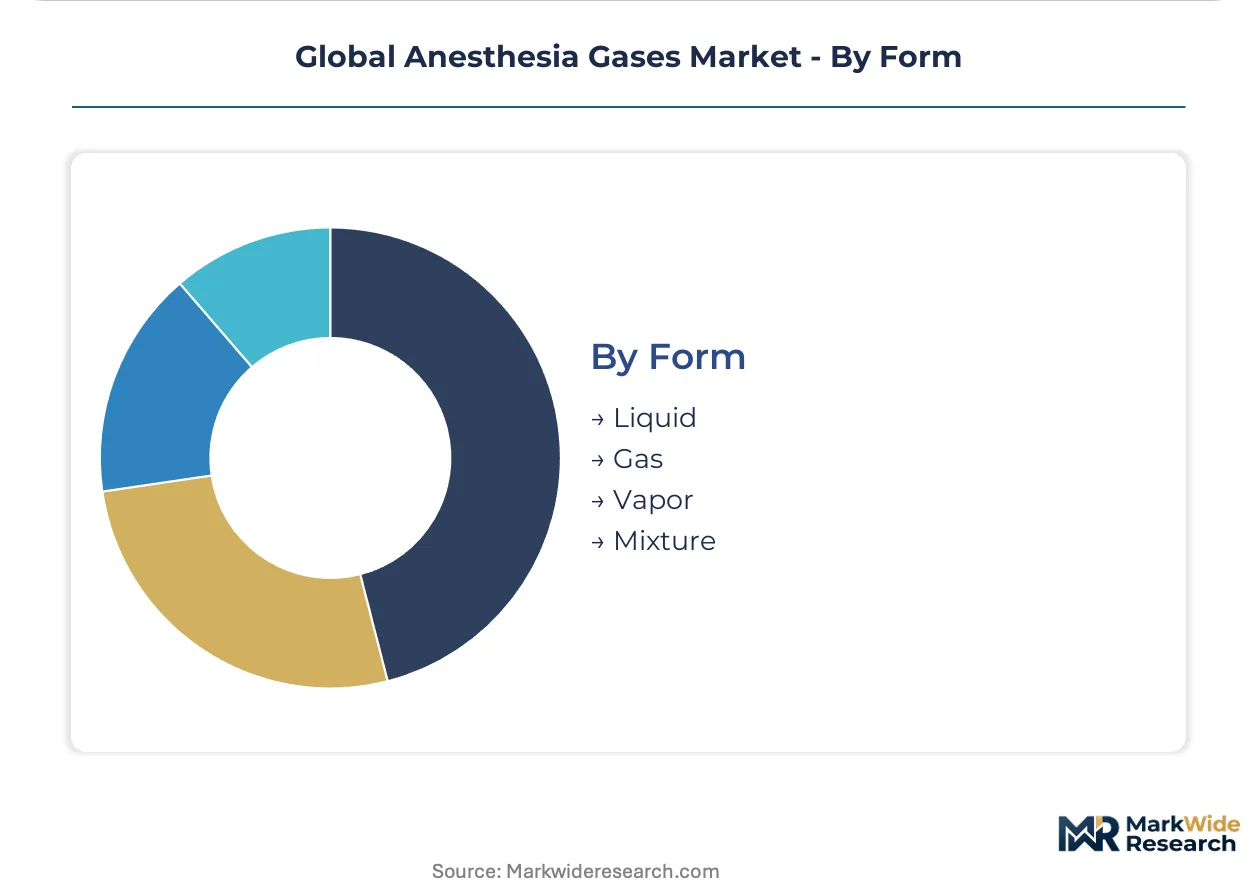
Form:
Supply concentration varies sharply by physical state, with liquid formulations commanding manufacturing complexity that gas and mixture products cannot replicate.
- Liquid:Volatile anesthetics stored as liquids in amber bottles require vaporizer conversion for patient delivery. Hospital pharmacies in India and Brazil prefer this form for inventory stability and reduced cylinder handling costs.
- Gas:Nitrous oxide and medical-grade oxygen distribute via high-pressure cylinders or pipeline systems. Linde plc and Air Liquide control bulk logistics networks spanning multiple continents.
- Vapor:Agent-specific vaporizers heat and meter liquid anesthetic into carrier gas flows. Precision engineering requirements limit manufacturing to specialized biomedical equipment suppliers.
- Mixture:Pre-blended nitrous oxide-oxygen combinations simplify dental and emergency applications. Regulatory batch testing by India's CDSCO and the United States FDA governs compounding facility certifications.
Liquid formulations dominate procurement volume. Vapor delivery systems are where technology investment concentrates as closed-loop control advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical precursors for halogenated ether synthesis concentrate among European and East Asian suppliers, forcing anesthesia gas manufacturers to navigate complex cross-border procurement networks while responding to divergent national regulatory frameworks.
United States
Ambulatory surgical centers in Texas and California are scaling sevoflurane utilization for same-day discharge protocols. The FDA enforces Current Good Manufacturing Practice standards for volatile anesthetic purity, tightening batch documentation requirements. The Boston-Cambridge medical technology corridor hosts precision vaporizer engineering clusters serving academic medical centers.
Germany
Academic medical centers in Berlin and Munich pilot closed-loop anesthesia delivery systems for complex cardiac procedures. The EU F-Gas Regulation phases down hydrofluorocarbon production quotas, constraining desflurane supply availability. The Baden-Württemberg industrial belt anchors specialized hospital gas distribution infrastructure development.
India
Government-funded surgical access programs targeting rural hospital infrastructure are accelerating procurement of integrated anesthesia workstations. The CDSCO mandates rigorous batch testing protocols for imported anesthesia gases, compelling foreign suppliers to establish local manufacturing partnerships. The pharmaceutical manufacturing corridor in Gujarat and Maharashtra is reconfiguring supply dynamics for generic volatile anesthetics.
China
Hospital infrastructure expansion in tier-two cities is driving demand for anesthesia delivery systems with localized technical support. The NMPA regulates medical device registration for vaporizer platforms, shaping how multinational suppliers structure joint ventures. The Yangtze River Delta medical device manufacturing cluster is developing domestic vaporizer production capabilities.
Japan
Aging surgical populations in Tokyo and Osaka are expanding demand for agents with favorable hemodynamic profiles in geriatric cases. The PMDA oversees pharmacovigilance requirements for greenhouse gas potency disclosures. The Nagoya medical equipment manufacturing hub specializes in precision gas analyzer instrumentation for operating room safety systems.
Global Anesthesia Gases Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base stratifies across three tiers: multinational healthcare conglomerates with captive anesthesia portfolios, specialized medical gas logistics operators controlling cylinder refill networks, and regional pharmaceutical manufacturers supplying generic volatile agents. Competitive dynamics center on backward integration into fluorinated raw material supply and geographic expansion through localized manufacturing partnerships.
Among diversified healthcare conglomerates, AbbVie Inc. and Baxter International Inc. occupy positions spanning pharmaceutical production and delivery system integration. Fresenius SE & Co. KGaA exemplifies the specialized hospital infrastructure archetype, while Linde plc represents bulk medical gas logistics operators with multi-continental cylinder distribution networks.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Baxter International Inc. |
| Fresenius SE & Co. KGaA |
| Drägerwerk AG & Co. KGaA |
| GE Healthcare |
| Mindray Medical International Limited |
| Piramal Enterprises Ltd. |
| Linde plc |
| Air Liquide S.A. |
| Others |
Supply & Pricing Matrix
Single-source dependency on fluorinated ether precursors from European and East Asian suppliers compresses margin buffers for generic volatile anesthetic manufacturers while simultaneously widening spreads between premium branded and economy-tier formulations. This concentration dynamic forces procurement teams to absorb input volatility through inventory buffers or contract escalation clauses, reshaping how pricing tiers align with supply security guarantees.
Pricing Analysis
The FDA's Current Good Manufacturing Practice standards dictate the pricing tier structure by imposing compliance cost burdens that stratify manufacturers across premium, standard, and economy levels. Price differentiation hinges on vaporizer compatibility certification and batch documentation rigor, with CDSCO-mandated testing for Indian imports adding geographic delivery cost premiums. Pricing pressure stems from EU F-Gas Regulation quota constraints on desflurane precursors, forcing portfolio rebalancing toward sevoflurane. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure cost accounting, while academic medical centers prioritize hemodynamic profile performance over unit economics.
Supply Chain Analysis
Extended payment terms from Indian hospital procurement committees are compressing working capital cycles for anesthesia workstation suppliers, forcing trade finance facility expansion. Manufacturing concentrates in Germany for precision vaporizer engineering, India for generic volatile anesthetic production, and China for domestic market anesthesia delivery systems. Raw material dependencies rest on fluorinated methyl isopropyl ether precursors, heated vaporizer heating elements, and medical-grade aluminum cylinder stock. Single-source vulnerability concentrates in halogenated ether synthesis intermediates from limited European chemical specialists. Distribution runs through regional hospital gas logistics operators controlling cylinder refill networks and integrated delivery network consortia managing equipment leasing pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anesthesia gases market functions as a regulatory entrenchment story where FDA and EMA manufacturing standards create formidable compliance moats that protect incumbents from commodity substitution. Switching costs for hospital formularies and vaporizer fleet standardization reinforce this defensive positioning.
For Market Incumbents: Build captive supply moats through backward integration into fluorinated raw material production or long-term offtake agreements with European specialty chemical suppliers. Capacity addition in Gujarat and Maharashtra pharmaceutical corridors secures cost leadership against emerging Indian generic competition. CDSCO batch testing mandates threaten margin compression unless local manufacturing partnerships neutralize import documentation burdens. For New Entrants and Emerging Players: Build out tele-anesthesia remote monitoring capabilities as a service layer atop commodity anesthesia delivery hardware, targeting rural Indian hospital infrastructure and United States ambulatory surgical center networks. Underpenetrated diagnostic imaging sedation in tier-two Chinese cities offers the most penetrable geographic entry point. Go-to-market execution should emphasize per-procedure pricing arrangements that align vendor incentives with utilization efficiency metrics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized hospital gas logistics operators with multi-continental cylinder distribution networks and captive vaporizer engineering capabilities. Long-term viability over the next decade hinges on portfolio resilience against environmental regulatory pressure on high-global-warming-potential agents. Acquisition targets should demonstrate closed-loop anesthesia delivery system development pipelines or low-flow anesthesia technique IP. The signal to watch is EU F-Gas Regulation enforcement intensity and corresponding desflurane supply allocation announcements.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Local Manufacturing Partnership | Foreign suppliers establish Indian production to bypass import batch testing documentation burdens. |
| EU F-Gas Regulation Compliance Pathway | Manufacturers reconfigure desflurane synthesis or pivot portfolio toward sevoflurane dominance. |
| Closed-Loop Anesthesia System Development | Academic medical centers in Germany and the United States pilot bispectral index-integrated platforms. |
| Ambulatory Surgical Center Equipment Leasing | Integrated delivery networks in Texas and California shift from capital purchase to per-procedure pricing. |
| Fluorinated Precursor Backward Integration | Generic manufacturers secure cost stability through captive supply of methyl isopropyl ether intermediates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with anesthesiologists, hospital pharmacy directors, biomedical engineering managers, GPO contracts specialists, and anesthesia equipment procurement leads. Secondary validation drew from FDA 510(k) filings, CDSCO import registration databases, EMA manufacturing authorization records, and EU F-Gas Regulation quota allocation disclosures. Bottom-up procedure volume modeling across surgical subspecialties was triangulated against top-down volatile anesthetic consumption data from hospital procurement databases.
Calibration against historical price realization and volume shipment patterns informed growth trajectory assumptions across the analysis window. Segmentation dimensions modeled include gas type pharmacological profile, application setting, end-user facility tier, and physical formulation state. CAGRs were derived from procedure volume elasticity to surgical access program expansion and vaporizer installed base replacement cycles. Industry-specific forecast inputs incorporated REACH framework occupational exposure limit evolution and pediatric anesthesia protocol standardization trends.
Stress conditions across fluorinated raw material allocation disruption, CDSCO regulatory enforcement intensity, and ambulatory surgical center reimbursement rate compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hospital infrastructure build-out pacing and environmental regulatory stringency progression. Macroeconomic contraction affecting elective surgical volumes, unanticipated EPA greenhouse gas potency rulemaking, or breakthrough intravenous sedation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Anesthetics Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Anesthesia Breathing Bags Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Sedation in ICU Setting Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Aspirating System Market
Anesthesiology
Epinephrine Market