
 Japan Diagnostic Imaging Market | 2026-2036
Japan Diagnostic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Diagnostic Imaging Market Foresight
Aftermarket service revenue is reconfiguring margin pools across the Japan Diagnostic Imaging landscape. Canon Medical Systems Corporation leverages its domestic manufacturing base to sustain shorter service response times. Siemens Healthineers anchors its position through advanced MRI platform specialization. Koninklijke Philips N.V. competes on integrated digital imaging ecosystems that extend beyond hardware sales.
Japan Diagnostic Imaging encompasses systems that generate visual representations of internal body structures using ionizing radiation, magnetic fields, or acoustic energy, with spatial resolution parameters ranging from sub-millimeter CT slices to whole-body MRI field strengths of 1.5 to 3 Tesla. These technologies serve primarily to enable non-invasive disease detection, treatment planning, and therapeutic monitoring across clinical settings. CT Scan and MRI equipment command the dominant share of capital expenditure among product types, while Hybrid Imaging represents the fastest-expanding technology segment as Japanese institutions pursue functional-anatomical fusion capabilities. Digital Imaging has matured into the standard architecture, though Portable Imaging is gaining traction in rural prefectures lacking fixed infrastructure.
PMDA approval pathways and JIS standards govern device safety and electromagnetic compatibility requirements for all systems sold domestically. METI coordinates reimbursement pricing through the Central Social Insurance Medical Council, directly influencing hospital upgrade cycles and manufacturer revenue predictability. Stakeholders must monitor how Japan's next medical fee schedule revision balances cost containment against incentives for AI-integrated diagnostic platforms.
Market Dynamics
METI's reimbursement revisions are compressing replacement cycles while PMDA approval pathways lengthen for AI-integrated systems, creating a structural tension between upgrade urgency and certification friction that dominates capital allocation decisions across Japanese imaging departments.
Growth Catalysts
- Aging Demographics:Japan's super-aged society is expanding screening volumes for oncology and cardiovascular conditions, driving hospital procurement of high-field MRI systems in tertiary centers.
- METI Medical Fee Schedule:Biennial reimbursement revisions incentivize digital equipment upgrades by adjusting technical fees for advanced imaging modalities.
- Hybrid Imaging Convergence:PET-CT and PET-MRI fusion systems are penetrating academic medical centers seeking functional-anatomical correlation for precision oncology.
Market Restraints
- Helium Supply Concentration:MRI magnet cooling depends on helium imports concentrated through Qatar and Algeria, exposing operators to price volatility and allocation disruptions.
- PMDA Review Timelines:Novel software-as-medical-device submissions face extended evaluation periods that delay revenue recognition for AI-embedded platforms.
- Capital Intensity:3 Tesla MRI and spectral CT systems require infrastructure investments exceeding facility budgets in rural prefectures.
Strategic Opportunities
- Rural Prefecture Penetration:Portable ultrasound and mobile CT units address access gaps in Hokkaido and Tohoku regions lacking fixed diagnostic infrastructure.
- AI Integration Tailwinds:METI's Society 5.0 framework prioritizes regulatory pathways for machine-learning diagnostic algorithms.
- Aftermarket Service Unbundling:Independent service organizations are capturing maintenance contracts from OEM-installed bases through remote monitoring capabilities.
Industry Challenges
- Radiologist Workforce Constraints:Training pipeline limitations and geographic maldistribution create interpretation bottlenecks that constrain equipment utilization rates.
- Legacy System Interoperability:PACS integration with cloud-native AI platforms requires middleware investments that strain IT budgets in municipal hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Diagnostic Imaging Market |
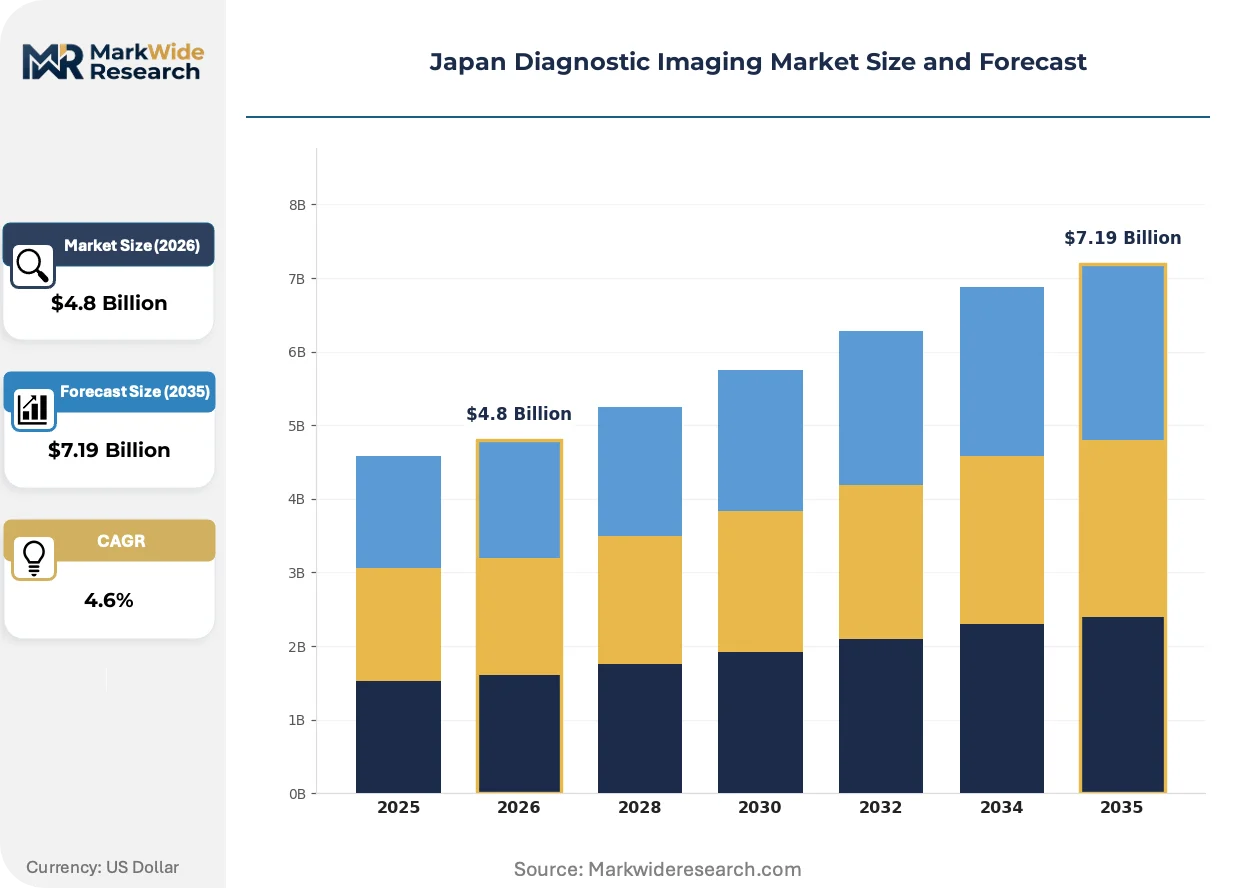
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scan, Ultrasound End User: Hospitals, Clinics, Diagnostic Centers, Research Laboratories Technology: Digital Imaging, Analog Imaging, Portable Imaging, Hybrid Imaging Application: Oncology, Neurology, Cardiology, Musculoskeletal |
| Companies Covered | Koninklijke Philips N.V., Samsung Medison Co., Ltd., Canon Medical Systems Corporation, Hitachi, Ltd., Hologic, Inc., GE Healthcare, FUJIFILM Holdings Corporation, Konica Minolta, Inc., Siemens Healthineers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Diagnostic Imaging Market Shifts & Advancements
Digital architecture is displacing analog workflows across Japanese imaging departments, with three convergent forces reshaping equipment specifications, procurement criteria, and service delivery models.
Photon-counting CT detector technology is migrating from research installations to commercial deployment at select university hospitals in Osaka and Kyoto. Toshiba Medical Systems and Canon Medical Systems are fielding first-generation systems for cardiac and pulmonary applications. The shift is compressing dose-exposure thresholds while expanding spectral imaging capabilities that were previously confined to dual-source configurations.
PMDA's software-as-medical-device guidance issued under the Pharmaceuticals and Medical Devices Act is tightening validation requirements for AI-assisted diagnostic tools. Manufacturers must demonstrate clinical utility across Japanese patient populations rather than relying on overseas trial data. Domestic developers are responding by establishing in-country training datasets and regulatory affairs capabilities.
After-sales service contracts are fragmenting from bundled equipment-service packages toward unbundled performance-based arrangements. University hospitals in Tokyo and Nagoya are piloting uptime-guarantee structures that shift downtime risk to service providers. The model is penetrating fastest among institutions with multiple vendor platforms seeking standardized SLA terms.
Japan Diagnostic Imaging Market Segmentation
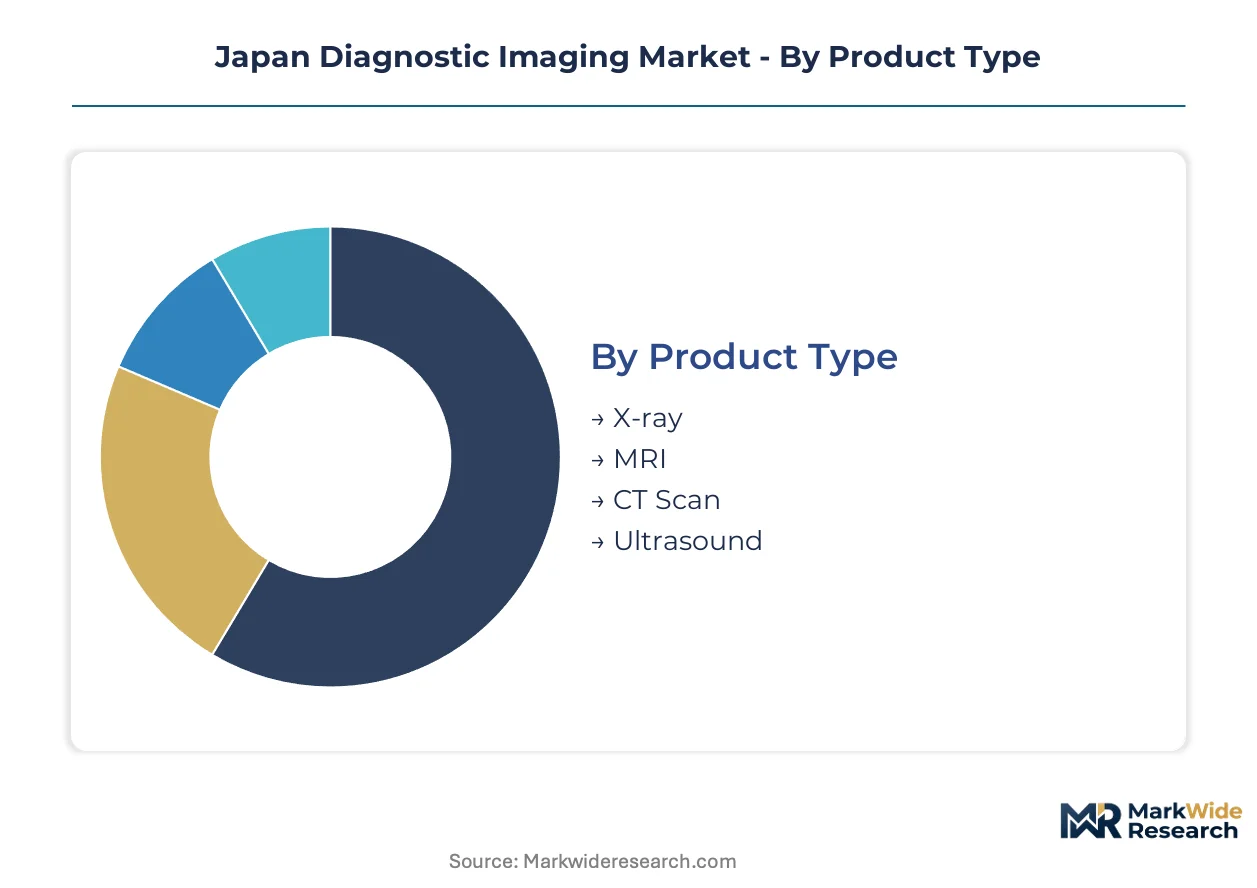
Segmentation reveals how procurement priorities diverge across Japanese healthcare infrastructure. Equipment specifications, reimbursement pathways, and clinical workflows vary sharply between metropolitan tertiary centers and rural primary care facilities.
Product Type:
Mature modalities anchor installed base maintenance while emerging technologies capture replacement expenditure.
- CT Scan:Multi-detector systems with 64-slice and above configurations dominate cancer screening programs. Tokyo's National Cancer Center and Osaka University Hospital drive demand for spectral CT capabilities that separate iodine from calcium at sub-millisecond temporal resolution. METI reimbursement adjustments for CT-based lung cancer screening compress replacement cycles to 7-9 years.
- MRI:Superconducting magnets at 1.5 Tesla and 3 Tesla field strengths command premium capital allocation for neurological and musculoskeletal diagnostics. Kanto region hospitals prioritize 3 Tesla platforms for functional neuroimaging research, while 1.5 Tesla systems satisfy routine clinical demand in prefectural medical centers.
- X-ray:Digital radiography panels and fluoroscopy systems serve high-volume screening applications including tuberculosis mass surveys.
- Ultrasound:Cart-based and point-of-care systems address obstetric, cardiac, and abdominal imaging with lower infrastructure requirements.
CT Scan retains volume leadership; MRI holds the steepest expansion curve.
End User:
Customer concentration follows bed capacity and case complexity gradients across Japan's healthcare pyramid.
- Hospitals:Tertiary academic medical centers and designated cancer hospitals concentrate procurement of hybrid imaging platforms. Keio University Hospital and Nagoya University Hospital deploy PET-MRI systems for precision oncology trials. These institutions negotiate multi-year service contracts with uptime guarantees exceeding 98%.
- Diagnostic Centers:Specialized imaging facilities focus on high-throughput screening operations with standardized protocols. Independent diagnostic centers in Tokyo's 23 wards process over 40% of metropolitan health checkup imaging volume.
- Clinics:Primary care and specialty clinics utilize compact ultrasound and digital X-ray for immediate diagnostic confirmation.
- Research Laboratories:University-affiliated imaging cores support preclinical and translational studies with preclinical MRI and micro-CT systems.
Hospitals command capital expenditure concentration; Diagnostic Centers are climbing the fastest on screening volume expansion.
Technology:
Architecture transitions from legacy analog toward computational imaging with mobility and fusion capabilities.
- Digital Imaging:PACS-integrated acquisition with DICOM standardization has displaced film-based workflows across metropolitan institutions. Direct radiography detectors and digital fluoroscopy now constitute baseline procurement specifications for equipment replacement.
- Hybrid Imaging:PET-CT and PET-MRI fusion systems integrate functional metabolic data with anatomical localization. National Cancer Center Japan and Osaka International Cancer Institute lead PET-MRI adoption for radiation therapy planning.
- Portable Imaging:Battery-powered ultrasound and mobile CT units address access gaps in Hokkaido mountain municipalities and Tohoku coastal communities lacking fixed infrastructure.
- Analog Imaging:Film-screen radiography persists only in legacy installations awaiting capital replacement cycles.
Digital Imaging dominates installed base conversion; Hybrid Imaging gains share fastest on precision oncology demand.
Application:
Clinical demand concentrates where aging demographics expand disease prevalence and screening eligibility.
- Oncology:Lung, colorectal, and gastric cancer screening programs drive CT and MRI procurement under national health insurance coverage. Stomach cancer screening reaches 40% of eligible population in prefectures with highest elderly concentration.
- Neurology:Stroke emergency protocols and dementia evaluation protocols require rapid MRI access. Japanese Society of Neuroradiology guidelines mandate diffusion-weighted imaging within 30 minutes of hospital arrival for acute stroke.
- Cardiology:Coronary CT angiography and cardiac MRI address ischemic heart disease burden. Stress perfusion MRI protocols expand at cardiovascular centers in Fukuoka and Sapporo.
- Musculoskeletal:Osteoarthritis and osteoporosis screening utilize dual-energy X-ray absorptiometry and weight-bearing MRI.
Oncology anchors procedure volume; Neurology demonstrates the steepest technology upgrade intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan tertiary centers exhibit low price elasticity for premium imaging systems, while rural prefectures face severe capital constraints that compress procurement budgets and extend replacement cycles beyond industry norms.
Kanto/Tokyo
Tokyo's concentration of designated cancer hospitals and university medical centers drives procurement of 3 Tesla MRI and spectral CT platforms. METI's biennial reimbursement revisions accelerate equipment turnover at Keio University Hospital and the National Cancer Center Japan. The Tokyo-Osaka corridor anchors hybrid imaging adoption, with PET-MRI installations concentrated at academic institutions pursuing precision oncology protocols.
Kansai/Osaka
Osaka University Hospital and Osaka International Cancer Institute lead PET-CT deployment for radiation therapy planning. PMDA's streamlined review pathways for software-as-medical-device submissions attract AI imaging developers to the Kansai biomedical cluster. Prefectural medical centers in Kyoto and Kobe balance 1.5 Tesla MRI procurement against budget constraints from municipal healthcare financing.
Chubu/Nagoya
Nagoya University Hospital pilots uptime-guarantee service contracts that shift downtime risk to equipment vendors. Aichi Prefecture's automotive industry heritage translates into manufacturing-process discipline at diagnostic device assembly facilities. Regional stroke centers expand diffusion-weighted MRI capacity under Japanese Society of Neuroradiology emergency protocols.
Kyushu
Fukuoka's cardiovascular centers deploy stress perfusion MRI protocols for ischemic heart disease evaluation. METI regional revitalization grants partially offset capital intensity barriers for 3 Tesla installations at prefectural hospitals. Kumamoto and Kagoshima medical centers rely on mobile CT units to address access gaps in outlying island communities.
Hokkaido
Sapporo's tertiary institutions anchor diagnostic imaging demand across northern Japan. Battery-powered portable ultrasound and mobile CT units serve mountain municipalities lacking fixed infrastructure. Prefectural budget limitations extend replacement cycles for digital radiography systems beyond the national average.
Japan Diagnostic Imaging Market Competitive Landscape
Integrated healthcare conglomerates and specialized imaging equipment manufacturers split the market based on portfolio breadth versus technical depth. The vendor base concentrates around three strategic archetypes: diversified electronics groups with medical divisions, pure-play diagnostic imaging specialists, and diversified industrial conglomerates with healthcare verticals. Competitive dynamics center on service contract unbundling and AI-integrated platform certification timelines.
Among diversified healthcare technology groups, Koninklijke Philips N.V. and Siemens Healthineers occupy positions emphasizing integrated digital imaging ecosystems and advanced MRI platform specialization respectively. Canon Medical Systems Corporation exemplifies the domestic manufacturing archetype, leveraging proximity to service networks for shorter response times. Samsung Medison Co., Ltd. represents the Korean electronics-based challenger model competing on portable and point-of-care system deployment.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Samsung Medison Co., Ltd. |
| Canon Medical Systems Corporation |
| Hitachi, Ltd. |
| Hologic, Inc. |
| GE Healthcare |
| FUJIFILM Holdings Corporation |
| Konica Minolta, Inc. |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Helium import concentration through Qatar and Algeria determines both premium-equipment pricing spreads and supply chain vulnerability for Japanese MRI operators. METI reimbursement compressions and PMDA certification friction feed back into procurement deferrals that reshape distributor inventory positions across domestic service networks.
Pricing Analysis
After-sales service contracts drive lifetime value for Japanese imaging equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates tertiary academic centers from prefectural hospitals and rural clinics. Price differentiation rests on field strength specifications, AI-embedded software tiers, and bundled uptime guarantees. Margins are tightening due to independent service organizations capturing maintenance revenue through remote monitoring capabilities. Rural prefectures exhibit highest price sensitivity; Tokyo's designated cancer hospitals demonstrate lowest elasticity for 3 Tesla platforms.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk for digital detector components and rare-earth magnet materials. Manufacturing concentrates in Japan for system assembly, Germany for precision gradient coils, and China for flat-panel detector substrates. Raw material dependencies include liquid helium for cryogenic cooling, gadolinium-based contrast agents, and high-purity silicon for photon-counting detectors. Single-source vulnerability in helium logistics creates allocation bottlenecks during supply disruptions. Distribution runs through authorized dealer networks with direct OEM service arms penetrating university hospital accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. PMDA certification timelines and METI reimbursement calibration create switching costs that protect incumbent installed bases.
For Market Incumbents: Insulate service contract portfolios through predictive maintenance platforms that preempt independent service organization incursions. Deepen backward integration into helium recycling infrastructure to offset Qatar supply volatility. Prioritize AI-embedded software certification investments that exploit PMDA's domestic clinical data requirements as a barrier against overseas algorithm developers. For New Entrants and Emerging Players: Portable ultrasound deployment in Hokkaido mountain municipalities and Tohoku coastal communities represents the most penetrable entry point for equipment lacking fixed infrastructure. Mobile CT units for rural stroke protocols offer secondary white-space access. Target GPO contracts at prefectural hospital consortia seeking standardized procurement terms across multi-vendor environments. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors aftermarket service specialists with remote monitoring capabilities. Long-term viability centers on unbundled performance-based contracts that shift downtime risk from operators to vendors. Acquisition target archetype: independent service organizations with established technician networks in underserved prefectures. Monitor METI medical fee schedule revision timing as inflection indicator for capital expenditure release.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Submission | Accelerates revenue recognition for AI-embedded diagnostic platforms through streamlined review pathways. |
| Helium Recycling Infrastructure Investment | Reduces operational exposure to Qatar supply disruptions for superconducting magnet cooling systems. |
| Prefectural Hospital GPO Partnership | Captures standardized procurement volume across municipal healthcare networks seeking SLA harmonization. |
| Remote Monitoring Platform Development | Enables predictive maintenance contracts that preempt independent service organization market entry. |
| Domestic Clinical Dataset Construction | Satisfies PMDA validation requirements for machine-learning algorithms using Japanese patient populations. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and aftermarket service heads and refined through secondary validation. Sources included METI medical device shipment statistics, PMDA approval databases, hospital procurement records, and Central Social Insurance Medical Council reimbursement schedules. Bottom-up equipment installation tracking and top-down healthcare expenditure analysis provided triangulation across methodology approaches.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product modality, end-user facility tier, technology architecture, and regional prefecture cluster. CAGRs were synthesized from replacement cycle velocities and reimbursement-adjusted procurement timing. Industry-specific forecast inputs incorporated METI biennial fee schedule revision patterns and PMDA software-as-medical-device review timeline trends.
Practitioners should monitor helium allocation disruptions, METI reimbursement compression magnitude, and PMDA AI guidance evolution for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mexico Mammography Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Medical Holography Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
Digital Breast Tomosynthesis (DBT) Equipment Market