
 Veterinary Catheters Market | 2026-2036
Veterinary Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Catheters Market Analytics
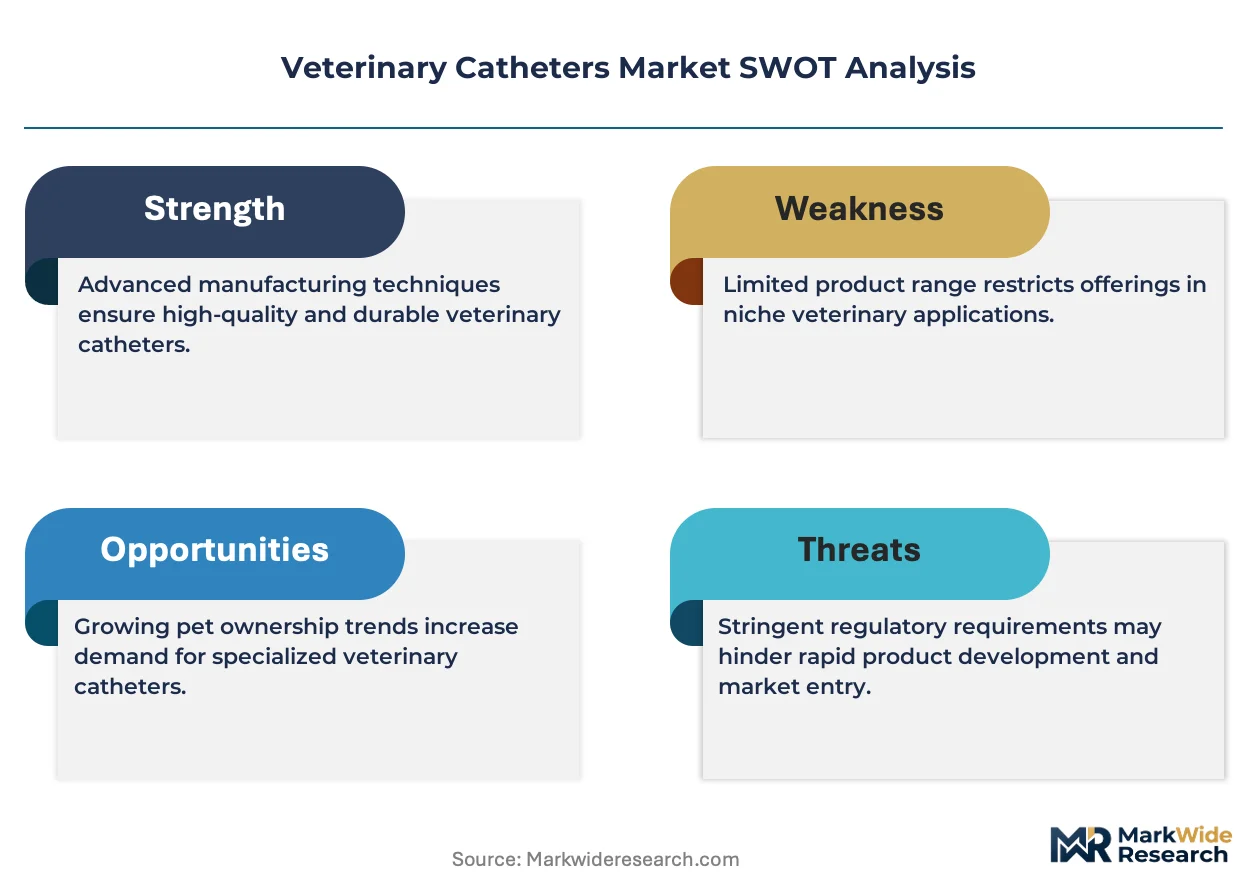
The EU Green Deal is restructuring procurement criteria across European veterinary hospital chains, favoring silicone-based disposables with lower environmental footprints. Smiths Medical leverages its European manufacturing footprint to sustain compliance with REACH-mandated material disclosures. B. Braun Vet Care anchors its competitive position through specialized catheter portfolios for equine and companion animal segments. Teleflex Incorporated competes on scale, operating centralized distribution hubs that reduce lead times for emergency veterinary orders.
Veterinary catheters are sterile, flexible tubes manufactured from silicone, polyurethane, or PVC, typically ranging from 3 French to 14 French in diameter, designed for fluid delivery, anesthesia administration, or physiological monitoring in animal patients. Their primary purpose is to provide minimally invasive vascular or urinary access during surgical procedures, critical care management, and diagnostic sampling across species. Urinary catheters command the largest revenue share due to high procedural volume in feline obstructive uropathy cases, while central venous catheters represent the fastest-expanding category as academic veterinary hospitals adopt human-standard critical care protocols. Silicone materials capture premium positioning because of superior biocompatibility in long-term indwelling applications, whereas PVC dominates high-volume, short-term use in general practice settings.
The FDA Center for Veterinary Medicine enforces biocompatibility and sterility standards that shape product development timelines and testing costs for US market entrants, while ISO 10993 biological evaluation protocols provide harmonized safety benchmarks recognized across OECD veterinary device markets. The EU Medical Device Regulation extends its influence into veterinary sectors through overlapping supply chain audits and shared manufacturing facilities with human device producers. Stakeholders must monitor evolving reimbursement frameworks for advanced veterinary interventions as these determine hospital capital allocation toward specialized catheter inventories.
Market Dynamics
The veterinary catheters market is experiencing structural compression as academic veterinary hospitals import human-standard critical care protocols, forcing manufacturers to bridge the gap between companion animal anatomy and human-device specifications without triggering full human-device regulatory pathways.
Growth Catalysts
- Feline Obstructive Uropathy Epidemiology:The rising incidence of feline lower urinary tract disease in domestic cat populations drives procedural volume for urinary catheterization across general practice and emergency settings.
- ISO 10993 Harmonization:Biological evaluation protocols recognized across OECD veterinary device markets reduce redundant testing burdens for manufacturers seeking multi-jurisdiction approvals.
- Silicone Biocompatibility Premium:Superior performance in long-term indwelling applications commands price premiums that justify manufacturing complexity and material costs.
Market Restraints
- Specialty Resin Supply Concentration:Medical-grade silicone precursor manufacturing clusters in Germany and Japan create geographic vulnerability for catheter producers dependent on just-in-time material flows.
- FDA Center for Veterinary Medicine Testing Burden:Biocompatibility and sterility validation requirements extend product development timelines and elevate capital requirements for US market entrants.
- PVC Substitution Ceiling:Environmental liability concerns and REACH-mandated material disclosures constrain short-term PVC catheter growth despite cost advantages in high-volume general practice.
Strategic Opportunities
- Equine Critical Care Expansion:Underpenetrated large-animal interventional capabilities at referral hospitals create demand for specialized large-bore catheter portfolios.
- EU Green Deal Procurement Criteria:Restructured purchasing frameworks across European veterinary hospital chains favor silicone-based disposables with documented lower environmental footprints.
- Telemedicine-Triage Integration:Remote consultation platforms are compressing diagnostic-to-treatment intervals, accelerating demand for pre-positioned catheter inventories at satellite clinics.
Industry Challenges
- Veterinary Interventionalist Training Pipeline:The scarcity of residency-trained specialists capable of advanced catheter placement limits adoption velocity for central venous and arterial product categories.
- Dual-Use Facility Compliance Complexity:Shared manufacturing facilities with human medical device producers subject veterinary lines to EU MDR audit scope expansion and quality system overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Catheters Market |
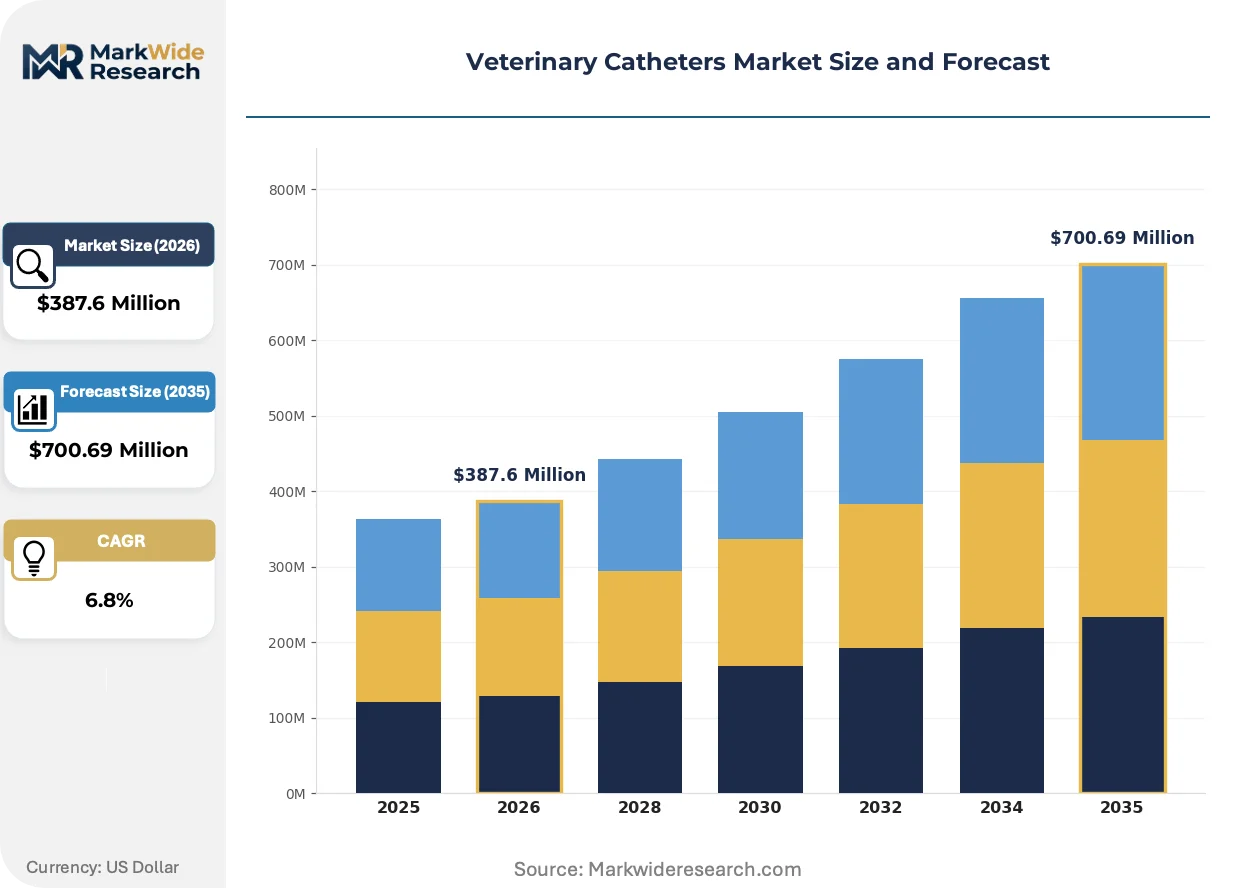
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urinary Catheters, IV Catheters, Endotracheal Tubes, Central Venous Catheters Material: Silicone, Polyurethane, PVC, Latex End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Emergency Services Application: Fluid Administration, Anesthesia, Diagnostics, Monitoring |
| Companies Covered | Genia, SAI Infusion Technologies, Smiths Medical, Teleflex Incorporated, B. Braun Vet Care, Vygon S.A., Millpledge Veterinary, Cook Medical, Jørgen Kruuse A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Catheters Market Evolving Landscape
Material science convergence with digital manufacturing is collapsing the traditional trade-off between catheter customization and unit economics, enabling patient-specific geometries at production scales previously reserved for standardized SKUs.
Antimicrobial surface modification technology is unifying infection resistance with mechanical performance in polyurethane formulations. Academic veterinary hospitals in the United States and Japan are piloting these coated catheters in immunocompromised oncology patients. The technology is unifying previously separate product categories—prophylactic and therapeutic—into single-device protocols that reduce inventory complexity.
REACH-mandated material disclosure requirements are forcing reformulation of plasticizer systems in PVC catheters across European supply chains. Manufacturers must document full substance inventories from resin to finished device. German and French veterinary hospital chains are now requiring REACH-compliant documentation as a gate for contract eligibility, compressing procurement timelines for non-compliant suppliers.
Consolidation among specialty veterinary practice groups is centralizing purchasing authority and compressing supplier rosters. Multi-site hospital networks in the United States are negotiating system-wide catheter contracts that displace fragmented clinic-level ordering. Texas and California veterinary mega-groups are pioneering direct manufacturer relationships that bypass traditional distribution markups, forcing distributors to unbundle logistics from technical support services.
Veterinary Catheters Market Segmentation
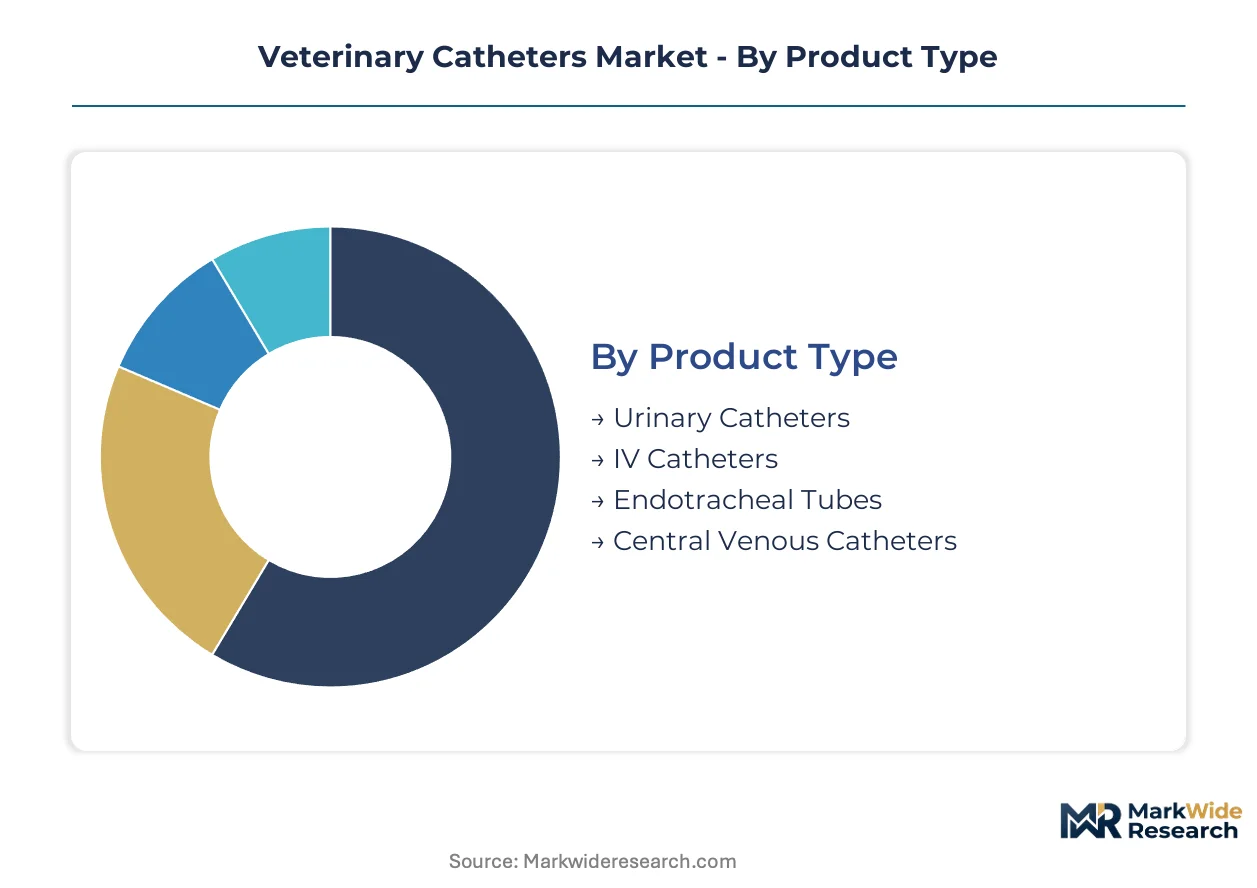
Veterinary catheter procurement patterns diverge sharply across product categories, with material specifications and end-use settings dictating margin structures. Manufacturers must align production footprints to these segment-specific demand clusters rather than treating the market as uniform.
Product Type:
Supply concentration clusters around urinary and IV catheter lines, where production scale economies dominate manufacturing investment decisions.
- Urinary Catheters:Silicone or polyurethane tubes ranging 3-14 French, designed for feline obstructive uropathy management and post-surgical drainage. Demand concentrates in United States emergency and specialty practices where pet insurance coverage drives procedural volume.
- IV Catheters:Peripheral vascular access devices in standardized gauges for fluid and medication delivery. German and Japanese general practice networks consume high volumes of short-term PVC variants, while silicone formulations penetrate long-term critical care.
- Endotracheal Tubes:Cuffed and uncuffed airway management devices sized across species from feline to equine.
- Central Venous Catheters:Multi-lumen devices for pressure monitoring and parenteral nutrition in academic hospital intensive care units.
Urinary catheters absorb the bulk of installed capacity; central venous catheters are expanding most quickly.
Material:
Cost tier differentiation separates premium silicone formulations from commodity PVC production, with polyurethane occupying a technical mid-market position.
- Silicone:Platinum-cured elastomer with superior biocompatibility for indwelling applications exceeding 72 hours. United States academic veterinary hospitals specify silicone for oncology and critical care patients, justifying 40-60% price premiums over PVC alternatives.
- Polyurethane:Thermoplastic with tunable durometer enabling thin-wall high-flow designs. Japanese manufacturers favor polyurethane for antimicrobial coating compatibility in advanced product development.
- PVC:Plasticized polymer dominating high-volume, short-term general practice use across Germany and France despite REACH-mandated reformulation pressures.
- Latex:Natural rubber option retained for cost-sensitive markets and specific compatibility requirements.
Silicone commands the highest margin tier; polyurethane is gaining share fastest as coating technologies mature.
End User:
Customer type determines order frequency, technical support requirements, and contract structure, with institutional buyers extracting volume concessions unavailable to independent clinics.
- Veterinary Clinics:Independent and small-group general practices purchasing standardized SKUs through distributor channels. United States clinic consolidation is compressing supplier rosters and shifting procurement toward system-wide contracts.
- Animal Hospitals:Multi-specialty referral institutions with in-house anesthesia, surgery, and critical care capabilities. German university hospitals drive specifications for central venous and arterial catheter portfolios.
- Research Laboratories:Contract research organizations and academic facilities with protocol-specific device requirements.
- Emergency Services:After-hours and urgent care networks requiring rapid inventory replenishment and 24-hour technical support access.
Animal hospitals concentrate purchasing volume; emergency services are expanding catheter consumption fastest as network coverage broadens.
Application:
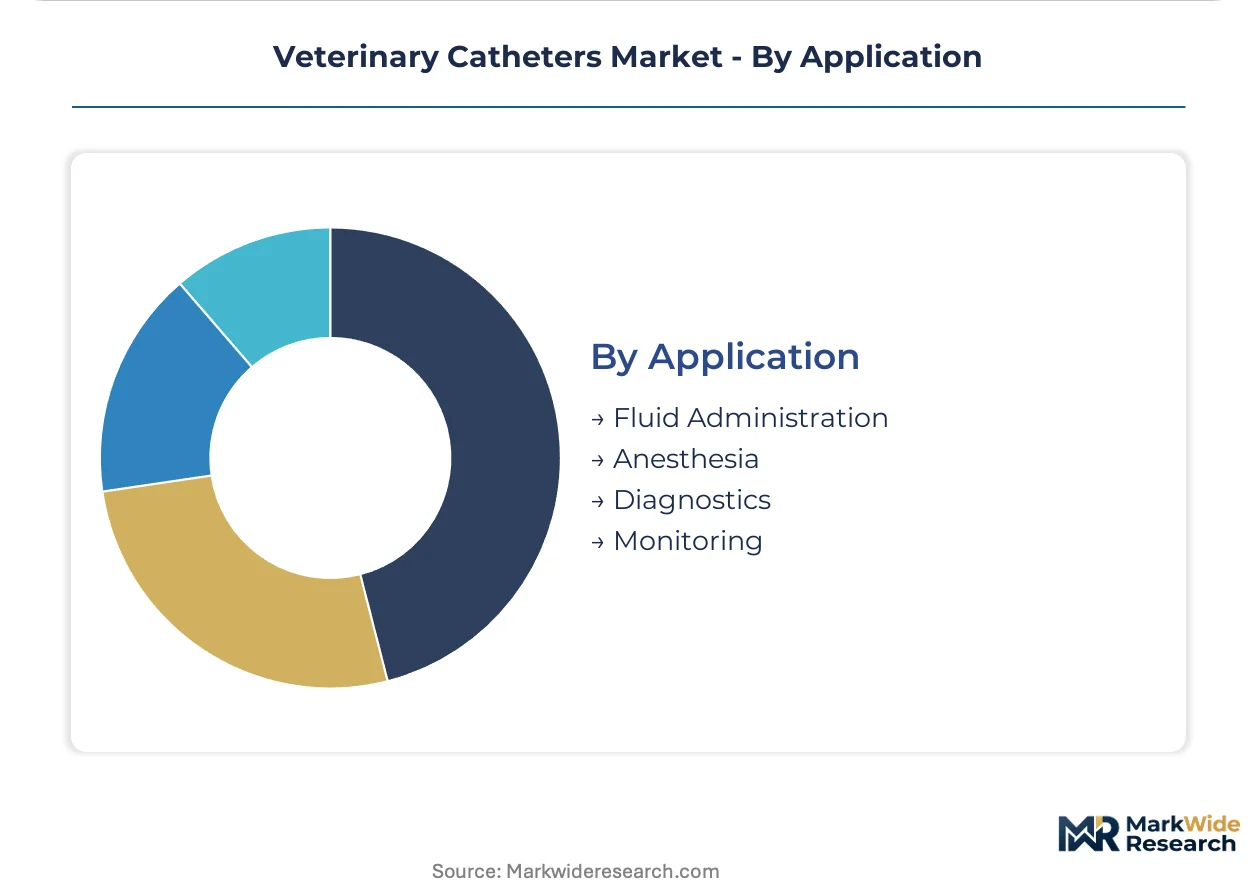
Volume distribution across use cases reflects the procedural mix of companion versus large animal practice, with anesthesia and fluid administration forming the baseline demand layer.
- Fluid Administration:Crystalloid and colloid delivery for resuscitation, maintenance, and therapeutic purposes. Japanese small animal practices generate consistent demand for peripheral IV catheter replacements every 72-96 hours per patient.
- Anesthesia:Inhalant delivery and airway management during surgical procedures. United States specialty surgery centers specify cuffed endotracheal tubes with pressure monitoring capabilities.
- Diagnostics:Blood sampling, urine collection, and contrast injection for imaging studies.
- Monitoring:Central venous pressure, arterial blood pressure, and cardiac output measurement in critical care settings.
Fluid administration anchors baseline production planning; monitoring applications are climbing the fastest as critical care protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of medical-grade silicone precursors clusters in Germany and Japan, while consumption concentrates in the United States where pet insurance penetration drives procedural volume. This geographic split shapes procurement logistics and regulatory compliance burdens across the value chain.
United States
Specialty veterinary clinics in Texas and California are expanding interventional capabilities for critical care. The FDA Center for Veterinary Medicine enforces stringent biocompatibility requirements that extend product development timelines. Academic veterinary hospitals in the Northeast corridor are adopting human-standard protocols, accelerating demand for central venous catheter portfolios.
Germany
General practice networks consume high volumes of short-term PVC catheters despite REACH-mandated reformulation pressures. ECHA disclosure requirements are forcing manufacturers to document full substance inventories from resin to finished device. The Baden-Württemberg industrial corridor hosts concentrated medical-grade silicone precursor production serving European catheter fabricators.
Japan
Small animal practices generate consistent demand for peripheral IV catheter replacements every 72-96 hours per patient. METI standards harmonize with ISO 10993 protocols to reduce redundant testing burdens. The Kansai region anchors polyurethane formulation expertise for antimicrobial coating compatibility in advanced product development.
United Kingdom
Multi-site veterinary hospital networks are negotiating system-wide catheter contracts that displace fragmented clinic-level ordering. The EU Medical Device Regulation extends audit scope into shared manufacturing facilities with human device producers. The Southeast England corridor concentrates distribution infrastructure for emergency veterinary supply chains.
France
Veterinary hospital chains in the Île-de-France region now require REACH-compliant documentation as a gate for contract eligibility. ANSM oversight converges with EU MDR requirements for facilities producing both human and veterinary devices. The Lyon cluster supports specialized catheter portfolios for equine and companion animal segments.
Veterinary Catheters Market Competitive Landscape
The competitive structure tilts toward diversified medical device conglomerates with veterinary-specific divisions. Market concentration is moderate, with tiered positioning separating premium silicone specialists from high-volume PVC producers. Two archetypes dominate: integrated human-veterinary device manufacturers leveraging shared regulatory compliance infrastructure, and pure-play veterinary specialists capturing niche species applications. Competitive moves center on M&A to acquire antimicrobial coating technologies and strategic partnerships with academic veterinary hospitals for protocol co-development.
Among diversified medical device conglomerates, Smiths Medical, Teleflex Incorporated, and B. Braun Vet Care occupy positions that exemplify scale-driven competitive advantages. Smiths Medical leverages European manufacturing footprints to sustain REACH compliance. Teleflex operates centralized distribution hubs reducing lead times for emergency orders. B. Braun Vet Care anchors its position through specialized portfolios for equine and companion animal segments.
| Leading Market Players |
|---|
| Genia |
| SAI Infusion Technologies |
| Smiths Medical |
| Teleflex Incorporated |
| B. Braun Vet Care |
| Vygon S.A. |
| Millpledge Veterinary |
| Cook Medical |
| Jørgen Kruuse A/S |
| Others |
Value Network & Pricing Analysis
EU Green Deal procurement criteria are restructuring purchasing frameworks across European veterinary hospital chains, compelling manufacturers to reformulate silicone precursor sourcing and absorb certification documentation costs that compress margins on mid-tier polyurethane lines. This demand-side specification shift forces supply chains to pivot toward REACH-compliant material flows, creating pricing power for German and Japanese resin producers while squeezing general-practice PVC suppliers.
Pricing Analysis
Outcome-based pricing anchored to indwelling duration and infection resistance metrics separates premium silicone portfolios from commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by biocompatibility certification tier and customization depth. Cost compression in PVC general-practice segments is intensifying because REACH-mandated plasticizer reformulations add documentation overhead without corresponding price recovery. Emergency veterinary networks exhibit lowest price sensitivity due to 24-hour replenishment requirements, while independent clinics negotiate aggressively on standardized SKUs.
Supply Chain Analysis
Freight cost escalation on medical-grade silicone precursors from Germany and Japan is reshaping regional manufacturing economics for catheter fabricators. Raw material sourcing draws from platinum-cured elastomer feedstock clusters in Baden-Württemberg, thermoplastic polyurethane formulation expertise in Kansai, and plasticized polymer compounding in Lyon. Single-source vulnerability concentrates in German medical-grade silicone precursor production serving European fabricators. Distribution runs through centralized hubs operated by diversified device conglomerates, with satellite clinic pre-positioning accelerating in Texas and California veterinary networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary catheter manufacturing is consolidating around REACH-compliant silicone specialists and antimicrobial coating technology holders, with EU MDR audit scope expansion and distributor disintermediation pressuring sub-scale PVC producers toward exit or acquisition.
For Market Incumbents: Extend antimicrobial coating R&D partnerships with Japanese polyurethane formulators to defend against emerging coating-technology specialists. Deepen backward integration into platinum-cured silicone precursor production through offtake agreements with Baden-Württemberg resin manufacturers, securing supply continuity as REACH documentation requirements tighten. For New Entrants and Emerging Players: Antimicrobial surface modification technology offers entry leverage into immunocompromised oncology catheter protocols at United States academic veterinary hospitals. Equine critical care large-bore portfolios remain underpenetrated at referral institutions, with direct manufacturer relationships bypassing traditional distribution markups as the viable go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors coating-technology specialists and REACH-compliant silicone compounders ahead of EU Green Deal procurement mandate expansion. Long-term viability hinges on regulatory compliance infrastructure rather than volume scale alone. Monitor FDA Center for Veterinary Medicine biocompatibility guidance revisions as the inflection signal for accelerated central venous catheter adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Partnership | Japanese polyurethane formulators enable infection-resistant catheter protocols for oncology patients. |
| REACH Compliance Certification | German resin documentation gates contract eligibility with Île-de-France hospital chains. |
| Equine Portfolio Expansion | Lyon manufacturing cluster supports specialized large-bore catheter development for referral hospitals. |
| Emergency Distribution Hub | Centralized replenishment infrastructure reduces lead times for 24-hour veterinary networks. |
| Academic Hospital Protocol Co-Development | Northeast corridor teaching hospitals validate human-standard critical care catheter specifications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with veterinary purchasing committee members, biomedical engineers at academic hospitals, GPO contracts managers, and distributor logistics heads. FDA Center for Veterinary Medicine submission databases, ECHA REACH registration dossiers, ISO 10993 biological evaluation protocols, and European veterinary hospital procurement contracts provided triangulation points. Bottom-up catheter volume estimates by material tier and end-use setting reconciled against top-down market value assessments.
Data-stream reconciliation across shipment records, hospital procurement databases, and manufacturer revenue disclosures shaped the analytical framework. Segmentation dimensions modeled include catheter type, material formulation, end-user category, application purpose, and regional regulatory cluster. CAGRs derived from trend extrapolation of procedural volumes, material substitution elasticities, and reimbursement framework evolution. Antimicrobial coating adoption curves and EU Green Deal procurement timeline assumptions informed trajectory projections across the analysis window.
Several conditions sit outside the modeled scope, including sudden FDA biocompatibility standard revisions, disruptive antimicrobial resistance patterns altering coating efficacy valuations, and macroeconomic shocks to pet insurance penetration rates. Forecasts reflect documented assumptions about specialist training pipeline expansion and REACH enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Plethysmograph Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
China Drug Delivery Devices Market