
 Magnetic Resonance Imaging (MRI) Contrast Agents Market | 2026-2036
Magnetic Resonance Imaging (MRI) Contrast Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Resonance Imaging (MRI) Contrast Agents Market Foresight
Macrocyclic chelate specifications is unwinding older linear formulations across the MRI contrast agent landscape. Bayer AG leverages its integrated radiology portfolio to sustain manufacturing scale in gadolinium-based production. Bracco Imaging anchors European supply through specialized contrast media facilities. GE HealthCare differentiates via technology leadership in high-relaxivity agent development.
Magnetic resonance imaging contrast agents are paramagnetic or superparamagnetic compounds, typically formulated as gadolinium chelates or iron oxide nanoparticles, that alter local magnetic field properties to enhance tissue visualization during MRI procedures. These agents function by shortening T1 or T2 relaxation times of surrounding water protons, enabling radiologists to distinguish pathological from normal tissue with greater diagnostic confidence. Gadolinium-based formulations occupy the dominant commercial position due to their established efficacy profile and broad regulatory approval across neurological and oncological indications. Intravenous administration routes command the primary volume channel, while diagnostic imaging centers represent the fastest-growing end-user segment as outpatient procedural volumes expand.
The FDA maintains stringent post-market surveillance requirements for gadolinium-based agents through its pharmacovigilance framework, while the EMA's PRAC has issued specific restrictions on linear gadolinium retention risks that reshape European prescribing patterns. ISO 10993 biocompatibility standards govern preclinical safety evaluation protocols, creating compliance barriers for new market entrants. Stakeholders must monitor evolving regulatory distinctions between macrocyclic and linear chelate classifications to anticipate reimbursement and formulary positioning shifts.
Market Dynamics
The FDA's pharmacovigilance framework for gadolinium retention is compressing formulation timelines and forcing manufacturers to accelerate macrocyclic chelate transitions ahead of scheduled patent expirations.
Growth Catalysts
- EMA PRAC Restrictions:European prescribing limitations on linear gadolinium agents are redirecting volume toward macrocyclic alternatives, expanding the addressable premium formulation segment.
- Oncology Protocol Expansion:Major hospital systems are embedding gadolinium-enhanced sequences into standardized cancer staging workflows, creating procedural pull-through demand.
- High-Field MRI Installations:Concentrated capital deployment across specialized diagnostic imaging centers in the United States is elevating relaxivity specifications and agent performance requirements.
Market Restraints
- Gadolinium Supply Concentration:Rare earth processing capacity clusters in China, creating raw material dependency and geopolitical exposure for chelate manufacturers.
- Biocompatibility Certification Barriers:ISO 10993 preclinical evaluation protocols impose extended timelines and capital requirements that filter new entrants from commercialization.
- Iron Oxide Nanoparticle Substitution:Superparamagnetic alternatives for liver and lymph node imaging are capturing specific indication share from gadolinium-based agents.
Strategic Opportunities
- Outpatient Diagnostic Imaging Centers:Ambulatory procedural volume expansion in the United States is creating channel-specific formulation and packaging demand distinct from hospital procurement.
- Macrocyclic-Linear Regulatory Divergence:Reimbursement and formulary positioning gaps between chelate classifications are opening premium positioning windows for compliant manufacturers.
- Artificial Intelligence-Assisted Protocol Optimization:Convergence of machine learning-based scan timing and contrast dosing algorithms is enabling personalized administration models.
Industry Challenges
- Specialized Radiopharmaceutical Manufacturing Talent:GMP-qualified personnel scarcity in chelate synthesis and aseptic filling operations is constraining production scale-up velocity.
- Legacy Linear Formulation Inventory Transition:Supply chain reconfiguration friction from EMA-mandated withdrawals is forcing write-downs and distribution channel restructuring.
- Multi-Jurisdiction Pharmacovigilance Coordination:Divergent FDA and EMA post-market surveillance reporting requirements are elevating compliance operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Resonance Imaging (MRI) Contrast Agents Market |
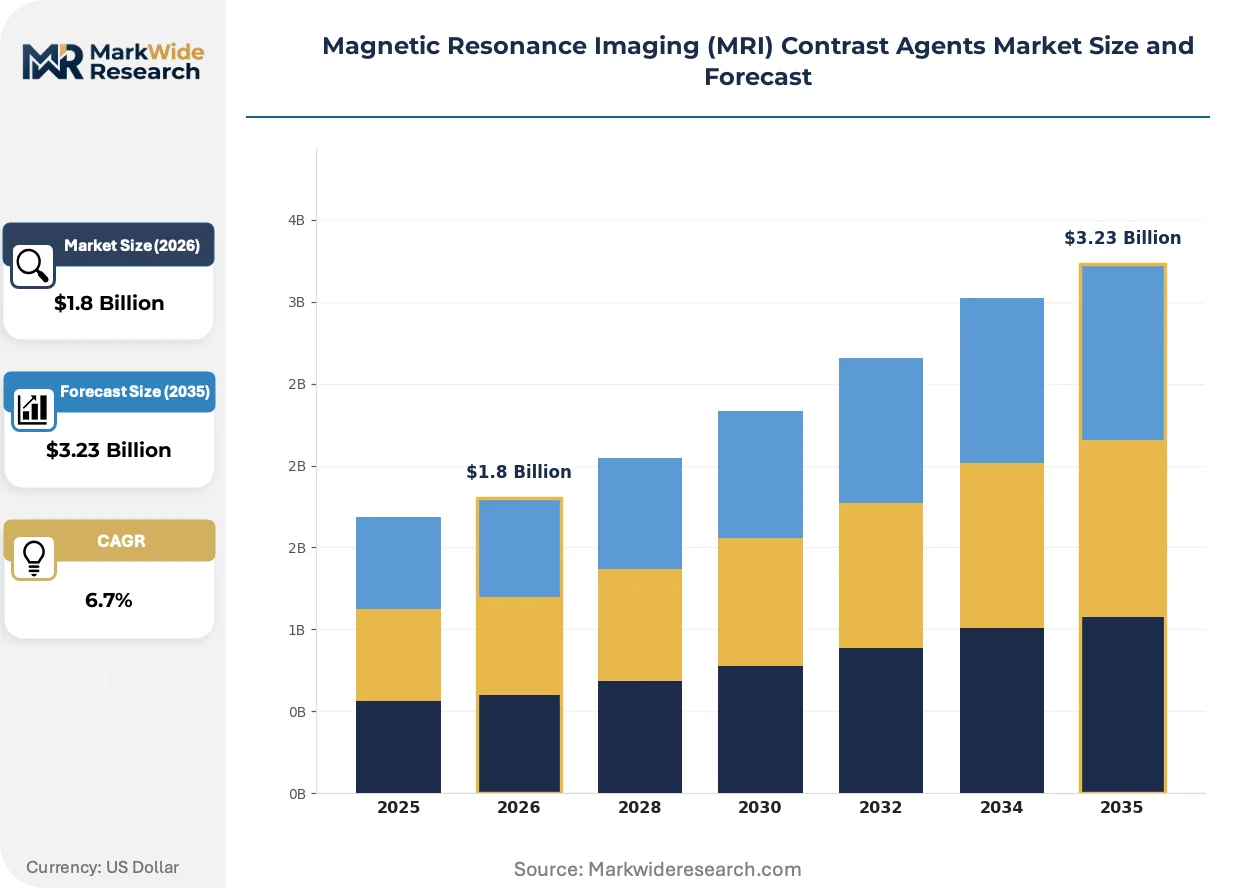
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gadolinium-based, Iron-based, Manganese-based, Others End User: Hospitals, Diagnostic Imaging Centers, Research Laboratories, Outpatient Facilities Administration Route: Intravenous, Oral, Intra-arterial, Subcutaneous Application: Neurology, Cardiology, Oncology, Musculoskeletal |
| Companies Covered | Bayer AG, Bracco Imaging, Guerbet, GE HealthCare, Fresenius Kabi, Lantheus Holdings, Canon Medical Systems, Zydus Lifesciences, Farmak Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Resonance Imaging (MRI) Contrast Agents Market Shifts & Advancements
Macrocyclic chelate architecture is displacing legacy linear formulations across the MRI contrast agent landscape, while artificial intelligence integration and ambulatory channel expansion are reconfiguring delivery models and procurement patterns.
High-relaxivity gadolinium complexes are bifurcating the premium agent segment from standard macrocyclic offerings. Tertiary academic medical centers are adopting these formulations for high-field 3T and 7T protocols where signal enhancement efficiency determines diagnostic throughput. The technology is bifurcating prescribing patterns into performance-tiered categories that align reimbursement with relaxivity metrics rather than chelate class alone.
REACH authorization requirements for gadolinium-containing substances are tightening environmental discharge controls across European manufacturing facilities. ECHA substance evaluation processes are extending registration timelines and elevating waste treatment capital requirements for production sites. German and French formulation plants are most affected, with operators investing in closed-loop water recovery systems to maintain operating permits.
Hospital procurement departments are consolidating contrast agent purchasing through radiology service line agreements rather than standalone pharmaceutical tenders. Group purchasing organizations are capturing aggregated volume from previously independent imaging centers, compressing vendor negotiation leverage. This concentration is most visible in the United States, where integrated delivery networks now control majority outpatient MRI procedural volume.
Magnetic Resonance Imaging (MRI) Contrast Agents Market Segmentation
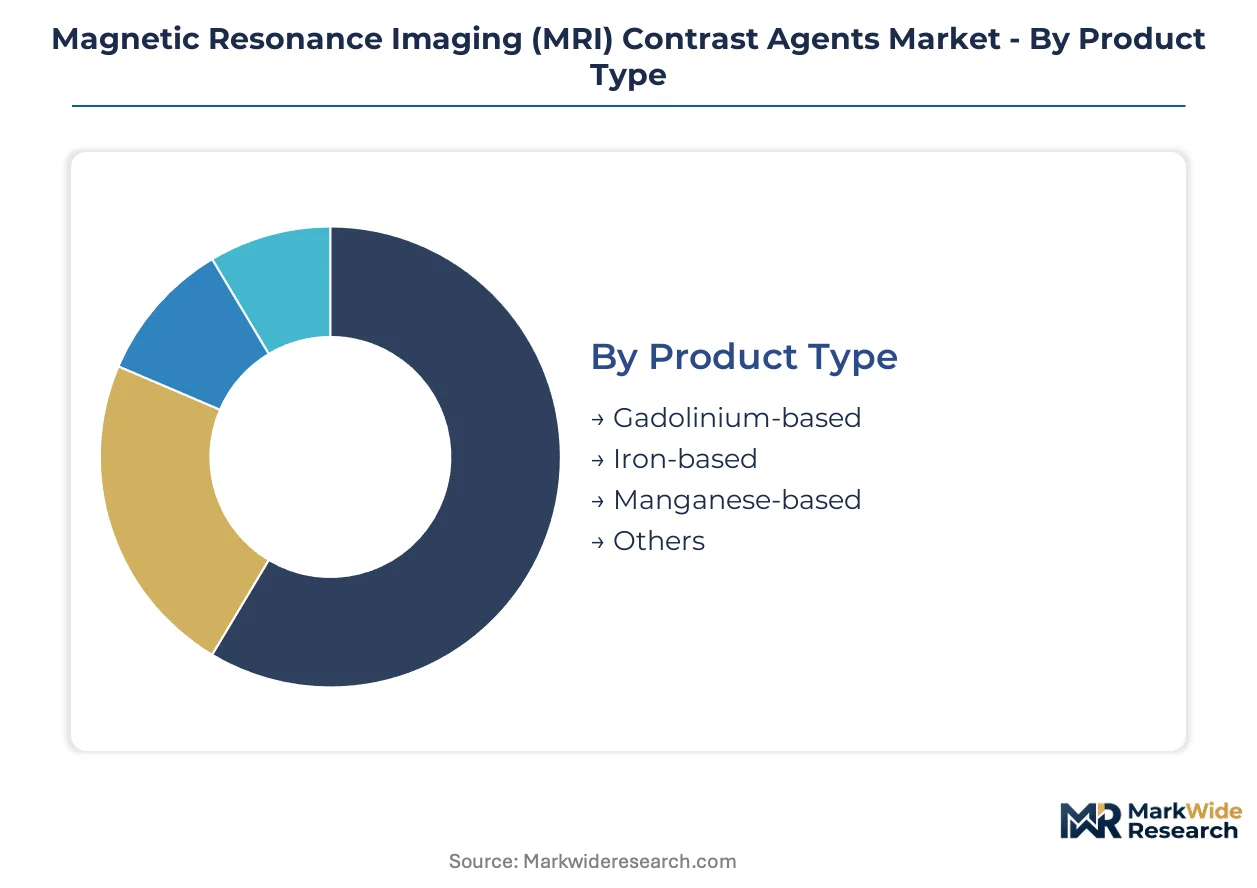
MRI contrast agent procurement flows through distinct channel hierarchies that reshape formulation requirements and packaging specifications. Understanding segment-level demand concentration enables manufacturers to align production capacity with procedural volume expansion.
Product Type:
Gadolinium-based formulations dominate hospital procurement through radiology service line agreements, while iron-based alternatives capture specialized liver imaging protocols via academic medical center tenders.
- Gadolinium-based:Paramagnetic chelates—macrocyclic and linear architectures—shorten T1 relaxation times for enhanced tissue contrast. Demand concentrates in United States oncology departments where high-field 3T and 7T installations drive premium macrocyclic uptake amid FDA retention safety reviews.
- Iron-based:Superparamagnetic iron oxide nanoparticles exploit T2 shortening effects for reticuloendothelial system imaging. German and French hospital systems are expanding liver and lymph node protocols following EMA PRAC restrictions on linear gadolinium alternatives.
- Manganese-based:Paramagnetic manganese chelates serve niche hepatobiliary indications where gadolinium contraindications exist.
- Others:Emerging barium and perfluorocarbon formulations occupy experimental and veterinary imaging channels.
By volume, Gadolinium-based leads. By growth pace, Iron-based is gaining share fastest amid regulatory pressure on linear chelate retention.
End User:
Cost tier stratification separates capital-intensive hospital installations from ambulatory diagnostic centers where procedure throughput determines procurement economics.
- Hospitals:Integrated delivery networks aggregate contrast agent purchasing through enterprise radiology contracts. United States hospital systems embed gadolinium-enhanced sequences into standardized cancer staging workflows, creating procedural pull-through demand for high-relaxivity formulations.
- Diagnostic Imaging Centers:Outpatient facilities represent the fastest-expanding channel as ambulatory MRI procedural volumes climb. These centers favor single-dose prefilled syringes and streamlined macrocyclic protocols that minimize inventory complexity.
- Research Laboratories:Academic and commercial research sites procure specialized agents for clinical trial imaging endpoints and novel indication development.
- Outpatient Facilities:Freestanding surgical and specialty clinics administer contrast for preoperative planning and postoperative monitoring.
By installed base, Hospitals dominate. By expansion trajectory, Diagnostic Imaging Centers are climbing the fastest.
Administration Route:
Volume concentration in intravenous delivery creates manufacturing scale advantages that oral and specialized routes cannot match.
- Intravenous:Bolus and power injector administration commands the primary volume channel across all end-user segments. Prefilled syringe and bulk vial formats align with United States hospital formulary standardization and European ambulatory center procurement.
- Oral:Gastrointestinal tract visualization for enterography and pelvic floor imaging occupies secondary indication share.
- Intra-arterial:Catheter-directed delivery supports specialized vascular and oncologic interventional protocols.
- Subcutaneous:Lymphatic mapping applications in sentinel node biopsy procedures drive limited procedural demand.
By procedure count, Intravenous leads. By indication expansion, Intra-arterial shows steepest trajectory amid interventional oncology growth.
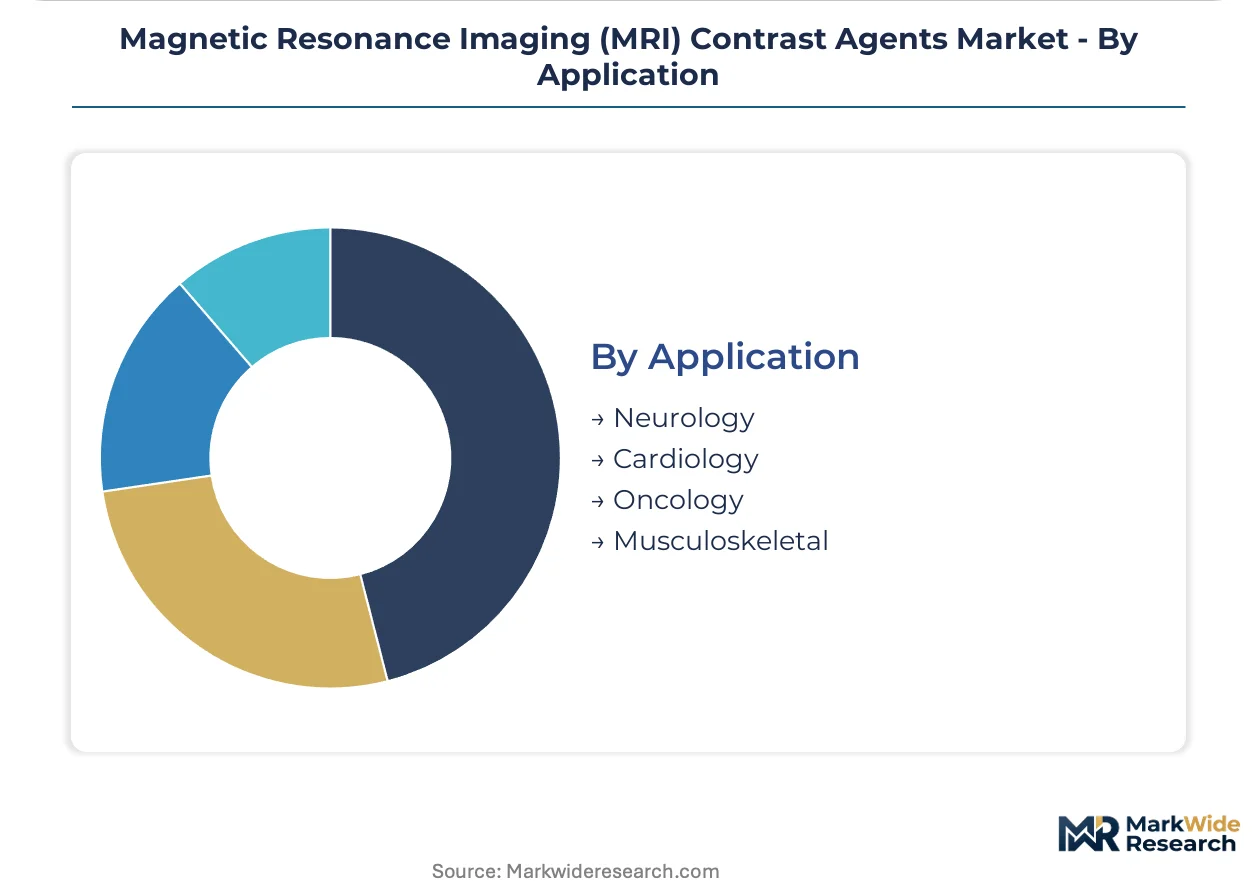
Application:
Clinical workflow integration varies by specialty, with oncology embedding contrast protocols into standardized pathways while cardiology adoption remains indication-specific.
- Neurology:Blood-brain barrier imaging and demyelinating disease protocols anchor gadolinium demand. United States academic medical centers are adopting high-relaxivity agents for 7T research protocols where signal enhancement efficiency determines diagnostic confidence.
- Oncology:Tumor characterization, staging, and treatment response monitoring drive the fastest protocol expansion. Major hospital systems are standardizing gadolinium-enhanced sequences across solid tumor workflows, creating sustained procedural pull-through.
- Cardiology:Stress perfusion and viability imaging occupy selective use patterns amid competing non-contrast modalities.
- Musculoskeletal:Joint and soft tissue inflammation assessment supports sports medicine and rheumatology applications.
By protocol penetration, Neurology leads. By workflow expansion, Oncology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China controls rare earth processing capacity that feeds chelate manufacturers across North America and Europe, creating a trade-flow dependency that shapes regional formulation strategies and inventory management.
United States
FDA pharmacovigilance requirements for gadolinium retention are accelerating macrocyclic transitions at major hospital systems. The agency's ongoing safety reviews reshape prescribing protocols across neurological and oncological indications. High-field 3T and 7T installations concentrate in tertiary academic medical centers in Boston, New York, and Houston, driving premium agent specifications.
Germany
EMA PRAC restrictions on linear gadolinium agents redirect hospital procurement toward macrocyclic alternatives. REACH authorization requirements tighten environmental discharge controls at manufacturing facilities. Formulation plants in Ludwigshafen and Frankfurt invest in closed-loop water recovery systems to maintain operating permits.
China
Rare earth processing clusters in Inner Mongolia and Jiangxi supply refined gadolinium oxide to global chelate manufacturers. NMPA regulatory harmonization with international standards accelerates domestic macrocyclic agent approvals. Shanghai and Beijing host expanding diagnostic imaging center networks that standardize contrast protocols.
Japan
PMDA post-market surveillance frameworks align with FDA retention safety evaluations. METI industrial policy supports high-relaxivity agent development through academic-industry partnerships. Osaka and Tokyo medical device clusters integrate contrast optimization into MRI system design.
India
CDSCO streamlined approval pathways for macrocyclic formulations expand diagnostic access in tier-1 cities. PLI scheme incentives attract contract manufacturing investment for export-oriented chelate production. Hyderabad and Ahmedabad pharmaceutical corridors develop specialized contrast media capabilities.
Magnetic Resonance Imaging (MRI) Contrast Agents Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and geographic coverage dimensions. Bayer AG and GE HealthCare anchor the consolidated tier through integrated radiology portfolios, while mid-scale European and Asian manufacturers occupy specialized niches. Three archetypes dominate: diversified healthcare conglomerates with captive chelate synthesis, standalone contrast media specialists with regional manufacturing depth, and emerging market contract manufacturers serving cost-sensitive procurement. Competitive moves concentrate on macrocyclic portfolio transitions and ambulatory channel packaging innovations.
Among diversified healthcare conglomerates, Bayer AG exemplifies the integrated radiology portfolio archetype, combining agent manufacturing with imaging system distribution. Bracco Imaging occupies a position within the European specialist tier, anchoring regional supply through dedicated contrast media infrastructure. GE HealthCare represents the technology-led archetype, with high-relaxivity development capabilities aligned to premium hospital system procurement. These three entities illustrate the competitive segmentation between scale-driven diversification, geographic specialization, and performance-tiered innovation.
| Leading Market Players |
|---|
| Bayer AG |
| Bracco Imaging |
| Guerbet |
| GE HealthCare |
| Fresenius Kabi |
| Lantheus Holdings |
| Canon Medical Systems |
| Zydus Lifesciences |
| Farmak Group |
| Others |
Supply & Pricing Matrix
ISO 10993 biocompatibility certification gates both supplier qualification and price tiering in MRI contrast agents, creating a dual barrier where only manufacturers with validated toxicology dossiers can access premium macrocyclic pricing while uncertified entrants compete solely on commoditized linear formulations.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through radiology service line agreements that aggregate volume across integrated delivery networks. Pricing stratifies across high-relaxivity premium tiers, standard macrocyclic mid-tiers, and economy linear formulations, with differentiation driven by relaxivity performance metrics and FDA retention safety profiles. Cost compression in the linear segment is intensifying because EMA-mandated withdrawals force inventory write-downs and distressed liquidation. Diagnostic imaging centers exhibit the highest price sensitivity due to thin procedural margins, while tertiary academic medical centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for gadolinium oxide shipments from Chinese rare earth processors. Raw material supply draws from China's Inner Mongolia and Jiangxi refining clusters, with chelate synthesis concentrated in Germany, France, and the United States. Single-source vulnerability pervades the upstream rare earth segment, where geopolitical friction threatens concentrate access. Distribution runs through specialized radiopharmaceutical cold chains serving hospital formularies and ambulatory imaging centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
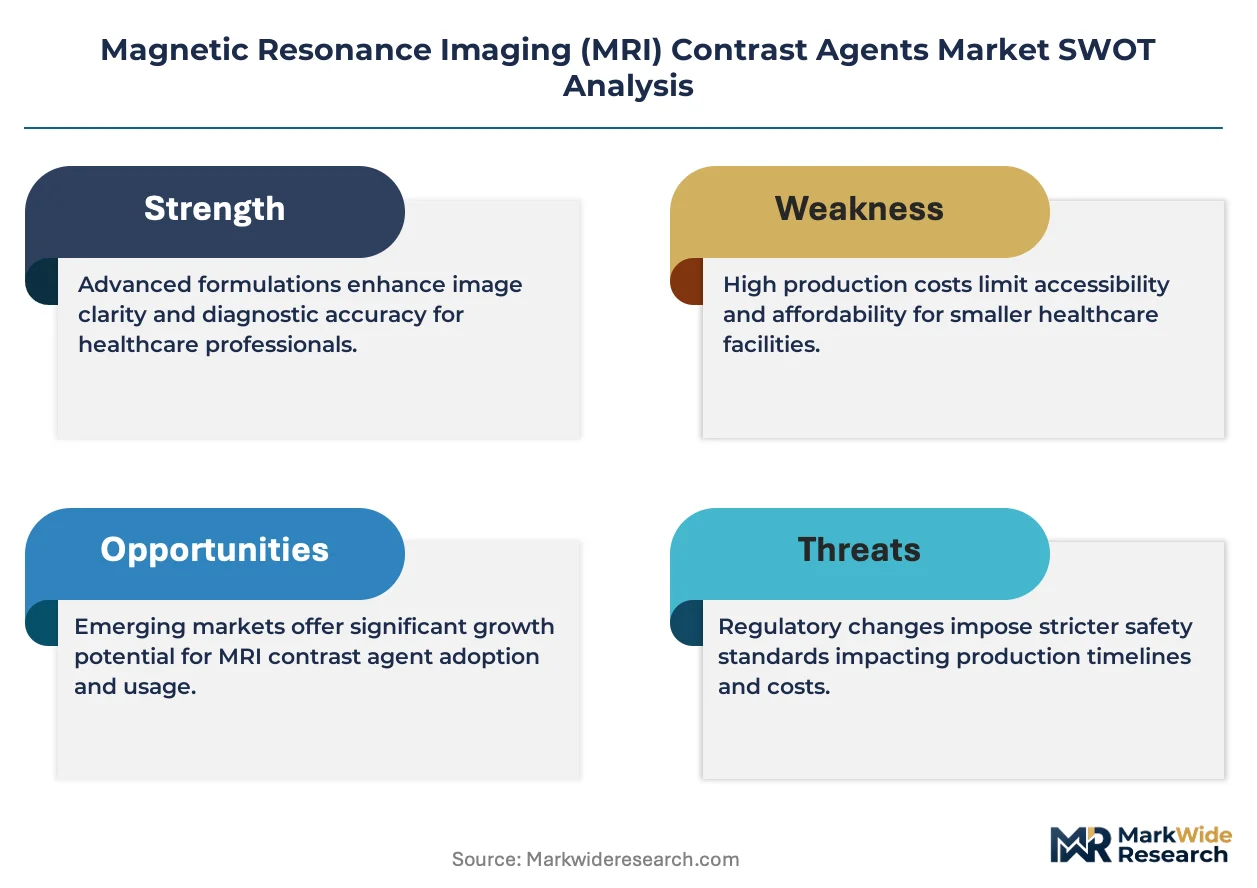
Iron oxide nanoparticle substitutes threaten gadolinium-based volume in liver and lymph node imaging, forcing incumbents to defend procedural indications through formulation innovation and regulatory compliance differentiation.
For Market Incumbents: Consolidate macrocyclic manufacturing scale through backward integration into rare earth oxide sourcing, securing supply continuity against Chinese export policy shifts. Deepen hospital system partnerships by embedding high-relaxivity agents into standardized oncology protocols, creating procedural stickiness that substitutes cannot easily displace.
For New Entrants and Emerging Players: Differentiate on ambulatory channel packaging innovations—single-dose prefilled syringes with extended stability profiles—to capture diagnostic imaging center procurement tenders. Target the United States outpatient facility segment where group purchasing organization consolidation has created vendor churn opportunities and incumbent service gaps.
For Investors and Strategic Acquirers: FDA macrocyclic safety guidance completion reshapes the acquisition landscape by clarifying which formulation portfolios carry long-term regulatory viability. Five-to-ten-year viability favors manufacturers with validated macrocyclic pipelines and established GMP synthesis infrastructure. The signal to watch is EMA PRAC linear agent restriction expansion into additional anatomical indications, which would accelerate premium tier demand and compress legacy asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Macrocyclic Portfolio Transition | EMA PRAC restrictions on linear agents redirect hospital procurement toward compliant formulations. |
| High-Relaxivity Agent Development | 3T and 7T MRI installations at academic medical centers demand enhanced signal efficiency. |
| Ambulatory Channel Packaging Innovation | Diagnostic imaging centers favor single-dose formats that minimize inventory complexity. |
| Backward Integration into Rare Earth Sourcing | Chinese supply concentration creates geopolitical exposure for chelate manufacturers. |
| Artificial Intelligence Protocol Integration | Machine learning dosing algorithms enable personalized administration at outpatient facilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiology department heads, hospital procurement managers, GPO contracts specialists, and chelate manufacturing plant directors. Secondary validation drew from FDA pharmacovigilance databases, EMA PRAC assessment reports, hospital formulary listings, and ISO 10993 biocompatibility filings. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, administration route, and application segments.
Across the analysis window, the forecasting framework modeled procedural volume trajectories by chelate class, relaxivity tier, and regional regulatory cluster. CAGRs were derived from weighted average growth rates across segment-level demand drivers, incorporating high-field MRI installation pipelines, oncology protocol expansion rates, and ambulatory imaging center buildouts as industry-specific inputs.
Material uncertainties—regulatory reclassification of macrocyclic agents, rare earth export policy shifts, and iron oxide substitution acceleration—sit outside the modeled envelope. Forecasts reflect documented assumptions about EMA PRAC restriction scope and FDA retention guidance finalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Europe Nuclear Imaging Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Global Cardiac Imaging Software Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Brazil Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Europe Portable X-Ray Devices Market