
 Mexico Hemp CBD Market | 2026-2036
Mexico Hemp CBD Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Hemp CBD Market Analysis
Modular dosing formats are hardening as the dominant product configuration, with single-serve sachets and metered tinctures replacing bulk oil bottles in pharmacy channels. HempMeds Mexico leverages its import licensing infrastructure to sustain first-mover positioning in regulated medical distribution. Joy Organics differentiates through USDA-certified organic sourcing that commands premium shelf placement in Mexico City wellness boutiques. Aurora Cannabis Inc. anchors its presence via pharmaceutical partnerships targeting therapeutic formulation standards.
Hemp CBD comprises cannabidiol extracted from Cannabis sativa L. plants containing less than 1% THC by dry weight, typically processed through CO2 or ethanol extraction into oils, isolates, or distillates for therapeutic and wellness applications. The formulation dimension shows full spectrum oils commanding current volume through established pharmacy relationships, while isolate segments attract pharmaceutical compounding demand driven by precise dosing requirements. Online distribution channels are expanding fastest as direct-to-consumer platforms bypass traditional retail markup structures, though pharmacy channels retain margin density through prescription-linked reimbursement pathways.
COFEPRIS maintains primary authority over cannabinoid product registration, with import permits required for all hemp-derived inputs under the General Health Law framework. The Secretariat of Agriculture and Rural Development (SADER) oversees cultivation licensing for domestic hemp production, creating dual-track compliance for imported versus locally sourced supply chains. Stakeholders must monitor evolving THC threshold definitions and pharmaceutical versus wellness classification boundaries that determine permissible health claims and distribution channel access.
Market Dynamics
COFEPRIS import permit streamlining is compressing product registration timelines from 18 months to under 8 months, triggering a supply-side reconfiguration as international suppliers accelerate Mexico market entry.
Growth Catalysts
- General Health Law Framework:COFEPRIS regulatory clarity on non-psychoactive cannabinoid thresholds is eliminating import ambiguity for pharmaceutical-grade formulations.
- Chronic Pain Management Protocols:Mexico City hospital networks are integrating CBD isolates into multimodal pain treatment regimens, creating institutional procurement pull.
- Wellness Center Density:Guadalajara and Monterrey boutique wellness chains are expanding CBD SKU counts to capture preventive health spending.
Market Restraints
- Import Dependency:Domestic hemp cultivation under SADER licensing remains below 15% of national CBD input requirements, concentrating supply risk with US and Canadian extractors.
- THC Threshold Volatility:COFEPRIS technical definitions for "non-detectable" THC vary by laboratory, creating batch rejection risk at customs.
- Pharmaceutical Synthesis Substitution:Synthetic cannabinoid analogs from Indian and Chinese manufacturers are capturing price-sensitive compounding pharmacy demand.
Strategic Opportunities
- Jalisco Agricultural Belt:SADER cultivation permits in the Guadalajara-Tepatitlán corridor offer 40% lower land costs versus imported biomass landed in Mexico City.
- Veterinary Therapeutics:Pet pain management and anxiety applications remain unserved by registered products, creating first-mover white space.
- Direct-to-Platform Distribution:Telehealth-integrated CBD subscription models bypass pharmacy markup structures and capture recurring revenue.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Third-party testing laboratories face 6-month recruitment cycles for HPLC-MS technicians capable of COFEPRIS-compliant cannabinoid profiling.
- Batch-Specific Registration Burden:Each imported isolate lot requires separate COFEPRIS sanitary registration, extending working capital cycles by 90-120 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Hemp CBD Market |
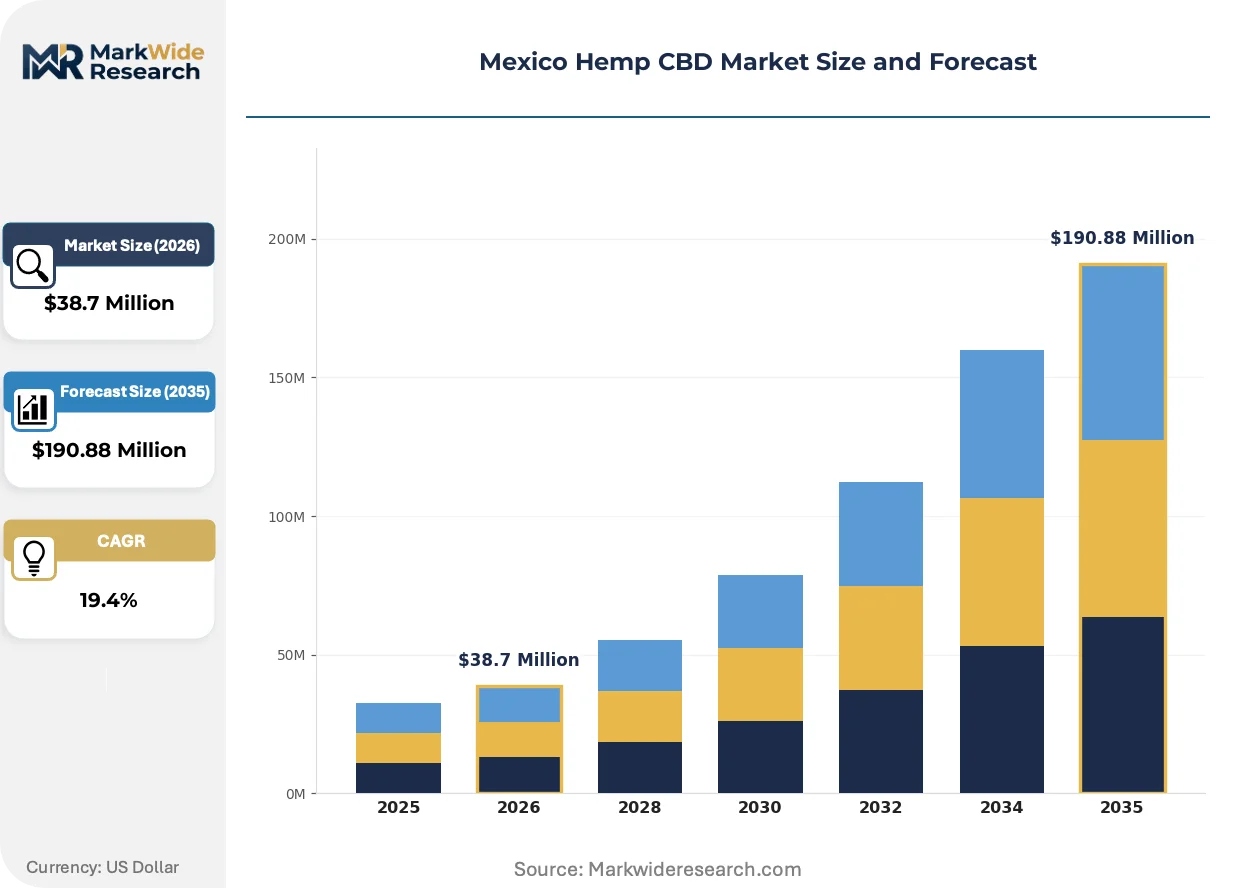
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $190.88 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Edibles, Tinctures, Topicals Distribution Channel: Online, Retail, Pharmacies, Dispensaries End User: Consumers, Wellness Centers, Healthcare Providers, Retailers Formulation: Full Spectrum, Broad Spectrum, Isolate, Others |
| Companies Covered | Elixinol, HempMeds Mexico, Canopy Growth Corporation, Joy Organics, CBD Life SA DE CV, Aurora Cannabis Inc., CV Sciences, Inc., Hempacco Co, Inc., ENDOCA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Hemp CBD Market Emerging Trajectories
Modular dosing formats and pharmaceutical-grade certification standards are displacing bulk commodity positioning, compressing margin structures for undifferentiated suppliers while rewarding precision manufacturing capabilities.
Nanoemulsion technology is expanding into Mexico's CBD beverage and functional food segments, enabling water-soluble cannabinoid integration at sub-micron particle sizes. Guadalajara-based contract manufacturers are adopting toll-processing agreements with US technology licensors. This convergence is compressing onset time claims from 45 minutes to under 15 minutes, forcing reformulation across the competitive set.
COFEPRIS is tightening pharmaceutical versus wellness classification boundaries through updated health claim enforcement guidelines. Products crossing into therapeutic positioning now require clinical evidence dossiers. Pharmacy channels are responding by segregating SKU assortments into prescription-linked and general wellness tiers, with reimbursement access determining shelf placement priority.
Clinician education initiatives by hospital pharmacy committees are accelerating CBD protocol adoption in chronic pain and oncology supportive care. Medical society endorsement programs are replacing direct-to-consumer marketing as the primary demand generation mechanism. Mexico City teaching hospitals are emerging as the critical reference accounts for national formulary inclusion decisions.
Mexico Hemp CBD Market Segmentation
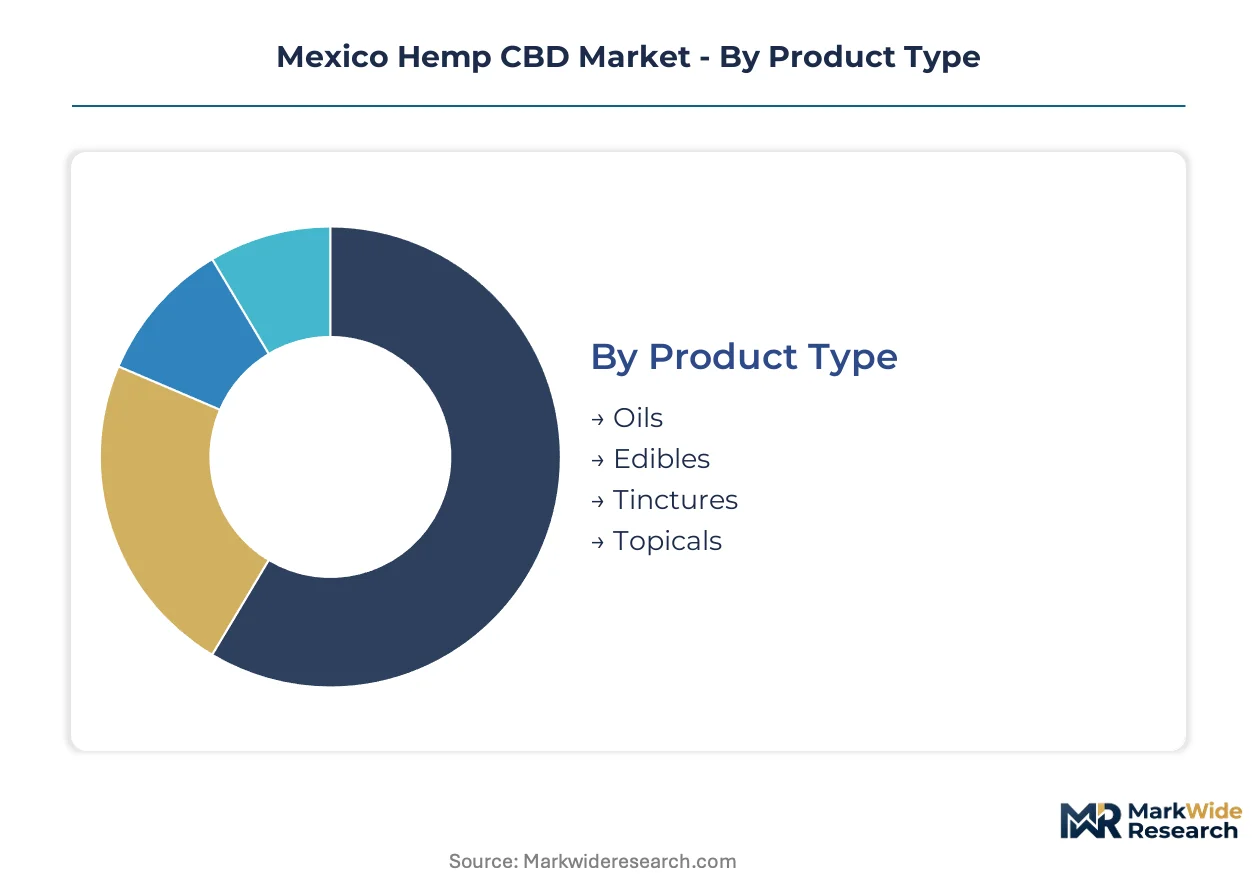
Segmentation in Mexico's hemp CBD market reveals how COFEPRIS regulatory tiers and distribution channel restrictions partition commercial opportunity. Product configuration and formulation choices directly determine permissible health claims, reimbursement access, and import permit complexity.
Product Type:
Supply concentration in pharmaceutical-grade manufacturing favors precision-dosed formats over bulk commodity presentations.
- Oils:CO2-extracted full spectrum and broad spectrum suspensions in MCT or hemp seed carrier bases dominate pharmacy procurement through established formulary relationships. Mexico City hospital networks specify oils for chronic pain protocols requiring titratable dosing and documented batch consistency.
- Tinctures:Alcohol or glycerin-based sublingual drops with metered droppers enable exact milligram control for clinician-supervised regimens. Guadalajara wellness boutiques prioritize tinctures for preventive health consumers seeking rapid onset without inhalation.
- Edibles:Gummies and functional foods face stricter COFEPRIS novel food classification, extending registration timelines.
- Topicals:Transdermal creams and balms occupy wellness channel shelf space with cosmetic positioning to bypass pharmaceutical registration.
Today's leader: Oils. Tomorrow's challenger: Tinctures.
Distribution Channel:
Channel access stratifies by regulatory classification, with reimbursement-linked pathways commanding margin density.
- Pharmacies:Hospital and retail pharmacy networks with COFEPRIS sanitary registration enable prescription-linked distribution and partial reimbursement through Seguro Popular and private insurer formularies.
- Online:Direct-to-consumer platforms bypass traditional retail markup structures and capture recurring subscription revenue, though cross-state shipping faces varying state-level enforcement.
- Retail:Specialty wellness stores and natural product retailers in Monterrey and Tijuana stock general wellness-tier SKUs without therapeutic claims.
- Dispensaries:Medical cannabis dispensaries under separate COFEPRIS medical marijuana permits represent a parallel channel with limited CBD-specific SKU focus.
Pharmacies anchor current revenue. Online channels are climbing the fastest.
End User:
Customer type determines pricing tolerance, with institutional procurement emphasizing total cost of protocol over unit price.
- Healthcare Providers:Hospital pharmacy committees and pain management specialists drive formulary inclusion decisions through evidence-based protocol development.
- Wellness Centers:Guadalajara and Mexico City boutique chains expand CBD SKU counts to capture preventive health spending from affluent urban demographics.
- Consumers:Direct purchasers span chronic condition self-managers to wellness-oriented prevention seekers with wide price sensitivity dispersion.
- Retailers:Pharmacy chains and independent wellness stores act as gatekeepers with shelf placement priority determined by margin structure and turnover velocity.
Healthcare providers set clinical standards. Wellness centers are gaining share fastest.
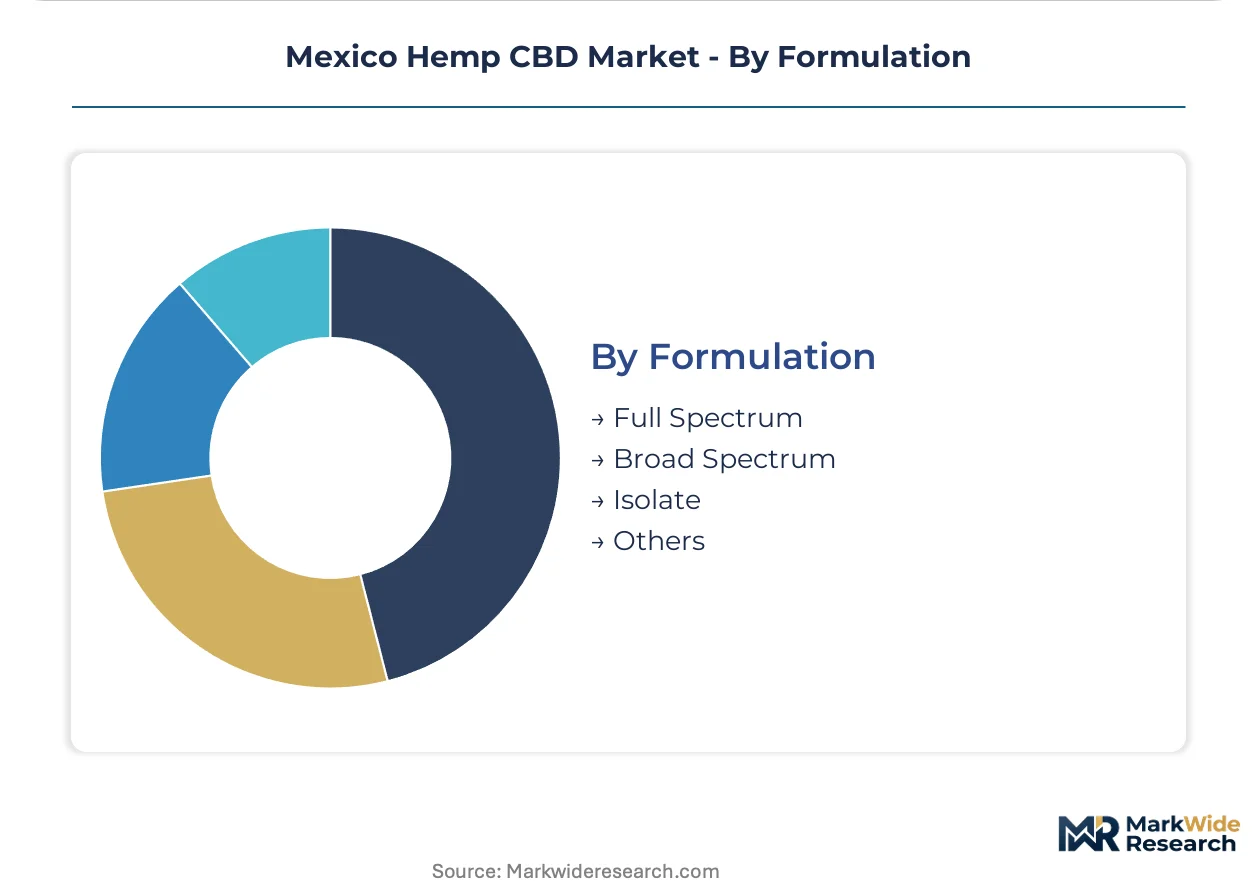
Formulation:
Technical specification tiers separate pharmaceutical compounding inputs from wellness-grade finished goods.
- Isolate:Crystalline CBD at 99%+ purity enables precise milligram dosing for hospital pharmacy compounding and eliminates THC batch rejection risk at customs. Mexico City oncology supportive care protocols specify isolate for drug interaction predictability.
- Full Spectrum:Whole-plant extracts retaining minor cannabinoids and terpenes leverage entourage effect positioning in wellness channels, though THC content creates import variability.
- Broad Spectrum:THC-free whole-plant formulations target consumers seeking entourage benefits without psychoactive compound exposure.
- Others:Nanoemulsion and liposomal delivery technologies enable water-soluble integration for beverage and functional food applications.
Isolate commands institutional procurement. Full spectrum leads consumer volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hemp CBD commerce in Mexico traces its regulatory foundation to 2017 COFEPRIS circulars that first distinguished non-psychoactive cannabinoids from controlled substances, enabling the import-dependent supply chains that now serve Mexico City hospital networks and Guadalajara wellness corridors.
Mexico City Metropolitan Area
Hospital pharmacy committees at Instituto Nacional de Cancerología and Hospital General de México drive institutional CBD procurement for chronic pain and oncology supportive care protocols. COFEPRIS maintains its central headquarters here, compressing registration timelines for sponsors with established regulatory relationships. Polanco and Condesa wellness boutiques cluster around high-margin tincture and isolate formulations targeting affluent preventive health consumers.
Jalisco
The Guadalajara-Tepatitlán agricultural corridor hosts SADER-licensed hemp cultivation pilots offering 40% lower land costs than imported biomass landed in Mexico City. Joy Organics anchors distribution through local wellness chain partnerships. Universidad de Guadalajara pharmaceutical research programs supply analytical chemistry talent for third-party testing laboratories serving COFEPRIS compliance requirements.
Nuevo León
Monterrey's industrial base supports contract manufacturing for nanoemulsion toll-processing agreements with US technology licensors. Hospital networks including Hospital Universitario and Hospital Zambrano Hellion integrate CBD isolates into multimodal pain management protocols. The state's proximity to Texas border logistics clusters reduces customs clearance variability for US-sourced extracts.
Northern Border States
Baja California, Chihuahua, and Tijuana corridors leverage maquiladora infrastructure for cross-border CBD product assembly and packaging operations. SADER cultivation permits remain sparse, preserving import dependency on California and Colorado extractors. Retail channels here face competitive pressure from US direct-to-consumer platforms with established cross-border fulfillment.
Bajío Region
Querétaro and Guanajuato pharmaceutical manufacturing clusters attract CBD isolate suppliers targeting compounding pharmacy demand. The region's medical device and pharma supplier ecosystem provides GMP-adjacent infrastructure for pharmaceutical-grade formulation. SADER has granted limited cultivation permits for research-scale hemp production near León.
Mexico Hemp CBD Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and distribution channel access, with USDA-organic and pharmaceutical-grade GMP certifications commanding 35-50% price premiums in Mexico City wellness boutiques and hospital pharmacies. The vendor base compresses into three tiers: import-license holders with COFEPRIS-established pathways, organic-certified specialists, and unbranded bulk suppliers serving price-sensitive compounding demand. Strategic moves concentrate on backward integration into SADER cultivation permits and telehealth platform partnerships for direct-to-consumer subscription capture.
Within the import-license holder tier, HempMeds Mexico and Aurora Cannabis Inc. occupy positions shaped by early regulatory engagement and pharmaceutical partnership structures. Joy Organics exemplifies the organic-certified specialist archetype. CBD Life SA DE CV represents domestic-structured entities navigating dual-track compliance for imported versus locally sourced supply chains.
| Leading Market Players |
|---|
| Elixinol |
| HempMeds Mexico |
| Canopy Growth Corporation |
| Joy Organics |
| CBD Life SA DE CV |
| Aurora Cannabis Inc. |
| CV Sciences, Inc. |
| Hempacco Co, Inc. |
| ENDOCA |
| Others |
Supply Flow & Price Mechanics
Hospital pharmacy committees in Mexico City concentrate procurement authority for pharmaceutical-grade CBD isolates, locking in contract-based long-term offtake structures that reward batch consistency over spot-market flexibility. This buyer concentration compresses margin capture for undifferentiated suppliers while amplifying pricing power for COFEPRIS-registered import-license holders with established formulary relationships.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, certified-organic, and bulk commodity levels separates GMP-certified isolates commanding premium placement in hospital formularies from USDA-organic wellness oils and unbranded inputs for compounding pharmacies. Price differentiation rests on certification tier and import-permit infrastructure rather than intrinsic cannabinoid content. Cost compression in the bulk commodity tier is intensifying because Indian and Chinese synthetic cannabinoid analogs capture price-sensitive compounding demand. Compounding pharmacies exhibit highest price sensitivity; hospital networks prioritize protocol reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Mexico City and Guadalajara operate hub-and-spoke patterns radiating from COFEPRIS-registered import terminals. Geographic supply concentration draws from US and Canadian extractors, with limited SADER-licensed domestic cultivation in Jalisco and Guanajuato. Raw material dependencies rest on CO2 extraction equipment, pharmaceutical-grade carrier oils, and HPLC-MS testing consumables. Single-source vulnerability concentrates in US border logistics clusters subject to customs clearance variability. Distribution runs through pharmacy networks with sanitary registration, bypassing traditional wholesale structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where demand is consolidating around pharmaceutical-grade specifications and COFEPRIS registration infrastructure. The shift toward clinician-supervised chronic pain protocols favors suppliers with institutional formulary access over wellness-channel generalists.
For Market Incumbents: Anchor formulary position through backward integration into SADER cultivation permits in the Guadalajara-Tepatitlán corridor, securing 40% cost advantages over imported biomass. Deepen clinical evidence dossiers to defend against COFEPRIS health claim enforcement tightening. Prioritize telehealth platform partnerships for recurring subscription capture before direct-to-consumer channels mature. For New Entrants and Emerging Players: Telehealth-integrated CBD subscription models offer the most penetrable entry vector, bypassing pharmacy markup structures and capturing recurring revenue without COFEPRIS sanitary registration burdens. Target veterinary therapeutics white space in pet pain management and anxiety applications, where registered products remain unserved. Pursue toll-processing agreements with Guadalajara contract manufacturers for nanoemulsion technology licensing. For Investors and Strategic Acquirers: Pharmaceutical distributors with established hospital network relationships are the most active acquirer in this space, seeking COFEPRIS import-license infrastructure to bolt onto existing medical supply chains. Acquisition target archetypes cluster around SADER cultivation permit holders with analytical chemistry capabilities and telehealth platform operators with prescription-linked fulfillment. Watch for COFEPRIS THC threshold definition harmonization as inflection indicator for import permit timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| SADER Cultivation Permit Acquisition | Backward integration into Jalisco agricultural belt secures 40% input cost advantage versus imported biomass. |
| Telehealth Platform Partnership | Direct-to-consumer subscription models bypass pharmacy markup and capture recurring revenue streams. |
| Pharmaceutical-Grade GMP Certification | COFEPRIS-registered manufacturing infrastructure enables hospital formulary inclusion and partial reimbursement access. |
| Nanoemulsion Technology Licensing | Guadalajara toll-processing agreements compress CBD onset claims from 45 minutes to under 15 minutes. |
| Clinical Evidence Dossier Development | Hospital pharmacy committee endorsement programs replace direct-to-consumer marketing as primary demand generation. |
Methodological Framework
Direct dialogue with COFEPRIS regulatory affairs specialists, hospital pharmacy committee members, SADER cultivation permit holders, and third-party testing laboratory directors grounded qualitative findings in operational reality. Secondary validation drew from COFEPRIS sanitary registration databases, SADER licensing records, General Health Law framework circulars, and import permit disclosure filings. Bottom-up demand modeling from hospital procurement data and wellness channel SKU counts triangulated against top-down market sizing from trade flow analysis and customs records.
Bottom-up volume projections aggregated across product type, formulation specification, distribution channel, and end-user segments, with top-down macro constraints from regulatory capacity and import permit issuance rates. CAGRs derived from segment-level growth rate differential analysis across the projection horizon, with cross-segment elasticity adjustments for channel shift dynamics. Forecast inputs incorporated COFEPRIS registration timeline compression scenarios and SADER cultivation permit expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to THC threshold definition volatility, synthetic cannabinoid substitution rates, and telehealth regulatory classification shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabis Cultivation Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
Morocco Medical Cannabis Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
Cannabis Vaporizers Market
Cannabis/Marijuana
Cannabinoids Market
Cannabis/Marijuana
Europe CBD Oil Market
Cannabis/Marijuana
Germany and Netherlands Medical Marijuana Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
CBD Consumer Health Market