
 Brain PET-MRI Systems Market | 2026-2036
Brain PET-MRI Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Brain PET-MRI Systems Market Intelligence
Buyer concentration among academic medical centers and large hospital networks is hardening across major markets. Siemens Healthineers AG leverages its established MRI installed base to cross-sell integrated PET-MRI configurations. GE Healthcare anchors its position through deep R&D partnerships with National Institutes of Health-funded neuroimaging consortia. Philips sustains competitive pressure with AI-assisted reconstruction workflows that reduce scan times.
Brain PET-MRI systems combine positron emission tomography detectors with magnetic resonance imaging magnets in a single gantry, typically operating at 3 Tesla field strength with lutetium-based scintillator crystals for gamma detection; the integrated platform enables simultaneous acquisition of metabolic and anatomical brain data for neuro-oncology and dementia research. Integrated systems command the deepest installed base due to their unified workflow, while AI-assisted imaging represents the fastest-expanding technology segment as vendors embed deep learning for motion correction and tracer uptake quantification. Hospitals absorb the majority of current shipments, though research institutions are widening procurement as grant funding for multi-site neuroimaging studies expands.
The FDA regulates these devices under 21 CFR Part 892 diagnostic radiology classifications, while the EU Medical Device Regulation requires notified body certification for Class IIa and above imaging systems; both frameworks elevate barriers for new entrants without established quality management systems. Japan's PMDA maintains distinct pharmaceutical and medical device agency review tracks that lengthen approval timelines for novel radiotracer-hardware combinations. Stakeholders must monitor evolving reimbursement codes for simultaneous PET-MRI procedures across Medicare, national health systems, and private payers.
Market Dynamics
Academic medical centers in the United States, Germany, and Japan are hardening procurement concentration, forcing vendors to bundle AI-assisted reconstruction and extended service contracts into integrated PET-MRI configurations.
Growth Catalysts
- EU MDR pre-certification routes:Streamlined notified body pathways for Class IIa imaging systems accelerate market access for hybrid platform vendors in Western Europe.
- Neurodegenerative disease research funding:Multi-site NIH-funded neuroimaging consortia in the United States expand installed base demand at university hospitals.
- Lutetium-based scintillator crystals:Improved gamma detection efficiency at 3 Tesla field strength enables simultaneous metabolic and anatomical acquisition workflows.
Market Restraints
- Helium supply volatility:MRI magnet cooling dependency on constrained global helium reserves elevates operational cost uncertainty for 3 Tesla systems.
- PMDA dual-track review:Japan's distinct pharmaceutical and medical device agency pathways lengthen approval timelines for novel radiotracer-hardware combinations.
- Fixed-site infrastructure requirements:Shielded suite construction and magnetic field containment specifications limit installation flexibility at smaller clinical sites.
Strategic Opportunities
- Research institution procurement:Grant-funded multi-site neuroimaging studies in Germany widen demand beyond traditional hospital buyers.
- AI-assisted motion correction:Deep learning integration with PET-MRI reconstruction compresses scan times and expands patient throughput capacity.
- Medicare reimbursement code evolution:Emerging coverage determinations for simultaneous PET-MRI procedures reduce payer friction in the United States.
Industry Challenges
- Specialized technologist shortage:Dual-modality certification requirements for PET-MRI operation constrain workforce scaling at expanding sites.
- Legacy PACS integration complexity:DICOM connectivity standards vary across vendor platforms, complicating unified workflow deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain PET-MRI Systems Market |
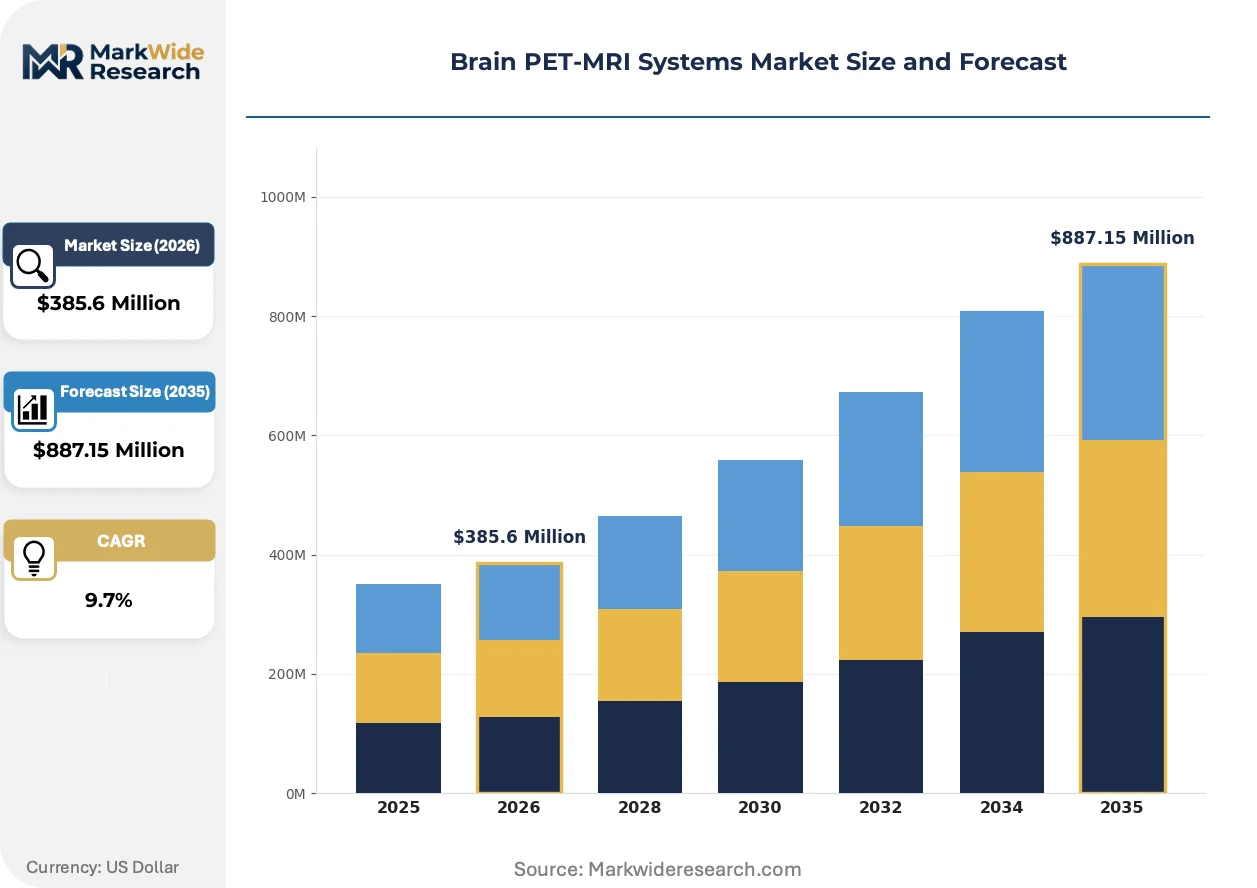
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $887.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Upgrades, Reagents End User: Hospitals, Research Institutions, Diagnostic Labs, Outpatient Facilities Technology: Time-of-Flight, Conventional, Hybrid Imaging, AI-assisted Imaging Application: Neurology Research, Oncology Imaging, Cognitive Disorders, Clinical Trials |
| Companies Covered | Bruker, MR Solutions, Siemens Healthineers AG, Aspect Imaging, Cubresa Inc., Koninklijke Philips N.V., Mediso Ltd., Canon Medical Systems, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain PET-MRI Systems Market Strategic Shifts & Innovations
Deep learning architectures are penetrating radiotracer quantification and motion artifact correction, compressing examination duration while preserving diagnostic fidelity in neuro-oncology workflows.
Silicon photomultiplier arrays are absorbing the role of traditional photomultiplier tubes in PET detector blocks, enabling slimmer gantry profiles and improved magnetic field compatibility. Academic medical centers in Japan are adopting this solid-state detection technology fastest, driven by METI-backed advanced medical equipment initiatives. The structural consequence is a compression in system footprint requirements, allowing retrofit installations at sites with constrained shielded suite dimensions.
MDR technical documentation requirements for Class IIa imaging systems are elevating quality management system burdens across European notified body jurisdictions. Manufacturers must demonstrate clinical evidence for intended purpose claims, extending certification timelines. Vendors are responding by consolidating EU regulatory affairs functions in Germany and Switzerland to streamline conformity assessment.
Hospital procurement committees are unbundling service contracts from capital equipment purchases, negotiating multi-vendor maintenance agreements and third-party software subscriptions separately. This disintermediation of traditional turnkey pricing is most visible in the United States, where IDN purchasing coalitions leverage volume commitments across imaging modalities. The shift pressures vendor margins on aftermarket revenue streams.
Brain PET-MRI Systems Market Segmentation
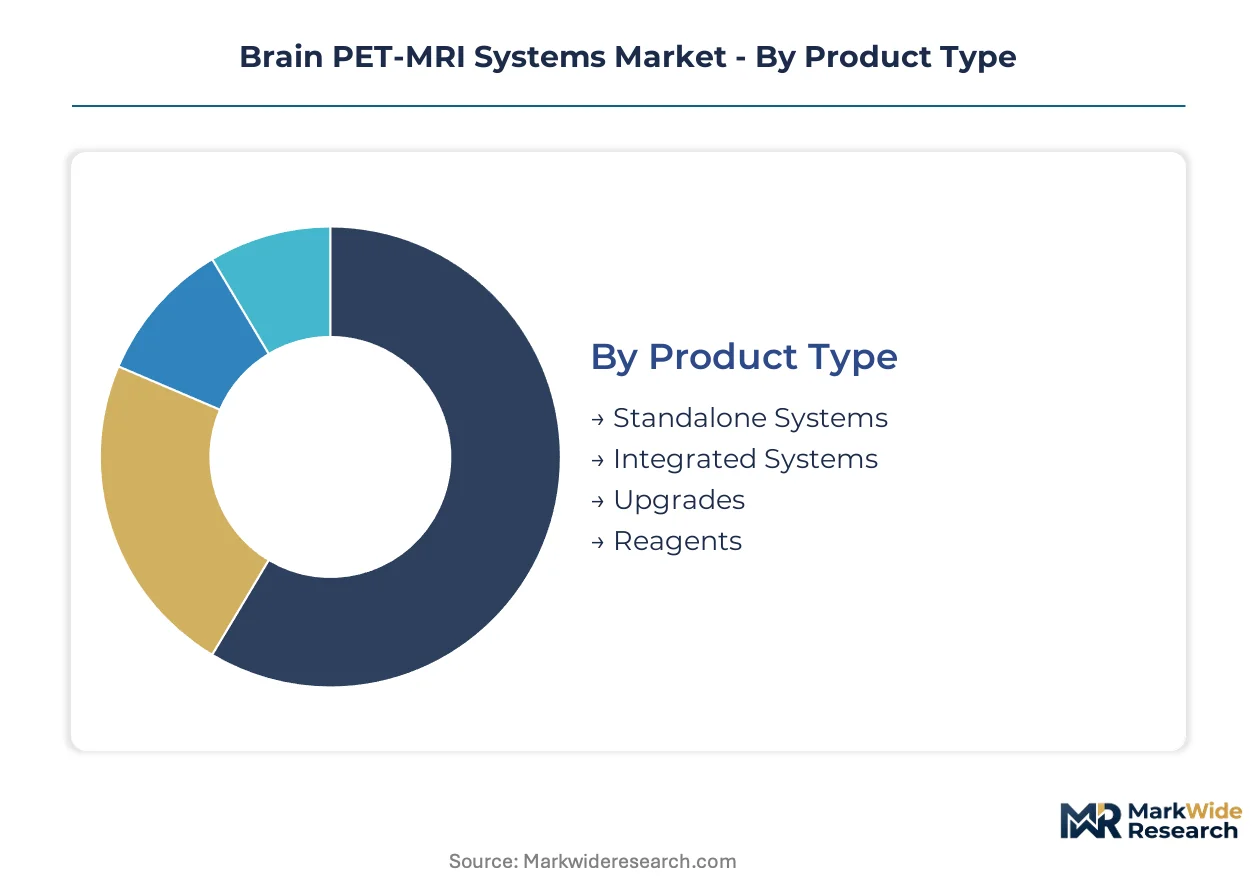
Segmentation in Brain PET-MRI Systems Market reveals distinct regulatory pathways and procurement patterns across product configurations, end-use environments, and technical architectures. Each segment carries unique certification burdens from FDA, EU MDR, and PMDA that shape vendor go-to-market strategies and buyer qualification timelines.
Product Type:
FDA 21 CFR Part 892 diagnostic radiology classifications apply differentially across product categories, with integrated systems facing the most stringent premarket notification requirements while upgrades navigate abbreviated 510(k) pathways.
- Integrated Systems:Unified gantry configurations combining 3 Tesla MRI magnets with lutetium-based PET detector arrays require simultaneous FDA clearance for both modalities. Academic medical centers in the United States absorb the majority of procurement volume as NIH-funded neuroimaging consortia expand installed base requirements.
- Standalone Systems:Separately housed PET and MRI units connected through software synchronization layers. Research institutions in Germany favor this architecture for flexibility in multi-site study protocols, though shielded suite construction costs limit deployment at smaller clinical sites.
- Upgrades:PET detector retrofits to existing MRI platforms. These configurations compress capital expenditure timelines for hospitals with established 3 Tesla installed bases.
- Reagents:Radiotracer consumables including fluorodeoxyglucose and novel tau-binding compounds. Japan's PMDA maintains distinct pharmaceutical review tracks that lengthen approval timelines for novel radiotracer-hardware combinations.
Integrated systems sit at the top of the volume ranking, with AI-assisted reconstruction modules climbing the fastest as vendors bundle deep learning workflows into new procurements.
End User:
Procurement authority concentrates differently across customer types, with hospitals leveraging IDN purchasing coalitions while research institutions navigate grant-funded acquisition cycles.
- Hospitals:Large hospital networks and academic medical centers anchor demand, particularly in the United States where Medicare reimbursement code evolution for simultaneous PET-MRI procedures reduces payer friction. IDN purchasing coalitions increasingly unbundle service contracts from capital equipment purchases.
- Research Institutions:Grant-funded multi-site neuroimaging studies in Germany and Japan widen demand beyond traditional hospital buyers. METI-backed advanced medical equipment initiatives in Japan accelerate solid-state detector adoption at university hospitals.
- Diagnostic Labs:Specialized imaging centers focus on high-throughput oncology workflows. These facilities prioritize AI-assisted motion correction to compress scan times and expand patient throughput capacity.
- Outpatient Facilities:Limited penetration due to fixed-site infrastructure requirements including shielded suite construction and magnetic field containment specifications.
Hospitals command the dominant share of current shipments, though research institutions are gaining share fastest as multi-site neuroimaging study funding expands across Germany and Japan.
Technology:
Technical architectures stratify by detection physics and computational integration, with silicon photomultiplier arrays displacing traditional photomultiplier tubes in premium configurations.
- AI-assisted Imaging:Deep learning architectures embedded for radiotracer quantification and motion artifact correction. This segment is expanding most quickly as vendors compete on reconstruction speed and diagnostic fidelity in neuro-oncology workflows.
- Time-of-Flight:Precision timing circuits measuring positron annihilation photon arrival differences. Improved signal-to-noise ratios enable reduced radiotracer dosing or shortened acquisition windows.
- Hybrid Imaging:Simultaneous PET-MRI acquisition with unified data streams. Academic medical centers in Japan adopt this configuration fastest, driven by solid-state detector compatibility with 3 Tesla field strengths.
- Conventional:Sequential PET and MRI acquisition without simultaneous data integration. Legacy installations persist where capital constraints limit full system replacement.
Conventional technology retains the largest installed base, with AI-assisted imaging recording the steepest expansion trajectory as procurement committees prioritize workflow efficiency.
Application:
Clinical use cases determine radiotracer selection, scan protocol duration, and reimbursement pathway complexity across buyer segments.
- Neurology Research:Longitudinal neurodegenerative disease studies requiring standardized acquisition protocols across multiple sites. NIH-funded consortia in the United States drive standardization requirements for amyloid and tau imaging biomarkers.
- Oncology Imaging:Brain tumor characterization and treatment response monitoring. These workflows demand rapid turnaround times that favor AI-assisted reconstruction for clinical decision support.
- Cognitive Disorders:Differential diagnosis of Alzheimer's disease and related dementias. Medicare coverage determinations in the United States increasingly recognize amyloid PET as a clinically necessary service.
- Clinical Trials:Multi-site pharmaceutical studies with centralized image analysis requirements. EU MDR technical documentation for Class IIa imaging systems elevates quality management system burdens for vendors supplying trial infrastructure.
Neurology research generates the highest procedure volume, with clinical trials applications scaling most rapidly as pharmaceutical sponsors expand central imaging vendor partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes exceed German shipments despite comparable academic medical center density, while Japanese adoption accelerates fastest among the three major markets due to METI-backed solid-state detector initiatives.
United States
NIH-funded neuroimaging consortia at university hospitals drive integrated system demand. FDA breakthrough device designation streamlines premarket notification for hybrid platforms. Major procurement clusters concentrate in Boston-Cambridge and Baltimore-Washington corridors where multi-site dementia research networks anchor installed base expansion.
Germany
Research institutions favor standalone architectures for flexible multi-site study protocols. EU MDR pre-certification routes accelerate Class IIa imaging system approvals through notified bodies in Berlin and Munich. The Heidelberg-Mannheim medical technology corridor hosts dense vendor regulatory affairs consolidation to manage technical documentation burdens.
Japan
METI advanced medical equipment initiatives accelerate silicon photomultiplier adoption at university hospitals. PMDA dual-track review lengthens timelines for novel radiotracer-hardware combinations. Tokyo-Osaka academic medical centers lead solid-state detector procurement as magnetic field compatibility improvements enable slimmer gantry retrofits.
United Kingdom
NHS England specialized commissioning frameworks concentrate PET-MRI deployment at designated neurosciences centers. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements extends certification timelines for new market entrants. London-Oxford-Cambridge golden triangle institutions dominate grant-funded neurology research procurement.
Switzerland
Swissmedic streamlined conformity assessment attracts vendor regulatory headquarters relocation from broader European jurisdictions. Federal technology transfer programs at ETH Zurich and University Hospital Basel accelerate research institution procurement cycles. The Basel-Zurich corridor concentrates vendor clinical evidence generation activities for EU MDR intended purpose claims.
Brain PET-MRI Systems Market Key Industry Players
German and Dutch producers anchor one tier; Japanese and British specialists hold differentiated positions in solid-state detection and compact system architectures. The vendor structure concentrates around three strategic archetypes: diversified imaging conglomerates with cross-modal installed bases, dedicated preclinical-to-clinical hybrid specialists, and component-technology pure-plays in detector materials. Dominant competitive moves include AI-assisted reconstruction bundling into capital equipment contracts and unbundled multi-vendor service agreement negotiation.
Among diversified imaging conglomerates, Siemens Healthineers AG and Koninklijke Philips N.V. occupy positions defined by established MRI installed base leverage and AI workflow integration respectively. GE Healthcare anchors the third position within this tier through NIH consortium partnerships. Dedicated hybrid specialists including MR Solutions and Cubresa Inc. exemplify focused preclinical-to-clinical platform development, while Bruker represents the component-technology archetype through magnetic resonance core expertise applied to integrated detection configurations.
| Leading Market Players |
|---|
| Bruker |
| MR Solutions |
| Siemens Healthineers AG |
| Aspect Imaging |
| Cubresa Inc. |
| Koninklijke Philips N.V. |
| Mediso Ltd. |
| Canon Medical Systems |
| GE Healthcare |
| Others |
Cost & Logistics Intelligence
Academic medical center procurement concentration in the United States, Germany, and Japan anchors contract-based long-term equipment offtake as the dominant pricing model. IDN purchasing coalitions leverage volume commitments across imaging modalities to compress vendor margins on bundled service contracts.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for integrated PET-MRI configurations as Siemens Healthineers and Canon Medical Systems expand manufacturing footprints. Three-tier pricing structure across premium, standard, and economy levels stratifies by AI-assisted reconstruction capability and field strength specification. Cost compression in the standard tier is intensifying because research institutions negotiate unbundled multi-vendor maintenance agreements. Diagnostic labs demonstrate the highest price sensitivity due to throughput-dependent ROI calculations, while academic medical centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Specialized technologist shortages in Germany and helium supply constraints in the United States complicate workforce scaling for 3 Tesla system manufacturing. Supply concentration centers on Japan for lutetium-based scintillator crystals, Germany for precision magnet winding, and the United States for AI reconstruction software. Component sourcing draws from constrained global helium reserves for cryogenic cooling, rare earth elements for magnet cores, and silicon photomultiplier arrays for solid-state detection. Single-source vulnerability in helium supply creates operational risk for MRI magnet production. Distribution runs through direct vendor-hospital contracting with regional service depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where NIH-funded neuroimaging consortia and METI-backed initiatives are shifting procurement toward AI-assisted reconstruction and solid-state detector specifications.
For Market Incumbents: Cement cross-selling leverage through MRI installed base lock-in while accelerating silicon photomultiplier integration to neutralize component-technology pure-plays. Deepen backward integration into lutetium-based scintillator supply to offset raw material dependency. Fortify regulatory affairs consolidation in Germany and Switzerland against EU MDR technical documentation burdens. For New Entrants and Emerging Players: AI-assisted motion correction algorithms offer a technology-first wedge into diagnostic lab segments where throughput optimization commands premium pricing. Target outpatient facility retrofits constrained by shielded suite dimensions as the most penetrable geography. Pursue grant-funded research institution procurement cycles in Germany as the primary go-to-market angle. For Investors and Strategic Acquirers: Diversified imaging conglomerates with established MRI installed bases are the most active acquirer in this space, seeking preclinical-to-clinical hybrid specialists to fill portfolio gaps. Long-term viability hinges on reimbursement code evolution for simultaneous PET-MRI procedures across Medicare and national health systems. Watch for FDA breakthrough device designation announcements as the inflection indicator for platform technology validation.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Reconstruction Bundling | Deep learning integration compresses scan times for NIH-funded neuroimaging consortia. |
| Solid-State Detector Adoption | Silicon photomultiplier arrays enable slimmer gantry retrofits at METI-backed Japanese sites. |
| EU MDR Regulatory Consolidation | Notified body certification streamlines Class IIa imaging system market access. |
| Service Contract Unbundling | IDN purchasing coalitions negotiate multi-vendor maintenance separately from capital equipment. |
| Helium Supply Hedging | Closed-loop cryogenic systems reduce operational cost uncertainty for 3 Tesla magnets. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with hospital purchasing committee members, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs leads at imaging conglomerates inform demand-side dynamics. Secondary sources include FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement determinations, and hospital procurement records. Bottom-up installed base modeling triangulates against top-down market sizing.
Granularity-level modeling disaggregates volume and value outputs by product type, end user, technology architecture, and application across the analysis window. Segmentation dimensions include integrated versus standalone system configuration, academic medical center versus research institution procurement authority, and AI-assisted versus conventional reconstruction methodology. CAGRs derive from logistic adoption curve fitting against NIH funding trajectories and METI equipment subsidy schedules. Forecast inputs incorporate helium supply volatility indices and EU MDR certification timeline distributions.
The model holds under stable NIH neuroimaging consortium funding and EU MDR notified body capacity; deviation in Medicare reimbursement code denial rates or PMDA dual-track review extensions would shift trajectory. Forecasts reflect documented assumptions regarding grant funding continuity and regulatory pathway efficiency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Closed MRI Systems Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
Medical Image Exchange System Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
Global Spinal Imaging Treatment Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Mammography Market
Medical Imaging
Canada Mammography Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Carotid Ultrasound Imaging Market