
 Biopsy Guidance System Market | 2026-2036
Biopsy Guidance System Market Size, Share, and Industry Trends Forecast 2026-2036
Biopsy Guidance System Market Intelligence
North American manufacturing capacity for precision biopsy instruments is narrowing as domestic producers scale cleanroom assembly lines. Becton, Dickinson and Company leverages its vascular access heritage to anchor percutaneous biopsy portfolios. Hologic, Inc. competes through breast health specialization that extends into stereotactic guidance ecosystems. Boston Scientific Corporation differentiates via interventional oncology workflows that integrate its therapeutic devices with navigation platforms.
A biopsy guidance system comprises imaging-modality hardware, needle navigation software, and disposable consumables engineered to extract tissue specimens with spatial accuracy below two millimeters deviation. These systems serve the primary commercial purpose of enabling minimally invasive diagnosis while reducing repeat procedure rates and sampling error. Ultrasound guidance occupies the largest installed base due to real-time visualization and lower capital burden, whereas robotic assistance represents the fastest-expanding technology segment as hospitals seek to standardize operator-dependent variability. MRI guidance commands premium positioning in prostate and breast applications where soft-tissue contrast determines diagnostic yield.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements determine market access cadence for new biopsy guidance platforms. The EPA regulates disposal pathways for radioactive seed localization markers used in some breast biopsy protocols. Stakeholders must monitor reimbursement coding revisions for image-guided needle placement procedures across Medicare and commercial payers.
Market Dynamics
Robotic navigation platforms are compressing operator-dependent variability in tissue sampling accuracy, forcing incumbent imaging hardware manufacturers to integrate software layers or cede procedural control to surgical robotics specialists.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance for predicate-device modifications accelerates platform upgrades and reduces time-to-market for enhanced needle navigation algorithms in US hospital systems.
- Oncology procedural volume expansion:Academic medical centers in the United States are retrofitting imaging suites with integrated guidance platforms to handle rising biopsy caseloads in lung and prostate screening programs.
- CE marking under EU MDR:Stricter technical documentation requirements for class IIa/IIb devices are filtering out marginal competitors and consolidating procurement toward full-stack platform vendors in European hospital networks.
Market Restraints
- Capital equipment intensity:MRI-compatible biopsy platforms require superconducting magnet shielding and specialized RF coils, constraining deployment to tertiary referral centers with dedicated interventional radiology budgets.
- Consumables supply concentration:Precision biopsy needles with echogenic coatings rely on German and Swiss specialty wire-drawing facilities, creating vulnerability to input cost volatility and capacity constraints.
- Reimbursement coding lag:CMS and commercial payers maintain separate fee schedules for image-guided versus freehand needle placement, compressing margins on integrated guidance workflows despite superior clinical outcomes.
Strategic Opportunities
- India diagnostic infrastructure buildout:CDSCO streamlined medical device registration and PLI scheme incentives for domestic manufacturing create entry points for mid-range ultrasound-guided platforms in tier-2 cities.
- AI-assisted real-time targeting:Convergence of deep learning segmentation with electromagnetic tracking enables automated lesion recognition, opening premium pricing tiers for software-augmented procedures.
- Ambulatory surgical center channel:Medicare site-of-service differentials are pulling low-complexity biopsies out of hospital outpatient departments, creating demand for compact, cart-based guidance systems with simplified workflows.
Industry Challenges
- Interventional radiologist training pipeline:Fellowship programs produce fewer operators capable of MRI-guided procedures than installed base expansion requires, creating regional access disparities.
- Legacy PACS integration complexity:Navigation software must interface with proprietary DICOM routers and institutional cybersecurity protocols, extending deployment timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopsy Guidance System Market |
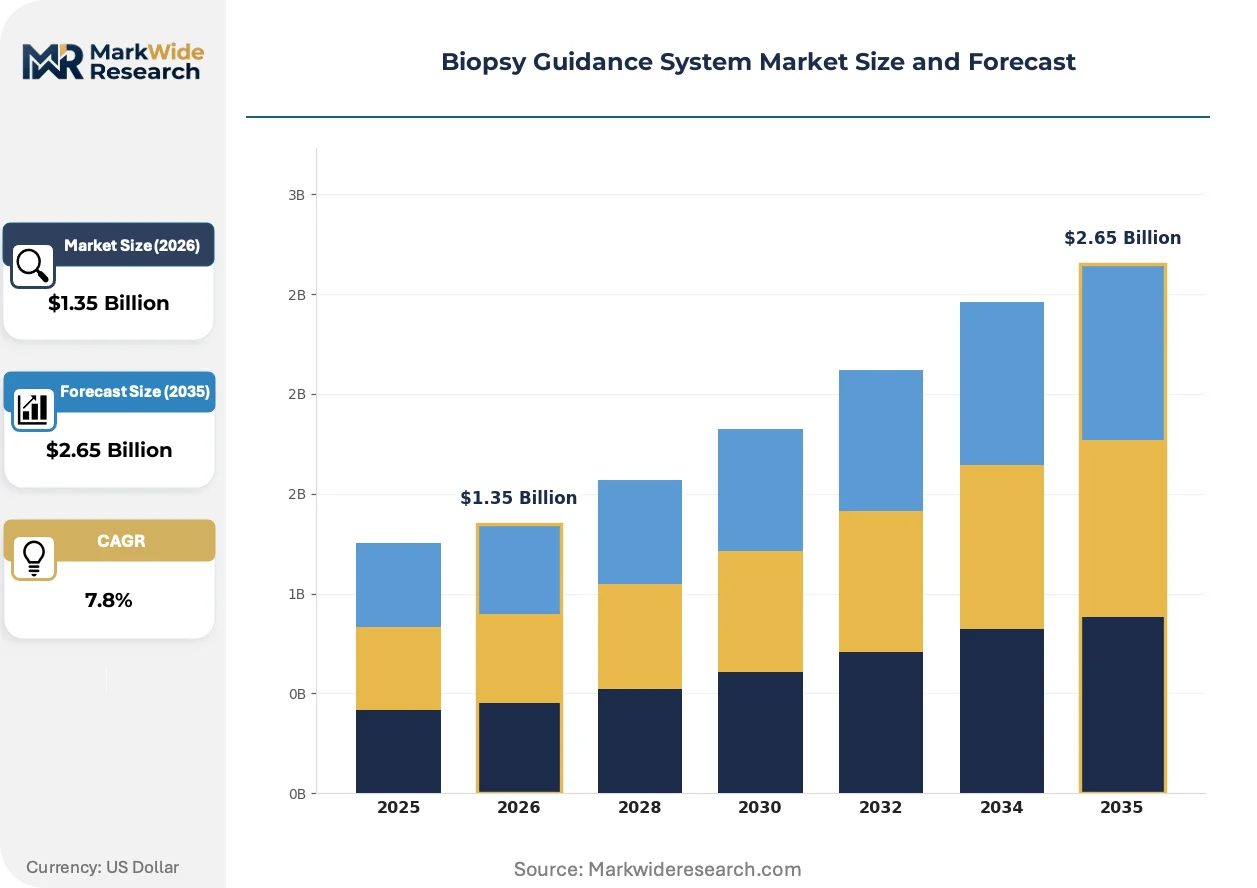
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Guidance, MRI Guidance, CT Guidance, X-ray Guidance End User: Hospitals, Diagnostic Clinics, Research Labs, Imaging Centers Technology: Optical Coherence Tomography, Radiofrequency Identification, 3D Imaging, Robotic Assistance Application: Oncology, Dermatology, Gastroenterology, Urology |
| Companies Covered | Becton, Dickinson and Company, Hologic, Inc., Devicor Medical Products, Inc., B. Braun Melsungen AG, Argon Medical Devices, Inc., Boston Scientific Corporation, INRAD Inc., Cook Medical, Planmed Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopsy Guidance System Market Strategic Shifts & Innovations
Electromagnetic tracking and optical localization are displacing mechanical needle guides across procedural categories, while regulatory data requirements for software-as-medical-device classifications are reshaping vendor R&D priorities.
Electromagnetic needle tracking is migrating from research-limited prototypes to standard-of-care deployment in academic centers. Community hospitals in the United States and Germany are adopting tabletop EM field generators for lung and renal biopsies. The technology is migrating from high-cost robotic platforms to affordable add-on modules, compressing price tiers and forcing pure-play navigation vendors toward software licensing models.
EU MDR technical documentation requirements for class IIa devices now mandate clinical evidence for needle navigation software updates. Manufacturers must submit post-market surveillance data for algorithm modifications that previously qualified as predicate-device equivalents. Breast biopsy platforms with AI-assisted targeting face extended notified body review timelines, advantaging vendors with established quality management systems over emerging competitors.
Hospital procurement committees are unbundling capital equipment from disposable contracts, reversing decade-long bundled-leasing arrangements. IDNs in the United States are negotiating separate needle supply agreements with third-party manufacturers, eroding captive consumables revenue for guidance system OEMs. This pattern is most visible in Midwestern health systems where GPO consolidation has strengthened buyer negotiating leverage against single-source platform vendors.
Biopsy Guidance System Market Segmentation
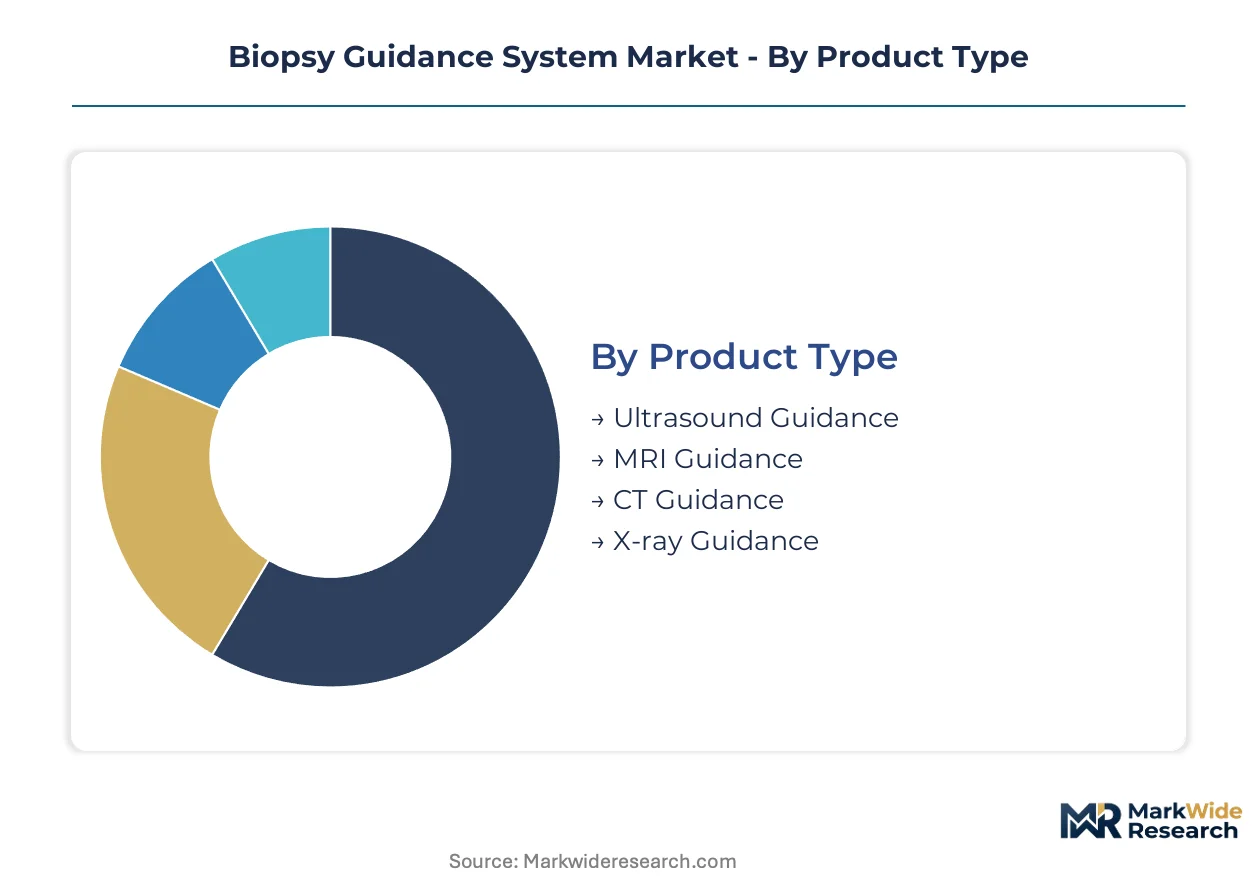
Segmentation in biopsy guidance systems reveals how capital intensity, procedural workflow, and reimbursement structures fragment purchasing authority across hospital departments. Equipment replacement cycles vary from five years for ultrasound platforms to twelve years for MRI-integrated suites.
Product Type:
Ultrasound platforms turn over fastest at community hospitals, while MRI-compatible systems cycle slowest due to magnet infrastructure requirements.
- Ultrasound Guidance:Real-time imaging with portable cart-based systems enables point-of-care deployment. Demand concentrates in United States ambulatory surgical centers where Medicare site-of-service differentials pull low-complexity biopsies from hospital outpatient departments.
- MRI Guidance:Superconducting magnet compatibility demands specialized RF coils and electromagnetic shielding. Academic medical centers in Germany and the United States deploy these for prostate and breast applications where soft-tissue contrast determines diagnostic yield.
- CT Guidance:Cross-sectional navigation for lung and bone lesions with fluoroscopic overlay. Interventional radiology suites in tertiary centers.
- X-ray Guidance:Stereotactic breast biopsy with digital mammography integration. Screening-dense networks in North America.
Ultrasound guidance dominates installed base. MRI guidance is where expansion concentrates.
End User:
Procurement authority splits between capital equipment committees and departmental operating budgets, creating tiered purchasing behavior.
- Hospitals:Integrated platform acquisitions with multi-modality imaging suites and captive consumables contracts. United States academic medical centers retrofitting interventional radiology departments.
- Diagnostic Clinics:Mid-range ultrasound-guided systems with simplified workflows. Tier-2 cities in India under CDSCO streamlined registration.
- Research Labs:Preclinical electromagnetic tracking systems for algorithm development. NIH-funded institutions in Maryland and Massachusetts.
- Imaging Centers:Lease-based stereotactic breast biopsy platforms with per-procedure revenue models. Independent diagnostic facilities in Texas and Florida.
Hospitals control capital deployment. Diagnostic clinics are climbing the fastest.
Technology:
Software layers are displacing hardware differentiation, compressing margins for pure-play navigation vendors.
- Robotic Assistance:Electromagnetic tracking with automated needle positioning reduces operator-dependent variability. United States hospitals seeking to standardize lung and renal biopsy accuracy.
- 3D Imaging:Reconstructed tomographic overlay for trajectory planning in complex anatomical regions. European centers under EU MDR class IIa documentation requirements.
- Optical Coherence Tomography:Microstructural tissue visualization for dermatologic and ophthalmic applications. Research-limited deployment in academic dermatology departments.
- Radiofrequency Identification:Needle tip localization for inventory tracking and procedure documentation. Integrated into vendor-managed consignment programs.
Robotic assistance commands premium pricing. 3D imaging modules are gaining share fastest.
Application:
Screening program expansion and site-of-service migration reshape procedure volume distribution across specialties.
- Oncology:Lung, prostate, and breast biopsy with staging integration. Rising procedural volumes in United States hospital networks expanding installed bases.
- Dermatology:Optical coherence-guided excision for melanoma margins. Outpatient dermatology practices in Germany and Switzerland.
- Gastroenterology:Endoscopic ultrasound with fine-needle aspiration. Hepatobiliary centers in Japan and South Korea.
- Urology:MRI-ultrasound fusion biopsy for prostate cancer detection. United States urology groups adopting navigation platforms.
Oncology anchors revenue concentration. Urology is where steepest expansion trajectory materializes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways anchor the United States as the dominant geography, while CE marking under EU MDR and CDSCO registration timelines shape access cadence across secondary markets. Academic medical centers and diagnostic infrastructure buildouts concentrate demand in specific national clusters.
United States
Academic medical centers in Boston, Baltimore, and Houston are retrofitting interventional radiology suites with integrated guidance platforms to handle rising lung and prostate screening volumes. FDA 510(k) clearance timelines determine product launch sequencing for navigation software upgrades. The NIH-funded research corridor between Maryland and Massachusetts anchors electromagnetic tracking algorithm development.
Germany
University hospitals in Munich and Heidelberg deploy MRI-compatible biopsy platforms for prostate applications where soft-tissue contrast determines diagnostic yield. EU MDR technical documentation requirements for class IIa devices filter procurement toward full-stack vendors with established quality systems. The Baden-Württemberg medical technology cluster concentrates precision instrument manufacturing.
India
Tier-2 cities including Pune, Ahmedabad, and Hyderabad are absorbing mid-range ultrasound-guided systems under CDSCO streamlined registration pathways. PLI scheme incentives for domestic manufacturing create entry points for cart-based guidance platforms. Diagnostic infrastructure buildout concentrates in Maharashtra and Gujarat where private hospital chains expand imaging networks.
Japan
Hepatobiliary centers in Tokyo and Osaka integrate endoscopic ultrasound with fine-needle aspiration for liver cancer staging. PMDA regulatory review timelines shape product registration for navigation software updates. The Kanto region anchors demand for compact guidance systems serving aging screening populations.
Switzerland
Swissmedic oversight of class IIa medical devices maintains stringent clinical evidence requirements for needle navigation platforms. Specialty wire-drawing facilities in the Jura region supply precision biopsy needles with echogenic coatings to European OEMs. The Basel-Zurich corridor concentrates contract manufacturing for disposable consumables.
Biopsy Guidance System Market Key Industry Players
Capability concentration sits with integrated imaging-platform vendors; scale advantage sits with diversified medical technology conglomerates. The vendor base stratifies across three tiers: full-stack platform developers controlling hardware-software-consumables workflows, pure-play navigation specialists licensing electromagnetic tracking modules, and regional disposable manufacturers supplying third-party needle contracts. Dominant competitive moves include backward integration into specialty wire-drawing capacity and strategic partnerships between robotics developers and imaging OEMs.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Boston Scientific Corporation exemplify the integrated-platform archetype, while Hologic, Inc. occupies a position within the breast-health specialization tier. These entities represent contrasting strategic postures: vascular-access heritage anchoring percutaneous portfolios, interventional oncology workflows merging therapeutic devices with navigation platforms, and screening-dense network penetration extending into stereotactic guidance ecosystems.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Hologic, Inc. |
| Devicor Medical Products, Inc. |
| B. Braun Melsungen AG |
| Argon Medical Devices, Inc. |
| Boston Scientific Corporation |
| INRAD Inc. |
| Cook Medical |
| Planmed Oy |
| Others |
Cost & Logistics Intelligence
Overcapacity in German precision wire-drawing facilities is compressing input costs for echogenic needle coatings while simultaneously eroding supplier pricing power, forcing guidance system OEMs to renegotiate consumables contracts or absorb margin compression.
Pricing Analysis
Geographic price spreads between United States academic medical centers and Indian tier-2 diagnostic clinics exceed three-to-one for comparable ultrasound-guided platforms. Three-tier pricing structure across premium, standard, and economy levels separates MRI-integrated suites with robotic assistance from cart-based ultrasound systems and refurbished legacy hardware. Price differentiation rests on FDA 510(k) clearance tier and CE marking under EU MDR class IIa documentation depth. Cost compression in mid-range segments is intensifying because hospital procurement committees unbundle capital equipment from disposable contracts. Community hospitals exhibit highest price sensitivity; academic centers with dedicated interventional radiology budgets demonstrate lowest.
Supply Chain Analysis
Export control regimes limiting electromagnetic tracking sensor flows from Switzerland constrain navigation module availability for non-EU OEMs. Manufacturing concentrates in Germany for precision biopsy needles, the United States for imaging-platform assembly, and Switzerland for specialty wire-drawing. Raw material dependencies include superconducting alloys for MRI-compatible components, echogenic coating substrates, and electromagnetic field generator substrates. Single-source vulnerability concentrates in Jura region wire-drawing facilities supplying European OEMs. Distribution runs through vendor-managed consignment programs at integrated delivery networks and third-party needle supply agreements with group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive moat anchored in regulatory entrenchment: FDA 510(k) clearance timelines and EU MDR technical documentation requirements create multi-year barriers that protect installed base positions from rapid competitive displacement.
For Market Incumbents: Insulate core revenue streams by securing captive supply agreements with German and Swiss specialty wire-drawing facilities before procurement committees complete unbundling transitions. Deepen backward integration into electromagnetic tracking sensor production to offset export control exposure. Prioritize software companion development for AI-assisted real-time targeting to maintain premium positioning against emerging navigation specialists. For New Entrants and Emerging Players: Establish a beachhead in Indian tier-2 cities where CDSCO streamlined registration and PLI scheme incentives lower capital barriers for mid-range ultrasound-guided platforms. Target ambulatory surgical centers in United States Midwestern health systems where site-of-service differentials pull low-complexity biopsies from hospital outpatient departments. Pursue software licensing models for electromagnetic tracking modules rather than competing on integrated hardware. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-stack platform vendors with captive consumables contracts and established quality management systems under EU MDR. Long-term viability across the analysis window favors vendors controlling hardware-software-consumables workflows with backward integration into precision manufacturing. Monitor FDA 510(k) clearance backlogs and notified body review timelines as inflection indicators for competitive access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR class IIa documentation requirements filter procurement toward established quality system vendors. |
| Hospital System Partnership | Integrated delivery network contracts lock in multi-modality platform deployments across retrofitted imaging suites. |
| Software Companion Development | AI-assisted real-time targeting algorithms open premium pricing tiers for navigation software upgrades. |
| Backward Integration | Captive supply of precision biopsy needles with echogenic coatings mitigates German and Swiss input cost volatility. |
| Reimbursement Strategy | CMS coding revisions for image-guided needle placement procedures determine margin sustainability on integrated workflows. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare fee schedules. Primary interviews engaged interventional radiologists, hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and regulatory affairs leads at guidance system OEMs. Secondary validation drew from SEC 10-K disclosures, CDSCO registration records, and proprietary hospital capital equipment expenditure tracking. Bottom-up procedure volume modeling and top-down imaging-platform shipment analysis were cross-referenced for triangulation.
Forecast inputs span imaging modality replacement cycles, procedural volume growth in lung and prostate screening programs, and reimbursement coding revision timelines. Segmentation dimensions include guidance technology type, end-user facility tier, application specialty, and regional regulatory cluster. CAGRs were derived from installed base expansion trajectories and per-procedure consumables attach rates. Industry-specific inputs incorporate electromagnetic tracking adoption curves and EU MDR transition completion schedules.
Stress conditions across FDA clearance backlog duration, German wire-drawing capacity utilization, and Medicare site-of-service differential magnitude were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procedural volume growth and technology substitution rates. Material shifts in FDA 510(k) pathway streamlining or EU MDR notified body capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Breath Samplers Market