
 Neurophotonics Market | 2026-2036
Neurophotonics Market Size, Share, and Industry Trends Forecast 2026-2036
Neurophotonics Market Analysis
The EU Medical Device Regulation is rebalancing procurement criteria toward certified optical imaging platforms in European neuroscience centers. Femtonics Ltd. leverages its two-photon microscopy specialization to anchor demand in live-cell neural imaging workflows. HORIBA Ltd. competes through its spectroscopy portfolio across multi-modal brain mapping installations. Carl Zeiss AG dominates the structured illumination segment with precision optics manufacturing at scale.
Neurophotonics encompasses the application of light-based technologies to neural tissue interrogation, spanning wavelength ranges from ultraviolet through near-infrared with sub-micron spatial resolution. The field employs femtosecond laser pulses, genetically encoded calcium indicators, and fiber-optic neural interfaces to enable real-time observation of neuronal activity in behaving organisms. Fluorescence microscopy commands the largest installed base among technology segments, while near infrared spectroography represents the fastest clinical translation pathway for non-invasive brain monitoring. Imaging systems capture the dominant share of product-type value pools due to integrated software-hardware bundling and recurring service contracts.
FDA optical imaging device classifications, EU MDR technical documentation requirements, and ISO 13485 quality management standards collectively elevate barriers for unvalidated neurophotonics entrants. Japan's PMDA enforces additional electromagnetic compatibility testing for laser-based neural interfaces sold into clinical settings. Stakeholders must monitor harmonization gaps between FDA 510(k) optical subsystem guidance and emerging EU AI Act requirements for machine-learning-enhanced neuronal signal interpretation.
Market Dynamics
Academic neuroscience departments in Germany, the United States, and Japan are accelerating capital deployment into fluorescence microscopy suites, compressing vendor sales cycles and reshaping equipment financing structures. EU Medical Device Regulation tightening on optical imaging certification is simultaneously elevating compliance costs and filtering supplier pools.
Growth Catalysts
- EU MDR optical imaging certification mandates:European neuroscience centers must recertify platforms, generating replacement demand for validated systems. Procurement officers prioritize pre-certified vendors.
- Live-cell neural imaging workflows:Two-photon microscopy enables real-time calcium indicator visualization in behaving organisms. Research hospitals in Switzerland and the United Kingdom scale installations.
- Japan PMDA electromagnetic compatibility pathways:Streamlined testing protocols for laser-based neural interfaces accelerate clinical translation timelines. Domestic manufacturers gain first-mover positioning.
Market Restraints
- Femtosecond laser component concentration:German and Austrian specialty laser suppliers control critical ultrafast pulse generation subsystems. Supply disruptions propagate through imaging system backlogs.
- ISO 13485 quality management implementation costs:Small-scale neurophotonics entrants face six-figure certification investments. Documentation requirements consume eighteen-month runway periods.
- Functional MRI substitution in clinical diagnostics:Hospital administrators default to established reimbursement codes for magnetic resonance brain mapping. Optical methods compete for capital budget prioritization.
Strategic Opportunities
- Near-infrared spectroscopy clinical translation:Non-invasive brain monitoring applications in neonatal intensive care units remain underpenetrated. Swiss and British university hospitals pilot ward-scale deployments.
- EU AI Act neuronal signal interpretation frameworks:Machine-learning-enhanced calcium imaging analysis qualifies for regulatory sandbox programs. Software-hardware bundling creates recurring revenue streams.
- Fiber-optic neural interface miniaturization:Convergence of silicon photonics and polymer waveguide fabrication enables chronic implantable devices. Japanese precision manufacturing clusters capture process IP.
Industry Challenges
- Cross-disciplinary talent scarcity:Optical engineering and systems neuroscience skill intersection commands premium compensation. German technical universities struggle to scale joint-degree program throughput.
- FDA 510(k) optical subsystem harmonization gaps:Divergent documentation requirements between FDA guidance and EU MDR technical files duplicate regulatory affairs overhead. Dual-market entrants absorb redundant compliance labor.
- Legacy microscopy infrastructure integration:Research hospitals in the United States face fiber-coupling incompatibility between installed fluorescence systems and next-generation photon-counting detectors. Retrofit engineering extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurophotonics Market |
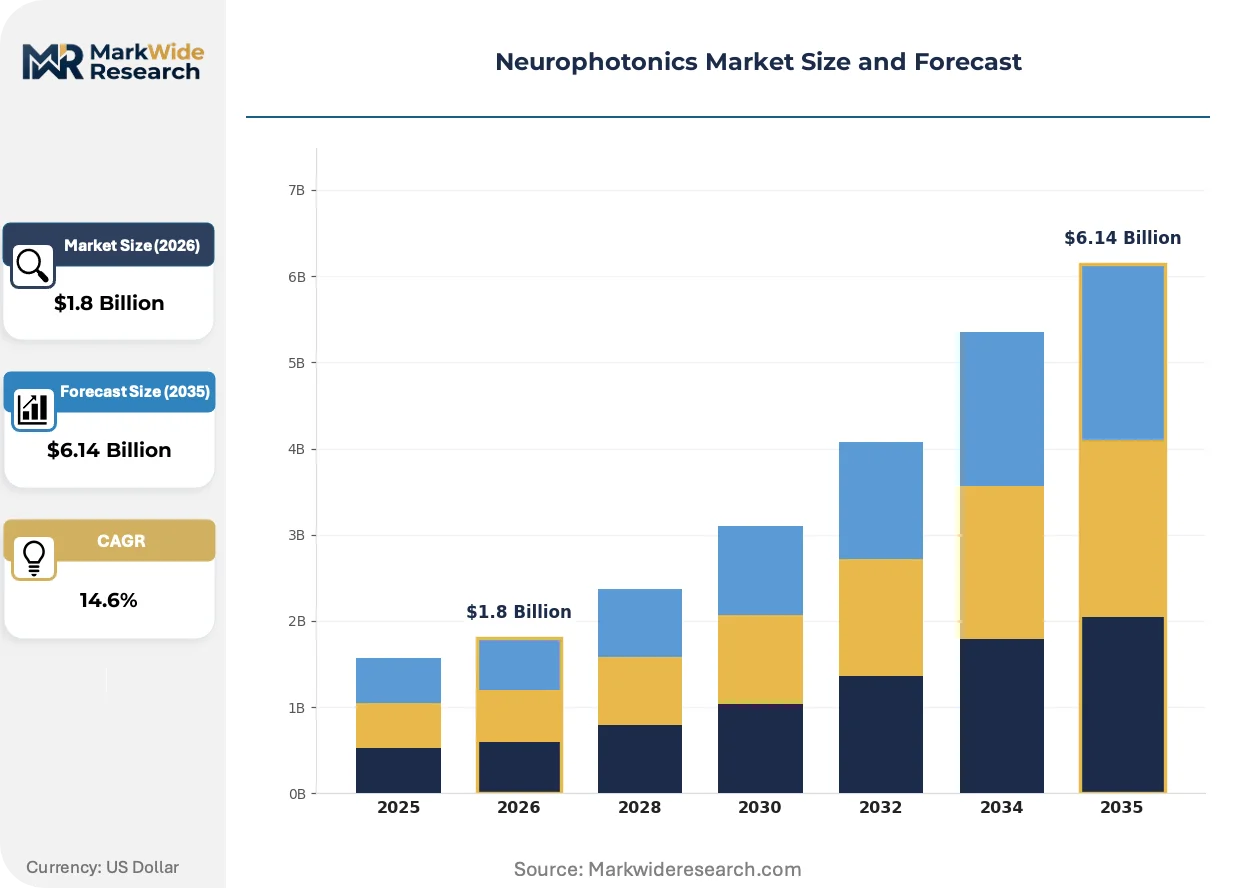
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lasers, Imaging Systems, Sensors, Light Sources Technology: Optical Coherence Tomography, Near Infrared Spectroscopy, Fluorescence Microscopy, Phototherapy Application: Research and Development, Diagnostics, Therapeutics, Clinical Applications End User: Research Institutions, Hospitals, Diagnostic Labs, Pharmaceutical Companies |
| Companies Covered | Femtonics Ltd., HORIBA Ltd., Artinis Medical Systems, Intelligent Imaging Innovations Inc., Inscopix Inc., Cairn Research Ltd., Bruker Corp., ISS Inc., Carl Zeiss AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurophotonics Market Emerging Trajectories
Photon-counting detector arrays and adaptive optics wavefront correction are compressing spatial resolution limits while expanding volumetric imaging depths. Regulatory frameworks for machine-learning-enhanced neuronal signal processing are crystallizing across multiple jurisdictions.
Genetically encoded voltage indicators are overtaking calcium indicators in voltage imaging applications requiring millisecond temporal precision. Neuroscience departments at Stanford University and the Max Planck Institute adopt these probes for action potential propagation studies. The technology is overtaking traditional electrophysiology in high-throughput screening workflows, compressing demand for patch-clamp equipment.
EU AI Act requirements for high-risk AI systems are mandating conformity assessments for machine-learning-enhanced neuronal signal interpretation software. Optical imaging vendors must embed explainability documentation and bias testing protocols into product development cycles. Multi-modal brain mapping installations in France and the Netherlands face eighteen-month certification timelines for AI-augmented calcium imaging analysis modules.
Research consortia in Japan and Switzerland are unbundling after-sales service contracts from hardware procurement, negotiating separate maintenance agreements with third-party optical service specialists. University-affiliated research hospitals in Tokyo and Basel now source preventive maintenance from independent metrology laboratories. This restructuring compresses vendor service margins while accelerating response times for laser alignment and detector calibration issues.
Neurophotonics Market Segmentation
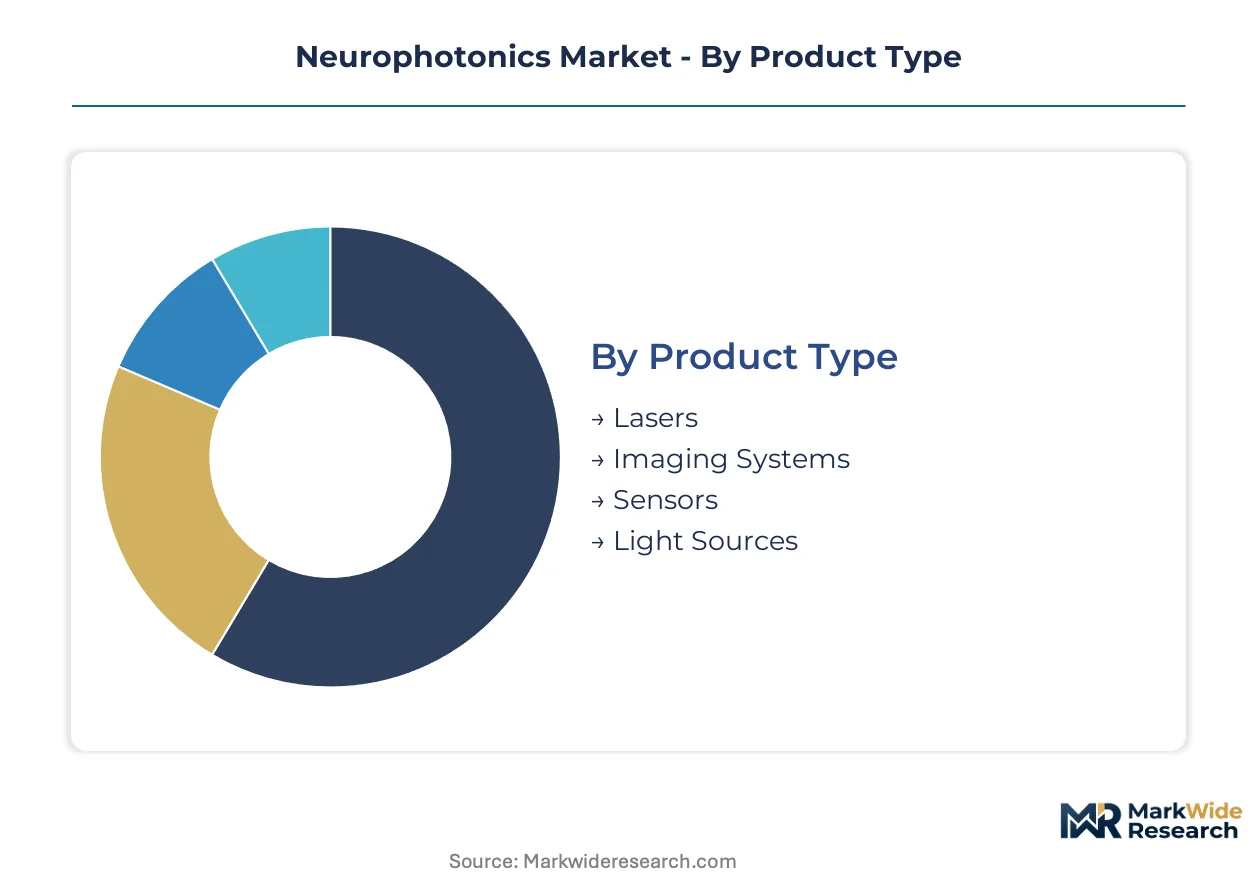
Neurophotonics segmentation reflects divergent technical requirements across fundamental research and clinical translation pathways. Procurement patterns split between capital-intensive imaging platforms and consumable light sources, while regulatory boundaries separate diagnostic-grade systems from research-only configurations.
Product Type:
Component specifications determine integration complexity and service revenue potential across neural interface deployments.
- Imaging Systems:Integrated fluorescence and two-photon microscopy platforms bundle precision optics with proprietary software control architectures. University-affiliated research hospitals in Japan and Switzerland concentrate procurement of these systems, driven by live-cell neural imaging workflow standardization and EU MDR certification requirements for clinical translation pathways.
- Lasers:Femtosecond pulse generation subsystems enable deep-tissue penetration through temporal focusing. German and Austrian specialty suppliers control critical ultrafast component manufacturing, creating supply concentration risks that propagate through imaging system production backlogs.
- Sensors:Photon-counting detector arrays and fiber-optic neural interfaces capture sub-micron spatial resolution signals.
- Light Sources:Wavelength-tunable LED and laser diode modules serve routine microscopy illumination requirements.
Mature deployment sits with Imaging Systems. Newer deployment is concentrated in Sensors.
Technology:
Resolution-depth tradeoffs and invasiveness constraints shape adoption velocity across neuroscience applications.
- Fluorescence Microscopy:Genetically encoded calcium and voltage indicator visualization dominates installed base metrics. Stanford University and Max Planck Institute neuroscience departments scale these platforms for action potential propagation studies, compressing demand for traditional electrophysiology equipment.
- Near Infrared Spectroscopy:Non-invasive brain monitoring penetrates neonatal intensive care and ward-scale clinical settings. Swiss and British university hospitals pilot expanded deployments, exploiting streamlined regulatory pathways for optical diagnostic methods outside established MRI reimbursement codes.
- Optical Coherence Tomography:Interferometric depth-resolved imaging supports retinal and cortical surface applications.
- Phototherapy:Targeted light delivery modulates neural activity in therapeutic protocols.
Clinical translation concentrates in Near Infrared Spectroscopy. Research dominance persists in Fluorescence Microscopy.
Application:
Budget authority and reimbursement infrastructure determine addressable market boundaries for each use case.
- Research and Development:Fundamental neuroscience investigations employ custom-configured microscopy suites with experimental flexibility prioritized over regulatory compliance. Academic departments in Germany and the United States accelerate capital deployment, compressing vendor sales cycles through centralized procurement initiatives.
- Diagnostics:Clinical-grade optical brain monitoring requires FDA 510(k) or EU MDR certification with embedded quality management systems. Hospital administrators weigh these platforms against functional MRI alternatives with established reimbursement codes, creating capital budget prioritization constraints.
- Therapeutics:Photobiomodulation and optogenetic intervention protocols.
- Clinical Applications:Integrated diagnostic-therapeutic workflows in specialized neurology centers.
Volume concentration aligns with Research and Development. Margin expansion concentrates in Diagnostics.
End User:
Procurement sophistication and service contract structures vary sharply across institutional categories.
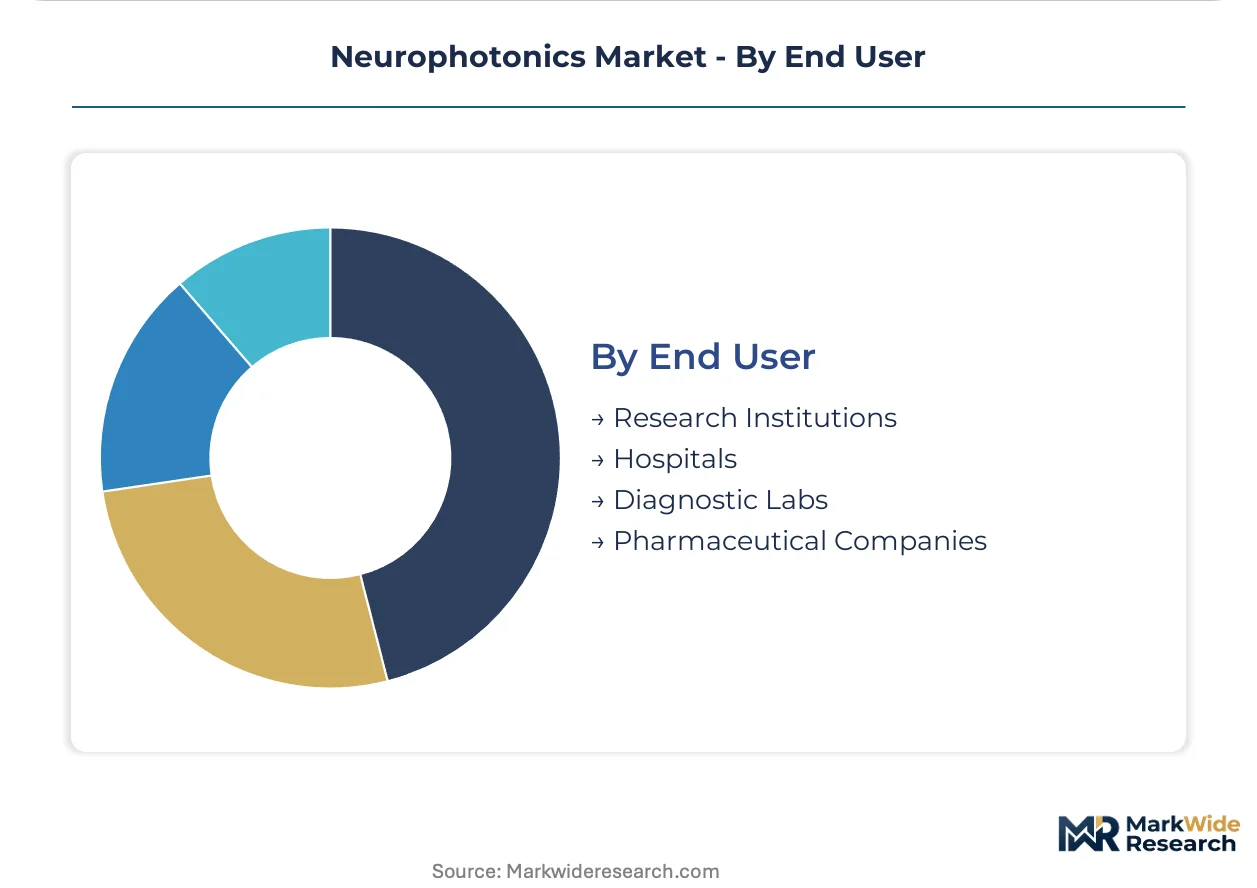
- Research Institutions:University neuroscience departments and Max Planck-style institutes negotiate multi-year equipment financing with integrated maintenance clauses. Japanese and Swiss consortia increasingly unbundle after-sales service contracts, sourcing preventive maintenance from independent metrology laboratories to accelerate laser alignment response times.
- Hospitals:University-affiliated research hospitals face fiber-coupling incompatibility between legacy fluorescence infrastructure and next-generation photon-counting detectors. Retrofit engineering extends deployment timelines while creating upgrade pathway decisions.
- Diagnostic Labs:Specialized neurology testing centers with streamlined optical imaging protocols.
- Pharmaceutical Companies:High-throughput screening operations displacing patch-clamp electrophysiology with voltage imaging methods.
Equipment financing innovation originates with Research Institutions. Regulatory compliance burden concentrates in Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of femtosecond laser subsystems concentrates in German and Austrian manufacturing clusters, while consumption of integrated imaging platforms spreads across university-affiliated research hospitals in Japan, Switzerland, and the United Kingdom.
United States
Stanford University and Max Planck Institute neuroscience departments scale fluorescence microscopy installations for voltage imaging applications. FDA 510(k) optical subsystem guidance shapes procurement criteria for clinical translation pathways. Greater Boston research hospitals face fiber-coupling incompatibility between legacy infrastructure and photon-counting detectors.
Germany
Academic neuroscience departments accelerate capital deployment into two-photon microscopy suites through centralized procurement initiatives. EU MDR technical documentation requirements elevate compliance costs for optical imaging system certification. Bavarian precision optics manufacturing clusters dominate structured illumination component supply.
Japan
Domestic manufacturers gain first-mover positioning through PMDA electromagnetic compatibility testing protocols for laser-based neural interfaces. METI research consortia unbundle after-sales service contracts from hardware procurement. Tokyo university hospitals now source preventive maintenance from independent metrology laboratories.
Switzerland
Swiss university hospitals pilot ward-scale near-infrared spectroscopy deployments in neonatal intensive care units. Swissmedic certification pathways for optical diagnostic methods operate outside established MRI reimbursement codes. Basel research clusters negotiate separate maintenance agreements with third-party optical service specialists.
United Kingdom
British university hospitals expand non-invasive brain monitoring applications for clinical translation. MHRA alignment with EU MDR requirements filters supplier pools toward pre-certified vendors. London neuroscience centers prioritize live-cell neural imaging workflow standardization in procurement decisions.
Neurophotonics Market Vendor Landscape
The competitive structure tilts toward precision optics specialists with captive manufacturing capabilities. Tiered vendor pools separate integrated platform providers from component subsystem suppliers. Two archetypes dominate: vertically integrated microscopy houses controlling optical design-to-assembly workflows, and laser subsystem specialists supplying femtosecond pulse generation technology. Competitive moves concentrate on strategic partnerships for AI-enhanced signal interpretation and geographic expansion into Asian research hospital networks.
Among European precision optics manufacturers, Carl Zeiss AG and Femtonics Ltd. exemplify divergent strategic positioning. Zeiss occupies a scale-driven position across structured illumination segments, while Femtonics represents specialized two-photon microscopy anchoring in live-cell neural imaging workflows. HORIBA Ltd. sits within the spectroscopy archetype, competing across multi-modal brain mapping installations through wavelength-tunable platform bundling.
| Leading Market Players |
|---|
| Femtonics Ltd. |
| HORIBA Ltd. |
| Artinis Medical Systems |
| Intelligent Imaging Innovations Inc. |
| Inscopix Inc. |
| Cairn Research Ltd. |
| Bruker Corp. |
| ISS Inc. |
| Carl Zeiss AG |
| Others |
Supply Flow & Price Mechanics
Family-owned precision optics specialists in Germany and Japan anchor supply-side discipline through multi-generational manufacturing know-how, translating captive process IP into pricing power that resists commoditization pressure from modular competitors.
Pricing Analysis
Cost-down pressure on research-grade imaging systems accelerates because Japanese and Swiss university consortia now unbundle after-sales service contracts from hardware procurement. Three-tier pricing structure across premium certified, standard research-grade, and economy configurable levels separates EU MDR-compliant platforms from research-only configurations. Certification grade and volume scale drive price differentiation, with pharmaceutical screening operations commanding least price sensitivity due to patch-clamp displacement timelines. Academic departments in Germany face greatest price sensitivity as centralized procurement initiatives compress vendor margins.
Supply Chain Analysis
Dual-sourcing requirements for femtosecond laser subsystems mandate multi-supplier qualification across German, Austrian, and Japanese specialty manufacturers. Critical inputs include titanium-doped sapphire crystals, polarization-maintaining fiber, and photon-counting detector arrays. Single-source vulnerability concentrates in Bavarian precision optics clusters where Carl Zeiss AG and mid-tier specialists control structured illumination component supply. Distribution runs through direct vendor-to-institution contracts with integrated maintenance clauses, though Tokyo and Basel research hospitals increasingly route preventive service through independent metrology laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Femtosecond laser component concentration in German and Austrian manufacturing clusters props pricing discipline, constraining imaging system throughput and elevating procurement lead times for non-preferred customers.
For Market Incumbents: Extend certification coverage across EU AI Act neuronal signal interpretation modules to preempt eighteen-month conformity assessment delays faced by French and Dutch multi-modal installations. Deepen backward integration into titanium-doped sapphire crystal supply through captive agreements with Bavarian specialty material processors. Functional MRI substitution in clinical diagnostics represents the primary margin threat requiring reimbursement strategy differentiation.
For New Entrants and Emerging Players: Silicon photonics-enabled fiber-optic neural interface miniaturization offers a technology-first wedge into chronic implantable device segments where Japanese precision manufacturing clusters currently dominate process IP. Near-infrared spectroscopy ward-scale deployments in Swiss and British neonatal intensive care units present the most penetrable white-space target. Go-to-market execution should prioritize independent metrology laboratory partnerships to bypass incumbent service bundling.
For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-certified mid-cap specialists with EU MDR technical documentation already filed, particularly those clustered in German precision optics manufacturing regions. Long-term viability over the next decade hinges on machine-learning-enhanced calcium imaging analysis capabilities qualifying for regulatory sandbox programs. Watch FDA 510(k) optical subsystem harmonization gaps with EU MDR as the inflection signal for dual-market compliance overhead expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Eighteen-month conformity timelines filter supplier pools toward pre-validated optical imaging platforms in European neuroscience centers. |
| Machine-Learning Software Companion Development | Explainability documentation and bias testing protocols embedded in neuronal signal interpretation modules unlock recurring revenue streams. |
| Hospital System Partnership | University-affiliated research hospitals in Japan and Switzerland unbundle service contracts, creating third-party maintenance ecosystem opportunities. |
| Backward Integration into Laser Subsystems | Captive supply of femtosecond pulse generation technology mitigates Austrian and German specialty supplier concentration risks. |
| Reimbursement Strategy | Optical brain monitoring methods compete against established functional MRI codes, requiring clinical economic evidence for capital budget prioritization. |
Methodological Framework
Multi-period observation of femtosecond laser subsystem backlogs, EU MDR certification timelines, and university procurement cycle compression anchored the trend analysis, supplemented by interviews with biomedical engineers at Stanford University and Max Planck Institute, GPO contracts managers at Japanese research hospital networks, regulatory affairs leads navigating FDA 510(k) optical subsystem guidance, and precision optics manufacturing executives in Bavarian clusters. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, PMDA electromagnetic compatibility testing protocols, and hospital procurement records. Bottom-up vendor shipment tracking and top-down research funding allocation analysis provided triangulation.
Segment-weighting across product type, technology, application, and end user dimensions shaped the analytical framework over the projection horizon. Imaging systems, lasers, sensors, and light sources received differential growth assumptions based on live-cell neural imaging workflow standardization velocity and near-infrared spectroscopy clinical translation progress. CAGRs derived from installed base expansion rates, replacement demand cycles, and research funding trajectories across German, Japanese, Swiss, British, and American neuroscience departments. Forecast inputs incorporated EU AI Act implementation timelines and fiber-optic neural interface miniaturization roadmaps from Japanese METI consortia.
Several conditions sit outside the modeled scope, including unforeseen supply disruptions in titanium-doped sapphire crystal processing, accelerated functional MRI reimbursement code expansion, and geopolitical restrictions on laser subsystem trade. Forecasts reflect assumptions about regulatory harmonization progress and research funding continuity. A model refresh is warranted upon material change in EU MDR certification backlog durations or PMDA electromagnetic compatibility testing protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
Canada Mammography Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
AI-Assisted Radiology Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Portable MRI Market