
 Veterinary Chemistry Analyzers Market | 2026-2036
Veterinary Chemistry Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Chemistry Analyzers Market Intelligence
A multi-source procurement strategy for reagents and consumables is hardening across large veterinary hospital groups, moving away from single-vendor lock-ins. This shift challenges players like IDEXX Laboratories, Inc., which leverages a closed-system model linking analyzers to proprietary consumables. Zoetis Inc. expands its diagnostic portfolio to offer broader compatibility across platforms. Heska Corporation competes by specializing in open-platform analyzers, giving clinics greater flexibility in sourcing supplies.
Veterinary chemistry analyzers are automated instruments that measure chemical and enzyme concentrations in animal biological samples like blood, serum, or urine. These systems employ technologies such as photometry and electrochemistry to quantify analytes critical for disease diagnosis, pre-surgical screening, and health monitoring. Benchtop models constitute the largest product segment by installed base, while portable analyzers see accelerated uptake in mobile veterinary services. Diagnostic laboratories and large animal hospitals remain the principal application segments, driving significant volume.
Instrument and reagent approvals are governed by regulatory bodies including the U.S. FDA's Center for Veterinary Medicine and the European Medicines Agency's CVMP. Compliance with quality management standards, notably ISO 13485 for medical devices, is also critical for global market access and ensuring device reliability. A key decision point for veterinarians is now the analyzer's ability to seamlessly integrate with practice management software systems for streamlined workflows and centralized data management.
Market Dynamics
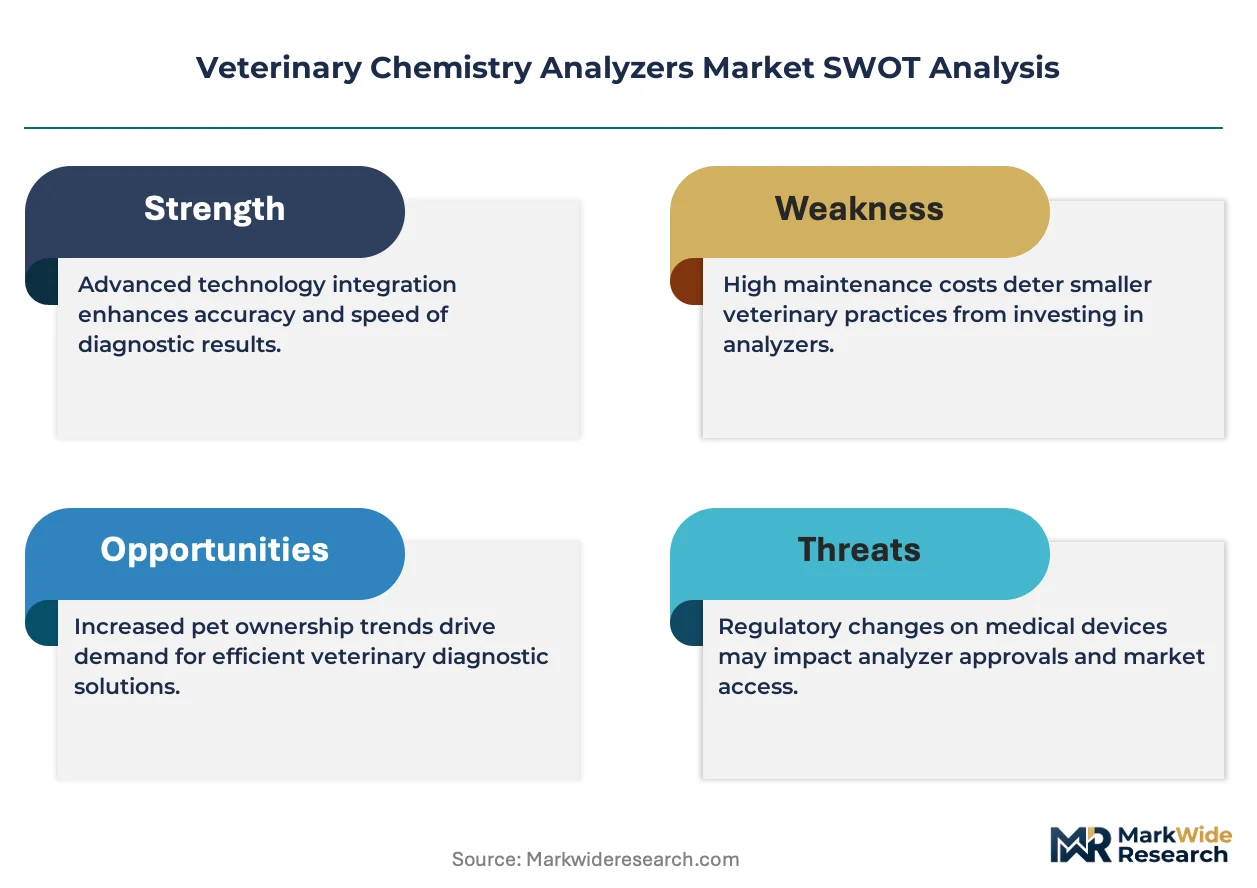
The central dynamic in the veterinary chemistry analyzer market is the conflict between vendor-driven closed-system ecosystems and a user-driven push for open-platform flexibility. This tension influences purchasing decisions, reagent pricing, and the competitive strategies of instrument manufacturers.
Growth Catalysts
- Pet Health Expenditure:Rising discretionary spending on companion animal health in developed nations, including the United States and Germany, directly correlates with investment in advanced in-house diagnostic capabilities.
- Point-of-Care Diagnostics:The trend toward miniaturization and portability allows for rapid testing in mobile veterinary units and emergency clinics, improving the speed and convenience of care delivery.
- Livestock Health Management:Demand for analyzers in production animal settings is supported by disease surveillance programs and the need to ensure food supply chain safety in agricultural economies.
Market Restraints
- High Instrument Cost:The significant initial capital outlay for high-throughput benchtop analyzers remains a primary adoption barrier for small, independent veterinary practices and clinics in emerging economies.
- Proprietary Consumables:The prevalence of closed-system analyzers links users to a single manufacturer for reagents and consumables, limiting pricing leverage and creating supply chain dependencies.
- Specialized Training Needs:Effective operation, quality control, and maintenance of advanced chemistry analyzers require specific technical skills, creating a potential bottleneck in clinics with limited staff training resources.
Strategic Opportunities
- Software Integration:Developing analyzers with advanced connectivity features that seamlessly integrate with a wide array of Practice Management Information Systems (PIMS) offers a key competitive differentiator.
- Exotic and Niche Species:Creating validated reagent panels and reference intervals for exotic animals, avian species, and reptiles addresses an underserved and high-value segment of veterinary medicine.
- Subscription-Based Models:Offering reagent rental or pay-per-test agreements provides an alternative to large upfront capital expenditures, expanding access for cost-sensitive veterinary practices.
Industry Challenges
- Data Standardization:A lack of universal standards for data formatting and communication between different diagnostic instruments and software systems complicates workflow automation and centralized record-keeping.
- Regulatory Divergence:Manufacturers face increased costs and longer development timelines to meet the distinct and evolving device approval requirements of the U.S. FDA and the European Medicines Agency.
- Cold Chain Logistics:Ensuring the temperature stability and efficacy of liquid reagents during transport and storage poses a significant logistical challenge, particularly for mobile and rural practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Chemistry Analyzers Market |
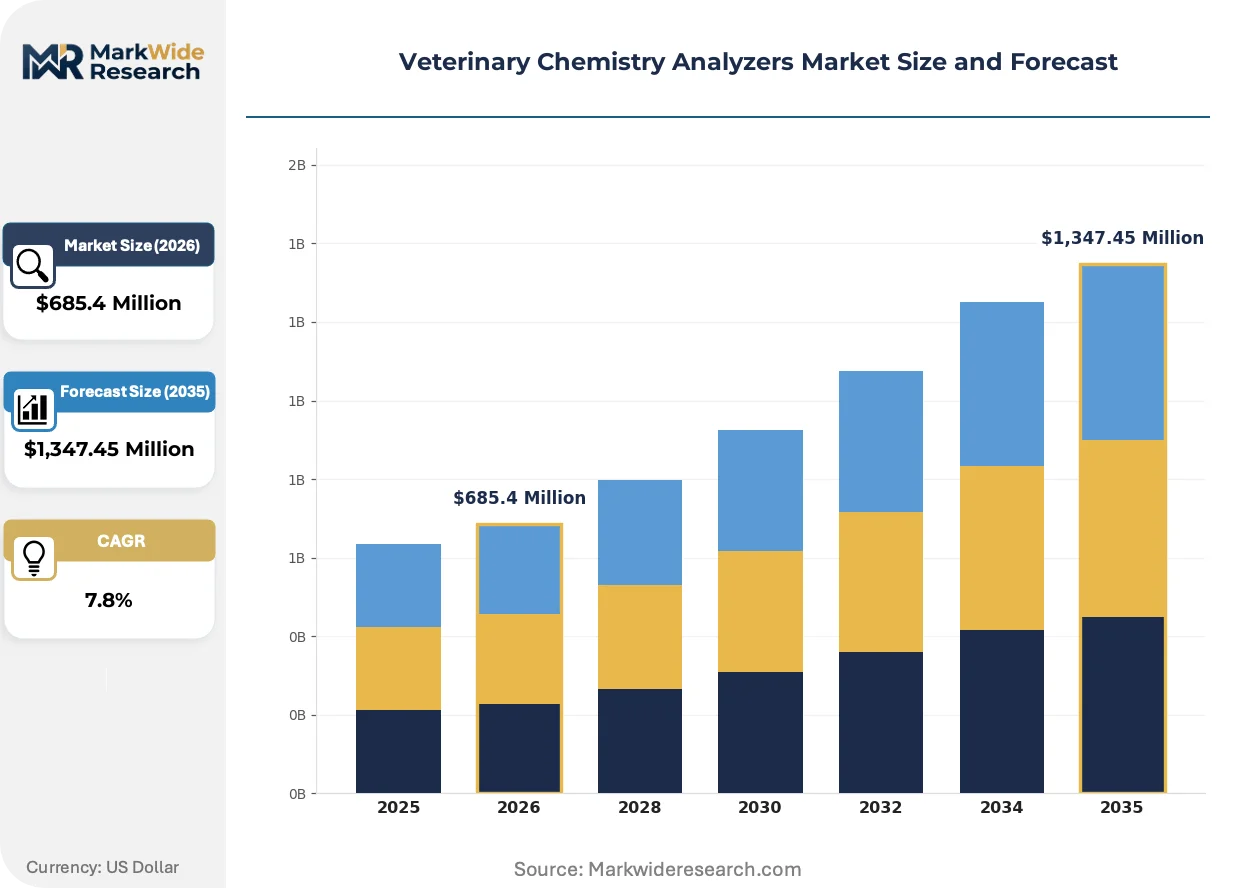
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automated, Semi-Automated, Portable, Benchtop Technology: Photometry, Electrochemistry, Turbidimetry, Potentiometry, Reflectance Application: Diagnostic Laboratories, Veterinary Clinics, Research Institutes, Animal Health Centers End User: Veterinarians, Animal Hospitals, Diagnostic Service Providers, Animal Breeders |
| Companies Covered | IDEXX Laboratories, Inc., Zoetis Inc., Heska Corporation, Randox Laboratories Ltd., HORIBA Medical, Chengdu Seamaty Technology Co., Ltd., DiaSys Diagnostic Systems GmbH, Abaxis Inc., URIT Medical Electronic Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Chemistry Analyzers Market Strategic Shifts & Innovations
The convergence of data management with diagnostic instrumentation is reshaping the market. Emphasis is shifting from standalone hardware performance to how effectively an analyzer integrates into a clinic's digital workflow, providing actionable insights alongside raw data.
Microfluidics technology enables the analysis of minute biological samples within a compact, often disposable, cartridge. Veterinary clinics and diagnostic laboratories are adopting these systems for their speed and reduced reagent consumption. This technology is modularizing diagnostic testing, allowing for flexible, multi-parameter analysis on smaller, more accessible point-of-care platforms.
Increased regulatory oversight, exemplified by guidelines from the European Medicines Agency's Committee for Medicinal Products for Veterinary Use (CVMP), is elevating standards for instrument and reagent validation. This shift compels manufacturers to provide more extensive data supporting the accuracy and reliability of their diagnostic systems. The segment most affected is new product development, which now must incorporate more rigorous clinical performance studies to gain market access in the EU.
A notable behavioral shift involves large veterinary hospital groups moving toward multi-vendor sourcing for consumables. This strategy directly challenges the traditional sales model of single-vendor, closed-system contracts. This change in procurement is most evident in the mature North American market, where consolidated corporate practices leverage their purchasing volume to demand greater flexibility and cost control.
Veterinary Chemistry Analyzers Market Segmentation
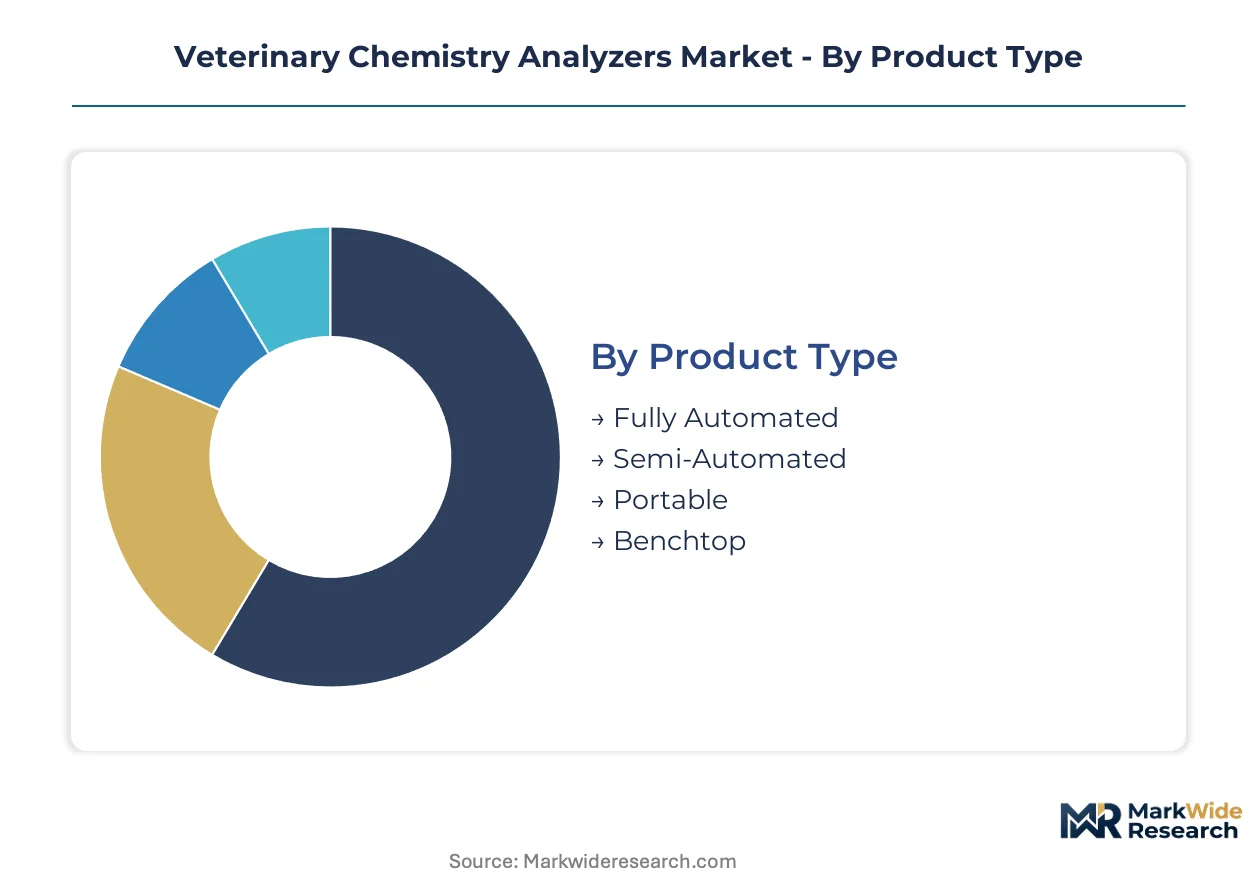
The veterinary chemistry analyzers market exhibits diverse segments, reflecting varied clinical needs and operational scales within animal healthcare. Understanding these distinctions helps stakeholders identify specific growth vectors and tailor product development to address distinct user requirements. This segmentation highlights technological preferences, application areas, and end-user profiles shaping market demand.
Product Type:
The market for veterinary chemistry analyzers is primarily differentiated by the level of automation and device portability, directly influencing workflow efficiency and deployment flexibility.
- Benchtop:These stationary systems offer high throughput and broad test menus, typically found in central laboratories or large animal hospitals. Demand for benchtop models remains strong in established diagnostic settings requiring comprehensive analytical capabilities for diverse sample volumes.
- Portable:Compact and lightweight, portable analyzers enable rapid point-of-care testing in mobile veterinary units, emergency clinics, and field settings. Their accelerating uptake is driven by the need for immediate results and improved convenience in delivering veterinary care.
- Fully Automated:These systems handle sample processing, analysis, and result reporting with minimal human intervention for maximum efficiency.
- Semi-Automated:Requiring manual steps for sample preparation or reagent loading, semi-automated analyzers balance cost-effectiveness with increased throughput.
Mature deployment sits with Benchtop models. Newer deployment is concentrated in Portable analyzers.
Technology:
The application focus of veterinary chemistry analyzers largely dictates the underlying analytical principles employed, which define their measurement capabilities for various diagnostic parameters.
- Photometry:This widely adopted technology measures the absorption or transmission of light through a sample to quantify analyte concentrations, forming the basis for many routine blood chemistry panels. Its versatility makes it a cornerstone in both benchtop and point-of-care systems.
- Electrochemistry:Utilizing electrical signals to measure ion concentrations and enzyme activity, electrochemistry is crucial for electrolytes, blood gases, and specific metabolic markers. Integration of this technology provides rapid and accurate results essential for critical care diagnostics.
- Turbidimetry:This method measures the cloudiness or turbidity of a sample to quantify analytes like proteins or immunoglobulins, often used in specialized assays.
- Potentiometry:Employing electrodes to measure electrical potential differences, potentiometry is commonly used for precise electrolyte measurements in biological fluids.
- Reflectance:This technology analyzes light reflected from a reagent-impregnated test strip, offering a simple, rapid method for urinalysis and blood tests.
Analytical precision and speed are driving the adoption of Electrochemistry, which is climbing the fastest in demand.
Application:
The customer type for veterinary chemistry analyzers varies significantly across different animal care settings, each requiring specific instrument features and throughput capabilities.
- Diagnostic Laboratories:These centralized facilities handle high volumes of samples, requiring high-throughput, fully automated analyzers with extensive test menus and robust data management systems. Significant volume is driven by referral cases and specialized testing.
- Veterinary Clinics:In-house testing capabilities are paramount for rapid diagnosis and treatment planning in general veterinary practices. The need for quick results for pre-surgical screening and urgent cases drives demand for compact, user-friendly systems.
- Research Institutes:Academic and commercial research facilities utilize these analyzers for studies on animal physiology, disease pathology, and drug development, often requiring specialized assays.
- Animal Health Centers:These facilities deploy analyzers for routine health checks, disease screening, and monitoring treatment efficacy.
Veterinary Clinics are gaining share fastest due to the push for immediate diagnostic insights, while Diagnostic Laboratories maintain established demand.
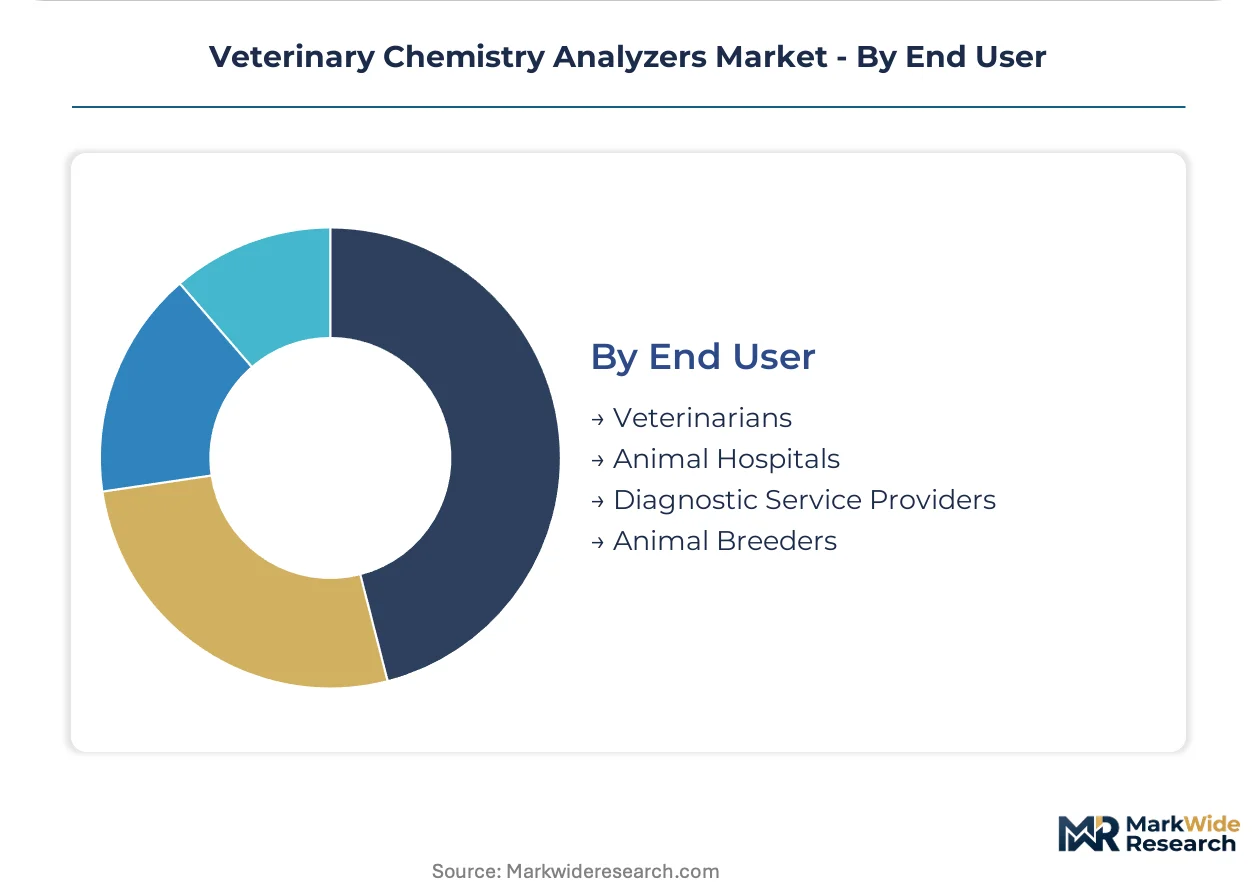
End User:
The volume of diagnostic tests performed by various end-users influences product design, pricing, and distribution channels for veterinary chemistry analyzers.
- Animal Hospitals:Large animal hospitals and corporate groups represent significant purchasers, investing in advanced, high-throughput systems for comprehensive in-house diagnostics. Their consolidated purchasing power drives demand for integrated solutions.
- Veterinarians:Individual practitioners and small clinics prioritize ease of use, cost-effectiveness, and rapid turnaround times for common diagnostic tests. Their purchasing decisions often hinge on budget constraints and immediate patient needs.
- Diagnostic Service Providers:These businesses offer specialized laboratory testing services to veterinary practices, requiring robust, scalable analyzer platforms to process large sample volumes efficiently.
- Animal Breeders:Breeders use chemistry analyzers for health screening, monitoring reproductive cycles, and early detection of diseases in their animals.
Investment by Animal Hospitals indicates the steepest expansion trajectory, while Veterinarians represent a broad, consistent base of users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for veterinary chemistry analyzers concentrates in developed markets with high pet ownership and significant spending on advanced veterinary care infrastructure. These regions drive investment in rapid, in-house diagnostic capabilities. The United States and Germany represent key areas for market expansion.
United States
High pet health expenditure drives demand for sophisticated in-house diagnostic tools across veterinary practices. The U.S. FDA's Center for Veterinary Medicine regulates instrument and reagent approvals for animal health products. Major veterinary hospital groups in urban centers like Dallas are integrating advanced analyzers for streamlined workflows and centralized data management.
Germany
Companion animal health spending supports the uptake of advanced diagnostic technologies within the German veterinary sector. The European Medicines Agency's CVMP provides regulatory oversight for veterinary medical devices and diagnostics. Research institutes in cities such as Munich focus on developing novel diagnostic assays for various animal diseases.
Japan
An aging pet population and increasing awareness of preventative care boost demand for routine health monitoring in Japan. The Ministry of Agriculture, Forestry and Fisheries (MAFF) oversees animal health regulations and standards. Veterinary clinics in the Kanto region are adopting portable analyzers for efficient point-of-care testing and rapid results.
Australia
High pet ownership rates contribute to sustained investment in veterinary diagnostic infrastructure across Australia. The Australian Pesticides and Veterinary Medicines Authority (APVMA) ensures product safety and efficacy for veterinary medical devices. Large animal hospitals in Sydney are centralizing diagnostic services with high-throughput benchtop systems.
United Kingdom
Significant discretionary spending on companion animals fuels demand for advanced diagnostic systems in the UK. The Veterinary Medicines Directorate (VMD) regulates veterinary medical devices and diagnostics to ensure quality. Corporate veterinary groups across London are implementing multi-vendor procurement strategies for consumables to gain flexibility.
Veterinary Chemistry Analyzers Market Key Industry Players
Portfolio diversification dominates the current landscape as companies seek to meet varied veterinary clinic needs and procurement preferences. The market exhibits a tiered structure, with established diagnostic solution providers competing alongside agile specialists. Strategic archetypes include integrated closed-system manufacturers, open-platform instrument providers, and broad diagnostic portfolio developers. Technology development and strategic partnerships are common competitive moves to enhance product offerings and market reach.
Integrated diagnostic solution providers like the US-based IDEXX Laboratories, Inc. represent a significant market archetype, often leveraging proprietary systems for comprehensive in-house testing. Another US-based entity, Zoetis Inc., exemplifies companies expanding their broader diagnostic portfolios to offer wider platform compatibility across various instrumentation and services. Heska Corporation, also based in the US, anchors the segment specializing in open-platform analyzers, providing clinics with greater flexibility in sourcing reagents and consumables and challenging traditional closed-system models.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| Zoetis Inc. |
| Heska Corporation |
| Randox Laboratories Ltd. |
| HORIBA Medical |
| Chengdu Seamaty Technology Co., Ltd. |
| DiaSys Diagnostic Systems GmbH |
| Abaxis Inc. |
| URIT Medical Electronic Co. Ltd. |
Cost & Logistics Intelligence
Regulatory compliance with ISO 13485 standards gates qualified supply for veterinary chemistry analyzers, influencing premium-tier pricing for validated instruments and reagents. This mandate ensures device reliability and market access, impacting manufacturer costs.
Pricing Analysis
Volume-driven sales of proprietary consumables yield high margins for integrated providers, contrasting with lower-margin instrument sales. Pricing stratifies across premium, standard, and economy tiers based on brand reputation and instrument capabilities. Downward pricing pressure on reagents stems from large hospital groups demanding multi-vendor sourcing. Small veterinary practices exhibit high price sensitivity, while large animal hospitals prioritize integrated solutions.
Supply Chain Analysis
Single-source vulnerability for proprietary reagents sits with integrated diagnostic solution providers like IDEXX Laboratories. Component manufacturing for analyzers draws from global hubs, including China for electronics and Germany for precision instruments. Cold chain logistics for liquid reagents pose a significant structural risk, particularly for mobile and rural practitioners. Distribution runs through direct sales channels to large animal hospitals and through distributors to smaller veterinary clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is in a technology-transition phase, as microfluidics technology displaces legacy benchtop systems for rapid, point-of-care diagnostics.
For Market Incumbents: Lock in existing customer bases by enhancing software integration with practice management systems and expanding test menus. Develop broader compatibility across platforms to counter multi-vendor procurement strategies from large hospital groups. Invest in R&D for next-generation microfluidics to stay ahead of emerging point-of-care technologies. This strategy addresses the threat of supplier commoditization and strengthens ecosystem loyalty.
For New Entrants and Emerging Players: A price-point gap exists between premium, feature-rich analyzers and basic, cost-effective options, creating an entry point for new players. Target underserved small veterinary practices and mobile units with affordable, semi-automated portable systems. Offer subscription-based models for reagent rental or pay-per-test agreements to lower upfront capital expenditure. Focus on validated reagent panels for exotic animals, addressing a high-value niche segment.
For Investors and Strategic Acquirers: Widespread adoption of multi-vendor procurement by large veterinary hospital groups is the leading indicator that traditional closed-system models are eroding. The market demonstrates long-term viability, driven by sustained pet health expenditure and demand for rapid diagnostics. Acquire agile specialists in open-platform analyzers or advanced software integration capabilities. Monitor regulatory changes, particularly regarding data standardization, as a key signal for future market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Integration Enhancement | Seamless data flow improves clinic efficiency and centralizes patient records for veterinarians. |
| Open-Platform Analyzer Development | Greater flexibility in reagent sourcing attracts corporate veterinary groups seeking cost control. |
| Subscription Model Launch | Lower upfront costs expand market access for budget-sensitive small veterinary practices. |
| Microfluidics R&D Investment | Compact, rapid point-of-care devices improve diagnostic speed in mobile veterinary services. |
| Regulatory Compliance Expansion | Adherence to U.S. FDA and European Medicines Agency standards ensures global market access. |
Research Approach
Multi-period observation of pet health expenditure, diagnostic test volumes, and technology adoption rates anchored the trend analysis, supplemented by interviews. Primary research involved discussions with veterinary clinic owners, diagnostic lab managers, instrument manufacturers, and regulatory affairs specialists. Secondary validation drew from industry association reports, government health statistics, scientific publications, and company financial filings. This approach ensured robust bottom-up and top-down triangulation of market insights.
An input-output matrix structured the quantitative forecast, modeling market dynamics across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth patterns and projected technology adoption. Key industry-specific inputs included pet ownership rates and veterinary visit frequency.
Inputs from public financial disclosures and industry reports were available through the study window; gaps in granular regional spending data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Unforeseen regulatory changes or economic downturns affecting pet care spending represent key risk factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
HIV Diagnostics Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Creatine Kinase Reagent Market
Diagnostics
Vision Screeners Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
FISH Probe Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market