
 Global Automated Analyzers Market | 2026-2036
Global Automated Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Analyzers Market Analysis
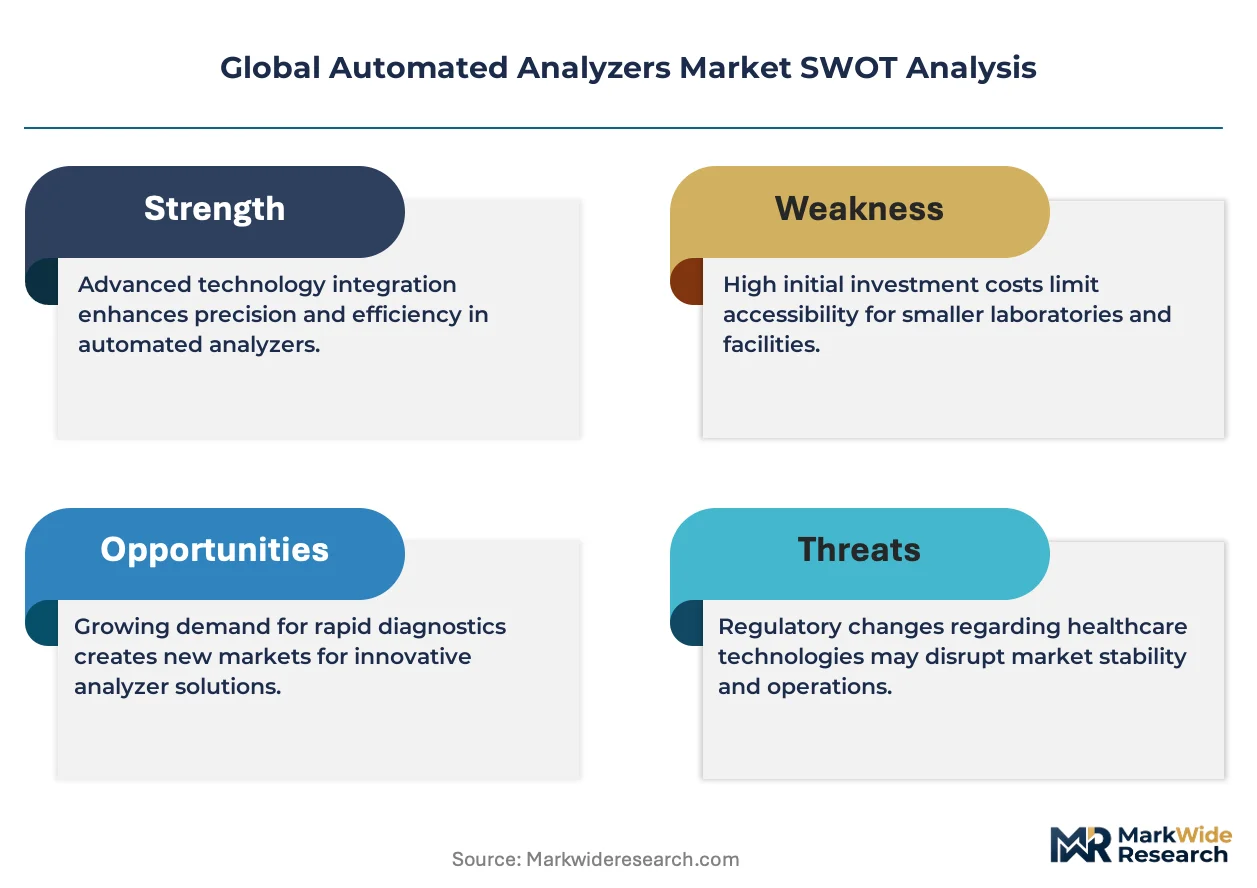
The EU In Vitro Diagnostic Regulation is decoupling legacy product lines from the European market, forcing manufacturers to absorb recertification costs or abandon installed bases. Danaher Corporation leverages its Beckman Coulter diagnostics portfolio to sustain service revenue from existing clinical chemistry installations while navigating compliance timelines. Abbott Laboratories anchors its competitive position through immunoassay analyzer specialization, particularly in high-throughput cardiac biomarker testing workflows.
Automated analyzers comprise electromechanical systems that process biological specimens through controlled fluidic pathways, applying optical, electrochemical, or fluorescent detection methods to quantify analytes with throughput rates exceeding 1,000 tests per hour. These instruments serve diagnostic laboratories by standardizing reproducibility, reducing manual pipetting errors, and enabling continuous batch processing of blood, urine, and other sample matrices. Clinical analyzers and immunoassay analyzers command the dominant share of installed base value, while hematology analyzers face margin compression from Chinese domestic manufacturers. End-user demand tilts toward diagnostic laboratories over hospital core labs, as outsourcing trends consolidate testing volume into centralized reference facilities.
FDA premarket notification requirements for Class II in vitro diagnostic devices shape product development timelines and predicate device selection for US market entrants, while China's NMPA enforces GB standard compliance and clinical trial data submission for imported analyzer registrations. The EU MDR and IVDR frameworks collectively extend conformity assessment durations, favoring manufacturers with established notified body relationships and robust quality management systems. Stakeholders must monitor regulatory divergence between FDA's streamlined 510(k) modernization initiative and the EU's intensified clinical evidence expectations when allocating product development resources across geographic markets.
Market Dynamics
The EU In Vitro Diagnostic Regulation is forcing manufacturers to recertify legacy platforms, absorbing substantial compliance costs while creating competitive separation between firms with established notified body relationships and those without. This regulatory pressure is compressing margins for mid-tier suppliers and accelerating consolidation across European diagnostic markets.
Growth Catalysts
- IVDR Recertification Mandates:The EU In Vitro Diagnostic Regulation compels laboratories to replace non-compliant instruments, generating replacement demand for fully automated immunoassay systems in Germany, France, and Italy.
- Cardiac Biomarker Testing Expansion:Hospital core labs are expanding high-sensitivity troponin workflows, requiring continuous batch processing capabilities that manual methods cannot match.
- China's Tier-One Hospital Procurement:Government centralized purchasing programs in Beijing, Shanghai, and Guangzhou are consolidating biochemistry analyzer deployments into regional reference laboratories.
Market Restraints
- IVDR Conformity Assessment Duration:Extended notified body review timelines are delaying product launches by 18-36 months, freezing R&D returns for manufacturers without pre-existing EU quality management certifications.
- Optical Component Supply Concentration:Precision photomultiplier tubes and laser diodes concentrate among Japanese and German component suppliers, exposing analyzer manufacturers to single-source fragility.
- Fluorescent Reagent Cost Volatility:Rare earth elements and specialized fluorophores face price instability driven by Chinese export quotas on lanthanide processing.
Strategic Opportunities
- Point-of-Care Molecular Integration:Convergence of PCR amplification with electrochemical detection is electrifying near-patient testing workflows, enabling decentralized infectious disease diagnostics outside hospital core labs.
- India's Reference Laboratory Buildout:The country's national pharmaceutical regulator is streamlining CDSCO import licenses for analyzers, opening private diagnostic chains in Mumbai, Delhi, and Bangalore to automated platform adoption.
- AI-Assisted Result Interpretation:Machine learning algorithms flagging anomalous patterns in hematology scattergrams are reducing manual slide review rates and differentiating premium analyzer tiers.
Industry Challenges
- Multidisciplinary Field Service Engineering:Maintenance of fluidic, optical, and software subsystems demands hybrid skill sets spanning mechanical engineering, biochemistry, and IT networking that training pipelines have not scaled to meet.
- Legacy LIS Integration Complexity:Hospital information system vendors use proprietary data formats, forcing analyzer manufacturers to maintain costly middleware development for each major LIS platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Analyzers Market |
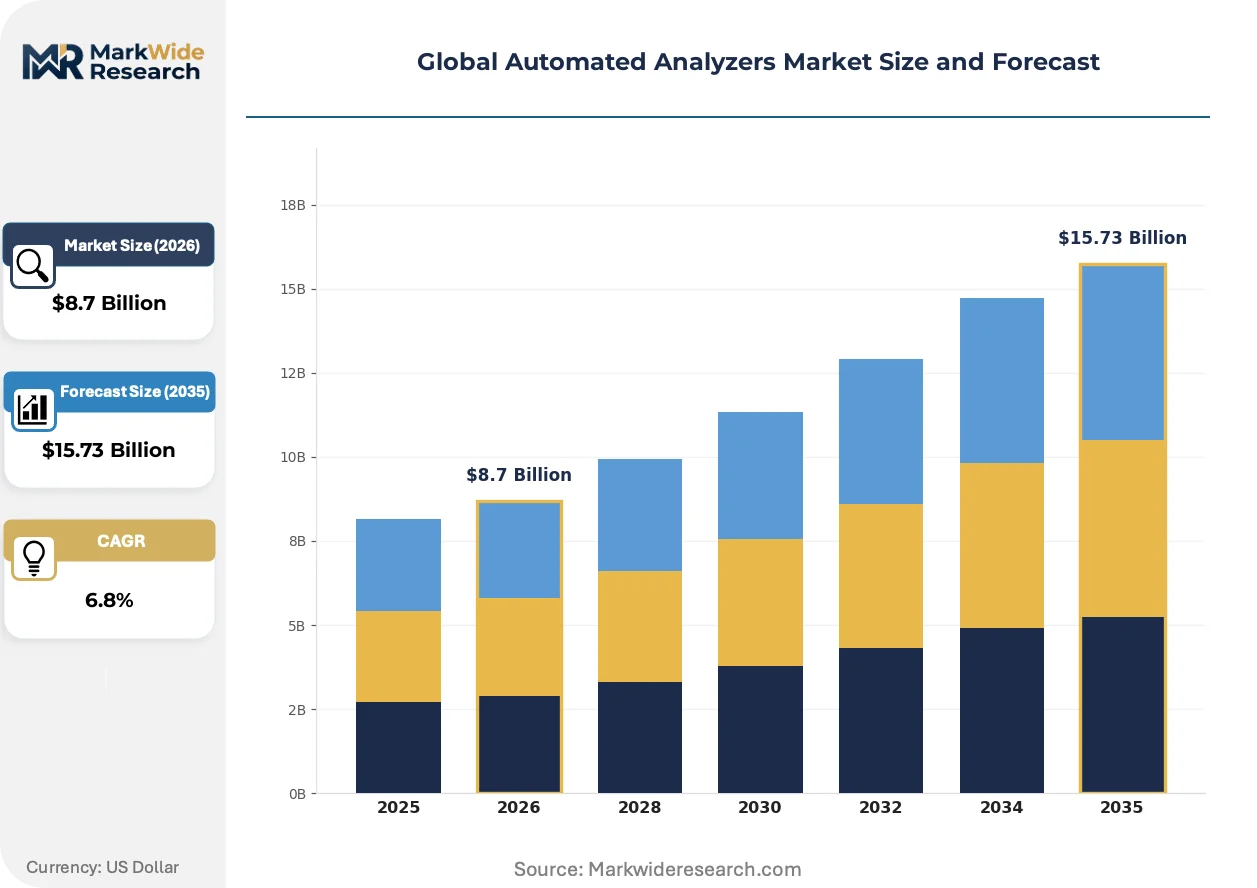
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Analyzers, Biochemical Analyzers, Hematology Analyzers, Immunoassay Analyzers End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Technology: Electrochemical, Optical, Colorimetric, Fluorescent Application: Blood Testing, Urinalysis, Disease Screening, Quality Control |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Becton Dickinson, Sysmex Corporation, Agilent Technologies, Mindray Medical International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Analyzers Market Emerging Trajectories
Automated analyzer development is pivoting toward modular architectures that decouple sample processing from detection modules, allowing laboratories to upgrade capabilities without full instrument replacement. This shift is compressing product lifecycles and reshaping vendor service revenue models.
Microfluidic cartridge systems integrating pre-stored reagents with disposable fluidic pathways are electrifying decentralized testing workflows. Rural and outpatient clinics in the United States are adopting these platforms to reduce sample transport logistics. The technology is enabling diagnostic networks to extend reach without capital-intensive core lab infrastructure.
The EU Medical Device Regulation and In Vitro Diagnostic Regulation collectively extend clinical evidence requirements for predicate device claims. Manufacturers must now generate prospective performance studies rather than relying on literature-based equivalence. High-throughput chemistry analyzers face the steepest compliance burden, with several legacy platforms withdrawn from European markets rather than recertified.
Consolidated procurement through group purchasing organizations is compressing vendor sales cycles and standardizing specification requirements across multi-hospital networks. Diagnostic laboratories in the United States are unbundling after-sales service contracts from instrument purchases, pressuring manufacturer service margins. This behavioral shift is most pronounced in Texas and Florida, where private equity-backed laboratory rollups dominate purchasing decisions.
Global Automated Analyzers Market Segmentation
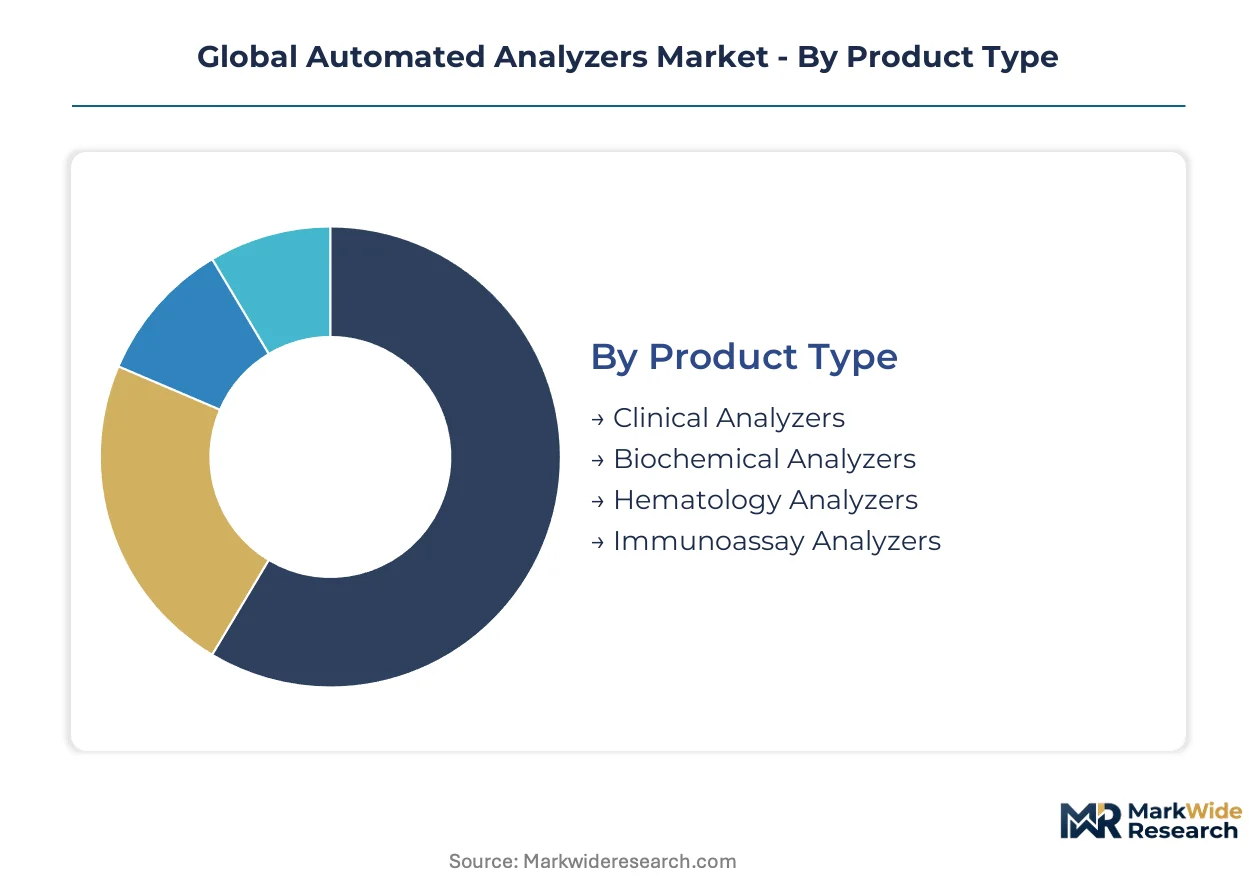
Segmentation in automated analyzers reveals how purchasing decisions bifurcate between throughput-maximizing reference laboratories and precision-focused clinical settings. Product architecture, detection methodology, and end-user workflow requirements create distinct competitive battlegrounds with divergent margin profiles.
Product Type:
Procurement committees prioritize throughput specifications and reagent flexibility when selecting across analyzer categories, with total cost of ownership calculations extending 7-10 years.
- Clinical Analyzers:These systems integrate multiple detection modalities into unified platforms processing 800-1,200 tests per hour. German university hospitals are replacing aging modular systems with consolidated clinical chemistry platforms to reduce maintenance contracts and floor space requirements.
- Immunoassay Analyzers:Specialized systems employing chemiluminescent detection achieve femtomolar sensitivity for cardiac troponin and endocrine panels. China's tier-one hospital networks are centralizing immunoassay workloads into regional reference laboratories, driving demand for continuous batch processing capabilities.
- Biochemical Analyzers:Photometric and ion-selective electrode systems dominate routine metabolic panel testing in high-volume settings.
- Hematology Analyzers:Impedance and flow cytometry-based cell counters face margin compression from domestic Chinese manufacturers.
Clinical analyzers lead on scale; immunoassay analyzers lead on momentum.
End User:
Capital deployment cycles and staffing models create divergent purchasing behaviors across customer types, with outsourcing trends consolidating volume into specialized operators.
- Diagnostic Laboratories:Reference facilities operate 24/7 batch processing workflows requiring 99.5% uptime guarantees and automated sample handling. Private equity-backed laboratory rollups in Texas and Florida are unbundling service contracts from instrument purchases, pressuring vendor margins.
- Hospitals:Core laboratories demand STAT processing capabilities and seamless LIS integration for emergency department workflows. US health systems are expanding fully automated immunoassay installations to meet rising cardiac biomarker test volumes without proportional staffing increases.
- Research Institutions:Academic medical centers prioritize methodological flexibility and custom assay development capabilities.
- Home Care:Point-of-care settings drive demand for cartridge-based systems with minimal operator training requirements.
Diagnostic laboratories dominate installed base value; home care is climbing the fastest.
Technology:
Detection modality selection determines reagent cost structures, calibration frequency, and regulatory classification pathways for manufacturers.
- Optical:Photometric and nephelometric systems leveraging monochromatic light sources provide cost-effective quantification for routine chemistry panels. Japanese and German suppliers concentrate precision photomultiplier tube production, creating single-source fragility for analyzer manufacturers.
- Fluorescent:Time-resolved fluorometry and chemiluminescence achieve lowest detection limits for high-sensitivity troponin and infectious disease markers. Chinese export quotas on lanthanide processing generate rare earth element price volatility for specialized fluorophores.
- Electrochemical:Ion-selective electrodes and amperometric sensors offer maintenance advantages for electrolyte and glucose monitoring.
- Colorimetric:Classical absorbance-based methods retain cost competitiveness for emerging market installations.
Optical technology leads on scale; fluorescent detection leads on momentum.
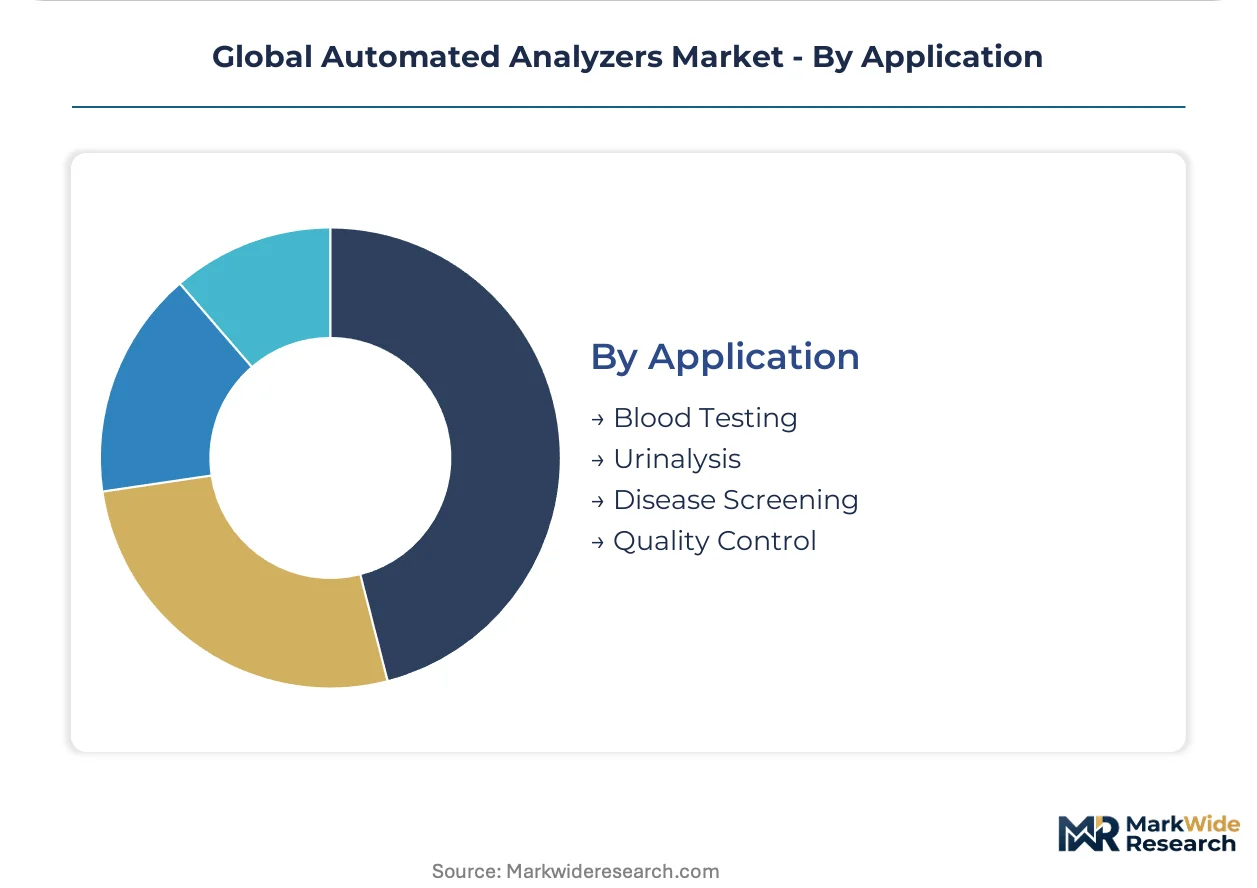
Application:
Test menu breadth and regulatory clearance requirements shape product development resource allocation across clinical use cases.
- Blood Testing:Serum and plasma analysis commands the largest reagent revenue stream, spanning metabolic panels to specialized protein assays. EU IVDR recertification mandates are forcing replacement of legacy clinical chemistry platforms in Germany, France, and Italy.
- Disease Screening:Population-scale testing for infectious disease and cancer markers requires high-throughput batch processing with automated result flagging. India's CDSCO import license streamlining is opening private diagnostic chains in Mumbai, Delhi, and Bangalore to automated platform adoption.
- Urinalysis:Automated microscopy and chemistry strip reading consolidates manual workflow steps in high-volume settings.
- Quality Control:Manufacturing and pharmaceutical applications demand traceable calibration and audit documentation.
Blood testing leads on scale; disease screening leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated analyzer technology originated in post-war Germany and Japan, where precision engineering capabilities converged with clinical chemistry advances. These foundations established manufacturing expertise that now distributes across five strategic national markets.
United States
Hospital core labs in Texas and Florida are consolidating cardiac biomarker testing into high-throughput immunoassay workflows. FDA premarket notification requirements for Class II in vitro diagnostic devices shape product development timelines for domestic and imported systems alike. Private equity-backed laboratory rollups in Houston and Miami are unbundling service contracts from instrument purchases, pressuring vendor margins.
Germany
University hospitals in Bavaria and Baden-Württemberg are replacing aging modular systems with consolidated clinical chemistry platforms. The EU In Vitro Diagnostic Regulation compels recertification of legacy platforms, generating replacement demand in Berlin and Frankfurt reference laboratories. German university hospitals prioritize throughput specifications and reagent flexibility in procurement committees.
China
Tier-one hospital networks in Beijing, Shanghai, and Guangzhou are centralizing biochemistry analyzer deployments through government procurement programs. The NMPA enforces GB standard compliance and clinical trial data submission for imported analyzer registrations. Domestic manufacturers in Shenzhen and Hangzhou are compressing margins for hematology analyzer imports.
India
Private diagnostic chains in Mumbai, Delhi, and Bangalore are expanding automated platform adoption as CDSCO streamlines import licenses. The country's national pharmaceutical regulator is reducing regulatory friction for reference laboratory buildouts. Diagnostic networks in Maharashtra and Karnataka are consolidating testing volume into centralized facilities.
Japan
Precision photomultiplier tube and laser diode suppliers in Osaka and Nagoya create single-source fragility for analyzer manufacturers globally. METI industrial policy supports domestic production of optical components for diagnostic instrumentation. Japanese component concentration exposes global supply chains to geographic concentration risk.
Global Automated Analyzers Market Vendor Landscape
The competitive structure tilts toward diversified life science conglomerates with diagnostics divisions. Consolidation among reference laboratory customers is compressing vendor sales cycles and standardizing specification requirements. Two strategic archetypes dominate: integrated diagnostics platforms spanning chemistry and immunoassay modalities, and specialized hematology or molecular testing specialists. M&A activity targets notified body relationships for EU IVDR compliance, while geographic expansion focuses on India's emerging reference laboratory segment.
Among US-based diversified health science conglomerates, Danaher Corporation and Abbott Laboratories exemplify contrasting strategic positions. Danaher leverages its Beckman Coulter diagnostics portfolio to sustain service revenue from existing clinical chemistry installations. Abbott anchors competitive positioning through immunoassay analyzer specialization. Swiss-based Roche Diagnostics and German-rooted Siemens Healthineers occupy positions emphasizing European regulatory navigation capabilities. Japanese precision instrumentation heritage is represented by Sysmex Corporation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Becton Dickinson |
| Sysmex Corporation |
| Agilent Technologies |
| Mindray Medical International Limited |
| Others |
Supply Flow & Price Mechanics
Reference laboratory rollups in Texas and Florida operate on unbundled service-contract models that strip instrument purchases from recurring revenue streams, compressing vendor margins and forcing manufacturers toward modular upgrade architectures rather than full-system replacements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the installed base by throughput specification and reagent flexibility. Price differentiation hinges on IVDR certification status and continuous batch-processing capability, with premium tiers commanding service-integrated contracts. Cost compression in economy-tier hematology analyzers is intensifying because domestic Chinese manufacturers in Shenzhen and Hangzhou are flooding tier-two hospital procurement channels. Diagnostic laboratories in Germany and France show lowest price sensitivity due to replacement mandates, while India's emerging private diagnostic chains exhibit acute cost consciousness.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for precision photomultiplier tubes and laser diodes, while distributor networks serve mid-tier analyzer manufacturers with lower volume requirements. Component manufacturing concentrates in Japan, Germany, and China, with Osaka and Nagoya suppliers anchoring optical subsystem production. Raw material dependencies include rare earth lanthanides for fluorescent reagents, precision-machined fluidic manifolds, and specialized electronic substrates. Single-source vulnerability in Japanese photomultiplier tube supply exposes global analyzer production to geographic concentration risk. Distribution runs through regional service organizations that maintain field engineering capabilities for fluidic, optical, and software subsystem maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Automated Analyzers Market represents a late-cycle quality story where EU IVDR recertification mandates and cardiac biomarker workflow expansion are elevating demand toward premium-tier immunoassay platforms with validated clinical evidence packages.
For Market Incumbents: Acquire notified body relationships and established EU quality management certifications to accelerate IVDR conformity assessment timelines. Consolidate middleware development capabilities for legacy LIS integration to defend service revenue against unbundling pressure from private equity-backed laboratory rollups. Backward integration into precision optical component sourcing mitigates single-source fragility from Japanese suppliers. For New Entrants and Emerging Players: Enter via India's streamlined CDSCO import license pathway to capture reference laboratory buildout in Mumbai, Delhi, and Bangalore. Target disease screening applications in decentralized settings where microfluidic cartridge systems reduce capital barriers. Partner with regional diagnostic chains on outcome-based service contracts rather than capital equipment sales. For Investors and Strategic Acquirers: Diversified life science conglomerates with diagnostics divisions are the most active acquirer in this space, seeking EU regulatory navigation capabilities and installed base service revenue. Long-term viability rests on convergence toward AI-assisted result interpretation and point-of-care molecular integration. Monitor IVDR recertification completion rates among mid-tier European manufacturers as consolidation inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Recertification Acceleration | Notified body pre-submissions in Berlin and Frankfurt compress conformity assessment timelines for legacy platform replacements. |
| Modular Architecture Development | Decoupled sample processing and detection modules extend instrument lifecycles and reshape vendor service revenue models. |
| AI-Assisted Result Interpretation | Machine learning algorithms flagging hematology scattergram anomalies reduce manual slide review rates in high-throughput settings. |
| Point-of-Care Molecular Integration | PCR-electrochemical convergence enables decentralized infectious disease diagnostics outside hospital core lab infrastructure. |
| India Reference Laboratory Partnership | CDSCO streamlining opens private diagnostic chains in Maharashtra and Karnataka to automated platform adoption. |
Methodological Framework
Multiple input streams — primary interviews with biomedical engineers and GPO contracts managers, secondary validation through FDA 510(k) filings and EMA IVDR submission databases, and customs trade data — were reconciled to construct bottom-up and top-down triangulation. Conversations with hospital purchasing committees in Texas and Florida, field service engineering directors, and regulatory affairs leads at notified bodies informed competitive positioning assessments. SEC 10-K diagnostics segment disclosures and hospital procurement databases provided installed base and revenue segmentation anchors.
Historical shipment data cross-referenced against panel input from reference laboratory operators shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, detection methodology, end-user workflow requirements, and regional regulatory cluster. CAGRs were derived from instrument replacement cycles, reagent revenue per installed unit, and test volume expansion in cardiac biomarker and infectious disease screening applications. Reagent cost volatility in fluorescent detection and optical component supply concentration informed scenario-weighted outputs.
Inputs from EMA IVDR submission trackers and NMPA registration databases were available through the study window; gaps in real-time notified body queue transparency introduce uncertainty bands around European replacement demand timing. Forecasts reflect documented assumptions regarding IVDR enforcement consistency and tier-one hospital procurement continuity in China. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Global Cell Analysis Instruments Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Orbital Shakers Market
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
North America Laboratory Hoods and Enclosure Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Latin America Laboratory Equipment and Disposables Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market