
 Australia Magnetic Resonance Imaging Market | 2026-2036
Australia Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Magnetic Resonance Imaging Market Outlook
The TGA's strengthened medical device conformity assessment pathways is repositioning procurement standards across Australian healthcare networks. Siemens Healthineers leverages its established service infrastructure to sustain long-term hospital contracts in major capital cities. GE Healthcare anchors its competitive stance through localized technical support and training programs for radiology departments. Canon Medical Systems Corporation specializes in high-field system configurations that align with tertiary referral center requirements.
Magnetic resonance imaging deploys superconducting magnets generating field strengths from 1.5 to 7 Tesla, utilizing radiofrequency coils and gradient systems to produce detailed soft-tissue images without ionizing radiation; the technology serves primarily for neurological, oncological, and musculoskeletal diagnosis where tissue contrast resolution exceeds computed tomography capabilities. Closed MRI systems dominate installed base volumes due to superior signal-to-noise ratios and established reimbursement pathways, while functional MRI segments attract growing research funding from neuroimaging consortia seeking real-time cortical mapping capabilities. High-field MRI technology captures premium margin pools as academic medical centers prioritize 3 Tesla platforms for advanced spectroscopy and diffusion tensor applications.
TGA medical device regulations and the Australian Radiation Protection and Nuclear Safety Agency (ARPANSA) safety standards jointly determine electromagnetic field exposure limits and equipment licensing protocols for clinical MRI installations. The Medical Technology Association of Australia (MTAA) code of practice further shapes supplier conduct regarding maintenance documentation and spare parts availability commitments. Stakeholders must monitor TGA's alignment with International Electrotechnical Commission (IEC) 60601-2-33 revisions to anticipate compliance cost shifts and potential equipment retirement timelines.
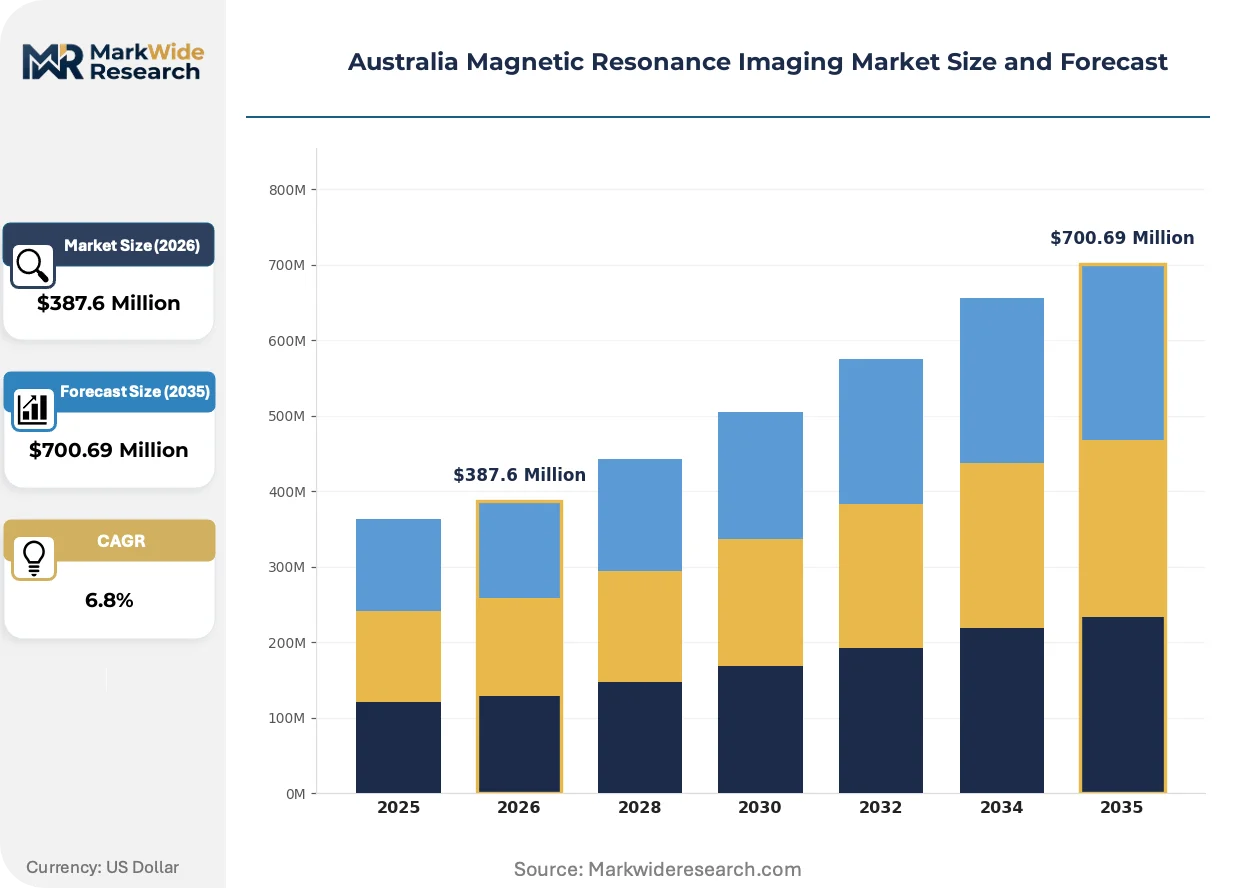
Market Dynamics
The Therapeutic Goods Administration's 2024 medical device framework revisions are compressing equipment certification timelines while expanding electromagnetic field exposure documentation requirements, forcing hospital procurement committees to front-load compliance verification into vendor selection criteria.
Growth Catalysts
- ARPANSA Safety Standard Updates:The Australian Radiation Protection and Nuclear Safety Agency's tightened electromagnetic field monitoring protocols are mandating infrastructure upgrades across Queensland and Western Australia hospital networks, creating replacement demand for aging 1.5 Tesla systems.
- Neuroimaging Research Consortia:Functional MRI applications for real-time cortical mapping are attracting National Health and Medical Research Council funding, driving 3 Tesla platform procurement at tertiary referral centers in Melbourne and Sydney.
- Metropolitan Hospital Network Consolidation:New South Wales and Victoria health district mergers are standardizing imaging procurement across previously independent facilities, concentrating volume purchasing power with preferred equipment vendors.
Market Restraints
- Helium Supply Concentration:Superconducting magnet cooling depends on liquid helium imports from Qatar and the United States, exposing operators to price volatility and delivery disruptions that extend equipment commissioning timelines.
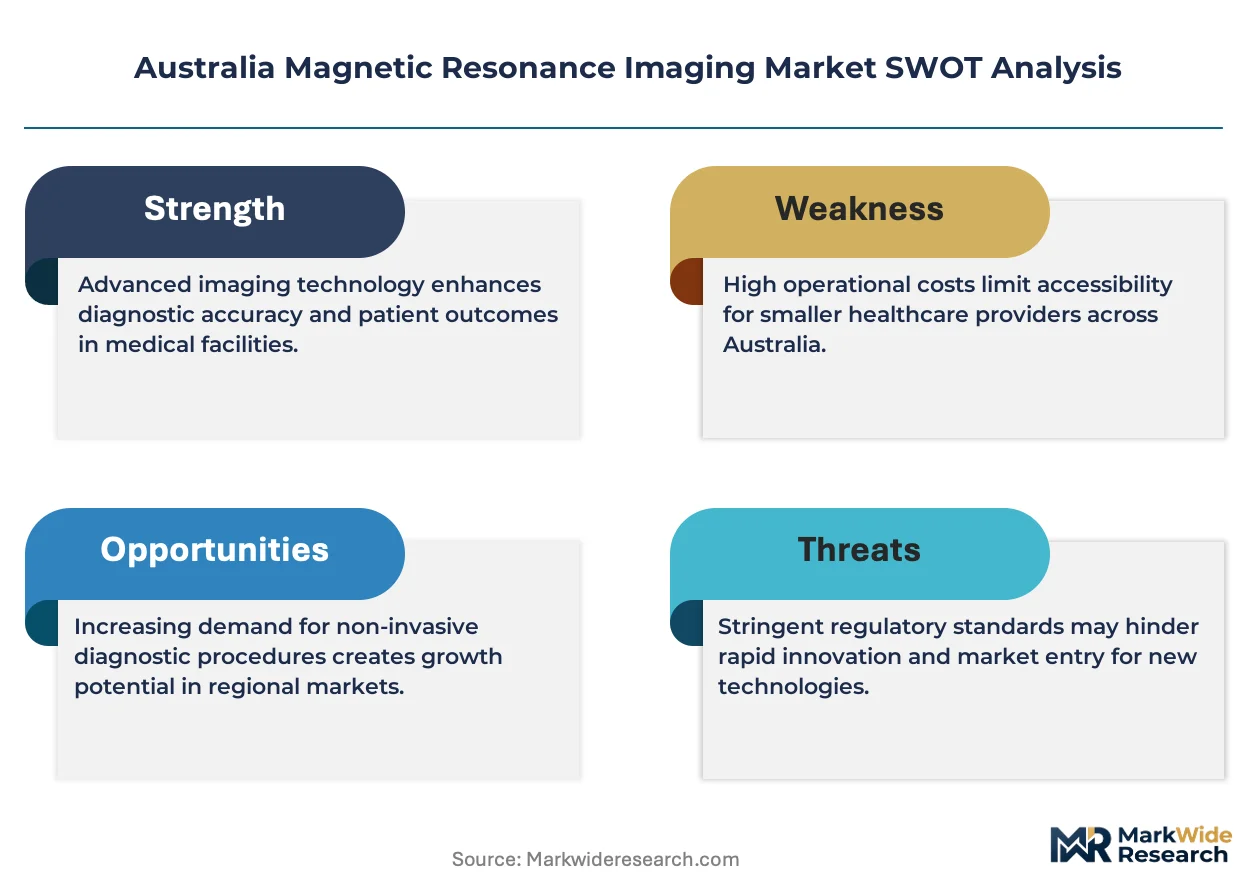
- TGA Conformity Assessment Costs:The Therapeutic Goods Administration's expanded technical documentation requirements for imported imaging equipment have increased pre-market approval expenditures, disproportionately affecting mid-tier regional hospitals with constrained capital budgets.
- Computed Tomography Substitution:Advanced multi-detector CT systems with spectral imaging capabilities are capturing musculoskeletal and emergency diagnostic volumes where tissue contrast requirements permit ionizing radiation exposure.
Strategic Opportunities
- Regional Queensland Penetration:Townsville, Cairns, and Mackay hospital networks operate below national MRI scanner density benchmarks, presenting first-mover positioning for vendors establishing localized service infrastructure.
- Artificial Intelligence Integration:Machine learning-based scan sequence optimization and automated lesion detection algorithms are converging with high-field platforms, enabling throughput gains that justify premium equipment pricing at high-volume metropolitan sites.
- Mobile MRI Deployment:Trailer-mounted 1.5 Tesla systems are penetrating rural Victoria and South Australia through leasing models that circumvent permanent installation capital requirements while addressing geographic access inequities.
Industry Challenges
- Specialized Technician Scarcity:Radiographer training programs produce insufficient graduates with magnetic resonance physics specialization, forcing hospital networks to compete for experienced operators through salary premiums that compress equipment lifecycle cost models.
- Legacy System Integration Complexity:PACS connectivity and radiology information system interoperability requirements extend installation timelines for replacement scanners, delaying revenue recognition and complicating equipment retirement planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Magnetic Resonance Imaging Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Technology: High-Field MRI, Low-Field MRI, Ultra-High-Field MRI, Multi-Parametric MRI Application: Oncology, Neurology, Cardiology, Musculoskeletal |
| Companies Covered | Canon Medical Systems Corporation, Esaote SpA, Siemens Healthineers, Sonologic Inc, United Imaging Healthcare Co Ltd, GE Healthcare, Fujifilm Holdings Corporation, Hyperfine, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Magnetic Resonance Imaging Market Strategic Shifts
Artificial intelligence-enabled workflow automation is compressing scan duration parameters while expanding diagnostic protocol standardization across Australian hospital networks, fundamentally altering equipment utilization economics and procurement evaluation criteria.
Compressed sensing reconstruction algorithms are overtaking conventional Fourier transform methods in clinical deployment. These mathematical techniques enable diagnostic-quality imaging from substantially reduced k-space sampling, cutting patient table time by thirty to fifty percent at high-throughput Sydney and Melbourne facilities. The technology is overtaking legacy sequence designs as the default configuration in new 3 Tesla platform tenders, compressing competitive differentiation around raw magnet specifications.
The Therapeutic Goods Administration's alignment with IEC 60601-2-33 fourth edition electromagnetic compatibility standards is mandating expanded shielding documentation and modified radiofrequency coil certification pathways. Equipment suppliers must now submit expanded electromagnetic field emission mapping data prior to market authorization, extending pre-approval timelines by four to six months. High-field system categories face the most pronounced compliance burden, with 7 Tesla research platforms requiring additional site-specific safety dossiers that delay academic medical center installations.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchase agreements, negotiating standalone maintenance terms with third-party technical service providers. This behavioral shift disrupts manufacturer-captive service revenue models and compresses multi-year contract values, particularly visible in New South Wales public hospital tender processes where independent service organization qualifications now receive weighted evaluation scoring. The pattern is fragmenting vendor-customer relationships and accelerating price transparency across metropolitan Australian healthcare networks.
Australia Magnetic Resonance Imaging Market Segmentation
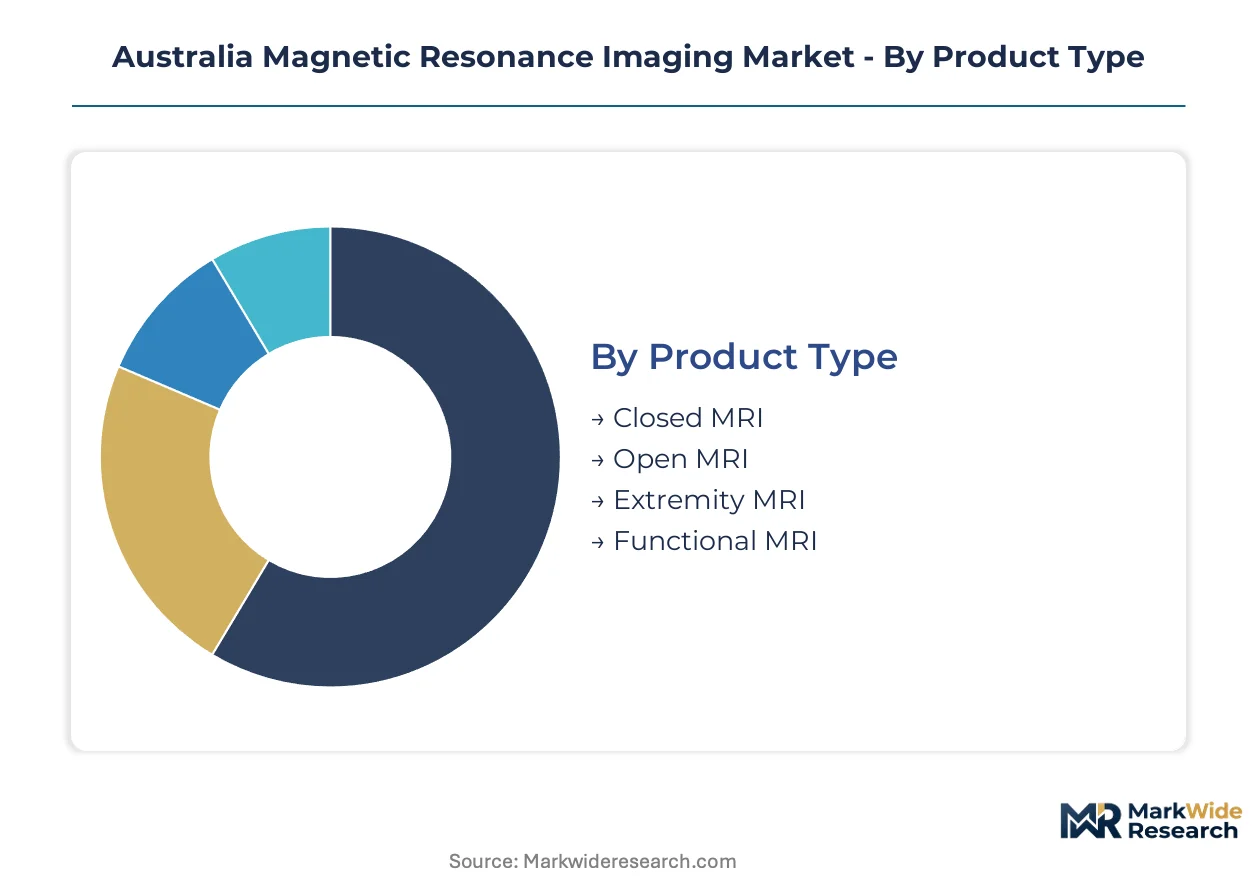
Equipment replacement cycles across New South Wales and Victoria hospital networks are fragmenting procurement patterns by technical specification and clinical use case. Understanding how scanner configurations align with infrastructure constraints and regulatory requirements enables targeted positioning for vendor service contracts.
Product Type:
Replacement demand from aging 1.5 Tesla installations is driving differential upgrade pathways across metropolitan and regional hospital networks.
- Closed MRI:Superconducting cylindrical bore designs generate field strengths from 1.5 to 3 Tesla with superior signal-to-noise ratios. Sydney and Melbourne tertiary centers prioritize these systems for high-throughput neurology and oncology diagnostics where image resolution requirements are non-negotiable.
- Open MRI:Permanent magnet or resistive electromagnet configurations eliminate enclosed bore constraints, accommodating claustrophobic patients and bariatric cases. Queensland regional hospitals are expanding procurement of these systems where patient comfort considerations override raw performance specifications.
- Extremity MRI:Dedicated limb-focused scanners with compact footprints and lower field strengths serve orthopedic clinics and sports medicine facilities.
- Functional MRI:Blood-oxygen-level-dependent imaging capabilities enable real-time cortical mapping for neurosurgical planning and research applications.
Volume placements concentrate in Closed MRI; the faster expansion belongs to Functional MRI.
End User:
Capital allocation patterns diverge sharply between public hospital procurement committees and private diagnostic operators.
- Hospitals:Public health district mergers in New South Wales and Victoria are consolidating purchasing authority across previously independent facilities, enabling volume discounts on 3 Tesla platform acquisitions.
- Diagnostic Centers:Independent imaging operators in Brisbane and Perth metropolitan corridors are deploying 1.5 Tesla systems through equipment leasing arrangements that minimize upfront capital exposure.
- Research Institutions:University-affiliated medical centers in Melbourne and Sydney are securing National Health and Medical Research Council funding for 7 Tesla research-dedicated installations.
- Imaging Clinics:Private radiology practices are expanding mobile MRI service models into rural Victoria and South Australia.
Procurement volume clusters at Hospitals; Research Institutions are climbing the fastest.
Technology:
Field strength specifications determine reimbursement eligibility and clinical application scope across Australian healthcare networks.
- High-Field MRI:3 Tesla platforms dominate new installations at academic medical centers where advanced spectroscopy and diffusion tensor imaging justify premium capital outlays. TGA electromagnetic field documentation requirements are extending pre-approval timelines for these systems.
- Low-Field MRI:Sub-1 Tesla permanent magnet systems serve point-of-care musculoskeletal applications and veterinary markets where infrastructure constraints prohibit cryogenic cooling systems.
- Ultra-High-Field MRI:7 Tesla research platforms require ARPANSA site-specific safety dossiers and specialized electromagnetic shielding that delay commissioning.
- Multi-Parametric MRI:Integrated diffusion-weighted, dynamic contrast-enhanced, and spectroscopic sequences are standardizing prostate and breast cancer staging protocols.
Installed base tilts toward High-Field MRI; Ultra-High-Field MRI is gaining share fastest.
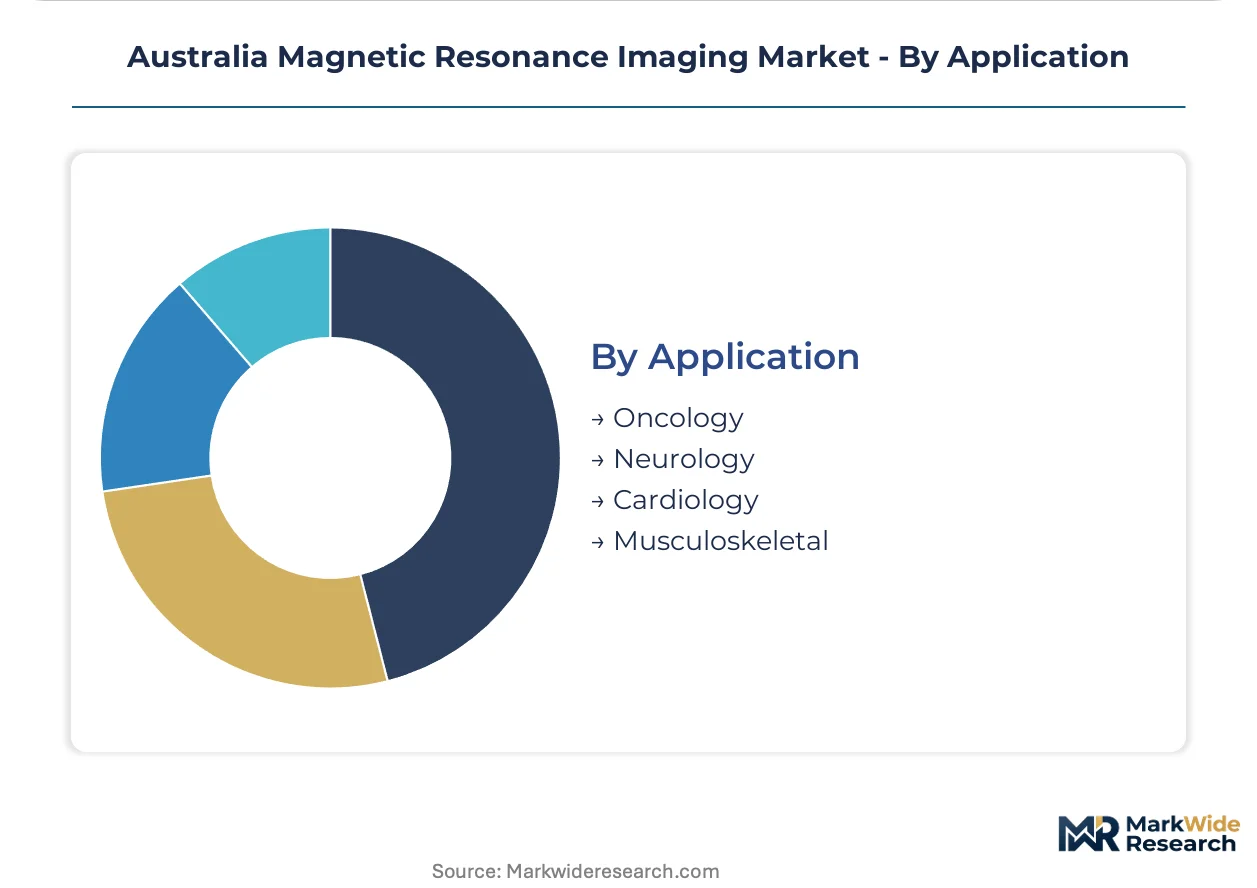
Application:
Clinical indication requirements are reshaping coil configuration preferences and sequence protocol standardization.
- Oncology:Multi-parametric sequences for tumor characterization and treatment response monitoring are driving 3 Tesla procurement at comprehensive cancer centers.
- Neurology:Functional MRI and diffusion tensor applications for pre-surgical planning command premium equipment specifications at Melbourne and Sydney referral centers.
- Cardiology:Stress perfusion and delayed enhancement imaging for ischemic and non-ischemic cardiomyopathy evaluation.
- Musculoskeletal:High-resolution cartilage and ligament imaging for sports medicine and orthopedic surgery planning.
Procedure volume concentrates in Oncology; Neurology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney anchors the Australian MRI market through tertiary hospital network consolidation and concentrated neuroimaging research funding. Melbourne follows with academic medical center procurement driving high-field system adoption. Regional disparities persist across Queensland and Western Australia where scanner density falls below metropolitan benchmarks.
New South Wales
Public health district mergers in Sydney and Newcastle are consolidating procurement authority across previously independent facilities. TGA medical device framework revisions are compressing equipment certification timelines for imported imaging systems. The Sydney metropolitan corridor hosts the highest scanner density nationally with major tertiary centers prioritizing 3 Tesla platform replacements.
Victoria
Melbourne's academic medical centers are securing National Health and Medical Research Council funding for functional MRI research installations. ARPANSA electromagnetic field monitoring protocols are mandating infrastructure upgrades across metropolitan hospital networks. The Melbourne biomedical precinct concentrates neuroimaging consortia seeking real-time cortical mapping capabilities.
Queensland
Regional hospital networks in Townsville, Cairns, and Mackay operate below national MRI scanner density benchmarks. TGA conformity assessment costs for imported equipment disproportionately affect mid-tier regional facilities with constrained capital budgets. Brisbane metropolitan diagnostic centers are expanding 1.5 Tesla system deployments through equipment leasing arrangements.
Western Australia
ARPANSA safety standard updates are driving replacement demand for aging 1.5 Tesla systems across Perth hospital networks. The Therapeutic Goods Administration's expanded technical documentation requirements have increased pre-market approval expenditures. Perth's tertiary referral centers are prioritizing high-field platform acquisitions for advanced spectroscopy applications.
South Australia
Mobile MRI trailer-mounted systems are penetrating rural South Australia through leasing models circumventing permanent installation capital requirements. Helium supply concentration from Qatar and United States imports exposes operators to price volatility extending equipment commissioning timelines. Adelaide metropolitan hospitals are standardizing imaging procurement across consolidated health district structures.
Australia Magnetic Resonance Imaging Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with established service infrastructure. Siemens Healthineers and GE Healthcare anchor procurement relationships through localized technical support networks in Sydney and Melbourne. Canon Medical Systems Corporation occupies a specialist position in high-field system configurations. Strategic moves concentrate on unbundling after-sales service contracts from equipment purchase agreements and negotiating standalone maintenance terms with third-party providers.
Among multinational imaging equipment suppliers, Siemens Healthineers exemplifies the integrated service-provider archetype through long-term hospital contracts in major capital cities. GE Healthcare represents the technical-support-driven competitive position with training programs for radiology departments. Canon Medical Systems Corporation sits within the high-field specialization tier aligning with tertiary referral center requirements.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Esaote SpA |
| Siemens Healthineers |
| Sonologic Inc |
| United Imaging Healthcare Co Ltd |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Hyperfine |
| Koninklijke Philips NV |
| Others |
Value Chain & Pricing Dynamics
Captive service infrastructure from Siemens Healthineers and GE Healthcare anchors pricing power across Australian hospital networks, with long-term maintenance contracts bundled into equipment procurement creating vendor lock-in that regional competitors struggle to displace.
Pricing Analysis
Throughput-based pricing anchors equipment valuation at high-volume Sydney and Melbourne tertiary centers, where scan-minute economics justify premium 3 Tesla platform outlays. Price differentiation separates high-field research systems from standard clinical configurations, with TGA electromagnetic field documentation requirements adding compliance premiums to ultra-high-field categories. Cost compression in mid-tier regional hospital procurement is intensifying because ARPANSA-mandated infrastructure upgrades divert capital from equipment replacement budgets. Public health district mergers exhibit lowest price sensitivity through consolidated volume purchasing, while independent diagnostic centers in Brisbane and Perth face acute capital constraints.
Supply Chain Analysis
Direct-to-hospital channels handle metropolitan health network demand, with manufacturer field service engineers maintaining localized spare parts depots in Sydney and Melbourne. Superconducting magnet fabrication concentrates in Germany, Japan, and the United States, while radiofrequency coil assemblies source from China and South Korea. Liquid helium cooling draws from Qatar and United States import streams, exposing operators to commodity price volatility that extends equipment commissioning timelines. Single-source vulnerability in cryogenic gas supply chains threatens installation schedules across Queensland and Western Australia regional networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around service infrastructure scale, with TGA compliance cost escalation forcing mid-tier regional vendors toward exit or acquisition.
For Market Incumbents: Deepen captive service contract penetration through predictive maintenance platforms that reduce hospital radiographer downtime. Siemens Healthineers and GE Healthcare should expand Queensland technical support footprints to preempt Canon Medical Systems' high-field specialization from anchoring Townsville and Cairns installations. Vertical integration into helium recovery systems mitigates supply disruption risk that currently compresses margin models at regional deployment sites. For New Entrants and Emerging Players: Enter via mobile MRI leasing models that circumvent permanent installation capital barriers in rural Victoria and South Australia. United Imaging Healthcare and Esaote SpA can target independent diagnostic center procurement in Perth metropolitan corridors where equipment leasing arrangements minimize upfront capital exposure. A software-companion go-to-market angle—AI-enabled scan sequence optimization—differentiates against entrenched service infrastructure at high-volume metropolitan sites. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medical technology conglomerates seeking Australian service infrastructure scale. Long-term viability favors vendors with ARPANSA-compliant electromagnetic shielding capabilities and TGA pre-market approval track records. The signal to watch is National Health and Medical Research Council funding allocation shifts toward functional MRI research consortia, which would accelerate 7 Tesla platform demand at academic medical centers.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery System Deployment | Mitigates Qatar and United States import concentration that currently extends regional equipment commissioning timelines. |
| AI Workflow Integration Partnership | Enables throughput gains at high-volume Sydney and Melbourne facilities that justify premium 3 Tesla platform pricing. |
| Mobile MRI Leasing Expansion | Addresses geographic access inequities in rural South Australia without permanent installation capital requirements. |
| Third-Party Service Contract Qualification | Captures procurement committee scoring weight in New South Wales public hospital tender processes that unbundle maintenance terms. |
| 7 Tesla Research Platform Site Certification | Secures ARPANSA site-specific safety dossier approval for Melbourne and Sydney academic medical center installations. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with hospital procurement managers, biomedical engineers, radiology department heads, and GPO contracts managers with TGA medical device registration databases, ARPANSA safety standard documentation, and Medicare Benefits Schedule procedure volume data. Bottom-up equipment installation tracking and top-down healthcare expenditure analysis provided triangulation across metropolitan and regional hospital network coverage.
Segment-level modeling addressed field strength tiers, product configurations, end-user categories, and clinical applications across the projection horizon, with CAGRs derived from replacement cycle analysis and population-adjusted scanner density benchmarks. TGA electromagnetic field documentation timeline assumptions and helium supply cost trajectories informed infrastructure investment sensitivity parameters throughout the forecast period.
Revisions become necessary when ARPANSA safety standard updates accelerate replacement demand beyond modeled infrastructure depreciation schedules or when TGA alignment with IEC 60601-2-33 revisions extends pre-market approval timelines. Periodic stress-testing of base assumptions against National Health and Medical Research Council funding allocation patterns and public health district merger implementation progress is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Italy Magnetic Resonance Imaging Market