
 Global Respiratory Syncytial Virus (RSV) Diagnostic Market | 2026-2036
Global Respiratory Syncytial Virus (RSV) Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Respiratory Syncytial Virus (RSV) Diagnostic Market Analysis
Clinical laboratory technician shortages across North America and Western Europe is collapsing throughput capacity at reference labs during seasonal RSV peaks. Abbott Laboratories leverages its integrated Alinity platform to sustain automated sample-to-answer workflows in understaffed hospital settings. Thermo Fisher Scientific anchors its position through end-to-end nucleic acid extraction and amplification systems that reduce hands-on time. bioMérieux SA differentiates with syndromic respiratory panels that compete on multiplexing breadth beyond single-pathogen assays.
Respiratory Syncytial Virus (RSV) diagnostics comprise in vitro testing systems that detect viral antigens, nucleic acids, or host antibodies in respiratory specimens, typically requiring nasopharyngeal swab collection and processing within controlled temperature windows to preserve RNA integrity. These products serve the clinical imperative of distinguishing RSV from influenza and COVID-19 in symptomatic infants, elderly patients, and immunocompromised populations where antiviral timing affects hospitalization duration. PCR assays occupy the premium tier of the product type landscape due to their analytical sensitivity in low-viral-load specimens, while antigen tests capture volume in urgent care and pediatric clinics where fifteen-minute turnaround outweighs absolute sensitivity. Real-time PCR technology leads the technology dimension in revenue terms, though nucleic acid amplification platforms are gaining placement in decentralized settings through cartridge-based miniaturization.
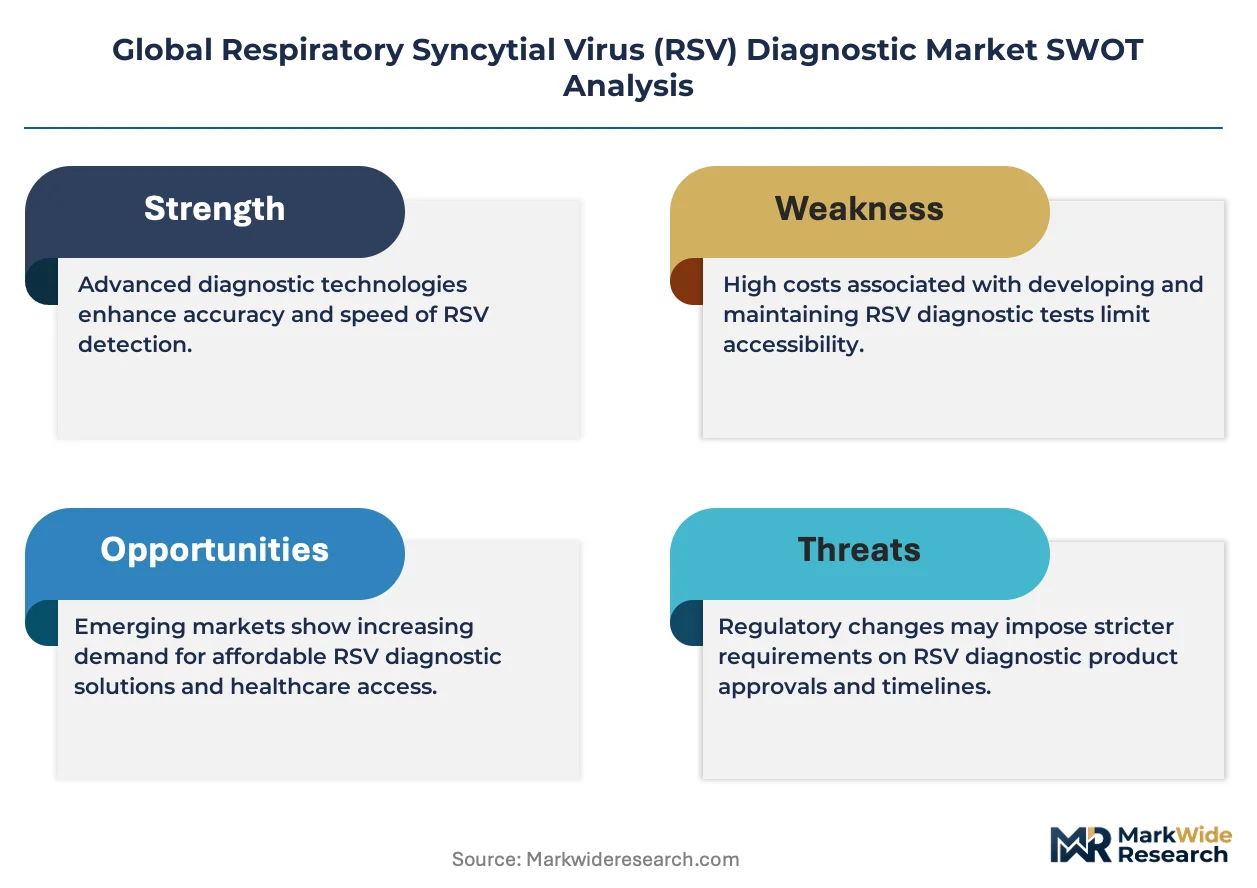
FDA emergency use authorization pathways and CLIA waiver standards shape which RSV assays reach point-of-care settings versus centralized laboratory menus in the United States. The EMA's in vitro diagnostic regulation and CE marking requirements under the EU IVDR framework are raising documentation burdens for manufacturers seeking European market access, effectively filtering smaller kit suppliers from commercialization. Stakeholders must monitor how seasonal disease burden variability and shifting payer coverage for multiplex respiratory panels reshape capital allocation between centralized high-throughput systems and distributed rapid testing infrastructure.
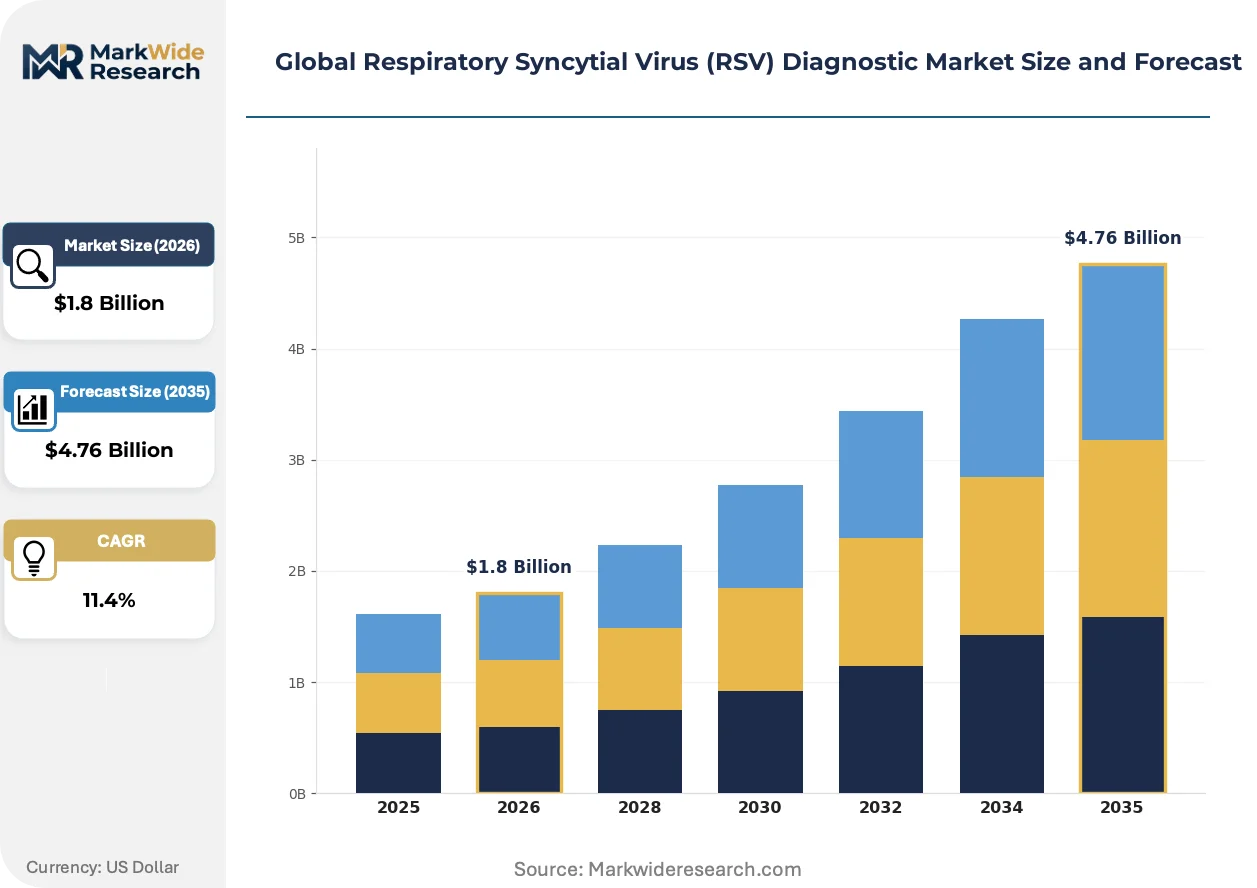
Market Dynamics
The FDA's emergency use authorization framework is compressing assay validation timelines while simultaneously fragmenting placement between centralized laboratories and point-of-care settings, creating divergent capacity investments across health systems.
Growth Catalysts
- CLIA Waiver Expansion:The FDA's CLIA waiver standards are enabling rapid antigen tests in urgent care clinics and pediatric offices, decentralizing diagnostic access beyond hospital laboratories.
- Syndromic Panel Demand:Pediatric hospitals are expanding multiplex respiratory testing programs to distinguish RSV from influenza and COVID-19 in single specimen runs.
- Cartridge Miniaturization:Nucleic acid amplification technologies are gaining placement in decentralized settings through portable, cartridge-based platforms that preserve PCR sensitivity.
Market Restraints
- Reference Lab Bottlenecks:Clinical laboratory technician shortages across the United States and Germany are collapsing throughput capacity at centralized facilities during seasonal RSV peaks.
- EU IVDR Documentation Burden:The European Medicines Agency's in vitro diagnostic regulation and CE marking requirements under the EU IVDR framework are raising compliance costs and filtering smaller kit suppliers from commercialization.
- RNA Degradation Windows:Nasopharyngeal specimen integrity requirements mandate controlled cold-chain logistics that constrain test distribution in regions with limited refrigeration infrastructure.
Strategic Opportunities
- Home-Based Collection Models:Self-collected nasal swab protocols paired with mail-in PCR processing are opening access in rural United States counties lacking proximate laboratory infrastructure.
- Integrated Alinity Workflows:Automated sample-to-answer systems are capturing placement in understaffed hospital settings by reducing hands-on technician time.
- Seasonal Surveillance Contracts:The Centers for Disease Control and Prevention's RSV surveillance networks are driving recurring procurement cycles for high-throughput molecular platforms in state public health laboratories.
Industry Challenges
- Technician Training Deficits:Molecular diagnostics specialization requirements exceed the supply of certified clinical laboratory scientists capable of operating real-time PCR platforms.
- Legacy LIS Integration:Hospital information system interoperability gaps are forcing custom middleware development to connect new RSV assays with existing laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Respiratory Syncytial Virus (RSV) Diagnostic Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antigen Tests, PCR Assays, Serology Tests, Viral Culture Technology: Real-Time PCR, ELISA, Nucleic Acid Amplification, Immunofluorescence End User: Hospitals, Laboratories, Clinics, Home Care Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Becton, Dickinson and Company, bioMérieux SA, QuidelOrtho Corporation, Danaher Corporation, QIAGEN N.V., Hologic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Respiratory Syncytial Virus (RSV) Diagnostic Market Emerging Trajectories
Diagnostic modality selection is splitting along a speed-versus-sensitivity axis, with procurement patterns diverging between emergency departments prioritizing turnaround time and neonatal intensive care units demanding analytical precision.
Cartridge-based miniaturization of nucleic acid amplification platforms is bifurcating the installed base between high-throughput batch processing in reference laboratories and single-test workflows in decentralized clinics. Community health centers in the United States are adopting these portable systems to reduce specimen transport delays. The structural consequence is compressing revenue concentration among manufacturers capable of serving both throughput tiers with unified chemistry.
The European Union's In Vitro Diagnostic Regulation is mandating expanded clinical evidence requirements and quality management system audits for CE marking renewal. Manufacturers are redirecting regulatory affairs resources from new product development to legacy assay recertification. Smaller kit suppliers without dedicated EU regulatory teams are withdrawing from the European market, consolidating commercial access among established multinationals.
Hospital procurement committees are unbundling respiratory testing contracts from comprehensive laboratory service agreements, creating direct purchasing relationships with assay manufacturers. This disintermediation is displacing traditional distribution intermediaries in the United States acute care segment. Integrated delivery networks in Texas and Florida are piloting this model to capture volume-based pricing concessions.
Global Respiratory Syncytial Virus (RSV) Diagnostic Market Segmentation
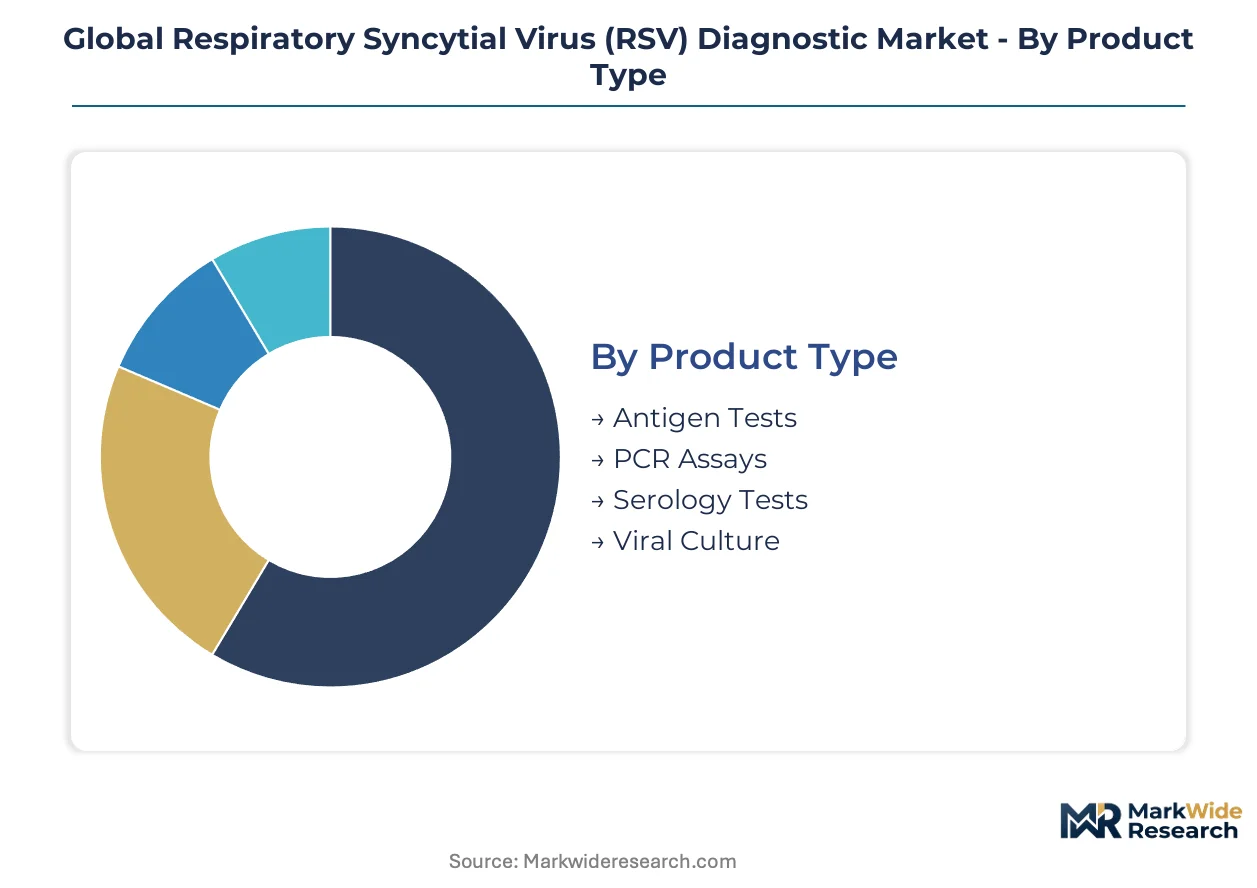
RSV diagnostic procurement splits along speed-versus-sensitivity tradeoffs that reshape capital allocation across health systems. Segment boundaries blur as cartridge-based miniaturization collapses the distance between laboratory-grade precision and point-of-care convenience.
Product Type:
Antigen tests face the most acute substitution pressure from emerging nucleic acid amplification platforms that narrow the turnaround gap without sacrificing analytical performance.
- PCR Assays:These systems detect viral RNA through reverse transcription and polymerase chain reaction amplification, achieving analytical sensitivity below 100 copies per milliliter. Neonatal intensive care units in the United States prioritize PCR placement for immunocompromised infant populations where antiviral timing affects hospitalization duration.
- Antigen Tests:Lateral flow immunoassays targeting RSV fusion protein deliver qualitative results within fifteen minutes using unprocessed respiratory specimens. Urgent care clinics in Texas and Florida capture patient volume through same-visit diagnosis and treatment initiation.
- Serology Tests:Enzyme-linked immunosorbent assays measuring IgM and IgG antibody responses support retrospective outbreak investigation in epidemiological surveillance networks.
- Viral Culture:Shell vial and traditional cell culture methods retain niche application in research laboratories and antiviral susceptibility testing protocols.
Antigen tests retain volume leadership in decentralized settings; PCR assays hold the steepest expansion curve as CLIA-waived molecular platforms penetrate pediatric offices.
Technology:
Cost tier stratification separates premium instrumentation from disposable cartridge systems, with procurement committees weighing capital expenditure against per-test operating economics.
- Real-Time PCR:Fluorescence-based amplification monitoring enables quantitative viral load measurement with cycle threshold value reporting. State public health laboratories in California and New York anchor demand through CDC surveillance network participation requiring standardized molecular methods.
- Nucleic Acid Amplification:Isothermal amplification technologies eliminate thermal cycling requirements, permitting battery-operated portable platforms. Community health centers in rural United States counties adopt these systems to bypass specimen transport logistics.
- ELISA:Microplate-based antibody detection supports high-throughput seroprevalence studies in academic medical center research divisions.
- Immunofluorescence:Direct and indirect fluorescent antibody staining persists in hospital microbiology laboratories with trained technologist staffing.
Real-Time PCR dominates revenue concentration in centralized laboratories; nucleic acid amplification platforms are climbing the fastest through point-of-care placement expansion.
End User:
Application urgency varies dramatically across clinical settings, with emergency department throughput pressures diverging from neonatal intensive care precision requirements.
- Hospitals:Acute care institutions operate mixed diagnostic portfolios spanning emergency department rapid antigen screening and inpatient molecular confirmation. Pediatric hospitals in Ohio and Pennsylvania expand syndromic respiratory panels to distinguish RSV from influenza and COVID-19 in single specimen runs.
- Laboratories:Reference laboratories process high-volume seasonal testing peaks through automated extraction and batch PCR workflows. Technician shortages across the United States and Germany constrain throughput capacity during epidemic periods.
- Clinics:Urgent care and pediatric office settings prioritize CLIA-waived platforms requiring minimal operator training.
- Home Care:Self-collected nasal swab protocols paired with mail-in PCR processing extend access to rural counties lacking proximate laboratory infrastructure.
Laboratories retain the highest test volume throughput; home care represents the most rapidly emerging placement category as collection logistics simplify.
Distribution Channel:
Customer type fragmentation between integrated delivery networks and independent practices reshapes channel economics and service bundling requirements.
- Direct Sales:Manufacturer field organizations negotiate enterprise agreements with hospital procurement committees and laboratory networks. Integrated delivery networks in Texas pilot direct purchasing to capture volume-based pricing concessions outside traditional distribution markups.
- Distributors:Regional laboratory supply intermediaries maintain inventory buffers and technical support infrastructure for smaller clinical accounts.
- Online Retail:E-commerce platforms serve research institutions and outpatient clinics with standardized reagent replenishment.
- Others:Group purchasing organizations aggregate demand across health system alliances to extract contract concessions.
Direct sales channels command the largest transaction value concentration; online retail is expanding most quickly as procurement digitization accelerates in outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where CDC surveillance contracts anchor procurement premiums, while German reference laboratories face margin compression from technician wage inflation and EU IVDR compliance costs.
United States
Pediatric hospitals in Ohio and Pennsylvania drive multiplex respiratory panel adoption to distinguish RSV from influenza and COVID-19. The FDA's CLIA waiver framework accelerates point-of-care placement in urgent care clinics. Texas integrated delivery networks pilot direct manufacturer purchasing to bypass distribution markups.
Germany
Clinical laboratory technician shortages collapse throughput capacity at centralized facilities during seasonal peaks. The EMA's EU IVDR documentation requirements filter smaller kit suppliers from CE marking renewal. Bavarian reference laboratories redirect capital toward automated extraction systems to offset staffing deficits.
China
Provincial CDC networks expand molecular surveillance capacity through NMPA-registered PCR platforms. The country's national pharmaceutical regulator streamlines emergency use pathways for seasonal respiratory assays. Yangtze River Delta manufacturing clusters supply cartridge-based miniaturization components for domestic and export markets.
Japan
Neonatal intensive care units prioritize analytical sensitivity for immunocompromised infant populations. PMDA regulatory timelines shape assay validation sequencing for multinational manufacturers. Kanto region academic medical centers anchor demand for syndromic respiratory testing in pediatric wards.
United Kingdom
NHS procurement frameworks unbundle respiratory testing from comprehensive laboratory service agreements. MHRA post-Brexit regulatory autonomy creates divergence from EU IVDR implementation timelines. London-Southeast hospital networks consolidate purchasing through integrated care system alliances.
Global Respiratory Syncytial Virus (RSV) Diagnostic Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with consolidated multinational instrumentation manufacturers occupying premium molecular tiers while regional kit suppliers capture antigen test volume. The vendor base stratifies across three tiers: integrated platform providers with end-to-end extraction-to-amplification workflows, syndromic panel specialists competing on multiplexing breadth, and rapid test manufacturers optimized for CLIA-waived point-of-care deployment. Dominant competitive moves include automated workflow integration to reduce hands-on technician time and strategic partnerships with integrated delivery networks for direct enterprise contracting.
Among diversified life sciences conglomerates, Abbott Laboratories and Thermo Fisher Scientific exemplify platform-centric archetypes with unified chemistry spanning centralized and decentralized settings. bioMérieux SA occupies a specialist position within the syndromic panel segment. These three entities represent contrasting strategic postures: instrumentation integration versus assay menu breadth versus respiratory-focused multiplexing.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Becton, Dickinson and Company |
| bioMérieux SA |
| QuidelOrtho Corporation |
| Danaher Corporation |
| QIAGEN N.V. |
| Hologic, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day cartridge inventory cycles at U.S. hospital procurement committees concentrate purchasing leverage among manufacturers with domestic fill-finish capacity, compressing margins for suppliers dependent on transoceanic cold-chain logistics while elevating price premiums for CLIA-waived molecular platforms with guaranteed availability.
Pricing Analysis
Configured-to-order pricing for integrated Alinity workflows commands a 25-40% premium over standard reagent rental arrangements in the United States. Three-tier pricing structure across premium, standard, and economy levels stratifies by analytical sensitivity and automation depth, with neonatal intensive care units showing least price sensitivity due to clinical outcome imperatives. Cost compression in the antigen test tier is intensifying because of cartridge-based miniaturization narrowing the performance gap. Urgent care clinics in Texas and Florida exhibit highest price sensitivity, driving procurement toward per-test operating economics over capital expenditure.
Supply Chain Analysis
Just-in-time inventory preferences dominate U.S. hospital procurement, while European reference laboratories maintain strategic stockpiles against EU IVDR-related supply disruptions. Manufacturing concentrates in the United States, Germany, and China, with Yangtze River Delta clusters supplying cartridge miniaturization components. Raw material dependencies center on specialized polymerases, fluorescent probes, and precision-molded plastics. Single-source vulnerability in nucleic acid extraction chemistry creates concentration risk. Distribution runs through direct manufacturer field organizations for integrated delivery networks and regional laboratory supply intermediaries for smaller clinical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as cartridge-based miniaturization collapses the traditional speed-sensitivity tradeoff that once protected premium PCR pricing tiers.
For Market Incumbents: Consolidate automated workflow integration investments to reduce hands-on technician time in understaffed U.S. hospital laboratories. Deepen backward integration into nucleic acid extraction chemistry to secure supply continuity against single-source vulnerabilities. Defend against emerging cartridge-based NAM platforms by accelerating CLIA waiver expansion for molecular assays. For New Entrants and Emerging Players: Anchor in rural United States counties where mail-in PCR processing extends diagnostic access beyond proximate laboratory infrastructure. Target community health centers with battery-operated isothermal amplification platforms that bypass specimen transport logistics. Pursue group purchasing organization contracts to aggregate demand across independent pediatric practices. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates seeking to divest non-core respiratory diagnostics amid portfolio rationalization. Long-term viability hinges on regulatory navigation capabilities across FDA and EU IVDR frameworks. Watch for inflection when CDC surveillance contract renewals accelerate procurement cycles for high-throughput molecular platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA CLIA Waiver Pathway | Accelerates point-of-care placement in urgent care clinics and pediatric offices. |
| CE Marking Under EU IVDR | Filters smaller kit suppliers from European commercialization, consolidating access. |
| Hospital System Partnership | Texas integrated delivery networks pilot direct purchasing to capture volume concessions. |
| Software Companion Development | Resolves legacy LIS integration gaps forcing custom middleware expenditures. |
| Reimbursement Strategy | Shapes capital allocation between centralized systems and distributed rapid testing. |
Methodological Framework
A spread of perspectives from clinical laboratory directors, hospital procurement managers, regulatory affairs specialists, and assay development scientists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA CE marking databases, CDC surveillance network procurement records, and hospital GPO contract repositories. Bottom-up test volume modeling and top-down revenue triangulation anchored the quantitative framework.
Segmentation dimensions modeled span product type, technology platform, end-user setting, and distribution channel across the projection horizon. CAGRs derive from epidemiological burden projections, seasonal surveillance funding trajectories, and CLIA waiver expansion velocity. Forecast inputs incorporate technician shortage severity indices and EU IVDR compliance cost curves.
Decision-makers should treat outputs as directional under assumptions of stable FDA emergency use authorization frameworks and sustained CDC surveillance appropriations; material deviation would warrant model refresh. Revision becomes warranted when cartridge-based NAM platform penetration crosses thresholds that structurally compress PCR premium pricing tiers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global RSV Diagnostics Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Sperm Density Testing Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
Diabetes Testing System Market