
 Vision Screeners Market | 2026-2036
Vision Screeners Market Size, Share, and Industry Trends Forecast 2026-2036
Vision Screeners Market Intelligence
The U.S. Food and Drug Administration's (FDA) streamlined 510(k) clearance pathway for certain ophthalmic devices is shifting the cost-of-entry calculus for new market participants. Topcon Corporation leverages its expertise in optical coherence tomography to capture share in the advanced diagnostic segment. Carl Zeiss Meditec sustains its market position through a strong brand reputation and distribution network focused on hospitals and specialist clinics.
Vision screeners are automated or handheld devices designed for rapid, non-invasive detection of vision disorders. These instruments often utilize photoscreening or wavefront aberrometry to identify risk factors like refractive errors, strabismus, and amblyopia in pre-verbal children and adults. Handheld product types dominate due to their portability for use in schools and community health programs. Within end-user segments, hospitals represent a mature market, while demand from independent ophthalmologists for portable digital units is accelerating.
Market access is governed by stringent regulatory frameworks, including the EU's Medical Device Regulation (MDR) and clearance from Japan's Pharmaceuticals and Medical Devices Agency (PMDA). Compliance with ISO standards for ophthalmic instruments is also essential for product validation and commercialization. Stakeholders must now decide whether to invest in software-as-a-service models for data management or focus purely on hardware innovation to maintain competitive positioning.
Market Dynamics
The market's structure is defined by the convergence of public health policy mandating early childhood screenings and the miniaturization of diagnostic technologies. This combination enables mass-scale, non-invasive testing in non-clinical settings like schools and community centers.
Growth Catalysts
- State-Level Mandates:Legislation in multiple U.S. states requiring vision screening before school entry creates a consistent, large-scale demand base for portable, easy-to-use devices.
- Portable Retinal Imaging:The integration of advanced imaging into handheld units allows for early detection of serious conditions in community health programs beyond simple refractive errors.
- Public Health Initiatives:National health programs, such as those being expanded in India, are incorporating vision screening for children, opening new geographic markets for manufacturers.
Market Restraints
- Component Costs:High-precision optical components and sensors required for advanced diagnostics like optical coherence tomography maintain a high bill-of-materials cost, limiting affordability.
- Regulatory Burden:The EU's Medical Device Regulation (MDR) imposes stringent clinical evidence and post-market surveillance requirements, increasing time-to-market and compliance costs.
- Low-End Substitution:The proliferation of unregulated, consumer-grade smartphone applications for basic vision checks presents a low-fidelity substitution threat for non-critical screening.
Strategic Opportunities
- Software-as-a-Service (SaaS):Developing subscription-based platforms for data management, analysis, and referral tracking offers a recurring revenue stream beyond initial hardware sales.
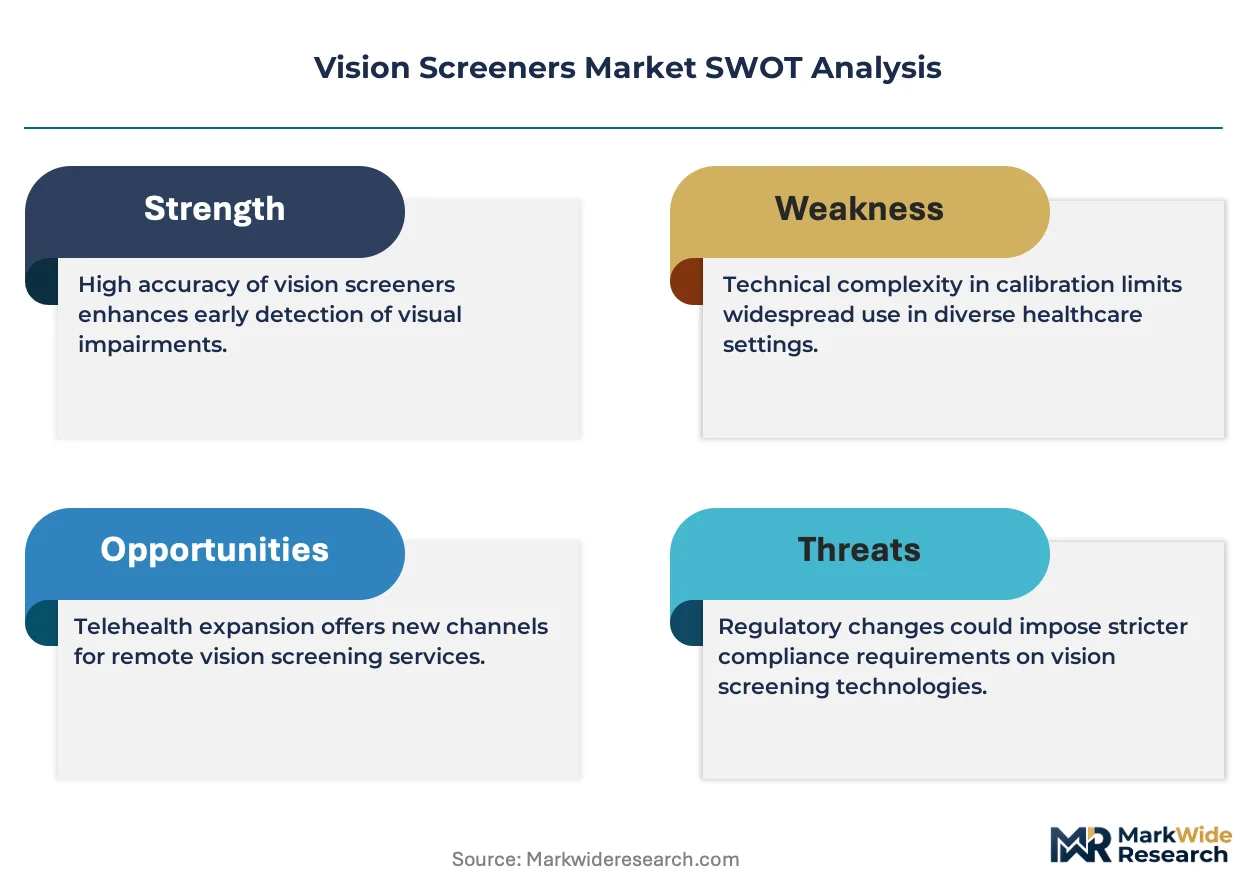
- Telehealth Integration:Opportunities exist to link screening devices with telehealth platforms, enabling remote consultations with ophthalmologists for immediate follow-up on flagged results.
- Emerging Market Penetration:School screening programs in underpenetrated regions like Southeast Asia and Latin America represent significant volume growth opportunities for durable, cost-effective devices.
Industry Challenges
- Data Interoperability:Ensuring seamless integration of screening data with diverse Electronic Health Record (EHR) systems used by hospitals and clinics remains a significant technical hurdle.
- Technician Training:A shortage of trained personnel to operate devices and correctly interpret results in school and community settings can limit the effectiveness of screening programs.
- Compliance Timelines:Achieving and maintaining ISO 13485 certification for medical device quality management is a lengthy and resource-intensive process for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vision Screeners Market |
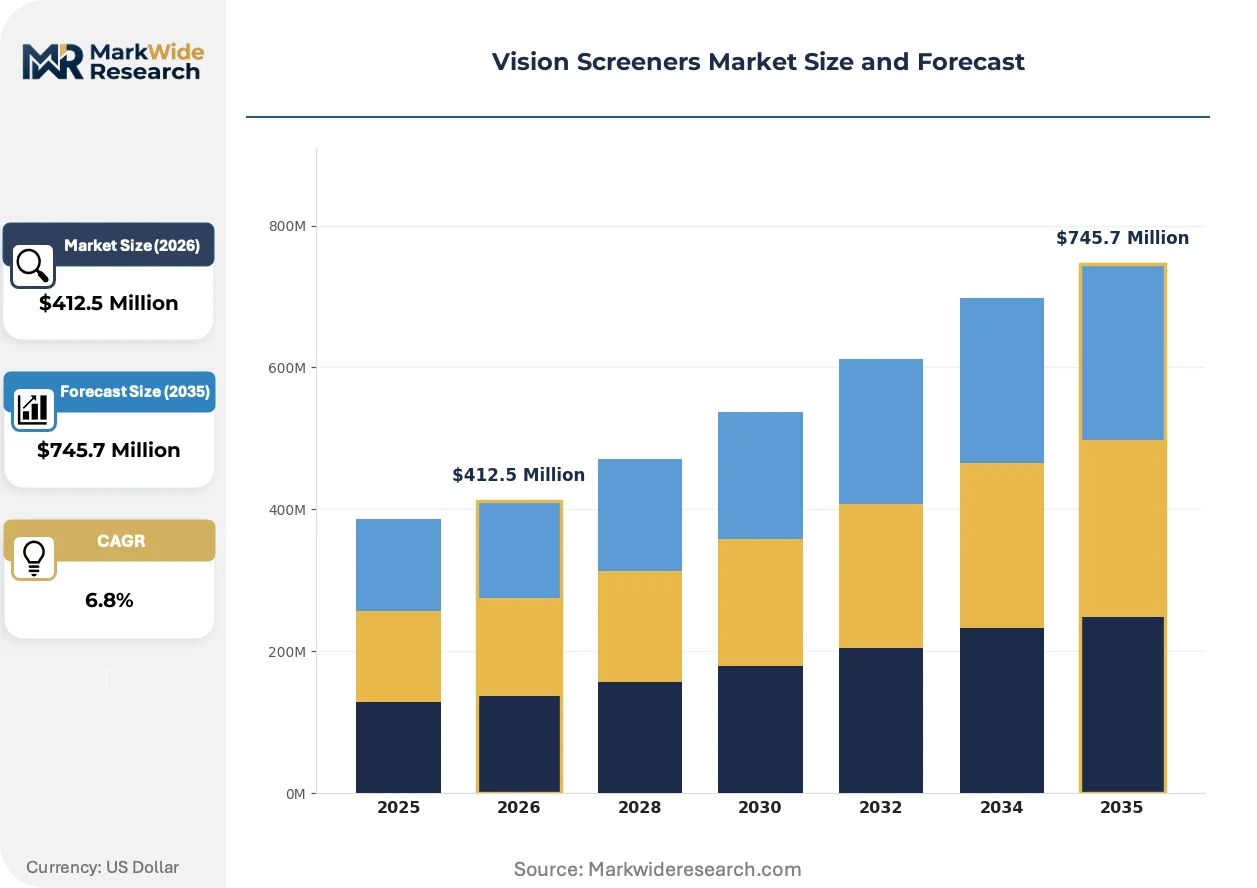
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
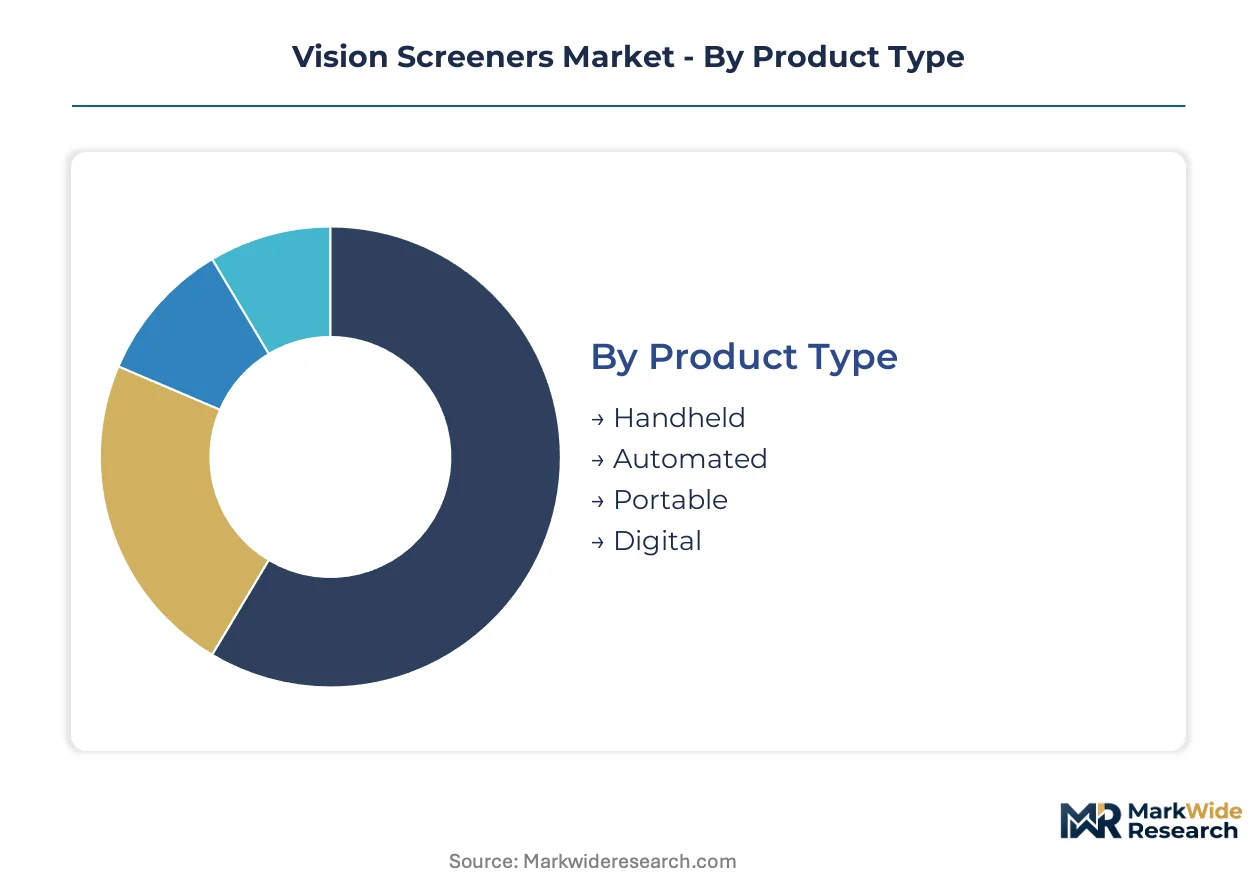
| Segmentation | Product Type: Handheld, Automated, Portable, Digital End User: Hospitals, Clinics, Ophthalmologists, Schools Technology: Optical Coherence Tomography, Retinal Imaging, Visual Field Testing, Wavefront Aberrometry Application: Routine Screening, Diagnosis, Research, Patient Monitoring |
| Companies Covered | Topcon Corporation, Hill-Rom Holdings, Carl Zeiss Meditec, NIDEK Co., Ltd., Canon Medical Systems, Essilor International, Honeywell International, Adaptica Srl, OCULUS Optikgeräte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vision Screeners Market Strategic Shifts & Innovations
A fundamental shift toward predictive vision health management is underway, driven by instrument connectivity and new regulatory pathways. The market is moving beyond simple anomaly detection to longitudinal data analysis for entire patient populations.
Wavefront aberrometry provides a detailed map of the eye's refractive errors, going beyond standard photoscreening. Specialist clinics and independent ophthalmologists are adopting this in portable formats for in-office diagnostics. This advanced optical measurement technology is converging with AI-driven analytical software to predict myopia progression and guide treatment choices.
Japan's Pharmaceuticals and Medical Devices Agency (PMDA) enforces a rigorous approval process for ophthalmic devices that requires extensive local clinical data. This regulatory framework influences product development, demanding specific validation against JIS standards for both hardware and software. Devices with novel AI algorithms face particular scrutiny from the PMDA to prove clinical benefit and data integrity.
End-user procurement is transitioning from single capital equipment purchases toward service-oriented subscription models that alter buying patterns. This model disrupts the traditional distributor sales cycle, replacing it with longer-term contracts covering hardware, software updates, and data management. This shift is most prominent within large school districts and public health networks in the United States.
Vision Screeners Market Segmentation
Understanding the segmentation within the vision screeners market is essential for identifying specific demand patterns and investment priorities. This analysis highlights how different product types, end-user requirements, technological capabilities, and application areas shape the competitive landscape for manufacturers.
Product Type:
The capital expenditure required for vision screening solutions varies significantly across product types, influencing market entry and operational scale.
- Handheld:These compact devices offer mobility, often integrating photoscreening or wavefront aberrometry for rapid assessments. Demand concentrates in schools and community health programs due to their ease of deployment in non-clinical settings.
- Automated:Automated screeners perform comprehensive diagnostic tests with minimal operator intervention, frequently utilizing advanced algorithms for data interpretation. Hospitals and large clinics drive demand for these high-throughput systems, prioritizing precision and reduced technician workload.
- Portable:These units balance diagnostic capability with transportability, serving independent ophthalmologists and mobile clinics.
- Digital:Digital screeners emphasize software-driven diagnostics and data integration, appealing to users focused on telehealth and EHR compatibility.
Handheld products absorb the bulk of installed capacity; Digital units are expanding most quickly.
End User:
Different end-user segments prioritize distinct features and operational efficiencies, shaping demand for specific vision screener functionalities.
- Hospitals:Hospitals require integrated systems capable of comprehensive diagnostics and seamless data exchange with Electronic Health Records. Procurement patterns in hospitals often involve larger capital equipment purchases, driven by the need for high patient throughput and advanced diagnostic capabilities.
- Schools:School-based programs demand rugged, user-friendly devices for mass screening of pre-verbal children and adolescents. State-level mandates in the United States create a consistent, large-scale demand base for these portable, easy-to-use devices.
- Clinics:General clinics seek versatile screeners for initial assessments and referrals, balancing cost with diagnostic accuracy.
- Ophthalmologists:Independent ophthalmologists increasingly adopt portable digital units for in-office diagnostics, valuing advanced features like wavefront aberrometry.
Hospitals represent a mature segment, while Schools show significant growth potential.
Technology:
The maturity of diagnostic technologies dictates their integration into vision screeners, influencing clinical utility and market acceptance.
- Optical Coherence Tomography:OCT provides high-resolution cross-sectional images of the retina and optic nerve, enabling early detection of serious ocular conditions. Topcon Corporation leverages its expertise in OCT to capture share in the advanced diagnostic segment.
- Wavefront Aberrometry:This technology maps the eye's refractive errors in detail, going beyond standard photoscreening to identify subtle aberrations. Specialist clinics and independent ophthalmologists adopt portable wavefront aberrometry for precise in-office diagnostics.
- Retinal Imaging:Portable retinal imaging units allow for early detection of serious conditions, expanding screening capabilities in community health programs.
- Visual Field Testing:Visual field testing assesses peripheral vision, primarily used for detecting conditions like glaucoma and neurological disorders.
Technological advancements in Wavefront Aberrometry are driving new applications, as Retinal Imaging maintains its foundational role.
Application:
The volume of tests performed for each application type significantly influences the design and deployment of vision screening devices.
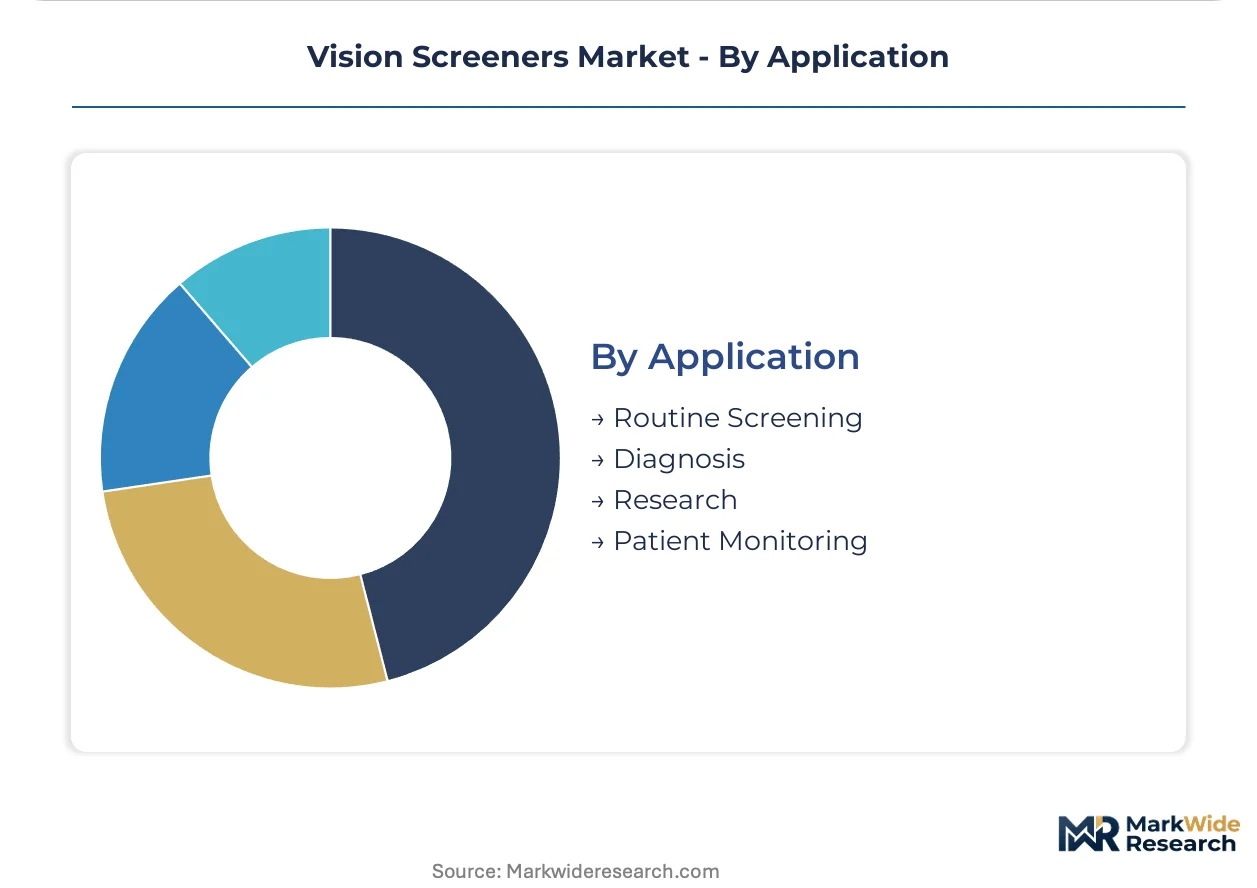
- Routine Screening:This application involves rapid, non-invasive detection of common vision disorders in large populations, often in non-clinical settings. Public health initiatives and state-level mandates for early childhood vision testing before school entry create consistent demand for these devices.
- Diagnosis:Diagnostic applications require higher precision and detailed data output to confirm specific vision disorders identified during screening. Telehealth integration offers opportunities to link screening devices with remote consultations for immediate follow-up on flagged results.
- Research:Research applications utilize vision screeners for clinical trials and studies on ocular health, often requiring specialized data collection capabilities.
- Patient Monitoring:Patient monitoring involves tracking the progression of known conditions, using devices that offer longitudinal data analysis capabilities.
Routine Screening drives the broadest adoption, while Diagnosis represents a high-value niche.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for vision screeners is particularly strong in developed economies, driven by established healthcare infrastructures and proactive public health policies. Emerging markets, however, represent significant future growth opportunities as national health programs expand access to preventative care. Regulatory frameworks and technological adoption vary considerably across key regions, influencing market dynamics.
United States
Consistent, large-scale demand for portable, easy-to-use vision screeners stems from state-level mandates requiring vision testing before school entry. The FDA's streamlined 510(k) clearance pathway for ophthalmic devices lowers the cost-of-entry for new market participants. Major school districts and public health networks in states like California and New York are transitioning towards subscription-based models for hardware and data management.
Japan
Japan's market for vision screeners is shaped by a rigorous approval process from the PMDA, requiring extensive local clinical data. Compliance with JIS standards for ophthalmic instruments is essential for product validation and commercialization. Tokyo and Osaka remain key centers for advanced diagnostic technology development, with companies focusing on novel AI algorithms for enhanced clinical benefit.
Germany
Germany's vision screener market benefits from a strong domestic medical device industry and robust healthcare spending. The EU's Medical Device Regulation (MDR) imposes stringent clinical evidence and post-market surveillance requirements, impacting time-to-market. Major medical technology hubs in Bavaria and Baden-Württemberg focus on high-precision optical components and advanced diagnostic systems.
India
Public health initiatives in India are significantly expanding vision screening programs for children, creating new geographic markets for manufacturers. The country's national pharmaceutical regulator oversees the approval of medical devices, emphasizing affordability and accessibility. Cities like Bangalore and Hyderabad are emerging as development centers for cost-effective, durable devices suitable for mass screening in community health programs.
United Kingdom
The United Kingdom's demand for vision screeners is influenced by national health service procurement and a focus on early detection of vision disorders in pediatric populations. Compliance with EU MDR standards, even post-Brexit, remains a significant factor for market access. London and Cambridge serve as centers for medical technology innovation, exploring telehealth integration for remote consultations and follow-up care.
Vision Screeners Market Key Industry Players
Japanese and German producers anchor one tier of the vision screeners market, specializing in high-precision optical components and advanced diagnostic systems, while US-based companies often focus on software-driven solutions and market access. The market exhibits a tiered structure, with established medical device giants competing alongside specialized ophthalmic technology firms and emerging software providers. Companies are increasingly engaging in strategic partnerships to integrate hardware with data management platforms, alongside portfolio diversification into software-as-a-service models.
On the premium-tier vector, Topcon Corporation exemplifies expertise in optical coherence tomography, capturing share in advanced diagnostic segments. Carl Zeiss Meditec, a German entity, sustains its market position through a strong brand reputation and an extensive distribution network focused on hospitals and specialist clinics. US-based Hill-Rom Holdings, Inc. occupies a position in the market by offering integrated medical technologies, including vision screening solutions, often targeting institutional healthcare providers.
| Leading Market Players |
|---|
| Topcon Corporation |
| Hill-Rom Holdings |
| Carl Zeiss Meditec |
| NIDEK Co., Ltd. |
| Canon Medical Systems |
| Essilor International |
| Honeywell International |
| Adaptica Srl |
| OCULUS Optikgeräte |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap manufacturers often dictate supply behavior and pricing discipline in the vision screeners market. Their long-term investment horizons influence component sourcing and product development strategies. This ownership structure supports sustained R&D for high-precision optical components.
Pricing Analysis
Premium pricing for devices with short lead times reflects specialized component availability. The market utilizes a hybrid pricing model, blending capital equipment purchases with service-oriented subscription models. Price differentiation stems from established brand reputation and the integration of advanced diagnostic technologies like wavefront aberrometry. Pricing softness arises from high component costs and the threat of low-end consumer-grade substitutions. Schools represent the most price-sensitive segment, while hospitals prioritize comprehensive diagnostics over lowest cost.
Supply Chain Analysis
Regional distribution centers support the downstream delivery of vision screeners to hospitals and clinics. Supply concentration centers in Japan and Germany for high-precision optical components, while the United States specializes in software-driven solutions. The market relies on advanced sensors and optical coherence tomography components. Regulatory burden from frameworks like the EU MDR presents a significant structural supply chain risk. Distribution runs through established networks, increasingly shifting towards longer-term service-oriented contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vision screeners market presents a compelling cost-of-compliance story, where stringent regulatory frameworks like the EU Medical Device Regulation (MDR) create a significant barrier-to-entry moat for compliant players. This ensures a competitive advantage for established manufacturers.
For Market Incumbents: Hedge against market disruption by low-end consumer applications through continuous R&D in advanced diagnostic technologies. Incumbents should invest in software-as-a-service models for data management, leveraging their extensive distribution networks. This approach reinforces their position against new market entrants benefiting from streamlined regulatory pathways. Maintaining ISO 13485 certification also provides a competitive advantage.
For New Entrants and Emerging Players: Begin with targeting underpenetrated school screening programs in emerging markets like Southeast Asia and Latin America. Develop durable, cost-effective devices designed for mass screening in non-clinical settings. A go-to-market angle focusing on regulatory efficiency, leveraging pathways like the FDA's 510(k) clearance, can accelerate market entry. Integrate basic digital units with telehealth platforms for remote consultation.
For Investors and Strategic Acquirers: Widespread adoption of subscription models by large school districts is the leading indicator that market consolidation will accelerate. The vision screeners market exhibits strong long-term viability over the next 5-10 years, driven by public health mandates. Acquisition targets should focus on specialized software providers offering robust data management and telehealth integration platforms. This strategy capitalizes on the market's shift towards service-oriented procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop SaaS Data Management Platforms | Offers recurring revenue streams and enhances data interoperability with Electronic Health Record (EHR) systems for hospitals. |
| Expand into Emerging Market School Programs | Captures significant volume growth opportunities in regions like India and Southeast Asia for cost-effective devices. |
| Integrate Telehealth Capabilities | Enables remote consultations with ophthalmologists for immediate follow-up on flagged results, improving patient outcomes. |
| Invest in Wavefront Aberrometry R&D | Enhances diagnostic accuracy for specialist clinics and independent ophthalmologists, predicting myopia progression. |
| Pursue FDA 510(k) Clearances | Streamlines market entry for new ophthalmic devices in the United States, reducing time-to-market for innovators. |
Research Approach
Multi-period observation of regulatory approvals and technology adoption rates anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary interviews included ophthalmologists, hospital procurement managers, school health program administrators, and medical device engineers. Secondary validation drew from FDA 510(k) filings, PMDA approval documents, ISO standards, and public health initiative reports. This approach enabled comprehensive bottom-up and top-down data triangulation.
Segment-weighting across product type, end-user segment, technology, application, and regional regulatory clusters formed the basis of the analytical framework. CAGRs were derived through a regression analysis of historical market data and projected growth drivers over the analysis window. Key industry-specific inputs included state-level mandates for vision screening and planned public health program expansion.
Underlying measurement precision varies by segment; automated devices and hospital end-users carry tighter precision than handheld units in community programs. Forecasts reflect assumptions regarding regulatory stability and technological integration. Component cost volatility and unforeseen regulatory changes represent key risk factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Meningitis Diagnosis and Treatment Market