
 Melanoma Cancer Diagnostics Market | 2026-2036
Melanoma Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Melanoma Cancer Diagnostics Market Outlook
Consolidation among oncology clinic networks and large diagnostic laboratory chains is repositioning procurement leverage toward centralized laboratory testing models. F. Hoffmann-La Roche Ltd leverages its companion diagnostic infrastructure to anchor molecular testing workflows in major health systems. Thermo Fisher Scientific Inc. competes through broad assay menu depth across PCR and next-generation sequencing platforms. Quest Diagnostics Incorporated controls extensive geographic reach through its national laboratory network, sustaining volume advantages in routine biopsy processing.
Melanoma cancer diagnostics encompasses laboratory and imaging methodologies that detect, classify, and monitor cutaneous malignant neoplasms through histopathological examination, molecular profiling, and biomarker quantification at sensitivity thresholds enabling early-stage intervention. The primary commercial purpose centers on guiding surgical margins, predicting metastatic risk, and selecting targeted or immunotherapy regimens. Molecular testing leads revenue contribution due to high assay complexity and reimbursement premiums for BRAF, NRAS, and c-KIT mutation panels. Point-of-care testing represents the fastest-growing delivery mode as adhesive patch-based genomic assays reduce dermatology referral bottlenecks. Biomarker testing commands concentrated margin pools where proprietary algorithms integrate multi-analyte signatures into risk stratification scores.
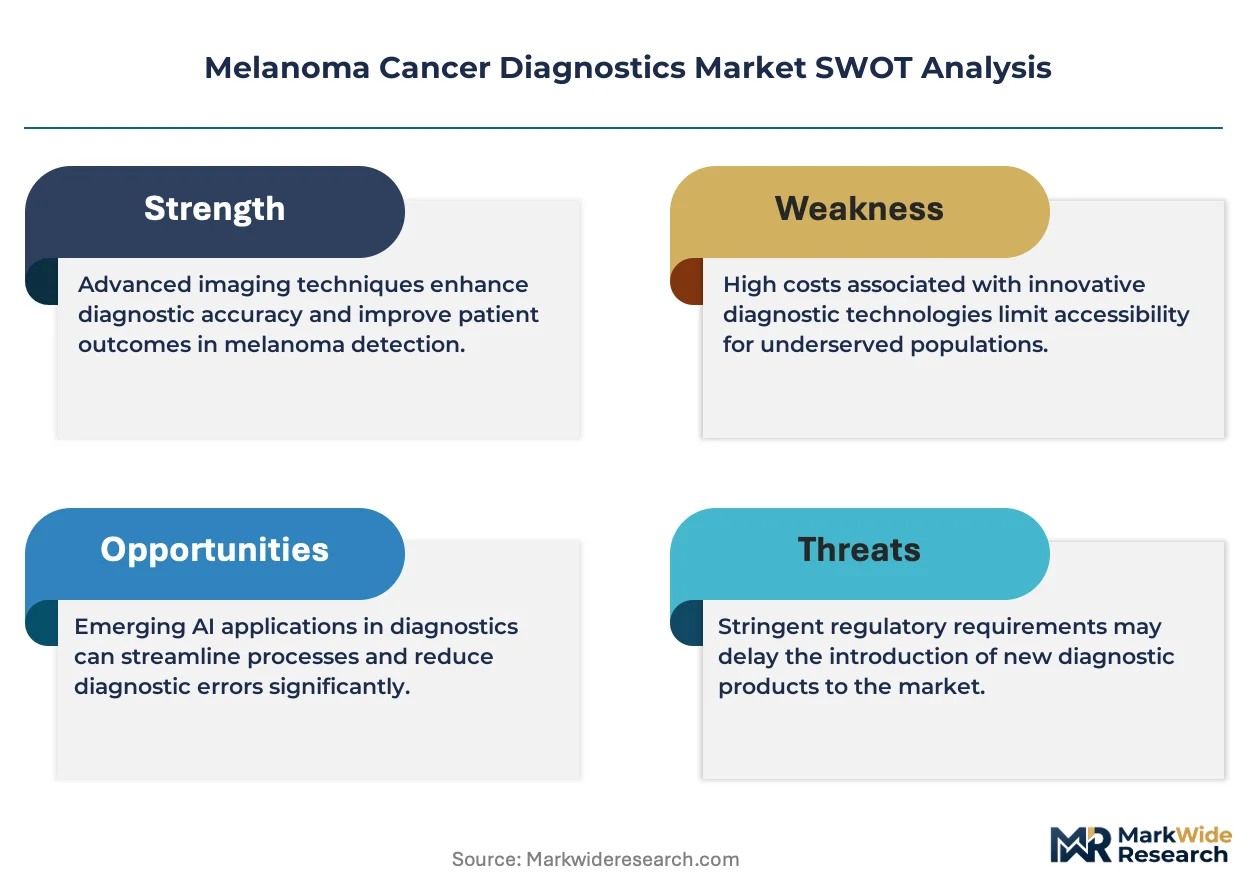
FDA breakthrough device designations and EMA companion diagnostic pathways shape product development timelines and market access conditions for novel assay platforms. ISO 15189 accreditation requirements and CLIA laboratory certification standards enforce quality benchmarks that filter smaller entrants from high-complexity testing segments. Stakeholders must monitor evolving payer coverage policies for liquid biopsy applications and artificial intelligence-augmented dermatoscopy as these modalities challenge traditional tissue-based diagnostic economics.
Market Dynamics
Companion diagnostic pathways at FDA and EMA are compressing commercialization timelines for molecular assay developers, while reimbursement volatility for liquid biopsy applications creates uneven adoption curves across health systems.
Growth Catalysts
- EMA companion diagnostic pathways:Accelerated market access for biomarker assays in Germany and France reduces time-to-revenue for assay developers targeting precision oncology workflows.
- Point-of-care adhesive patch platforms:Dermatology clinics in the United States are deploying genomic patch assays to bypass histopathology referral bottlenecks and capture same-visit diagnostic revenue.
- Specialized dermatopathology networks:Concentrated expertise in Japan's university hospital systems drives molecular testing penetration for BRAF mutation profiling in surgical oncology.
Market Restraints
- Reimbursement code fragmentation:CMS and private payers in the United States maintain inconsistent coverage policies for AI-augmented dermatoscopy, creating revenue uncertainty for digital pathology vendors.
- Fluorinated reagent supply concentration:PCR master mix production depends on specialty chemical suppliers concentrated in Germany and Switzerland, exposing assay manufacturers to input cost volatility.
- Tissue-based diagnostic economics:Liquid biopsy platforms threaten to displace surgical biopsy volumes in early-stage monitoring, compressing margin pools for histopathology service providers.
Strategic Opportunities
- Underpenetrated rural dermatology:Telemedicine-integrated patch testing in Australia's regional health districts addresses geographic access gaps without capital-intensive laboratory infrastructure.
- AI Act regulatory tailwind:The European Union's risk-classification framework for medical AI creates compliance roadmaps that favor established assay developers with quality management systems.
- NGS-immunohistochemistry convergence:Combined multi-omic workflows in tertiary cancer centers enable single-specimen comprehensive profiling, reducing patient sample burden and care coordination costs.
Industry Challenges
- Molecular pathologist workforce scarcity:Fellowship-trained dermatopathologists with dual competency in genomic interpretation command premium compensation, constraining laboratory expansion timelines.
- CLIA high-complexity certification timelines:New laboratory entrants face 12-18 month validation periods for BRAF and NRAS assay menus, delaying revenue generation in competitive metropolitan markets.
- Laboratory information system integration:Legacy LIS architectures in community hospital networks require custom middleware development to support multi-analyte report delivery, increasing implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melanoma Cancer Diagnostics Market |
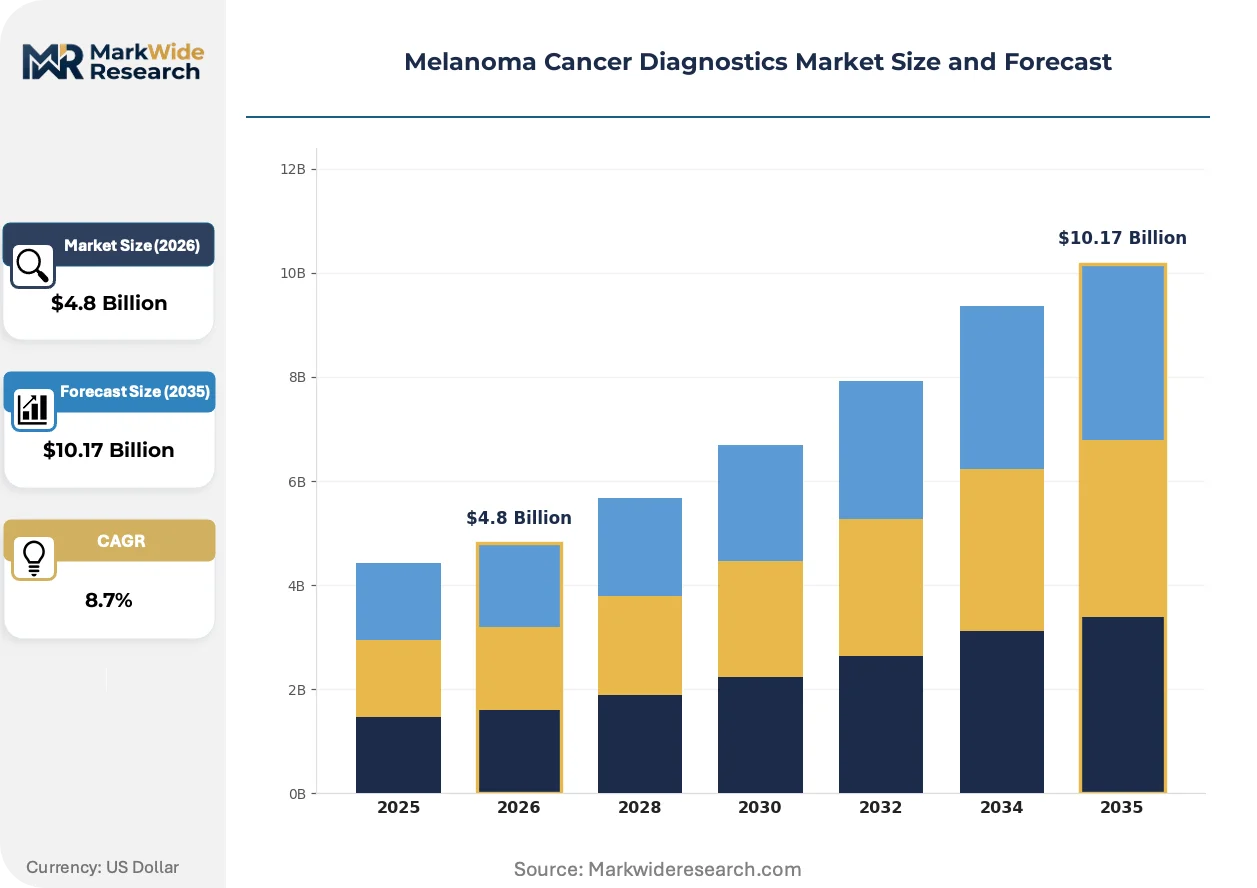
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Imaging, Molecular Testing, Biomarker Testing Technology: Next-Generation Sequencing, PCR, Immunohistochemistry, Fluorescence In Situ Hybridization End User: Hospitals, Diagnostic Laboratories, Research Institutions, Oncology Clinics Delivery Mode: In-house Testing, Point-of-Care Testing, Home Testing, Centralized Laboratory Testing |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Quest Diagnostics Incorporated, QIAGEN N.V., Illumina Inc., DermTech, Castle Biosciences, Siemens Healthineers AG, Foundation Medicine Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melanoma Cancer Diagnostics Market Strategic Shifts
Digital pathology and artificial intelligence are restructuring diagnostic workflows, while regulatory frameworks evolve to accommodate algorithm-augmented clinical decision support. These forces are compressing traditional histopathology timelines and redistributing value across the testing value chain.
Multiplex immunohistochemistry platforms are modularizing antibody panel deployment for immune-oncology biomarker quantification. Academic medical centers in Germany and the Netherlands are adopting these systems to consolidate PD-L1, CD8, and tumor-infiltrating lymphocyte scoring onto single-slide workflows. This modularization is reducing per-case reagent consumption while enabling standardized scoring algorithms that improve inter-observer concordance.
MDR Article 10 performance study requirements are extending conformity assessment timelines for novel in vitro diagnostic devices in the European Union. Manufacturers must now generate clinical evidence from European Union-based laboratories, increasing regulatory compliance costs for United States and Asian assay developers. Smaller molecular diagnostic firms are responding by prioritizing FDA 510(k) pathways first, deferring European market entry.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts that bundle instrumentation, consumables, and bioinformatics support. Community health systems in the United States are displacing point-solution purchasing in favor of multi-year partnerships with vendors offering comprehensive assay menus. This concentration is most visible in the southeastern states, where hospital network consolidation has reduced the number of independent contracting entities by half over the past five years.
Melanoma Cancer Diagnostics Market Segmentation
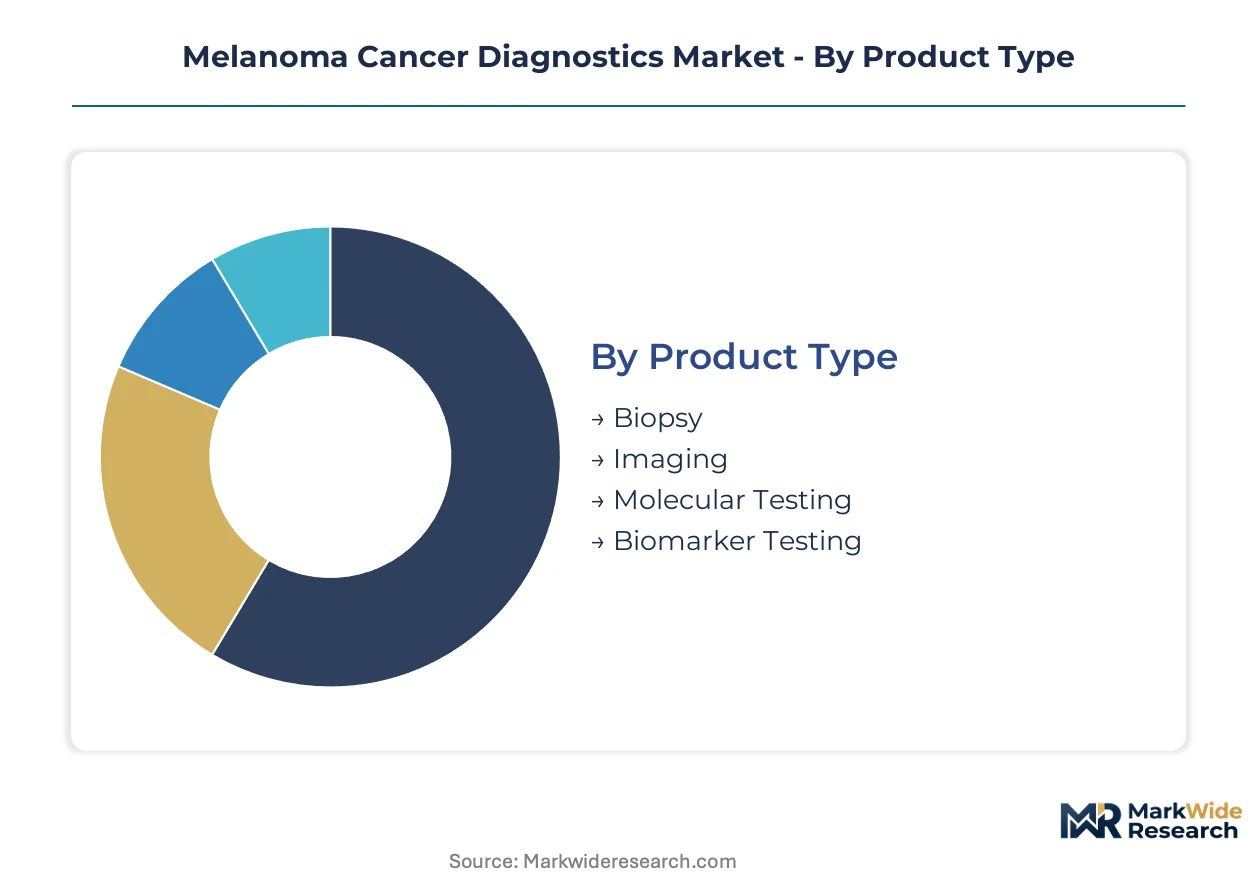
Melanoma cancer diagnostics segments by technical capability, care setting, and specimen handling workflow. Each category reflects distinct margin structures, regulatory pathways, and procurement dynamics that shape vendor positioning.
Product Type:
Molecular testing commands premium pricing through assay complexity, while biopsy processing sustains volume throughput in routine diagnostic workflows.
- Biopsy:Tissue acquisition and histopathological examination remain the foundational diagnostic step. United States dermatology practices process high volumes through CLIA-certified laboratories, constrained by pathologist workforce availability and reimbursement compression for standard histology.
- Molecular Testing:PCR and NGS-based mutation profiling for BRAF, NRAS, and c-KIT alterations guides targeted therapy selection. German university hospitals drive adoption through EMA companion diagnostic pathways that link assay reimbursement to drug approval status.
- Imaging:Dermatoscopy and confocal microscopy enable non-invasive lesion assessment. Japanese cancer centers integrate digital imaging networks to reduce unnecessary excisional procedures.
- Biomarker Testing:Multi-analyte signatures and circulating tumor DNA assays support risk stratification. Liquid biopsy applications face uneven payer coverage across United States health systems.
Mature deployment sits with Biopsy. Newer deployment is concentrated in Molecular Testing.
Technology:
Platform selection hinges on throughput requirements, turnaround time constraints, and capital expenditure thresholds across laboratory tiers.
- PCR:Established thermal cycling technology delivers rapid, cost-effective mutation detection for single-gene targets. Community hospital laboratories in the United States rely on PCR for BRAF V600E screening given lower equipment costs and simpler validation requirements.
- Next-Generation Sequencing:Massively parallel sequencing enables comprehensive genomic profiling from limited tissue specimens. Tertiary cancer centers in France and the Netherlands deploy NGS panels to consolidate biomarker testing and reduce sequential assay burden.
- Immunohistochemistry:Antibody-based protein detection supports PD-L1 expression scoring and lineage confirmation. Academic medical centers standardize IHC workflows through automated stainer platforms.
- Fluorescence In Situ Hybridization:Chromosomal rearrangement detection for rare fusion events. Reference laboratories maintain FISH capability for diagnostic dilemmas requiring cytogenetic resolution.
High-throughput deployment concentrates in Next-Generation Sequencing. Rapid-turnaround demand favors PCR.
End User:
Procurement authority varies by care setting, with hospital networks leveraging capital budgets and oncology clinics prioritizing operational flexibility.
- Diagnostic Laboratories:High-volume processing centers with established payer contracts and specialized dermatopathology expertise. Quest Diagnostics and similar national networks dominate routine biopsy workflows in the United States through geographic density and logistics infrastructure.
- Hospitals:Integrated health systems combining surgical oncology, pathology, and molecular diagnostics under unified governance. German university hospitals anchor precision oncology adoption through consolidated biomarker testing menus.
- Oncology Clinics:Ambulatory settings seeking point-of-care solutions to reduce referral delays. Australian regional clinics deploy telemedicine-integrated testing to address dermatologist access gaps.
- Research Institutions:Academic centers generating clinical evidence for novel assay validation. Japanese national cancer centers contribute patient cohorts to companion diagnostic development programs.
Consolidated purchasing power sits with Diagnostic Laboratories. Distributed demand growth is concentrated in Oncology Clinics.
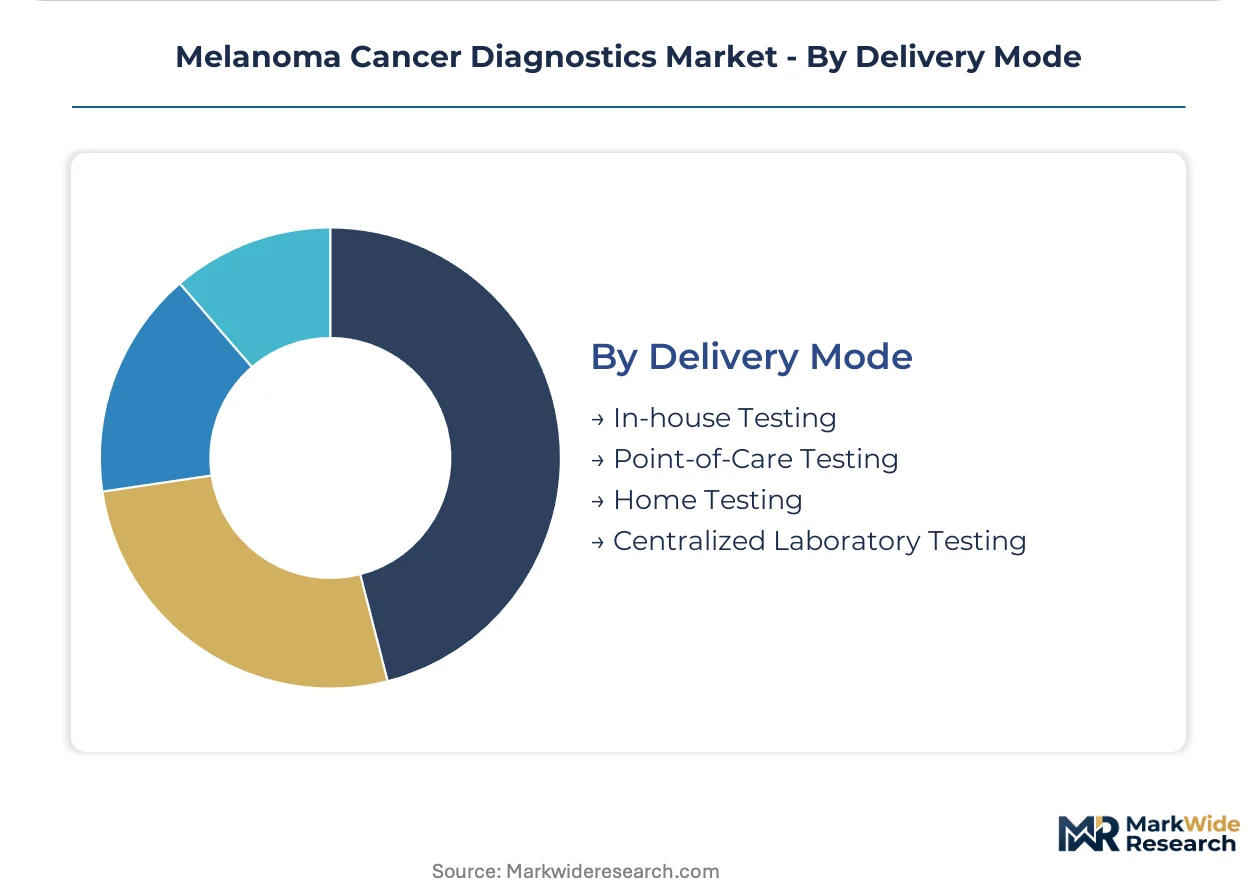
Delivery Mode:
Specimen logistics and result turnaround requirements determine optimal testing location across the care continuum.
- Centralized Laboratory Testing:High-complexity molecular assays processed in dedicated facilities with specialized equipment and personnel. United States regional reference laboratories handle NGS profiling for community oncology practices lacking in-house capability.
- Point-of-Care Testing:Adhesive patch-based genomic assays enable same-visit diagnosis in dermatology clinics. United States private practices capture revenue previously lost to external pathology referrals.
- In-house Testing:Hospital-based laboratories maintaining CLIA certification for routine histopathology. Japanese university hospitals preserve surgical pathology autonomy to support multidisciplinary tumor boards.
- Home Testing:Emerging self-collection models for monitoring applications. Regulatory frameworks for at-home melanoma surveillance remain under development in European markets.
Established infrastructure sits with Centralized Laboratory Testing. Steepest expansion trajectory is concentrated in Point-of-Care Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical feedstocks for PCR master mix production concentrate in German and Swiss manufacturing corridors, anchoring molecular assay supply chains to Central European industrial basins. Diagnostic demand distributes across tertiary cancer centers, university hospital networks, and specialized dermatopathology facilities in three dominant national markets.
United States
FDA breakthrough device designations compress commercialization timelines for biomarker assay developers targeting precision oncology workflows. Dermatology clinics deploy adhesive patch-based genomic assays to capture same-visit diagnostic revenue previously lost to external pathology referrals. The southeastern hospital network consolidation has halved independent contracting entities over five years, concentrating procurement authority around integrated platform contracts.
Germany
EMA companion diagnostic pathways accelerate market access for BRAF and NRAS mutation panels in university hospital systems. MDR Article 10 performance study requirements extend conformity assessment timelines for novel IVD devices, increasing regulatory compliance costs for foreign assay developers. The Baden-Württemberg and Bavaria regions anchor molecular testing adoption through consolidated biomarker menus in surgical oncology departments.
Japan
PMDA regulatory frameworks support companion diagnostic co-approval mechanisms that link assay reimbursement to targeted therapy authorization. University hospital networks in the Kanto and Kansai regions preserve surgical pathology autonomy to support multidisciplinary tumor boards. National cancer centers contribute patient cohorts to biomarker validation programs for emerging liquid biopsy applications.
Australia
TGA oversight governs in vitro diagnostic registration for telemedicine-integrated testing models addressing regional dermatologist access gaps. The New South Wales and Victoria health districts deploy point-of-care patch platforms without capital-intensive laboratory infrastructure. Rural procurement committees prioritize operational flexibility over comprehensive assay menus in community clinic networks.
Melanoma Cancer Diagnostics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue point-of-care delivery modes and algorithm-augmented diagnostic workflows. The market structures around three tiers: multinational diagnostic conglomerates with companion diagnostic infrastructure, specialized molecular assay developers with focused biomarker portfolios, and emerging platform innovators leveraging adhesive patch and AI-augmented technologies. Consolidation among hospital networks and laboratory chains is repositioning procurement leverage toward centralized testing models. Dominant competitive moves include strategic partnerships for integrated platform contracts and technology licensing for multi-analyte algorithm development.
Within the multinational conglomerate tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific Inc. represent established anchors with broad assay menu depth and companion diagnostic infrastructure. Quest Diagnostics Incorporated exemplifies the geographic scale archetype through national laboratory network density. These three entities occupy positions that reflect divergent strategic emphases: Roche anchors precision oncology workflows in major health systems, Thermo Fisher competes across PCR and NGS platform breadth, and Quest sustains volume advantages in routine biopsy processing through logistics infrastructure.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Quest Diagnostics Incorporated |
| QIAGEN N.V. |
| Illumina Inc. |
| DermTech |
| Castle Biosciences |
| Siemens Healthineers AG |
| Foundation Medicine Inc. |
| Others |
Value Chain & Pricing Dynamics
Fluorinated reagent spot indices in German and Swiss chemical corridors cascade through PCR master mix production into three-tier pricing structure across premium, standard, and economy levels for molecular assay manufacturers. Contract laboratories absorb input cost volatility through long-term offtake agreements with specialty chemical suppliers, while point-of-care patch developers face unbundled service economics that compress margin recovery on consumables alone.
Pricing Analysis
Extended warranty and bioinformatics support bundling separates premium molecular assay contracts from unbundled equipment-only transactions in community hospital procurement. Three-tier pricing structure across premium, standard, and economy levels dominates, with ISO 15189 certification tier and assay menu breadth as primary price differentiation drivers. Cost compression in standard-tier histopathology is intensifying because reimbursement compression for routine biopsy processing outpaces operational efficiency gains. Community hospital laboratories exhibit highest price sensitivity due to capital budget constraints, while tertiary cancer centers prioritize comprehensive assay menus over per-test economics.
Supply Chain Analysis
Return flows for refurbished NGS sequencers and recertified thermal cyclers create secondary equipment markets that extend asset lifecycles in budget-constrained laboratories. Manufacturing concentrates in Germany, Switzerland, and the United States for fluorinated polymer production, thermal cycling instrumentation, and optical detection modules. Raw material dependencies rest on specialty fluorochemicals, semiconductor-grade optics, and synthetic oligonucleotides. Single-source vulnerability from Swiss-German chemical corridor concentration exposes assay manufacturers to input disruption. Distribution runs through regional reference laboratory networks that consolidate specimen logistics and instrument service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CLIA high-complexity certification timelines and MDR Article 10 performance study requirements erect cost-of-compliance barriers that protect incumbent positions while filtering undercapitalized entrants from precision oncology segments.
For Market Incumbents: Deepen companion diagnostic infrastructure through EMA pathway investments that lock in reimbursement-linked assay positioning ahead of biosimilar entry. Anchor molecular testing workflows in German university hospital networks where consolidated procurement committees favor multi-year platform partnerships. Defend against liquid biopsy substitution threat by integrating tissue-based and circulating tumor DNA workflows into unified reporting systems. For New Entrants and Emerging Players: Capture telemedicine-integrated patch testing demand in Australian regional health districts where dermatologist scarcity creates addressable white space without reference laboratory competition. Target oncology clinic point-of-care deployment as the most penetrable delivery mode, bypassing CLIA certification barriers through adhesive patch genomic assay partnerships with established dermatology practice management platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor algorithm-augmented dermatoscopy developers with FDA breakthrough device designations in the United States, where reimbursement code fragmentation has compressed valuations below platform development costs. Long-term viability centers on proprietary multi-analyte risk scoring algorithms that command premium pricing through outcome-linked contracting. Monitor CMS coverage determinations for AI-augmented dermatoscopy as the critical inflection signal for digital pathology vendor revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | EMA pathway alignment with BRAF inhibitor approvals secures reimbursement-linked assay positioning in German hospital networks. |
| Point-of-Care Patch Platform Launch | Adhesive patch genomic assays bypass histopathology referral bottlenecks to capture same-visit revenue in United States dermatology clinics. |
| AI-Augmented Dermatoscopy FDA Submission | Breakthrough device designation compresses review timelines for algorithm-based lesion classification in precision oncology workflows. |
| NGS-IHC Convergence Workflow | Multi-omic single-specimen profiling reduces patient sample burden in French and Dutch tertiary cancer centers. |
| Liquid Biopsy Reimbursement Strategy | Coverage pathway development with CMS and private payers determines commercial viability for circulating tumor DNA monitoring applications. |
Study Parameters
FDA 510(k) clearance databases, EMA companion diagnostic approval records, and CMS Medicare reimbursement files formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with dermatopathology laboratory directors, hospital procurement committee chairs, molecular assay development executives, and payer policy specialists validated secondary findings and informed segmentation assumptions. Bottom-up assay volume modeling and top-down precision oncology spending allocation were triangulated to produce convergent market estimates.
Historical trendline analysis of molecular testing adoption rates, biopsy processing volumes, and companion diagnostic co-approval patterns established baseline trajectory parameters across the analysis window. Segmentation modeling incorporated product type, technology platform, end-user setting, and delivery mode dimensions. CAGRs were derived from fitted growth curves applied to validated base-year estimates, with BRAF mutation testing penetration rates and liquid biopsy coverage expansion serving as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement policy shifts and regulatory pathway evolution for AI-augmented diagnostics. Forecasts reflect documented assumptions regarding companion diagnostic co-approval timelines and payer coverage determination schedules. Practitioners should monitor FDA breakthrough device designation grants and CMS national coverage determinations for early signals of modality substitution risk.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Extraction Kits Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
FISH Probe Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Creatine Kinase Reagent Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Vibrio Diagnostics Market