
 Precision Diagnostics Market | 2026-2036
Precision Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Diagnostics Market Intelligence
Liquid biopsy analysis is pivoting diagnostic workflows away from traditional tissue-based sampling, altering the economic models for cancer monitoring. F. Hoffmann-La Roche leverages its integrated pharmaceutical and diagnostics portfolio to advance this shift. Illumina dominates the core sequencing technology that underpins many liquid biopsy assays. Meanwhile, Guardant Health specializes exclusively in this non-invasive testing space, competing on turnaround time and clinical data.
Precision diagnostics involve the use of genomic, proteomic, or other molecular information to identify specific biomarkers linked to disease. This enables the stratification of patients and the selection of targeted therapies, moving beyond a one-size-fits-all approach to medicine. Oncology analysis remains the dominant application, holding the largest share of revenue. However, the infectious disease detection segment is expanding rapidly, driven by advancements in Next-Generation Sequencing and Digital PCR technologies.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) dictate the stringent validation requirements for diagnostic assays. In parallel, China's NMPA is establishing its own fast-track approval pathways for innovative diagnostic tools, influencing market access strategies. Stakeholder success will hinge on navigating disparate reimbursement policies and managing the complex data privacy requirements associated with patient genomic information.
Market Dynamics
The convergence of high-throughput sequencing with advanced bioinformatics is the central force shaping the precision diagnostics market. This synthesis enables the analysis of complex genomic and proteomic data, moving diagnostics from simple detection to predictive and prognostic insights.
Growth Catalysts
- Expanded Oncology Applications:Pharmaceutical companies are increasingly integrating companion diagnostics into clinical trial designs to stratify patient populations, accelerating drug development timelines and improving success rates for targeted therapies.
- Advancing Sequencing Technology:The maturation of Next-Generation Sequencing and Digital PCR technologies enables more sensitive, rapid, and cost-effective testing, expanding applications beyond oncology into infectious diseases and rare genetic disorders.
- Regulatory Streamlining:Fast-track approval pathways, such as those established by China's NMPA and the US FDA, reduce the time-to-market for innovative diagnostic assays, incentivizing research and development investment.
Market Restraints
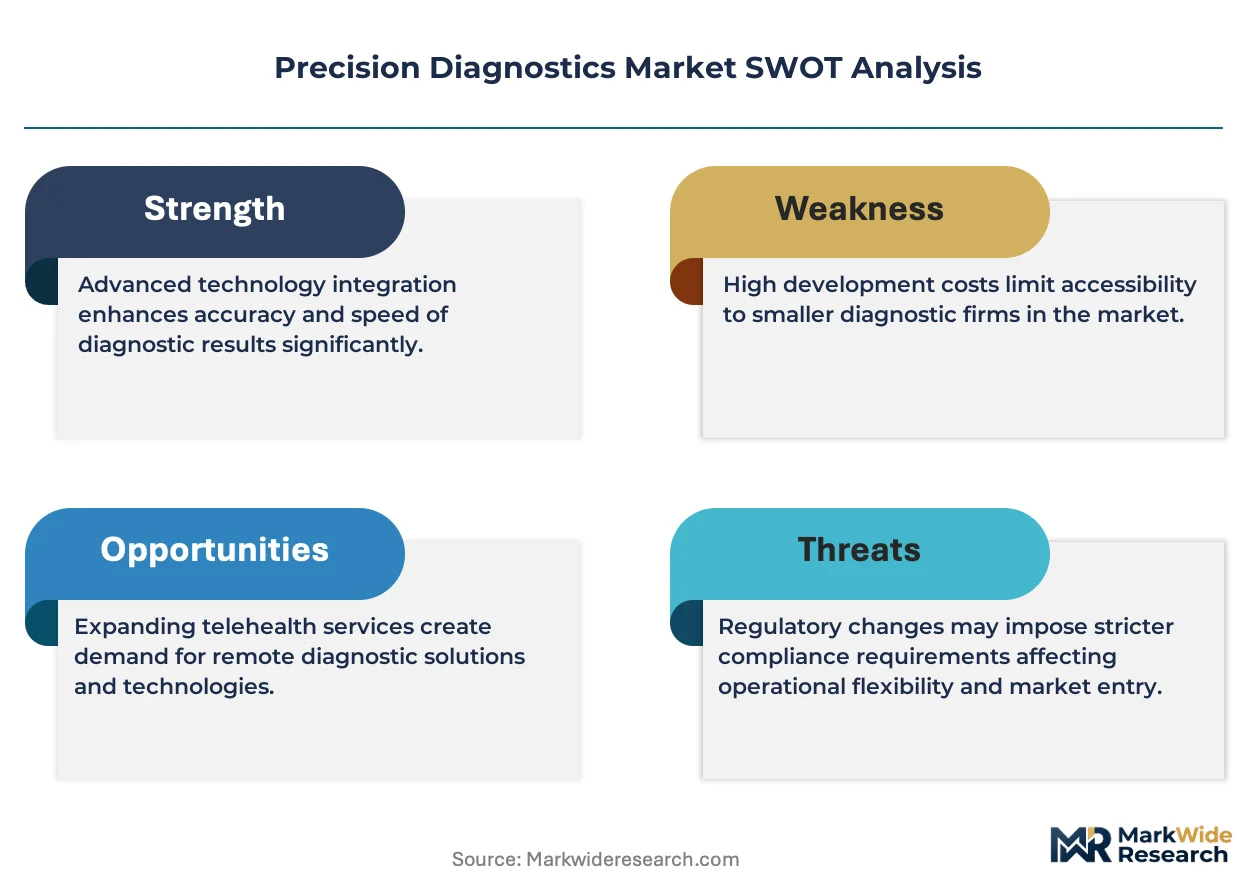
- Reimbursement Uncertainty:Inconsistent and fragmented reimbursement policies from payers in the United States and across European national health systems create significant financial barriers to the adoption of novel, high-cost diagnostic tests.
- High Capital Expenditure:The initial investment required for acquiring and maintaining advanced sequencing platforms and associated bioinformatics infrastructure remains a substantial barrier for smaller laboratories and hospitals.
- Technical Standardization Gaps:A lack of universally accepted standards for data analysis and interpretation across different diagnostic platforms can lead to variability in test results, complicating clinical decision-making.
Strategic Opportunities
- Emerging Market Penetration:There is significant opportunity in building diagnostic infrastructure in large, developing economies like India and Brazil, where a growing middle class is demanding access to advanced healthcare.
- Multi-Omics Integration:Combining genomic, proteomic, transcriptomic, and metabolomic data into integrated multi-omics assays offers a more comprehensive understanding of disease biology, enabling superior biomarker discovery.
- AI-Powered Diagnostics:Applying machine learning algorithms to large-scale patient datasets can uncover novel biomarkers and predictive signatures that are not discernible through conventional analysis, improving diagnostic accuracy.
Industry Challenges
- Specialized Talent Shortage:A critical scarcity of trained bioinformaticians and genetic counselors capable of interpreting complex genomic data and communicating results to clinicians and patients constrains market growth.
- Data Privacy and Security:Ensuring the security of sensitive patient genomic data while complying with stringent regulations like Europe's GDPR and the US's HIPAA presents a complex operational and technical challenge.
- System Integration Complexity:Integrating new, sophisticated diagnostic platforms with legacy Laboratory Information Systems and Electronic Health Record systems within hospitals is often a difficult and resource-intensive process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Diagnostics Market |
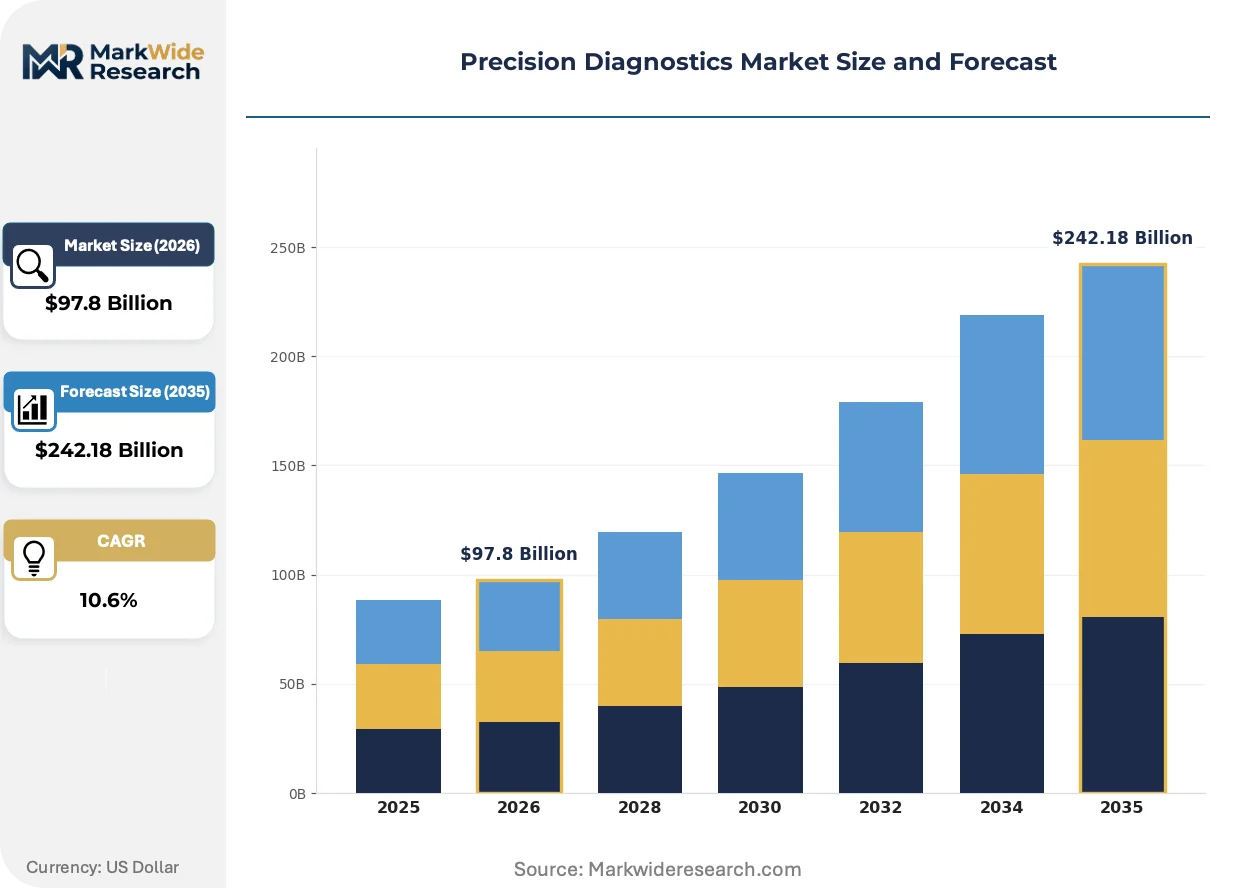
| Market Size in 2026 | $97.8 Billion |
| Market Size in 2035 | $242.18 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genomic Sequencing, Proteomics, Imaging Diagnostics, Biomarker Testing, Molecular Diagnostics, Cytogenetics Application: Oncology Analysis, Infectious Disease Detection, Genetic Disorder Screening, Cardiovascular Assessments, Neurological Evaluations, Rare Diseases End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Specialty Clinics, Academic Centers, Biotechnology Firms Technology: Next-Generation Sequencing, Digital PCR, Mass Spectrometry, Microarrays, Flow Cytometry, Imaging Mass Cytometry |
| Companies Covered | F. Hoffmann-La Roche, Thermo Fisher Scientific, Illumina, QIAGEN, Abbott Laboratories, Agilent Technologies, Quest Diagnostics, Siemens Healthineers, Guardant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Diagnostics Market Strategic Shifts & Innovations
Data-intensive methodologies are fundamentally reconfiguring the development and deployment of diagnostic tools. The market is shifting from single-marker tests toward complex, multi-analyte assays that require sophisticated computational analysis to yield clinically actionable insights, altering the competitive landscape.
Technology Evolution
Multi-cancer early detection tests analyze biomarkers like cell-free DNA in a single blood sample to screen for multiple types of cancer simultaneously. Large-scale population health initiatives and forward-thinking employers are beginning to pilot these assays for asymptomatic screening. This technology is rewriting the established paradigm of single-organ cancer screening, shifting focus towards pan-cancer surveillance and early intervention strategies.
Regulatory Shift
The European Union's In Vitro Diagnostic Regulation (IVDR) mandates more stringent requirements for clinical evidence, performance evaluation, and post-market surveillance. This regulatory overhaul increases the compliance burden for manufacturers, demanding a higher standard of proof for assay validity and utility. High-risk tests and companion diagnostics are most affected, compelling developers to invest more heavily in clinical validation to maintain market access in Europe.
Demand-Side Shift
A clear shift toward decentralized testing is moving sample analysis away from centralized reference laboratories and closer to the point of care. This trend challenges the established business models of large lab corporations, creating space for portable and rapid diagnostic platforms. The change is most visible in infectious disease screening and chronic disease monitoring, particularly in regions across North America and Europe seeking to improve healthcare access.
Precision Diagnostics Market Segmentation
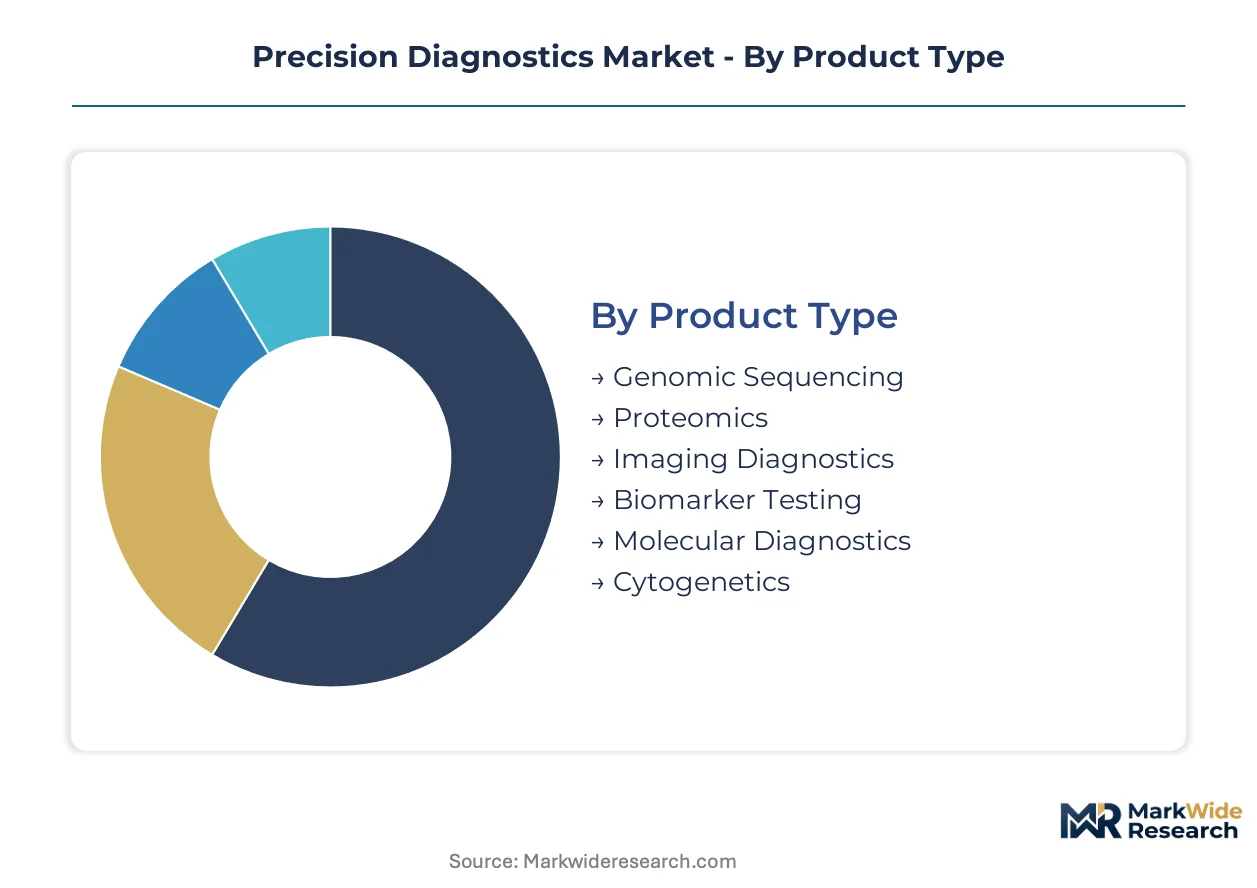
Precision diagnostics market segmentation reveals distinct value propositions across various product types, applications, end users, and underlying technologies. Understanding these divisions is crucial for stakeholders to align product development and market entry strategies effectively. These segments reflect diverse clinical needs and technological advancements.
Product Type:
Buyers prioritize specific product types based on the diagnostic information required for clinical decision-making and disease management.
- Genomic Sequencing:This segment encompasses technologies for analyzing DNA and RNA sequences to identify genetic variations linked to disease. Demand concentrates in oncology analysis and rare genetic disorder screening within advanced research institutes in the United States.
- Molecular Diagnostics:These assays detect specific nucleic acid sequences, such as DNA or RNA, indicative of pathogens or genetic predispositions. Infectious disease detection and companion diagnostics for targeted therapies drive adoption in diagnostic laboratories across Europe.
- Proteomics:Proteomics involves the large-scale study of proteins, enabling biomarker discovery and validation for various diseases. Pharmaceutical companies utilize proteomics for drug target identification.
- Imaging Diagnostics:This category includes advanced imaging techniques that integrate molecular information for enhanced diagnostic accuracy. Specialty clinics leverage these tools for detailed disease staging.
- Biomarker Testing:Biomarker tests identify specific biological indicators in patient samples for disease presence, progression, or treatment response. Academic centers employ these for early disease detection.
- Cytogenetics:Cytogenetics focuses on the study of chromosomes to detect structural and numerical abnormalities associated with genetic disorders and cancers. Diagnostic laboratories use cytogenetics for prenatal screening.
Volume sits with Molecular Diagnostics; growth tilts toward Genomic Sequencing.
Application:
The maturity of disease understanding shapes the application of precision diagnostics, influencing investment and clinical adoption patterns.
- Oncology Analysis:This application involves using molecular information to characterize tumors, stratify patients, and guide targeted cancer therapies. Pharmaceutical companies in China integrate oncology analysis into clinical trials for drug development.
- Infectious Disease Detection:Precision diagnostics identify pathogens quickly and accurately, facilitating rapid treatment decisions and outbreak management. Demand is strong in North America and Europe for point-of-care testing.
- Genetic Disorder Screening:These tests identify inherited genetic conditions, enabling early intervention or reproductive planning. Diagnostic laboratories offer comprehensive panels for newborn screening.
- Cardiovascular Assessments:Molecular biomarkers provide insights into cardiovascular disease risk, progression, and treatment response. Specialty clinics use these for personalized patient management.
- Neurological Evaluations:Precision diagnostics aid in the early detection and differential diagnosis of neurological disorders like Alzheimer's and Parkinson's disease. Research institutes develop novel assays.
- Rare Diseases:Genomic sequencing technologies are critical for diagnosing rare genetic conditions, often after long diagnostic odysseys. Academic centers lead research in this area.
Oncology Analysis maintains its market leadership, while Infectious Disease Detection exhibits the steepest expansion trajectory.
End User:
End users select precision diagnostic solutions based on their operational scale, patient care models, and research objectives.
- Diagnostic Laboratories:These facilities perform a wide range of precision diagnostic tests, often serving multiple healthcare providers. Centralized reference laboratories in the United States drive high-throughput sequencing adoption.
- Pharmaceutical Companies:These firms integrate precision diagnostics into drug discovery, development, and companion diagnostic strategies. European pharmaceutical companies leverage these tools to stratify patient populations for clinical trials.
- Research Institutes:Academic and independent research centers conduct fundamental and translational research using precision diagnostic tools. These institutes in India focus on biomarker discovery.
- Specialty Clinics:Clinics focusing on specific medical areas, such as oncology or cardiology, utilize precision diagnostics for personalized patient management. These clinics often prioritize rapid turnaround times.
- Academic Centers:University-affiliated medical centers combine patient care with research and education, fostering innovation in precision diagnostics. Academic centers in Japan contribute to technology validation.
- Biotechnology Firms:These companies develop and commercialize novel precision diagnostic assays and platforms. Biotechnology firms frequently partner with pharmaceutical companies.
Diagnostic Laboratories constitute the primary consumer base, with Pharmaceutical Companies driving significant innovation.
Technology:
Technology adoption is often dictated by the balance between analytical sensitivity, throughput, and capital investment for diagnostic platforms.
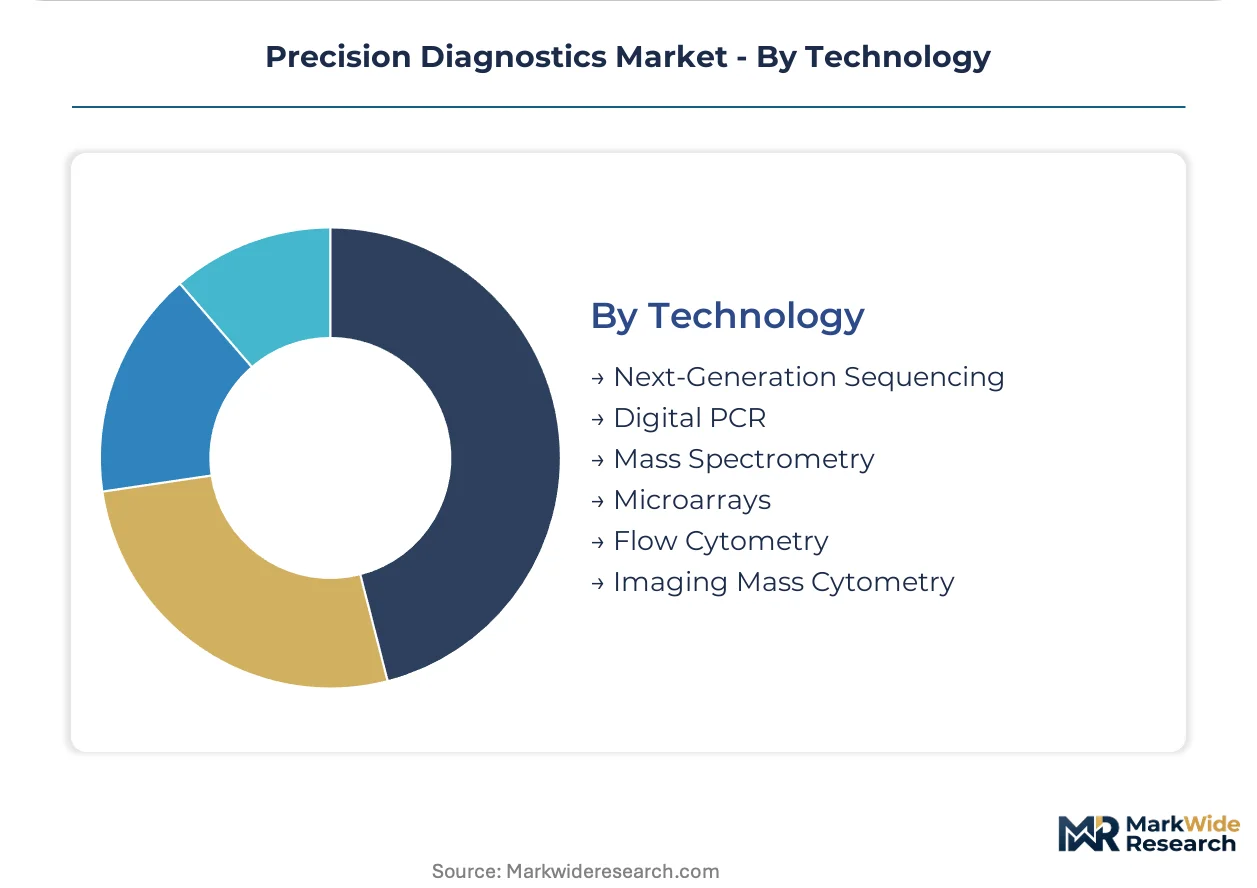
- Next-Generation Sequencing:This high-throughput technology allows for rapid and cost-effective sequencing of entire genomes or specific DNA/RNA regions. Research institutes and large diagnostic laboratories in the US utilize NGS for comprehensive genomic profiling.
- Digital PCR:Digital PCR offers absolute quantification of nucleic acids, providing high sensitivity for detecting rare mutations and low-abundance targets. Liquid biopsy applications in oncology are driving its adoption in specialty clinics.
- Mass Spectrometry:Mass spectrometry identifies and quantifies molecules based on their mass-to-charge ratio, used for proteomic analysis and biomarker discovery. Pharmaceutical companies employ mass spectrometry for drug metabolism studies.
- Microarrays:Microarrays enable simultaneous analysis of thousands of genetic markers, useful for gene expression profiling and genotyping. Academic centers use microarrays for large-scale genetic studies.
- Flow Cytometry:Flow cytometry rapidly measures and analyzes physical and chemical characteristics of cells or particles. Diagnostic laboratories apply flow cytometry for immunology and hematology testing.
- Imaging Mass Cytometry:This technology combines imaging with mass spectrometry to provide highly multiplexed spatial analysis of tissues. Research institutes leverage IMC for detailed tumor microenvironment characterization.
Next-Generation Sequencing forms the technological bedrock, while Digital PCR demonstrates rapid uptake in niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina exemplifies a special economic zone driving precision diagnostics concentration. These zones foster collaborative ecosystems, accelerating innovation and commercialization. Such focused development attracts investment and specialized talent.
United States
Demand for precision diagnostics in the United States stems from extensive oncology applications and widespread screening for rare genetic disorders. The US FDA dictates stringent validation requirements for novel diagnostic assays. Boston-Cambridge's biotech cluster drives significant innovation, with academic centers and startups pioneering new multi-omics technologies.
Germany
German demand for molecular diagnostics is strong, particularly for companion diagnostics supporting targeted therapies. The European Medicines Agency (EMA) and IVDR impose rigorous compliance burdens on manufacturers. Munich's vibrant medical technology sector fosters collaboration between research institutes and diagnostic companies, developing advanced platforms.
China
China's market expansion for precision diagnostics is propelled by extensive oncology analysis and infectious disease detection needs. The NMPA establishes fast-track approval pathways, influencing market access strategies for innovative tools. The Yangtze River Delta region concentrates pharmaceutical companies and diagnostic manufacturers, accelerating product development.
Japan
Japanese healthcare systems prioritize precision diagnostics for early disease detection, especially in neurological evaluations and genetic screening. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous oversight of diagnostic assay validity and utility. Tokyo's academic centers contribute significantly to technology validation, integrating new diagnostic tools into clinical practice.
India
India presents a substantial opportunity for precision diagnostics, driven by infectious disease detection and genetic disorder screening in a growing population. The CDSCO governs diagnostic product approvals, shaping market entry for domestic and international players. Bengaluru's burgeoning biotechnology sector contains research institutes focusing on biomarker discovery and localized diagnostic solutions.
Precision Diagnostics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments of the precision diagnostics market. The landscape features a tiered structure, with established multinational corporations alongside agile biotechnology startups. Strategic archetypes include integrated pharmaceutical-diagnostics players, pure-play sequencing technology providers, and specialized liquid biopsy firms. Market participants frequently engage in strategic partnerships and portfolio diversification, aiming to enhance their offerings and expand geographic reach.
Within the integrated pharmaceutical and diagnostics tier, Switzerland-based F. Hoffmann-La Roche exemplifies a strategy of leveraging a combined portfolio for market advantage. US-based Illumina, Inc. occupies a dominant position as a core sequencing technology provider, underpinning numerous diagnostic assays. Guardant Health, also US-based, represents a specialized pure-play firm focusing exclusively on non-invasive liquid biopsy testing. These entities anchor distinct segments, driving innovation through their specific business models and technological strengths.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Thermo Fisher Scientific |
| Illumina |
| QIAGEN |
| Abbott Laboratories |
| Agilent Technologies |
| Quest Diagnostics |
| Siemens Healthineers |
| Guardant Health |
Cost & Logistics Intelligence
The cost of high-purity nucleic acid synthesis reagents directly impacts the pricing of precision diagnostic assays. This fundamental input cost then influences the tiered pricing structures for advanced genomic sequencing and molecular diagnostic services offered to end-users.
Pricing Analysis
Short lead times for rapid diagnostic results command premium pricing in precision diagnostics. Value-based pricing dominates for highly specific companion diagnostics, reflecting their clinical utility in guiding targeted therapies. Assay sensitivity and US FDA regulatory approval status are key price differentiation drivers. Pricing pressure stems from increasing competition in high-volume segments like infectious disease detection. Academic centers are often more price-sensitive than pharmaceutical companies, which prioritize accuracy and speed for drug development.
Supply Chain Analysis
Dual-sourcing mandates for critical reagents and consumables are prevalent in precision diagnostics. Supply of specialized enzymes and oligonucleotides centers in the United States and Germany. China also provides significant volumes of general lab plastics. The industry relies heavily on high-purity nucleotides and specialized microfluidic components. Single-source vulnerability for proprietary sequencing chemistries presents a structural risk. Distribution runs through a network of specialized medical distributors and direct sales channels to diagnostic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precision diagnostics market is navigating a critical technology-transition phase. Next-Generation Sequencing is rapidly displacing traditional Sanger sequencing methods for comprehensive genomic profiling, fundamentally reshaping diagnostic workflows.
For Market Incumbents:Anticipate the increasing demand for integrated multi-omics solutions by investing in bioinformatics capabilities. Consolidate market share through strategic acquisitions of specialized liquid biopsy firms. The rapid emergence of AI-powered diagnostic platforms poses a threat to legacy data analysis approaches. Focused R&D in early disease detection assays will reinforce market leadership.
For New Entrants and Emerging Players:Academic research consortia offer an entry point for novel biomarker discovery platforms. Target underpenetrated markets in developing economies like India for infectious disease detection. The infectious disease segment in North America shows strong demand for rapid, decentralized testing. Partner with local diagnostic laboratories to navigate regional regulatory landscapes and establish trust.
For Investors and Strategic Acquirers:Distressed-cycle entries favor technology-agnostic platform providers in Europe, where IVDR compliance costs are high. The market offers sustained long-term growth driven by an aging global population and increasing prevalence of chronic diseases. Prioritize firms with robust intellectual property in AI-powered diagnostics or multi-cancer early detection. Watch for consolidation among mid-sized diagnostic companies as a signal of market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Predictive Diagnostics | Uncovers novel biomarkers and predictive signatures, enhancing diagnostic accuracy for complex diseases. |
| Expand Multi-Omics Assay Portfolio | Provides a comprehensive understanding of disease biology, enabling superior biomarker discovery for pharmaceutical companies. |
| Secure NMPA Fast-Track Approval | Accelerates market access for innovative diagnostic tools in China, influencing competitive positioning. |
| Invest in Decentralized Testing Platforms | Shifts sample analysis closer to the point of care, improving healthcare access in North America and Europe. |
| Strategic Partnerships with Academic Centers | Fosters innovation and technology validation, integrating new diagnostic tools into clinical practice in Japan. |
Research Approach
Trade association data, regulatory filings with the US FDA and EMA, and scientific literature anchored secondary inputs. This was complemented by primary interviews with diagnostic laboratory directors, pharmaceutical R&D executives, genetic counselors, and hospital procurement managers. Key secondary sources included company annual reports, patent databases, and clinical trial registries. A rigorous bottom-up and top-down triangulation approach validated all findings and data points for consistency.
Market sizing and forecasting were modeled at granular levels across product type, application, end user, technology, and regional segments. The analytical framework projected compound annual growth rates over the projection horizon, considering historical trends and future demand drivers. Key segmentation dimensions included genomic sequencing, oncology analysis, diagnostic laboratories, and Next-Generation Sequencing. Industry-specific forecast inputs included advancements in sequencing cost reduction and regulatory approval timelines for novel assays.
Caveats apply where unforeseen technological breakthroughs or significant shifts in reimbursement policies could materially shift the outlook. Forecasts reflect current assumptions regarding regulatory changes and healthcare spending patterns. Deviation in clinical trial success rates for targeted therapies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
Global Immunoprotein Diagnostic Testing Market
Diagnostics
Global Rapid Diagnostic Kits Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Veterinary Chemistry Analyzers Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
North America Molecular Diagnostics Market