
 Heart Monitoring Devices Market | 2026-2036
Heart Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Monitoring Devices Market Analytics
Home care settings are redrawing procurement patterns in cardiac monitoring as payers push remote patient management over facility-based observation. Medtronic leverages its implantable portfolio to anchor premium device contracts with integrated health systems. Boston Scientific Corporation competes through specialized electrophysiology workflows that streamline arrhythmia detection in hospital cath labs.
Heart monitoring devices encompass instruments that capture, record, and transmit cardiac electrical activity, blood pressure, or rhythm data through electrodes, pressure sensors, or photoplethysmography with sampling rates typically exceeding 250 Hz for diagnostic-grade ECG. These systems serve to detect ischemia, arrhythmias, or hemodynamic instability before clinical decompensation occurs. Wearable monitors and mobile health applications are capturing margin pools as consumers and physicians seek continuous ambulatory data without facility dependency, while Holter monitors retain structural importance in post-operative care protocols where extended multi-lead recording remains the clinical standard. ECG monitors occupy the largest installed base but face substitution pressure from patch-based wireless sensors that eliminate lead-wire artifacts during patient movement.
FDA premarket notification requirements and ISO 13485 quality management standards govern device design controls and post-market surveillance obligations for manufacturers seeking US market access, while the EU Medical Device Regulation imposes stricter clinical evidence thresholds for software-as-a-medical-device classifications including AI diagnostic modules. These frameworks elevate compliance costs but also create barriers that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must weigh capital deployment between cloud-based telemetry platforms and disposable patch economics as reimbursement models shift toward episode-based accountability.
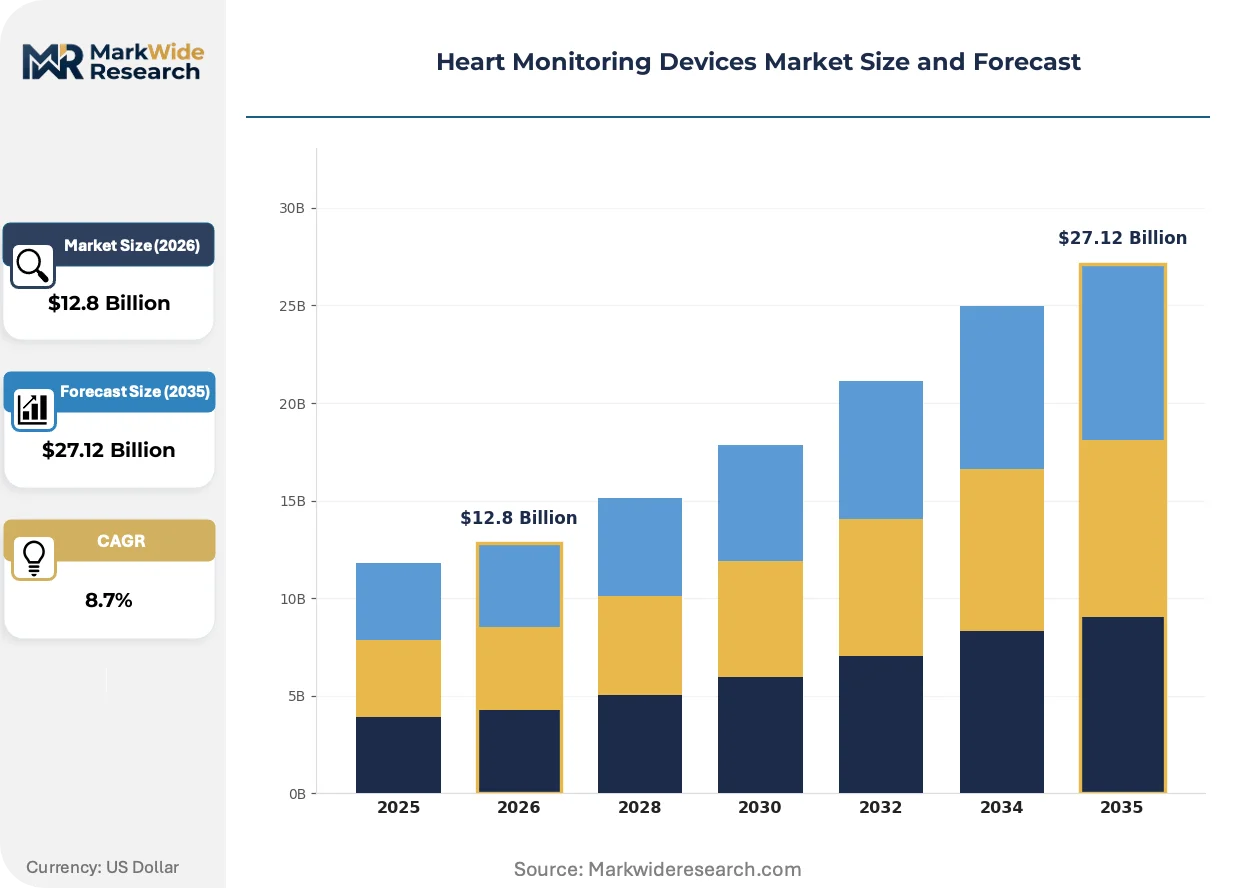
Market Dynamics
The transition from facility-based cardiac observation to ambulatory monitoring is compressing hospital capital budgets while expanding recurring revenue streams for connected device platforms. This structural pivot reconfigures procurement authority from cath lab directors to health system telemedicine committees.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage for wearable cardiac monitors has broadened patient access beyond traditional Holter indications, accelerating substitution of multi-day patch monitors for in-patient telemetry.
- AI-enabled diagnostic workflows:FDA 510(k) clearance pathways for algorithm-based ECG interpretation are compressing time-to-diagnosis for atrial fibrillation detection in emergency departments.
- Home care settings:Payer pressure for remote patient management over facility-based observation is redrawing procurement patterns toward disposable patch economics.
Market Restraints
- Clinical validation requirements:EU MDR imposes stricter clinical evidence thresholds for software-as-a-medical-device classifications, elevating compliance costs for algorithm-based diagnostic modules.
- Semiconductor supply concentration:Photoplethysmography sensor fabrication depends on concentrated Asian foundry capacity, creating input volatility for wearable monitor production.
- Lead-wire artifact persistence:Traditional Holter monitors retain structural importance in post-operative protocols where extended multi-lead recording remains the clinical standard, limiting full substitution.
Strategic Opportunities
- Rural health system penetration:Underpenetrated United States markets present white space for cloud-based telemetry platforms serving critical access hospitals lacking on-site electrophysiology expertise.
- Consumer channel expansion:Direct-to-patient distribution models bypass traditional durable medical equipment suppliers, capturing margin pools from wellness-oriented buyers seeking continuous ambulatory data.
- Episode-based accountability:Value-based care frameworks penalizing readmission create procurement incentives for integrated monitoring contracts spanning implantable through wearable device portfolios.
Industry Challenges
- Interoperability architecture:Integration complexity with legacy electronic health record systems delays deployment timelines for cloud-native telemetry platforms in established health systems.
- Regulatory affairs capacity:ISO 13485 quality management certification and FDA post-market surveillance obligations strain mid-tier manufacturers lacking dedicated compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Monitoring Devices Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Implantable Loop Recorders, Wearable Monitors, ECG Monitors End User: Hospitals, Home Care Settings, Rehabilitation Centers, Clinics Technology: Wireless Sensors, Mobile Health Applications, Telemetry Devices, Cloud-based Solutions Application: Arrhythmia Detection, Blood Pressure Monitoring, Heart Rate Monitoring, Post-operative Care |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Koninklijke Philips N.V., GE HealthCare, BIOTRONIK, ZOLL Medical Corporation, iRhythm Technologies, AliveCor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Monitoring Devices Market Evolving Landscape
Wireless patch-based sensors are actively displacing traditional wired ECG monitors across ambulatory diagnostic applications. This technology convergence is compressing hospital telemetry unit utilization while expanding data capture windows beyond conventional 24-48 hour Holter limits.
Photoplethysmography-enabled wearables is displacing single-lead ECG monitors in consumer and preventive screening segments. Health systems seeking to reduce telemetry nursing costs are adopting these devices for low-acuity cardiac monitoring, though diagnostic-grade arrhythmia detection still requires electrode-based systems for regulatory submission.
FDA breakthrough device designation pathways for AI diagnostic algorithms are accelerating market entry for machine-learning ECG interpretation tools. The industrial consequence compresses development timelines from concept to clinical deployment, with electrophysiology software vendors restructuring regulatory affairs teams to pursue parallel 510(k) submissions across multiple arrhythmia indications.
Subscription-based service contracts are displacing capital equipment purchases in health system procurement of cardiac monitoring infrastructure. Device manufacturers are responding with integrated hardware-software-data bundles that shift revenue recognition from upfront sale to recurring per-patient-per-month fees, most visible in United States integrated delivery networks managing total cost of care contracts.
Heart Monitoring Devices Market Segmentation
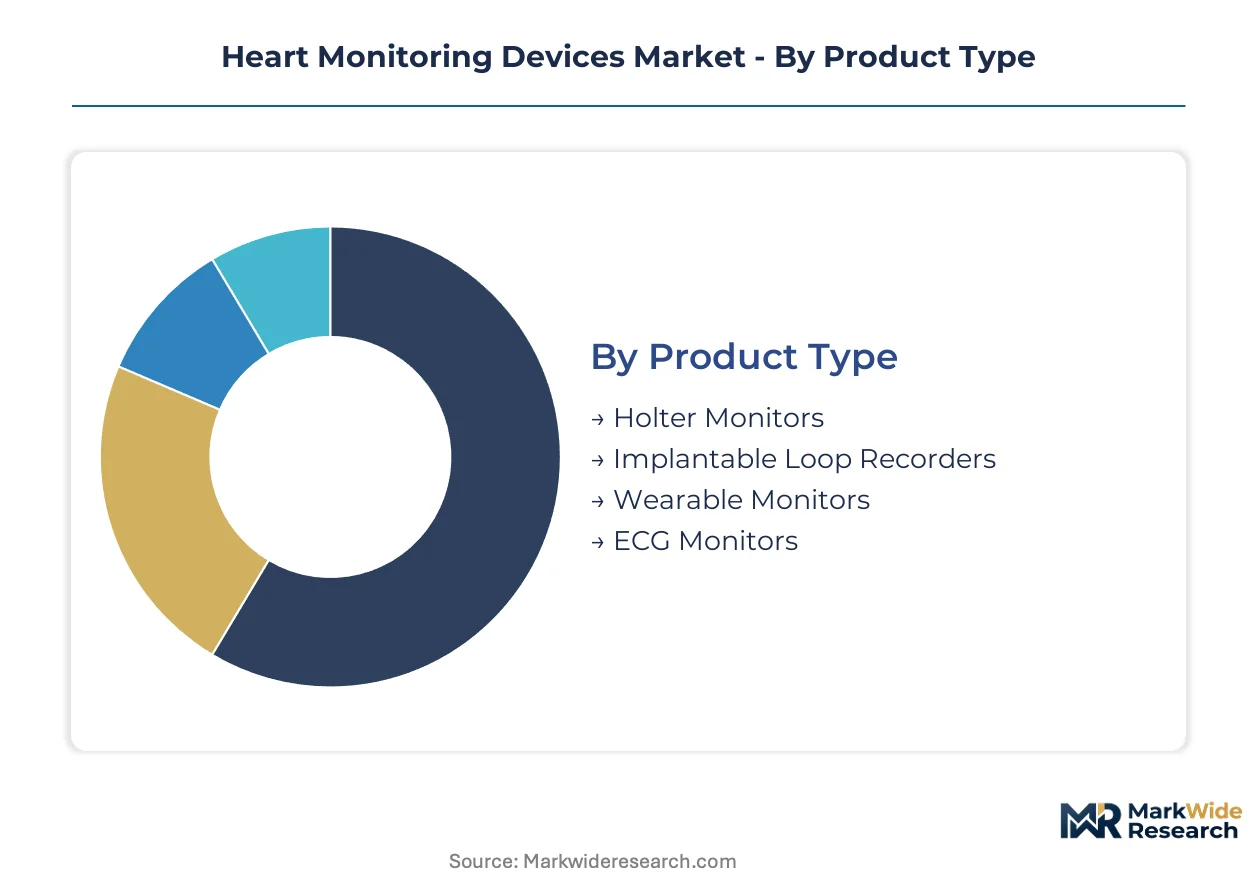
Segmentation in heart monitoring devices reveals how procurement authority is shifting from acute care facilities toward ambulatory and home-based channels. Understanding these divisions helps manufacturers align R&D investments with reimbursement pathways and regulatory requirements that vary sharply across product categories.
Product Type:
Premium pricing concentrates in implantable systems where surgical placement creates recurring follow-up revenue streams, while disposable patch economics dominate high-volume ambulatory diagnostics.
- Holter Monitors:Multi-lead wired systems sample cardiac electrical activity at 250+ Hz for diagnostic-grade arrhythmia detection. Hospital cath labs in the United States specify these for post-operative protocols where lead-wire stability outweighs patient mobility constraints.
- Implantable Loop Recorders:Subcutaneous devices provide continuous monitoring over 2-3 year lifespans with wireless data transmission to cloud platforms. Integrated health systems bundle these with electrophysiology service contracts under episode-based reimbursement models.
- Wearable Monitors:Patch-based wireless sensors eliminate lead artifacts during patient movement.
- ECG Monitors:Traditional electrode-based systems retain installed base in emergency departments.
The dominant share belongs to ECG Monitors, while Wearable Monitors is closing the gap fastest.
End User:
Volume concentration follows payer reimbursement codes, with Medicare expansion for remote patient management redirecting procurement toward non-facility settings.
- Hospitals:Inpatient telemetry units and emergency departments drive capital equipment purchases for acute arrhythmia detection. FDA 510(k) clearance requirements for diagnostic-grade devices keep procurement committees focused on established vendors with regulatory affairs infrastructure.
- Home Care Settings:Remote patient monitoring programs capture patients discharged under value-based care frameworks. Medicare reimbursement codes for wearable cardiac monitoring in the United States have broadened access beyond traditional facility-based observation.
- Rehabilitation Centers:Post-acute facilities monitor hemodynamic recovery during cardiac rehabilitation protocols.
- Clinics:Outpatient cardiology practices deploy patch monitors for intermittent symptom correlation.
Hospitals retain the largest procurement volume, though Home Care Settings is expanding most quickly as telemedicine committees gain purchasing authority.
Technology:
Development timelines compress where FDA breakthrough device pathways apply, favoring algorithm-based diagnostics over hardware-intensive sensor platforms.
- Wireless Sensors:Photoplethysmography-enabled patches transmit continuous data without lead-wire constraints. Asian foundry capacity for sensor fabrication creates supply volatility that manufacturers hedge through dual-sourcing agreements.
- Mobile Health Applications:Smartphone-integrated platforms capture consumer-oriented buyers seeking wellness data outside clinical workflows. Direct-to-patient distribution models bypass durable medical equipment suppliers.
- Telemetry Devices:Real-time transmission systems serve critical access hospitals lacking on-site electrophysiology expertise.
- Cloud-based Solutions:Subscription revenue models displace capital purchases in United States integrated delivery networks.
Wireless Sensors command the dominant technology position, while Mobile Health Applications shows the steepest expansion trajectory.
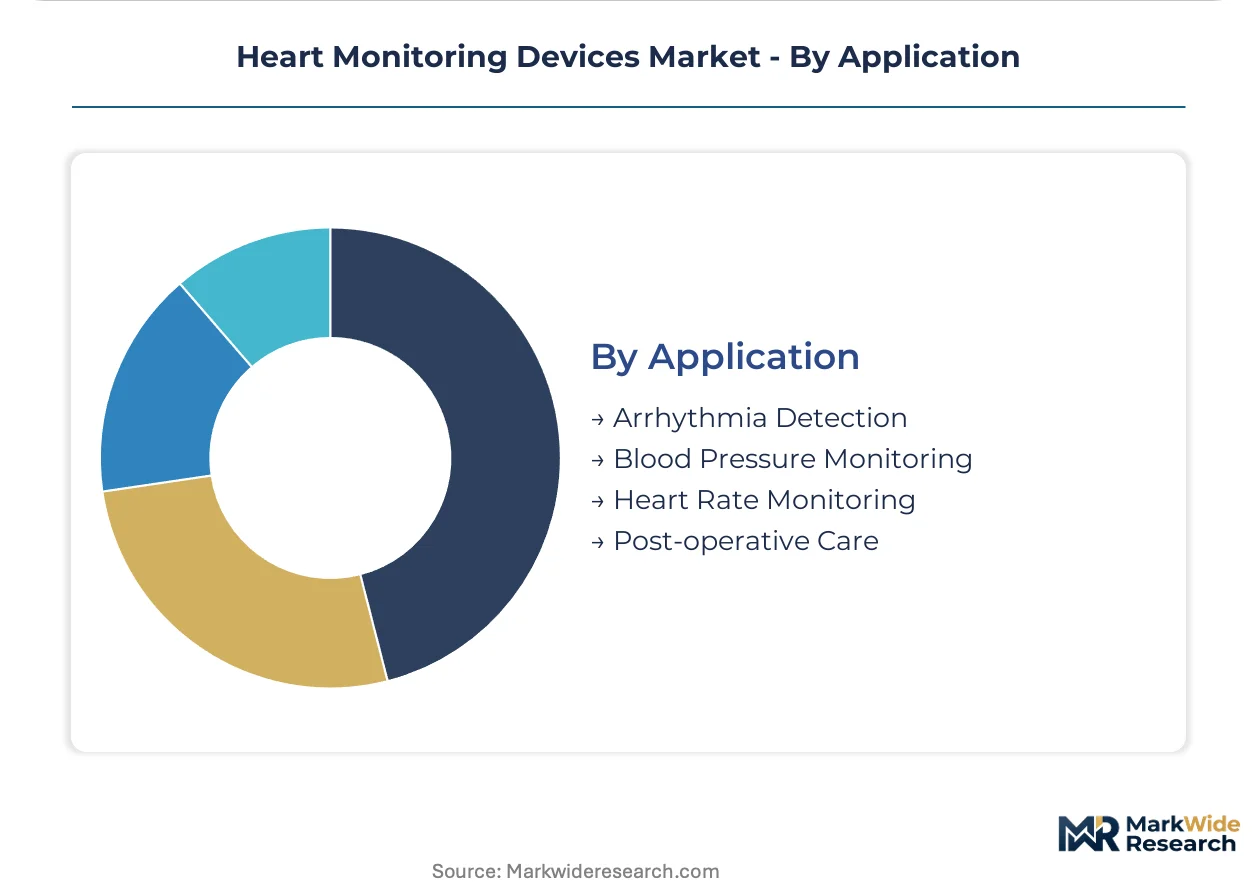
Application:
Clinical urgency determines price elasticity, with acute detection applications commanding premium reimbursement over preventive screening.
- Arrhythmia Detection:AI-enabled ECG interpretation algorithms accelerate atrial fibrillation identification in emergency departments. FDA clearance pathways for machine-learning diagnostics compress development timelines from concept to deployment.
- Post-operative Care:Extended multi-lead recording protocols following cardiac surgery specify Holter monitors for hemodynamic surveillance. Hospital readmission penalties under value-based care frameworks create procurement incentives for continuous monitoring contracts.
- Blood Pressure Monitoring:Cuffless optical sensors integrated into wearables capture ambulatory hypertension data.
- Heart Rate Monitoring:Consumer-grade photoplethysmography serves wellness segments with lower regulatory barriers.
Arrhythmia Detection holds the dominant application share, while Post-operative Care is gaining share fastest as surgical volumes recover and readmission penalties tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's 510(k) clearance infrastructure underwrites United States dominance in cardiac device commercialization, while Medicare reimbursement pathways accelerate ambulatory monitoring adoption. Germany's TÜV certification hubs and Japan's PMDA review capacity anchor regulatory throughput for EU and Asia-Pacific market entry respectively.
United States
Medicare reimbursement codes for wearable cardiac monitors and CMS readmission penalty frameworks drive procurement toward remote patient management. FDA breakthrough device designation pathways compress AI-enabled ECG algorithm timelines from concept to deployment. The Minneapolis medical device cluster concentrates electrophysiology expertise and integrated health system contracting.
Germany
Hospital system consolidation under Diagnosis-Related Group reimbursement creates demand for cloud-based telemetry platforms serving multi-site networks. EU MDR clinical evidence requirements for software-as-a-medical-device elevate compliance costs for algorithm-based diagnostics. The Baden-Württemberg industrial corridor hosts precision sensor fabrication for photoplethysmography components.
Japan
Aging demographics and Ministry of Health, Labour and Welfare remote monitoring reimbursement expansion accelerate patch-based wireless sensor adoption. PMDA Sakigake designation pathways fast-track AI diagnostic algorithms for atrial fibrillation detection. The Tokyo-Osaka medical technology corridor concentrates electrophysiology service contract negotiations.
China
National Health Commission directives on tiered diagnosis and treatment systems push cardiac monitoring capacity toward county-level hospitals. NMPA innovation approval pathways for AI-enabled medical devices compress registration timelines for algorithm-based ECG interpretation. The Yangtze River Delta manufacturing basin dominates photoplethysmography sensor assembly.
India
Central Drugs Standard Control Organization medical device rules and Ayushman Bharat digital health mission expansion create procurement incentives for low-cost wearable monitors. CDSCO streamlined registration for software-based diagnostics accelerates mobile health application market entry. The Bengaluru health technology cluster concentrates telemedicine platform development.
Heart Monitoring Devices Market Competitive Landscape
Listed leaders compete with private specialists across regulatory affairs capacity and integrated service contract scale. The vendor base stratifies into three tiers: diversified conglomerates with implantable portfolios, electrophysiology-focused mid-caps, and algorithm-native software vendors. Dominant competitive moves include cloud-based telemetry platform acquisitions and subscription-based service contract restructuring toward per-patient-per-month revenue recognition.
Within the diversified device tier, Medtronic and Abbott occupy positions anchoring premium implantable system contracts with integrated health systems. Boston Scientific Corporation exemplifies the electrophysiology-specialist archetype, competing through cath lab workflow integration. Among algorithm-native entrants, iRhythm Technologies and AliveCor represent the diagnostic software segment pursuing FDA 510(k) clearances for AI-enabled arrhythmia detection.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Koninklijke Philips N.V. |
| GE HealthCare |
| BIOTRONIK |
| ZOLL Medical Corporation |
| iRhythm Technologies |
| AliveCor |
| Others |
Value Network & Pricing Analysis
Per-patient-per-month subscription contracts anchor health system procurement, locking in multi-year revenue visibility for device manufacturers while securing predictable supply allocations for disposable patch components. This contract structure concentrates pricing power with integrated delivery networks managing total cost of care agreements under CMS reimbursement frameworks.
Pricing Analysis
Volume-discount tiering structures separate premium implantable systems from standard wearable monitors and economy-grade consumer devices. Three-tier pricing differentiation reflects FDA clearance status, with 510(k)-cleared diagnostic systems commanding sustained premiums over wellness-oriented photoplethysmography wearables. Pricing pressure stems from Medicare reimbursement compression for remote patient monitoring codes, squeezing margins on high-volume patch deployments. Hospital procurement committees exhibit lowest price sensitivity for implantable loop recorders bundled with electrophysiology service contracts, while direct-to-consumer channels face acute elasticity for fitness-oriented heart rate monitors.
Supply Chain Analysis
Taiwan and South Korea anchor photoplethysmography sensor wafer fabrication, while China dominates final assembly of disposable patch monitors and electrode manufacturing. Raw material dependencies span medical-grade silicones for biocompatible adhesives, lithium-polymer cells for extended-wear power, and specialized conductive polymers for dry electrode interfaces. Single-source vulnerability concentrates in Asian foundry capacity for PPG sensor chips, exposing manufacturers to geopolitical disruption or export restriction. Distribution runs through group purchasing organizations for hospital systems, direct-to-patient e-commerce for consumer wearables, and durable medical equipment suppliers for home care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heart monitoring devices constitute a high-growth disruption as FDA breakthrough device pathways compress AI-enabled diagnostic timelines from concept to clinical deployment. This regulatory inflection accelerates substitution of algorithm-based interpretation for traditional hardware-intensive telemetry.
For Market Incumbents: Shield implantable portfolio margins by deepening electrophysiology service contract penetration across integrated delivery networks. Prioritize backward integration into cloud-based telemetry platform development to defend against software-native entrants capturing recurring revenue streams. Accelerate ISO 13485 certification investments for algorithm modules ahead of EU MDR enforcement tightening.
For New Entrants and Emerging Players: Anchor in rural United States critical access hospitals lacking on-site electrophysiology expertise, where cloud-based diagnostic support commands premium positioning. Target direct-to-patient distribution for wellness-oriented photoplethysmography wearables bypassing traditional durable medical equipment channel capture. Pursue FDA 510(k) clearance for single-arrhythmia AI algorithms as fastest path to hospital procurement committee consideration.
For Investors and Strategic Acquirers: Algorithm-native diagnostic software vendors with cleared ECG interpretation modules represent priority acquisition targets as hardware manufacturers seek vertical capability expansion. Long-term viability favors platforms combining implantable through wearable device portfolios under episode-based reimbursement accountability. Watch for CMS reimbursement code expansion for continuous ambulatory monitoring as signal of inflection toward subscription revenue models.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates AI-enabled ECG algorithm clearance timelines under priority review pathways. |
| Hospital System Partnership | Locks in multi-year telemetry service contracts with integrated delivery networks under value-based care frameworks. |
| Software Companion Development | Extends hardware margins through recurring per-patient-per-month data analytics subscriptions. |
| Reimbursement Strategy | Secures Medicare coverage codes for wearable cardiac monitoring expanding patient access beyond facility settings. |
| CE Marking Pathway | Enables EU market entry for software-as-a-medical-device classifications under MDR clinical evidence requirements. |
Research Methodology
Desk research of FDA 510(k) clearance databases, CMS reimbursement code filings, and ISO 13485 certification registries preceded structured interviews with electrophysiology service line directors, hospital telemedicine committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, Medicare claims data, and medical device trade association reports. Bottom-up unit economics for patch-based monitors and implantable systems were triangulated against top-down health system spending allocations across the analysis window.
Variance-decomposition across product type, end-user setting, technology platform, and application use case shaped the analytical framework for value projections throughout the forecast period. CAGRs were derived from segmented adoption curves weighted by reimbursement pathway maturity and regulatory clearance status. Industry-specific inputs included FDA breakthrough device designation velocity, Medicare remote monitoring code utilization trends, and photoplethysmography sensor foundry capacity utilization.
Decision-makers should treat outputs as directional under assumptions of sustained CMS reimbursement expansion for ambulatory monitoring and stable FDA 510(k) review timelines for AI-enabled diagnostics; material deviation in regulatory throughput or payer coverage would warrant model refresh. Recalibration cycles align with material shifts in Medicare reimbursement policy, FDA guidance document updates for software-as-a-medical-device, and semiconductor supply capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Respiration Monitor Belt Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Wrist Blood Pressure Monitors Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Global Vital Sign Monitoring Market