
 Creatine Kinase Reagent Market | 2026-2036
Creatine Kinase Reagent Market Size, Share, and Industry Trends Forecast 2026-2036
Creatine Kinase Reagent Market Analysis
Point-of-care cardiac testing is expanding its share of creatine kinase reagent consumption as hospitals decentralize emergency triage. Abbott Laboratories leverages its installed base of bedside analyzers to sustain channel control in acute care settings. Danaher Corporation anchors its position through Beckman Coulter's specialized clinical chemistry systems, while Thermo Fisher Scientific competes with broad laboratory automation portfolios.
Creatine kinase reagents are diagnostic biochemical formulations containing stabilized enzyme substrates, cofactors, and chromogenic indicators that catalyze the phosphorylation of creatine to measure serum or plasma enzyme activity, typically quantified in units per liter at 37 degrees Celsius for standardized clinical interpretation. Their primary purpose is enabling rapid detection of myocardial infarction, muscular dystrophy, and rhabdomyolysis through quantitative enzyme activity measurement. Enzymatic reagents dominate current volume due to established compatibility with open-channel clinical chemistry analyzers, while electrochemical formats represent the fastest-growing category as manufacturers miniaturize sensors for handheld devices. Fluorescent detection methods concentrate in high-sensitivity research and reference laboratory segments where margin pools remain deepest.
FDA CLIA regulations and the European Union's In Vitro Diagnostic Regulation shape product classification, performance validation requirements, and market access timelines for creatine kinase reagent manufacturers. ISO 15189 accreditation standards for medical laboratories further drive demand for traceable, lot-standardized reagent formulations. Stakeholders must monitor evolving harmonization between FDA and EMA post-market surveillance requirements to anticipate compliance costs and competitive positioning adjustments.
Market Dynamics
Decentralization of cardiac diagnostics is restructuring creatine kinase reagent demand as hospitals shift enzyme testing from centralized labs to emergency department bedside units, compressing turnaround times and reconfiguring procurement relationships.
Growth Catalysts
- FDA CLIA-waived pathway:Streamlined regulatory clearance accelerates point-of-care assay deployment in US acute care settings.
- Emergency department triage networks:Hospital systems in Germany and China are building dedicated cardiovascular rapid-response units.
- Electrochemical sensor miniaturization:Handheld device formats enable testing outside traditional laboratory infrastructure.
Market Restraints
- Enzyme raw material concentration:Stabilized creatine kinase substrate supply clusters among three specialty chemical suppliers in Switzerland and Germany.
- IVDR compliance burden:Europe's In Vitro Diagnostic Regulation imposes extended performance validation timelines and notified body bottlenecks.
- High-sensitivity troponin substitution:Cardiac biomarker panels increasingly favor troponin I and T assays for myocardial infarction specificity.
Strategic Opportunities
- Ambulatory surgical centers:Outpatient facilities in the United States lack on-site cardiac enzyme testing capacity.
- MDR Article 110 performance studies:Manufacturers with existing clinical data gain accelerated European market access versus new entrants.
- Telemedicine-integrated home monitoring:Remote patient platforms require dry-reagent strip formats for post-discharge rhabdomyolysis surveillance.
Industry Challenges
- ISO 15189 traceability implementation:Medical laboratories demand lot-standardized reagent formulations with certified reference material alignment.
- Analyzer interface fragmentation:Open-channel clinical chemistry systems use proprietary communication protocols requiring custom calibration development.
- Reagent stability in variable climates:Cold chain infrastructure gaps in tropical markets degrade enzyme activity during distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creatine Kinase Reagent Market |
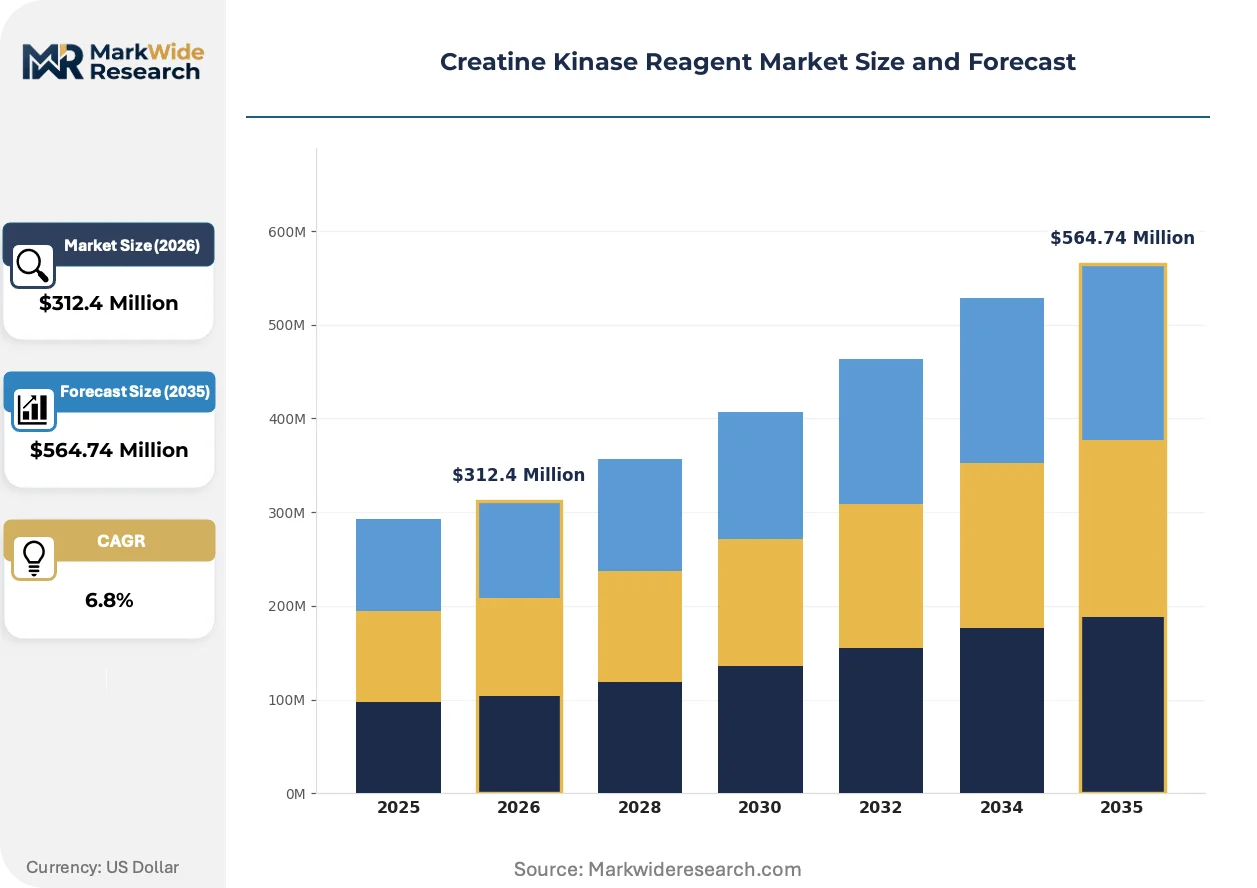
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic, Colorimetric, Electrochemical, Fluorescent Application: Cardiovascular Diagnostics, Toxicology, Neurological Disorders, Sports Medicine End User: Hospitals, Diagnostic Laboratories, Research Institutes, Point-of-Care Testing Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Abbott Laboratories, Danaher Corporation, BBI Solutions, DiaSys Diagnostic Systems GmbH, Boditech Med Inc., Randox Laboratories Ltd, Thermo Fisher Scientific, PerkinElmer Inc, Pointe Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creatine Kinase Reagent Market Emerging Trajectories
Reagent format evolution and regulatory harmonization are compressing product development cycles while procurement centralization reshapes vendor relationships across hospital networks.
Dry chemistry reagent strips are expanding into decentralized cardiac testing workflows. Rural clinics and ambulance services adopt these formats for field-deployable creatine kinase measurement without refrigerated storage. The technology is expanding into emergency medical services procurement frameworks previously reserved for laboratory-based liquid reagents.
Europe's MDR transition is forcing manufacturers to rebuild technical documentation and clinical evidence packages for legacy assays. Notified body capacity constraints extend certification timelines by twelve to eighteen months. High-throughput reference laboratories absorb these delays through buffer inventory, while point-of-care developers accelerate US FDA submissions to bypass European bottlenecks.
Hospital group purchasing organizations consolidate reagent procurement across multi-site networks. Academic medical centers in the United States negotiate system-wide contracts that bundle creatine kinase assays with broader cardiac biomarker panels. This concentration shifts pricing leverage toward buyers and pressures mid-tier manufacturers to demonstrate analyzer interoperability or exit contracted vendor lists.
Creatine Kinase Reagent Market Segmentation
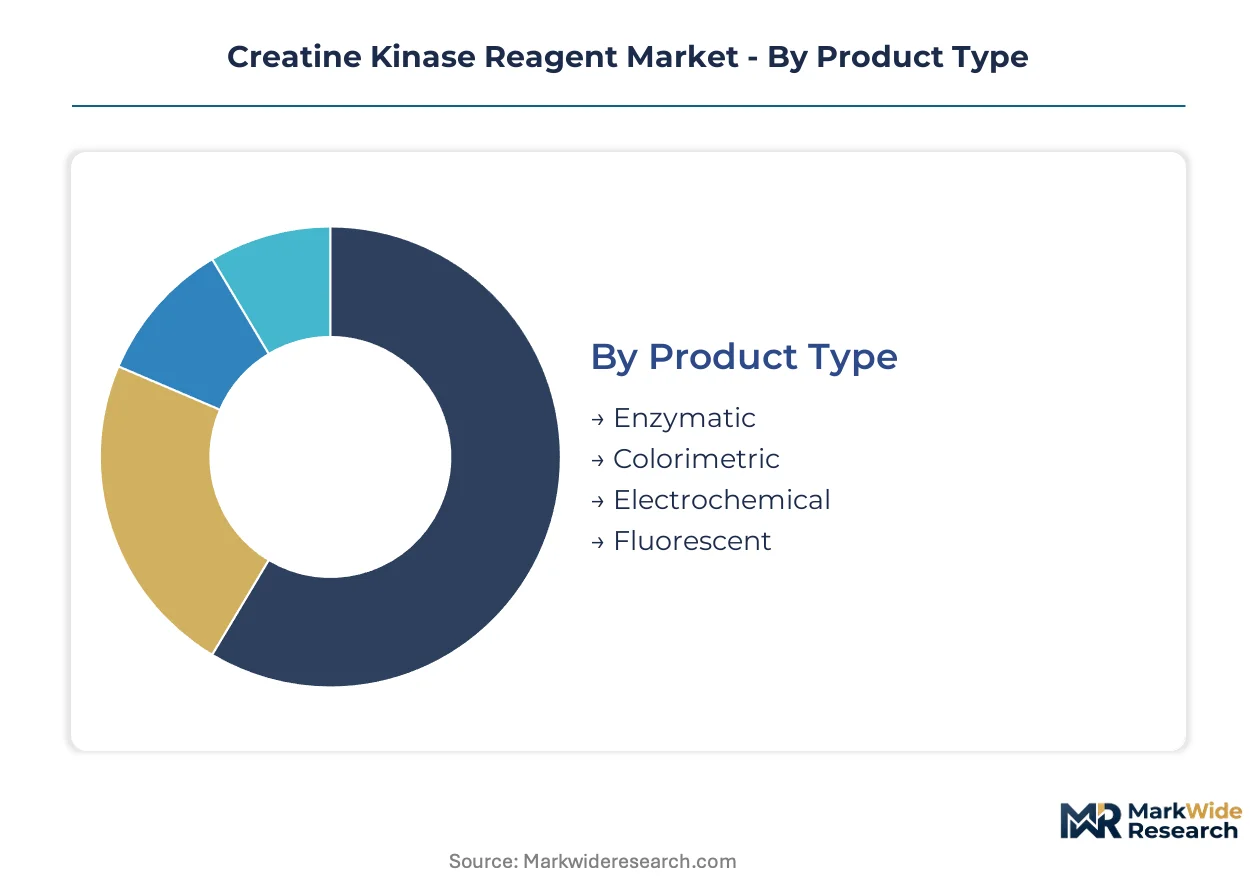
Creatine kinase reagent manufacturers configure product portfolios around analyzer compatibility, regulatory pathway, and end-user workflow requirements. Segment boundaries blur as electrochemical formats penetrate hospital emergency departments and dry chemistry strips expand into ambulatory settings.
Product Type:
Standardization dominates at the high-throughput laboratory tier while customization accelerates in point-of-care formats requiring sensor miniaturization and ambient stability engineering.
- Enzymatic:Formulations couple creatine phosphate with adenosine diphosphate in the presence of hexokinase and glucose-6-phosphate dehydrogenase to produce measurable NADH. Demand concentrates in Germany and the United States where centralized clinical chemistry analyzers process high cardiac biomarker volumes. Beckman Coulter and Abbott anchor procurement relationships through analyzer-reagent bundling contracts.
- Electrochemical:Miniaturized biosensors immobilize creatine kinase on electrode surfaces for handheld quantification without optical detection. China’s emergency department expansion drives fastest adoption as provincial hospital networks deploy bedside triage units. Sensor calibration drift remains the primary technical constraint limiting menu breadth.
- Colorimetric:Chromogenic substrates enable visual endpoint detection for resource-limited settings lacking spectrophotometric infrastructure.
- Fluorescent:High-sensitivity detection methods serve research institutes and reference laboratories requiring precise enzyme kinetics measurement.
Leading the category by volume: Enzymatic reagents compatible with open-channel analyzers. Growing fastest: Electrochemical formats gaining share in decentralized cardiac testing.
Application:
Margin pools concentrate where diagnostic specificity commands premium pricing and reimbursement codes reward rapid turnaround.
- Cardiovascular Diagnostics:Acute myocardial infarction triage consumes the majority of creatine kinase-MB and total CK reagent volumes. United States hospital systems bundle these assays with troponin panels under cardiovascular emergency protocols. High-sensitivity troponin I assays are displacing CK-MB in some protocols, compressing growth trajectories for legacy enzyme methods.
- Sports Medicine:Professional athletic programs and military training facilities deploy point-of-care units for exertional rhabdomyolysis screening. Australia’s institute of sport and United States collegiate athletic conferences drive procurement of dry-reagent strip formats. Seasonal training cycles create demand spikes requiring flexible inventory management.
- Toxicology:Forensic laboratories and occupational health clinics measure enzyme elevation following drug-induced muscle injury or chemical exposure.
- Neurological Disorders:Duchenne muscular dystrophy monitoring and statin-induced myopathy assessment utilize creatine kinase quantification in specialized neurology clinics.
Cardiovascular diagnostics generates the largest revenue pool. Sports medicine applications are expanding most quickly as athlete health monitoring protocols proliferate.
End User:
Procurement authority shifts from laboratory directors to emergency medicine chiefs as testing decentralizes.
- Hospitals:Acute care settings in the United States, Germany, and China maintain dual inventory—central lab liquid reagents and emergency department point-of-care cartridges. Capital equipment refresh cycles determine reagent contract renewal timing. Group purchasing organizations consolidate vendor selection across multi-hospital systems.
- Point-of-Care Testing:Emergency medical services and rural clinics adopt CLIA-waived formats for field-deployable cardiac enzyme measurement. FDA streamlined pathways accelerate deployment versus European IVDR timelines. Ambient temperature stability requirements constrain formulation chemistry.
- Diagnostic Laboratories:High-throughput reference sites demand lot-to-lot consistency and ISO 15189 traceability documentation.
- Research Institutes:Academic medical centers utilize specialized fluorescent and kinetic assay formats for mechanistic studies.
Hospitals command the largest absolute volume. Point-of-care testing is gaining share fastest as bedside triage networks expand.
Distribution Channel:
Channel strategy bifurcates between analyzer-integrated direct contracts and open-market availability for standardized reagents.
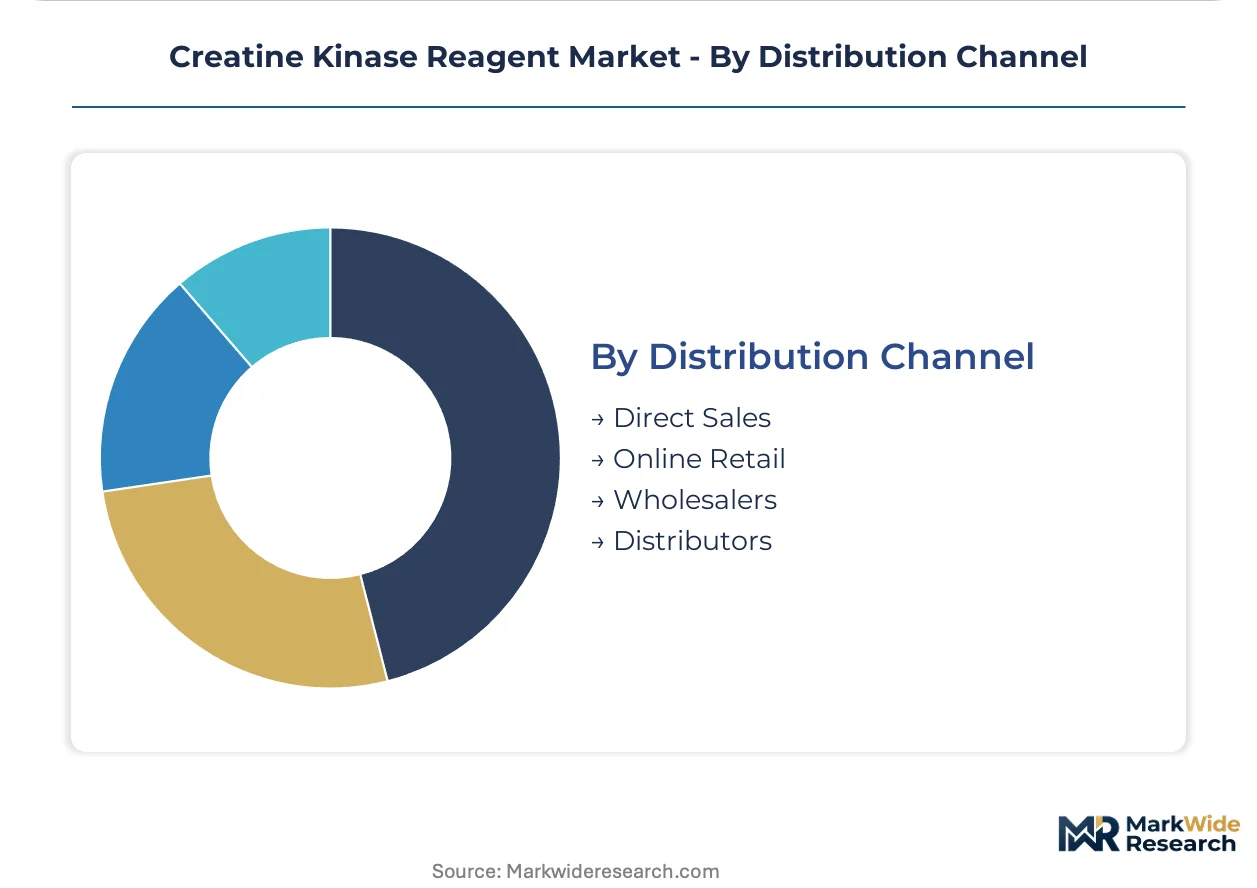
- Direct Sales:Manufacturers negotiate multi-year supply agreements bundling reagents with analyzer placement and service contracts. Abbott and Danaher dominate this channel through installed base leverage. Contract renewal windows create competitive displacement opportunities every three to five years.
- Distributors:Regional medical supply houses serve mid-tier laboratories lacking direct manufacturer relationships. Inventory carrying costs and cold chain logistics capabilities determine distributor viability in tropical markets.
- Online Retail:E-procurement platforms aggregate small-lot orders from research institutes and veterinary diagnostics.
- Wholesalers:Broad-line distributors handle commodity reagent formats with minimal technical support requirements.
Direct sales captures the largest revenue share. Distributor channels are expanding most quickly in emerging markets lacking manufacturer field presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Creatine kinase reagent production concentrates among specialty chemical suppliers in Switzerland and Germany, while consumption patterns diverge sharply across major healthcare markets building acute cardiovascular triage infrastructure.
United States
Emergency department point-of-care networks drive reagent demand as hospital systems decentralize cardiac enzyme testing. FDA CLIA-waived pathways accelerate deployment of bedside assay formats. The Boston-Cambridge medical technology cluster anchors analyzer-reagent bundling contracts for acute care settings.
Germany
Centralized clinical chemistry laboratories maintain high-throughput reagent volumes alongside expanding emergency department triage units. IVDR compliance requirements from EMA extend certification timelines for new assay introductions. The Rhine-Main region concentrates Beckman Coulter and Siemens Healthineers service infrastructure.
China
Provincial hospital networks deploy electrochemical biosensors for bedside cardiac testing in tier-two and tier-three cities. NMPA streamlined registration pathways accelerate domestic manufacturer market entry. The Yangtze River Delta cluster houses emerging point-of-care device assembly operations.
Japan
Aging demographics expand cardiovascular diagnostic volumes through hospital-based clinical chemistry analyzers. PMDA quality management system requirements enforce lot-to-lot reagent consistency standards. The Kansai region maintains specialized enzyme substrate purification capabilities.
Switzerland
Specialty chemical manufacturers supply stabilized creatine kinase substrates to global reagent formulators. Swissmedic medical device regulations align with MDR technical documentation requirements. The Basel biotech corridor anchors raw material supply relationships for European and Asian manufacturers.
Creatine Kinase Reagent Market Vendor Landscape
Top-tier vendors anchor analyzer-reagent bundling contracts, while mid-tier formulators compete on open-channel compatibility and price positioning. The market structure concentrates around three to five integrated diagnostic companies controlling installed base leverage, with fragmented specialty reagent suppliers serving niche applications. Strategic archetypes include full-system integrators, component specialists, and regional formulators. Dominant competitive moves involve analyzer placement agreements locking in multi-year reagent supply and geographic expansion through distributor partnerships in emerging markets.
Among US-based healthcare conglomerates, Abbott Laboratories and Danaher Corporation occupy positions exemplifying full-system integration archetypes, with the former leveraging bedside analyzer installed bases and the latter anchoring high-throughput clinical chemistry workflows. Thermo Fisher Scientific represents the diversified laboratory portfolio archetype, spanning reagent supply across multiple diagnostic modalities. DiaSys Diagnostic Systems GmbH and Randox Laboratories Ltd sit within the European specialist tier, occupying positions defined by regional regulatory expertise and open-system compatibility focus.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Danaher Corporation |
| BBI Solutions |
| DiaSys Diagnostic Systems GmbH |
| Boditech Med Inc. |
| Randox Laboratories Ltd |
| Thermo Fisher Scientific |
| PerkinElmer Inc |
| Pointe Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
Captive supply of stabilized creatine kinase substrates anchors pricing power for Swiss and German specialty chemical manufacturers, while analyzer-reagent bundling contracts lock hospital systems into multi-year procurement relationships that resist spot-market competition. This integration pattern concentrates margin capture upstream with substrate suppliers and downstream with integrated diagnostic companies, squeezing independent reagent formulators on both cost and channel access.
Pricing Analysis
Short lead-time premiums command pricing separation between emergency department cartridge formats and centralized laboratory liquid reagents. Three-tier pricing structure across premium, standard, and economy levels reflects analyzer compatibility certification, ISO 15189 traceability documentation, and cold chain logistics guarantees. Pricing pressure stems from group purchasing organization consolidation bundling cardiac biomarker panels. Academic medical centers exhibit lowest price sensitivity due to analyzer lock-in, while ambulatory surgical centers remain most price-sensitive with unmet on-site testing needs.
Supply Chain Analysis
Stabilized enzyme substrate supply rests on specialty chemical producers in Switzerland, Germany, and Japan purifying creatine phosphate and hexokinase to pharmaceutical-grade specifications. Reagent formulators depend on these inputs alongside chromogenic indicator dyes and diagnostic-grade cofactors sourced from regional chemical distributors. Single-source vulnerability concentrates around three substrate suppliers controlling stabilized creatine kinase formulations. Distribution runs through direct manufacturer contracts for high-throughput laboratories and regional medical supply houses for mid-tier facilities lacking analyzer bundling relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around installed base leverage and regulatory compliance scale, with IVDR documentation burdens and ISO 15189 traceability requirements forcing sub-scale formulators toward exit or acquisition.
For Market Incumbents: To counter high-sensitivity troponin substitution in cardiovascular protocols, Abbott and Danaher should deepen analyzer-reagent bundling with emergency department point-of-care networks and accelerate CLIA-waived assay submissions to capture ambulatory surgical center white space before mid-tier competitors achieve regulatory clearance. Backward integration into stabilized substrate production reduces exposure to Swiss and German supplier concentration. For New Entrants and Emerging Players: The gap between premium analyzer-integrated reagents and economy-grade open-channel formulations creates entry space for regional formulators targeting China's provincial hospital networks with NMPA-registered electrochemical biosensors and dry-reagent strips for telemedicine-integrated home monitoring platforms lacking cold chain infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-system integrators seeking open-channel compatibility portfolios and European regulatory expertise. Long-term viability favors formulators with documented IVDR technical files and existing ISO 15189-aligned reference material relationships. The signal to watch is notified body capacity expansion resolving European certification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Rebuild | Legacy assay manufacturers with existing clinical evidence gain accelerated European market access versus new entrants facing twelve-to-eighteen-month notified body delays. |
| CLIA-Waived Assay Submission | FDA streamlined pathways enable point-of-care deployment in US emergency departments and ambulatory surgical centers before European regulatory clearance. |
| Dry-Reagent Strip Format Development | Ambient stability engineering opens tropical market distribution and telemedicine-integrated post-discharge rhabdomyolysis surveillance applications. |
| Analyzer-Reagent Bundling Contract | Multi-year supply agreements with hospital group purchasing organizations lock in reagent volume and displace open-channel competitors during capital equipment refresh cycles. |
| Substrate Supplier Partnership | Long-term supply agreements with Swiss and German specialty chemical manufacturers secure stabilized enzyme input access and buffer against raw material concentration risk. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with clinical chemistry laboratory directors, emergency medicine chiefs, hospital procurement managers, and point-of-care device engineers. FDA 510(k) databases, EMA IVDR submission records, NMPA registration files, and ISO 15189 accreditation directories provided structured secondary validation. Bottom-up reagent volume estimates triangulated against top-down analyzer installed base calculations across the United States, Germany, and China.
Granularity-level modeling disaggregated volume and value across enzymatic, electrochemical, colorimetric, and fluorescent product types; cardiovascular diagnostics, sports medicine, toxicology, and neurological disorder applications; and hospitals, point-of-care testing sites, diagnostic laboratories, and research institutes as end users. CAGRs derived from regression analysis of historical reagent consumption against analyzer placement trends and regulatory pathway acceleration effects. Electrochemical sensor miniaturization curves and CLIA-waiver expansion timelines served as industry-specific forecast inputs.
Inputs from regulatory submission databases and hospital procurement records were available through the study window; gaps in real-time point-of-care utilization data introduce uncertainty bands around emergency department adoption trajectories. Forecasts reflect assumptions regarding notified body capacity resolution, NMPA streamlined pathway continuity, and high-sensitivity troponin substitution rates in cardiovascular protocols. Regulatory harmonization between FDA and EMA post-market surveillance requirements and cold chain infrastructure development in tropical markets warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Liver Function Tests Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
HDL Cholesterol Kits Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market