
 Body Fluid Collection and Diagnostics Market | 2026-2036
Body Fluid Collection and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Body Fluid Collection and Diagnostics Market Intelligence
Specimen processing service revenue is narrowing as point-of-care diagnostics capture margin pools previously held by centralized labs. Thermo Fisher Scientific leverages its vacuum tube and molecular diagnostics portfolio to control upstream sample integrity. QIAGEN specializes in automated nucleic acid extraction systems that anchor clinical laboratory throughput. BD dominates blood collection device manufacturing with scale advantages across hospital and research channels.
Body fluid collection and diagnostics encompasses the engineered systems, consumables, and analytical platforms used to acquire, stabilize, transport, and analyze biological specimens including blood, urine, saliva, sputum, and cerebrospinal fluid. Vacuum systems maintain specimen integrity through controlled pressure differentials and additive-coated tubes that prevent hemolysis or clot degradation during transit. Automated systems lead capital deployment as laboratories replace manual pipetting with robotic liquid handlers that reduce pre-analytical error rates. Point-of-care devices represent the fastest-expanding technology segment, driven by decentralized testing mandates in emergency departments and resource-limited settings. Saliva collection kits emerge as a high-growth product category, displacing venipuncture in pharmacogenomics and longitudinal wellness monitoring applications.
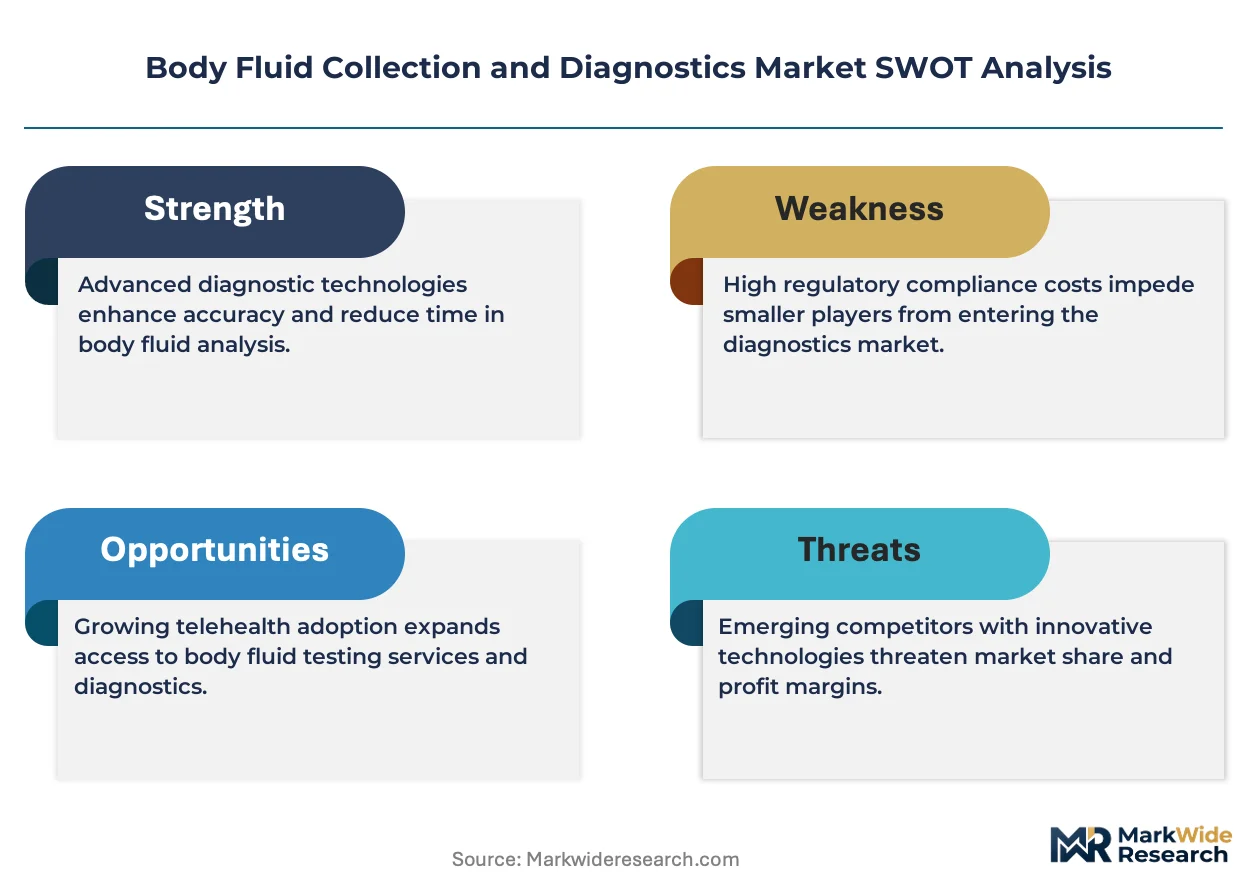
FDA enforces Clinical Laboratory Improvement Amendments that govern analytical validity and personnel certification for specimen testing facilities. EMA's In Vitro Diagnostic Regulation imposes stricter performance evaluation and post-market surveillance requirements on devices entering European clinical settings. China's NMPA accelerates review pathways for innovative diagnostic reagents under its priority review program. Stakeholders must monitor regulatory divergence between jurisdictions to avoid redundant clinical validation costs and supply chain fragmentation.
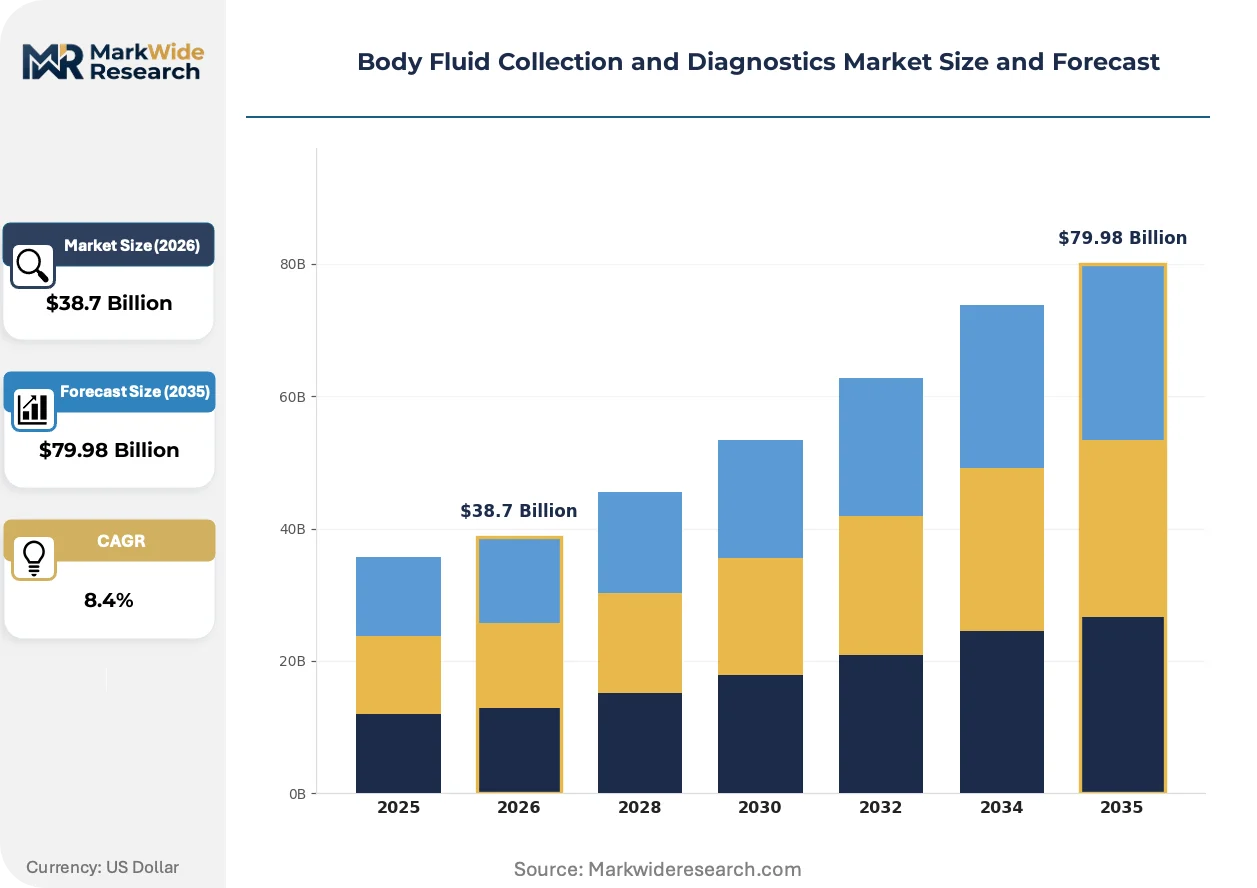
Market Dynamics
Liquid biopsy automation is compressing specimen processing economics as clinical laboratories consolidate manual workflows into integrated platforms that reduce pre-analytical error rates and labor intensity.
Growth Catalysts
- CLIA Laboratory Certification Mandates:FDA enforcement of analytical validity standards drives hospital systems to upgrade collection infrastructure and personnel training protocols.
- Pharmacogenomics Testing Expansion:Saliva-based collection kits displace venipuncture in longitudinal wellness monitoring and personalized medicine applications.
- Germany's Population Screening Scale-Up:Federal health ministry investments in decentralized diagnostic networks accelerate point-of-care device procurement across ambulatory care settings.
Market Restraints
- Specialized Additive Supply Concentration:Vacuum tube coating chemistries depend on limited European and North American specialty chemical suppliers subject to input volatility.
- IVDR Performance Evaluation Burden:EMA's stricter post-market surveillance requirements impose extended clinical validation timelines and documentation costs on platform developers.
- Manual Pipetting Skill Dependency:Pre-analytical error rates in resource-limited settings persist where robotic liquid handler capital investment remains prohibitive.
Strategic Opportunities
- China's Priority Review Pathway:NMPA accelerated timelines for innovative diagnostic reagents create first-mover advantages for automated extraction system developers.
- Emergency Department Decentralization:Point-of-care mandates in acute care settings open direct procurement channels bypassing centralized laboratory intermediaries.
- Digital Pathology Convergence:Integration of automated liquid handling with whole-slide imaging platforms enables closed-loop diagnostic workflows.
Industry Challenges
- Robotics Integration Complexity:Legacy laboratory information systems require costly middleware development to interface with new automated specimen processing platforms.
- Cross-Jurisdictional Validation Redundancy:Divergent FDA and EMA performance standards force manufacturers to duplicate clinical studies, fragmenting development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Fluid Collection and Diagnostics Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Collection Tubes, Urine Containers, Sputum Cups, Saliva Collection Kits Technology: Vacuum Systems, Manual Methods, Automated Systems, Point-of-Care Devices End User: Clinical Laboratories, Hospitals, Diagnostic Centers, Research Institutions Application: Infectious Disease Testing, Drug Testing, Biochemical Analysis, Genetic Testing |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories, F. Hoffmann-La Roche Ltd., Illumina Inc., QIAGEN, Guardant Health, Johnson & Johnson, Laboratory Corporation of America Holdings, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Fluid Collection and Diagnostics Market Strategic Shifts & Innovations
Specimen stabilization chemistry and microfluidic processing architectures are converging to enable sample-to-answer workflows that collapse the distance between collection and actionable diagnostic output.
Microfluidic cartridge systems integrate nucleic acid extraction, amplification, and detection into single-use consumables that eliminate manual transfer steps. Community health centers and emergency departments in the United States are adopting these platforms for infectious disease panels. Benchtop automation is rendering obsolete the multi-instrument, multi-operator workflows that previously dominated hospital laboratory throughput economics.
EMA's In Vitro Diagnostic Regulation imposes systematic post-market surveillance and performance evaluation documentation requirements on devices entering European clinical settings. Manufacturers must maintain clinical evidence registries and periodic safety reporting that extend far beyond pre-market clearance. High-complexity molecular diagnostics platforms face the steepest compliance burden, prompting consolidation among smaller reagent developers.
Hospital procurement committees now bundle collection device contracts with multi-year service agreements for automated platform maintenance and reagent supply. This subscription model displaces transactional purchasing of standalone consumables. Germany's hospital procurement cooperatives have pioneered this structure, locking in volume commitments that favor integrated platform vendors over specialized component suppliers.
Body Fluid Collection and Diagnostics Market Segmentation
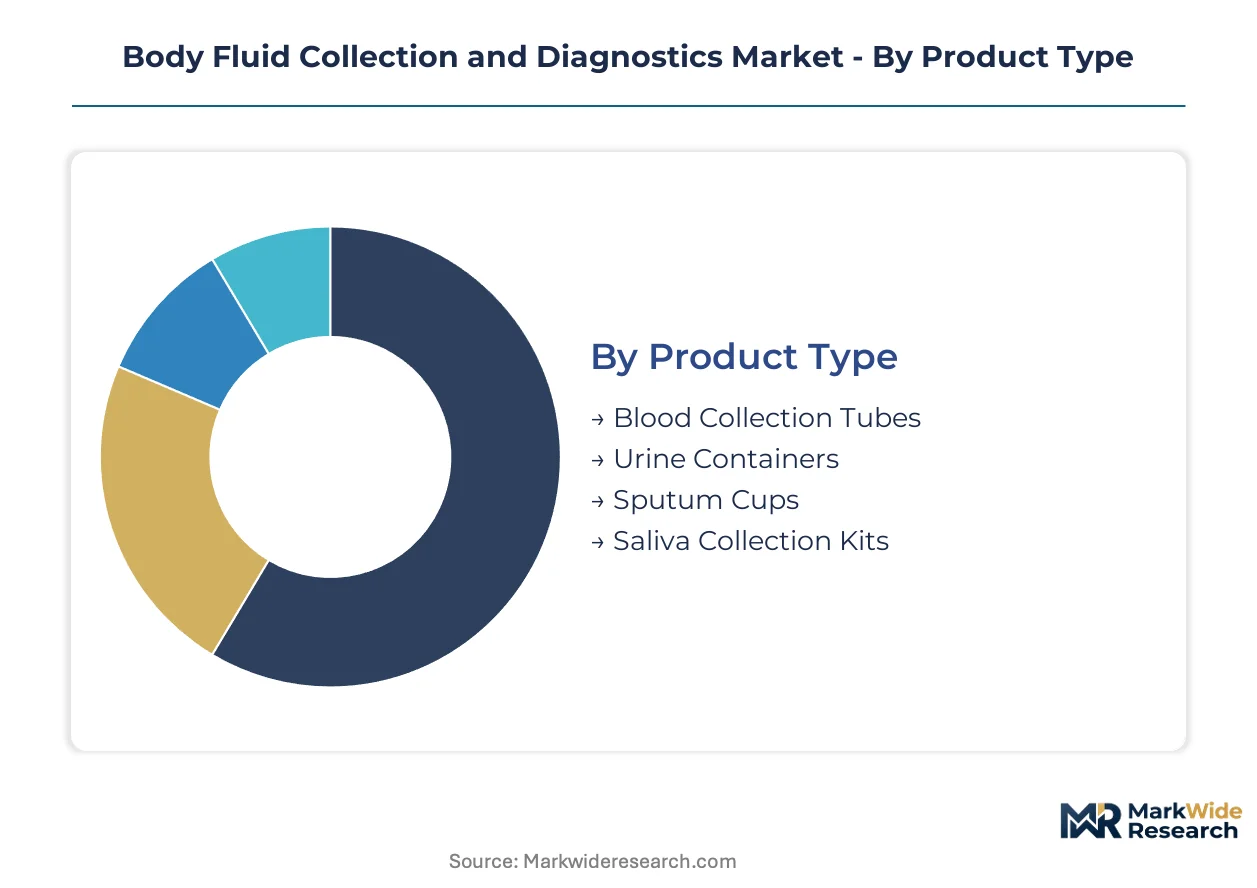
Segmentation in body fluid collection and diagnostics reveals how procurement patterns, technology maturation curves, and regulatory pathways create divergent margin structures across product categories. Understanding these divisions enables stakeholders to align capital deployment with the specific velocity of each segment's replacement cycle and compliance burden.
Product Type:
Blood collection tubes turn over on predictable replacement schedules tied to hospital procurement calendars, while saliva collection kits exhibit the most erratic demand spikes driven by wellness program launches and pharmacogenomics contract wins.
- Blood Collection Tubes:Vacuum-sealed borosilicate glass or plastic vessels with additive coatings (EDTA, heparin, serum separators) that preserve analyte stability during transport. Demand concentrates in United States hospital systems upgrading to closed-system sampling to reduce needlestick exposure liability.
- Saliva Collection Kits:Stabilization-buffered tubes and absorbent devices enabling non-invasive nucleic acid recovery for longitudinal monitoring. German ambulatory networks and United States direct-to-consumer wellness platforms are displacing venipuncture for pharmacogenomics and hormone panels.
- Urine Containers:Leak-resistant specimen cups with temperature strips and tamper-evident seals for chain-of-custody compliance.
- Sputum Cups:Wide-mouth containers with sterile collection protocols for tuberculosis and respiratory pathogen diagnostics.
Blood collection tubes anchor the volume base while saliva collection kits gain share at the steepest rate.
Technology:
Capital intensity separates these segments, with automated systems requiring multi-year depreciation schedules against point-of-care devices that amortize through consumable pull-through.
- Automated Systems:Robotic liquid handlers and track-based specimen processors that integrate barcode verification, centrifugation, and aliquoting. Clinical laboratories in China and the United States are consolidating manual workflows to reduce pre-analytical error rates and CLIA compliance exposure.
- Point-of-Care Devices:Cartridge-based or strip-based analyzers delivering sample-to-answer results without laboratory infrastructure. German emergency departments and United States community health centers are procuring these platforms to bypass centralized laboratory bottlenecks during infectious disease surges.
- Vacuum Systems:Evacuated tube technology maintaining controlled pressure differentials for precise blood volume collection.
- Manual Methods:Capillary tubes, syringes, and open-container techniques persisting in resource-constrained settings.
Vacuum systems dominate installed base value while point-of-care devices are expanding most quickly through decentralized procurement mandates.
End User:
Customer concentration and purchasing authority create tiered pricing power, with hospital procurement cooperatives extracting steeper discounts than fragmented diagnostic center networks.
- Clinical Laboratories:High-throughput reference and hospital-affiliated labs processing thousands of specimens daily with automated platforms and LIS integration. United States health systems and German hospital networks are consolidating vendor contracts to lock in multi-year reagent supply commitments.
- Hospitals:Acute care settings with mixed emergency department point-of-care and core laboratory workflows. China's tier-1 municipal hospitals are prioritizing automated extraction systems under NMPA priority review pathways.
- Diagnostic Centers:Independent outpatient facilities focused on routine screening and occupational health panels.
- Research Institutions:Academic and pharmaceutical R&D sites with specialized collection protocols for biomarker discovery.
Clinical laboratories command the largest absolute spend while hospitals are climbing the fastest through emergency department decentralization initiatives.
Application:
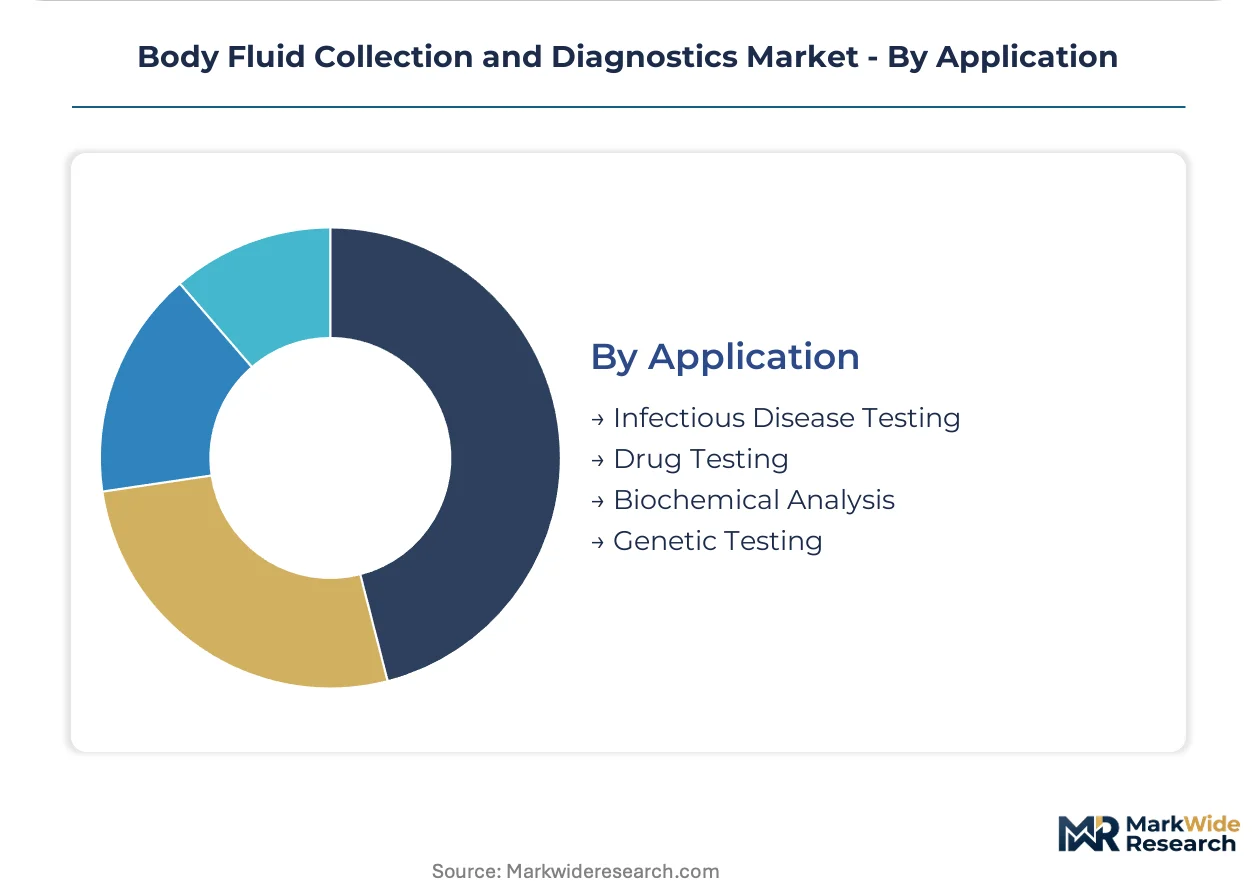
Test complexity and reimbursement stability determine collection infrastructure investment, with infectious disease panels offering predictable volume against genetic testing's lumpier project-based demand.
- Infectious Disease Testing:Respiratory, bloodstream, and sexually transmitted pathogen detection requiring sterile collection and rapid stabilization. United States community health centers and German public health laboratories are scaling cartridge-based platforms for tuberculosis and antimicrobial resistance surveillance.
- Genetic Testing:Germline and somatic nucleic acid analysis for inherited disease screening and oncology profiling. Saliva-based collection is displacing blood draws in United States pharmacogenomics and consumer wellness segments.
- Drug Testing:Urine and oral fluid collection for workplace compliance and forensic chain-of-custody protocols.
- Biochemical Analysis:Routine metabolic and enzymatic panels from serum or plasma specimens.
Biochemical analysis anchors routine volume while genetic testing is gaining share fastest through personalized medicine reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States favors high-throughput automated platforms for centralized laboratory consolidation, while Germany and China prioritize decentralized point-of-care networks for population screening scale-up.
United States
Hospital systems are consolidating vendor contracts for multi-year reagent supply commitments under CLIA laboratory certification mandates. FDA enforcement of analytical validity standards drives infrastructure upgrades across reference laboratories. The Greater Boston and San Francisco Bay Area clusters concentrate liquid biopsy automation development for oncology profiling applications.
Germany
Federal health ministry investments in decentralized diagnostic networks accelerate point-of-care device procurement across ambulatory care settings. EMA's In Vitro Diagnostic Regulation imposes systematic post-market surveillance requirements on platform developers. The Munich and Heidelberg regions anchor high-complexity molecular diagnostics manufacturing and clinical validation operations.
China
Tier-1 municipal hospitals prioritize automated extraction systems under NMPA priority review pathways for innovative diagnostic reagents. The national regulator accelerates review timelines to reduce dependency on imported specimen processing platforms. The Yangtze River Delta and Pearl River Delta clusters concentrate domestic manufacturing of vacuum tube and liquid handling consumables.
Japan
PMDA maintains stringent quality management system requirements for in vitro diagnostic device registration, favoring established platform vendors with documented post-market surveillance capabilities. METI funding programs support microfluidic processing architecture development for sample-to-answer workflows. The Kanto region around Tokyo dominates clinical laboratory automation integration and service infrastructure.
United Kingdom
NHS procurement frameworks bundle collection device contracts with automated platform maintenance agreements, displacing transactional consumables purchasing. MHRA alignment with EMA performance evaluation standards streamlines regulatory pathways for European market access. The Cambridge and Oxford clusters concentrate saliva-based diagnostics development for pharmacogenomics applications.
Body Fluid Collection and Diagnostics Market Key Industry Players
Capability concentration sits with specialized extraction system developers; scale advantage sits with diversified life sciences conglomerates. The market structures around three tiers: integrated platform vendors controlling upstream sample integrity, automated workflow specialists anchoring clinical laboratory throughput, and point-of-care device manufacturers capturing decentralized procurement channels. Dominant competitive moves include strategic partnerships between collection device manufacturers and diagnostic platform developers, plus backward integration into stabilization chemistry supply.
Among diversified laboratory infrastructure providers, Thermo Fisher Scientific Inc. and BD exemplify scale-driven positions spanning vacuum tube manufacturing through molecular diagnostics portfolios. QIAGEN occupies a specialist tier focused on automated nucleic acid extraction systems. These three entities represent distinct archetypes: the integrated conglomerate controlling specimen integrity upstream, the platform pure-play anchoring laboratory throughput economics, and the device-scale hybrid bridging centralized and decentralized testing environments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Illumina Inc. |
| QIAGEN |
| Guardant Health |
| Johnson & Johnson |
| Laboratory Corporation of America Holdings |
| BD |
| Others |
Cost & Logistics Intelligence
Trans-Pacific container freight corridors linking Shanghai to Long Beach transmit cost volatility directly into vacuum tube additive pricing, compressing margins for European coating chemistry suppliers while enabling Asian manufacturers to capture volume through freight-advantaged export pricing.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement cooperatives in Germany and the United States, locking in multi-year reagent supply commitments that displace spot purchasing of standalone consumables. Price differentiation rests on CLIA certification tier and bundled service intensity, with high-complexity molecular diagnostics platforms commanding premiums against commodity blood collection tubes. Cost compression in standard vacuum systems is intensifying as Chinese domestic manufacturers expand NMPA-cleared production capacity. Research institutions exhibit the highest price sensitivity due to grant-funded budget constraints, while integrated health systems leverage volume scale for steeper contractual discounts.
Supply Chain Analysis
Contract manufacturing for microfluidic cartridges concentrates with specialized polymer foundries in Germany, Switzerland, and Massachusetts, where precision molding capabilities anchor sample-to-answer device production. Borosilicate glass tubing for vacuum systems draws from German and Chinese specialty glass manufacturers, while stabilization buffer chemistries hinge on North American and European fine chemical suppliers. Single-source vulnerability in EDTA and heparin coating formulations exposes collection device assemblers to input volatility. Distribution runs through hospital procurement cooperatives and group purchasing organizations that consolidate demand across multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid biopsy automation represents a high-growth disruption as FDA and EMA convergence on analytical validity standards forces platform upgrades across clinical laboratory infrastructure.
For Market Incumbents: Build regulatory certification moats by accelerating IVDR technical documentation and FDA 510(k) pathway investments ahead of smaller reagent developers. Consolidate manual workflow vendors in China and Germany to preempt point-of-care decentralization threats. Backward integration into stabilization chemistry supply secures additive coating security against European specialty chemical concentration. For New Entrants and Emerging Players: Pursue saliva collection kit white space in United States direct-to-consumer pharmacogenomics and German ambulatory wellness monitoring, where venipuncture displacement creates new procurement channels. Target emergency department point-of-care mandates with cartridge-based infectious disease panels that bypass centralized laboratory intermediaries. Anchor go-to-market through GPO contracts managers seeking to diversify beyond incumbent vacuum tube suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates seeking to divest non-core collection device portfolios amid platform consolidation pressures. Five-to-ten year viability favors automated extraction system specialists with installed base expansion trajectories and recurring reagent revenue streams. Monitor NMPA priority review pathway approval velocity as inflection indicator for Chinese domestic substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | EMA compliance burden consolidates reagent developers unable to maintain clinical evidence registries. |
| Saliva Collection Kit Portfolio Expansion | Pharmacogenomics reimbursement expansion in United States displaces venipuncture for longitudinal monitoring. |
| Automated Platform Hospital Partnership | CLIA certification mandates drive multi-year service agreement bundling with collection device contracts. |
| Microfluidic Cartridge Manufacturing Scale-Up | German emergency department procurement opens direct channels bypassing centralized laboratory intermediaries. |
| NMPA Priority Review Pathway Engagement | Accelerated timelines for innovative diagnostic reagents reduce dependency on imported specimen processing platforms. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA IVDR technical documentation, hospital procurement databases, and GPO contract registries. Clinical laboratory directors, biomedical engineers, regulatory affairs specialists, and GPO contracts managers provided operational perspective on automation deployment economics. Bottom-up segmentation modeling triangulates against top-down macro validation across product type, technology platform, end-user concentration, and application complexity dimensions.
Forecast inputs span installed base replacement cycles, regulatory approval velocity, reimbursement pathway expansion, and procurement cooperative consolidation patterns across the projection horizon. Segmentation dimensions include collection device format, automation intensity tier, laboratory throughput class, and regional regulatory cluster. CAGRs derive from regression analysis of historical platform adoption curves applied to emerging technology substitution elasticities.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, freight rate volatility, and specialty chemical input pricing would shift the trajectory. Forecasts reflect documented assumptions on regulatory convergence timing and procurement centralization momentum. Quarterly review of NMPA approval announcements, hospital merger activity, and group purchasing organization contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Semen Analysis Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Elisa Tests Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Europe Molecular Diagnostics Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
Veterinary Diagnostic Services Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market