
 BRIC in-Vitro Diagnostics (IVD) Market | 2026-2036
BRIC in-Vitro Diagnostics (IVD) Market Size, Share, and Industry Trends Forecast 2026-2036
BRIC in-Vitro Diagnostics (IVD) Market Outlook
Diagnostic laboratories is pivoting toward high-throughput automated platforms across BRIC nations, outpacing hospital-based testing growth. Roche Diagnostics leverages its installed base of cobas systems to sustain service revenue in Brazilian urban centers. Abbott Laboratories Inc. anchors its competitive position through point-of-care specialization in Indian primary health settings. Siemens Healthineers differentiates via integrated imaging-diagnostic workflows in Russian federal hospital networks.
In-vitro diagnostics encompasses clinical tests performed on blood, tissue, or bodily fluid specimens outside the living organism, utilizing reagent kits, analyzers, and software platforms to detect disease biomarkers with sensitivity thresholds often reaching picogram-per-milliliter concentrations. Immunoassays occupy the largest revenue pool across BRIC markets due to established reimbursement pathways for infectious disease screening. Molecular diagnostics registers the fastest structural expansion, propelled by polymerase chain reaction and next-generation sequencing adoption in oncology and pathogen identification protocols. Hematology analyzers represent a mature segment where margin compression forces vendors toward consumable-locked instrument placements.
Brazil's ANVISA, India's CDSCO, and China's NMPA enforce divergent registration timelines and clinical evidence requirements that fragment product launch cadences across BRIC jurisdictions. Russia's national regulator mandates local manufacturing partnerships for state procurement eligibility, redirecting foreign capital toward joint venture structures. Stakeholders must monitor regulatory harmonization negotiations between India's CDSCO and WHO prequalification standards to anticipate accelerated market access pathways.
Market Dynamics
Automated platform consolidation is compressing margins for standalone reagent suppliers while locking hospital networks into long-term consumable contracts across Brazilian and Chinese diagnostic laboratories.
Growth Catalysts
- India's PLI scheme:Domestic manufacturing incentives are accelerating local production of diagnostic analyzers and reagent kits, reducing import dependency for molecular testing infrastructure.
- Polymerase chain reaction expansion:Oncology and infectious disease protocols in China's tier-one hospital networks are driving installed base growth for nucleic acid amplification platforms.
- Federal hospital procurement:Russian state purchasing mandates for localized production are redirecting foreign capital toward joint venture manufacturing structures.
Market Restraints
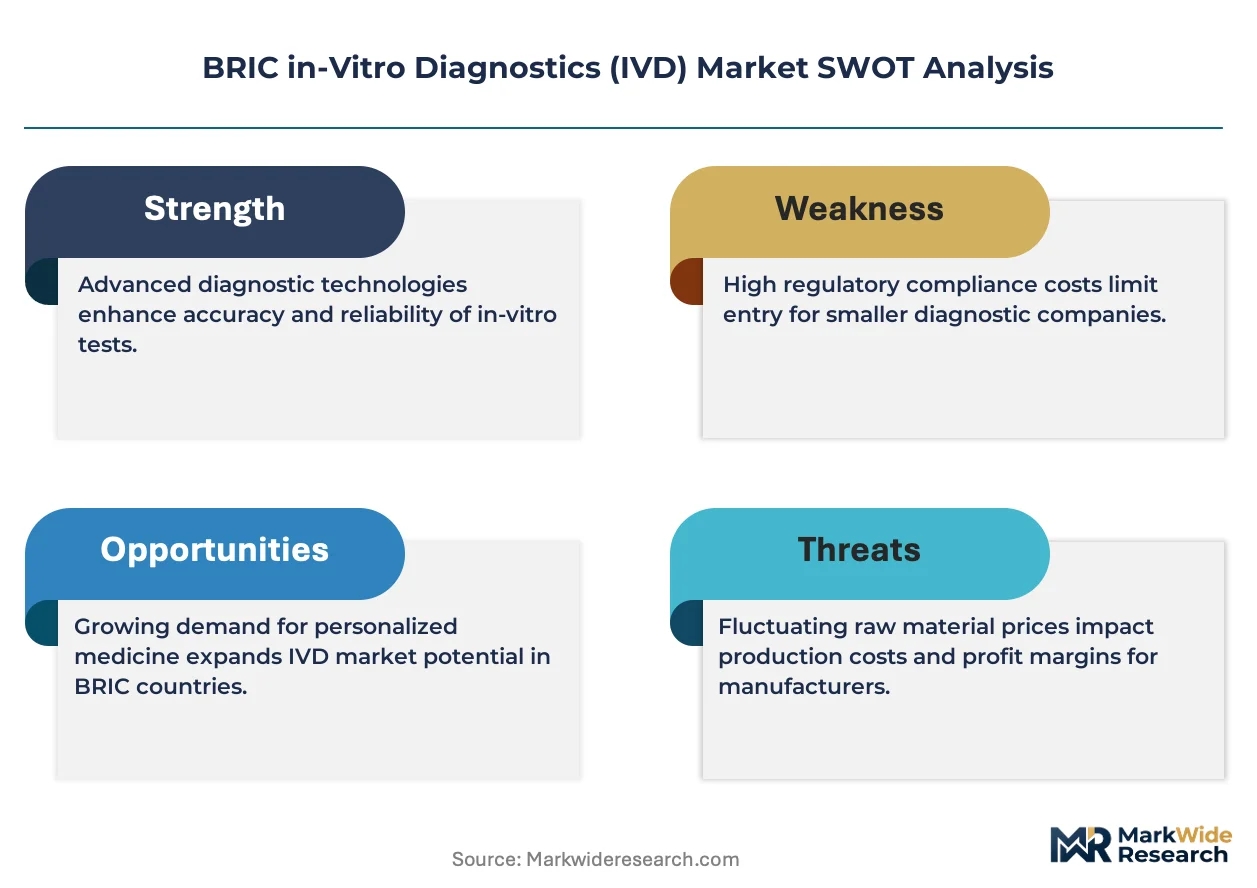
- Reagent price volatility:Enzyme and oligonucleotide input costs fluctuate with biotech raw material supply chains concentrated in East Asian contract manufacturers.
- Regulatory fragmentation:Divergent clinical evidence requirements between Brazil's ANVISA, India's CDSCO, and China's NMPA extend product registration timelines and duplicate development expenditure.
- Immunoassay substitution pressure:Chemiluminescence platforms are displacing older enzyme-linked immunosorbent assay formats, stranding capital in legacy analyzer installations.
Strategic Opportunities
- Point-of-care penetration in primary health:Indian rural clinic networks remain underserved by automated platforms, creating whitespace for portable diagnostic devices with simplified operator interfaces.
- Next-generation sequencing convergence:Integration of targeted gene panels with liquid biopsy workflows is opening oncology companion diagnostic applications in Chinese tertiary hospitals.
- CDSCO-WHO harmonization:Alignment between India's drug regulator and WHO prequalification standards promises accelerated market access pathways for multinational IVD registrants.
Industry Challenges
- Bioinformatics talent scarcity:Molecular diagnostics laboratories in Russia and Brazil face acute shortages of computational biologists capable of interpreting next-generation sequencing outputs.
- Legacy system integration friction:Hospital information system interoperability gaps complicate data exchange between new analyzers and existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRIC in-Vitro Diagnostics (IVD) Market |
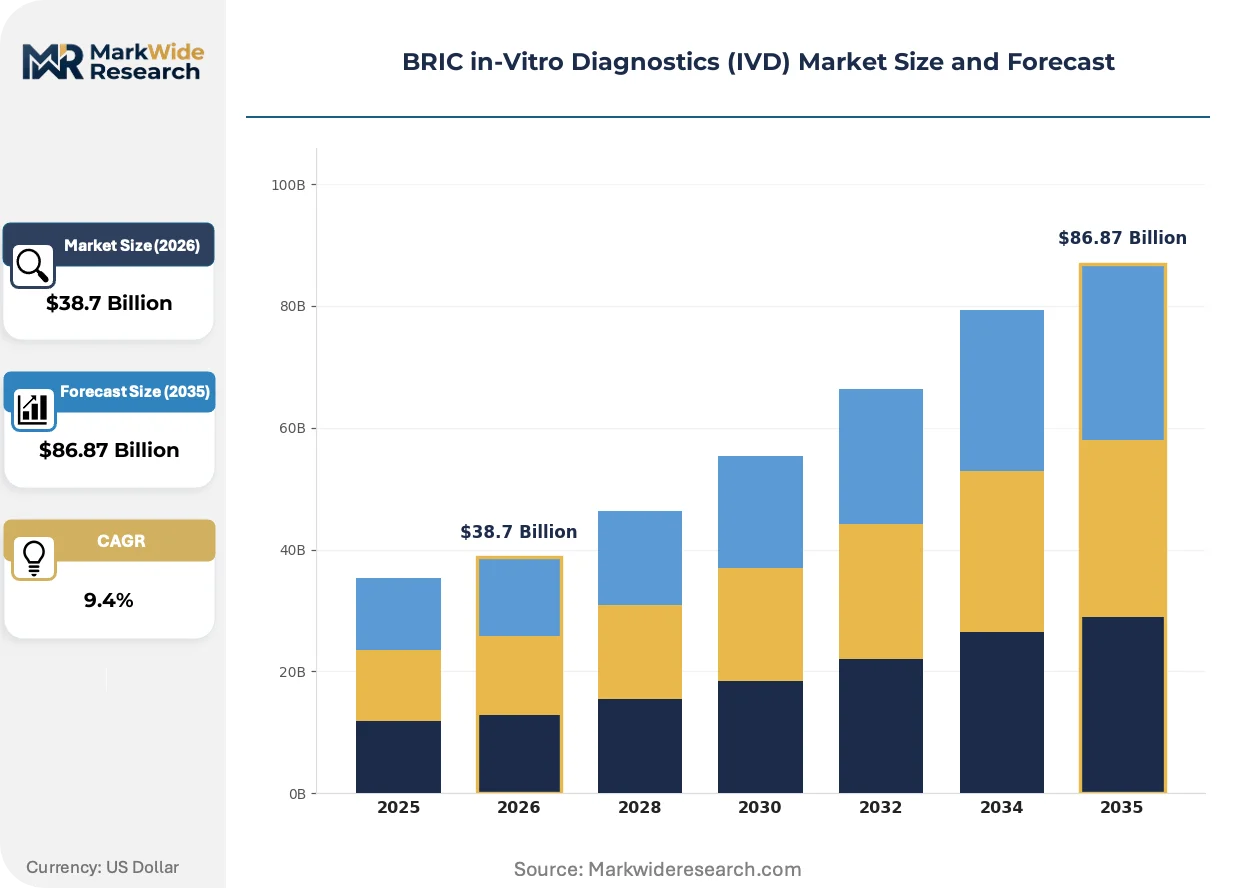
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Blood Gas Analyzers, Molecular Diagnostics, Hematology Analyzers End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Settings Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Mass Spectrometry, Next-Generation Sequencing Application: Infectious Diseases, Cancer, Metabolic Disorders, Cardiovascular Diseases |
| Companies Covered | Roche Diagnostics, Abbott Laboratories Inc., Siemens Healthineers, Danaher Corporation, Thermo Fisher Scientific Inc., Sysmex Corporation, Bio-Rad Laboratories, Inc., bioMérieux, Becton, Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRIC in-Vitro Diagnostics (IVD) Market Strategic Shifts
Digital pathology and artificial intelligence-assisted diagnostic interpretation are restructuring workflow economics in high-volume laboratories, compressing turnaround times while raising capital intensity requirements.
Next-generation sequencing platforms are rewriting competitive positioning in oncology diagnostics. Chinese tertiary hospital networks are adopting targeted gene panels at accelerated replacement cycles for solid tumor profiling. This compression of testing economics is forcing reagent suppliers toward bundled instrument-consumable contracts that lock in multi-year revenue streams.
Brazil's ANVISA has tightened post-market surveillance requirements for Class IV high-risk IVD devices, mandating real-world performance data submissions. Foreign manufacturers now face extended compliance timelines before commercial launch. Multinational registrants are responding by establishing local clinical affairs teams to manage adverse event reporting and periodic safety update obligations.
Hospital procurement departments across Indian metropolitan centers are consolidating vendor relationships through centralized tendering platforms. Standalone reagent suppliers face exclusion from multi-year framework agreements that favor integrated platform providers. This buyer concentration is most visible in Maharashtra and Karnataka state hospital networks, where diagnostic service outsourcing contracts now specify exclusive analyzer fleet commitments.
BRIC in-Vitro Diagnostics (IVD) Market Segmentation
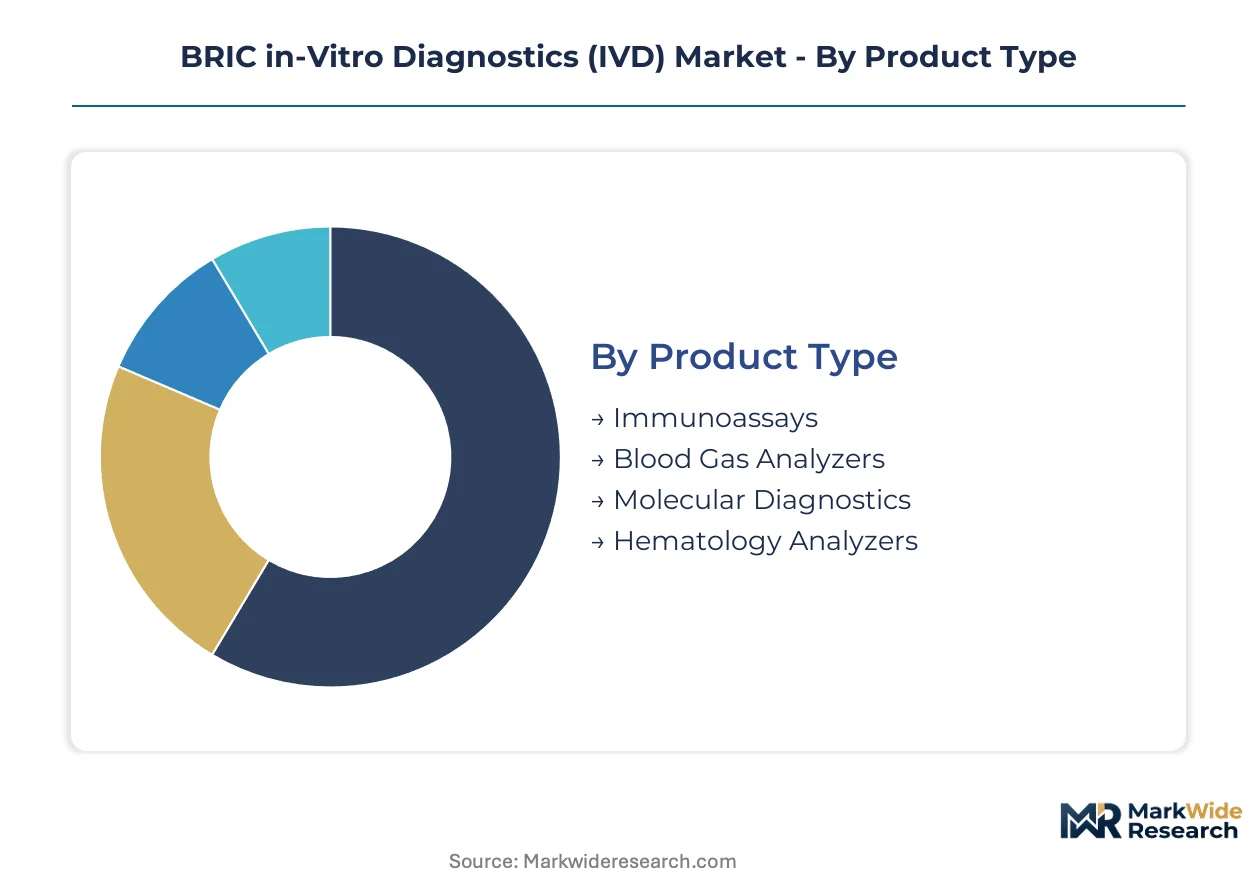
Segmentation in BRIC in-vitro diagnostics reveals how purchasing power, clinical workflow complexity, and regulatory pathways fragment demand across product categories. Buyers in Brazil, Russia, India, and China prioritize different performance thresholds, reimbursement eligibility, and automation integration levels.
Product Type:
Cost tiers separate high-volume routine screening from premium molecular platforms.
- Immunoassays:These chemiluminescence and enzyme-based tests detect antibodies, hormones, and infectious markers with established reimbursement codes across Brazilian and Indian hospital networks. Demand concentrates in urban diagnostic laboratories seeking throughput economies for infectious disease panels, though margin pressure from reagent commoditization forces vendors toward instrument-locked consumable contracts.
- Molecular Diagnostics:Nucleic acid amplification platforms and hybridization assays enable pathogen identification and genetic mutation detection at sensitivity thresholds reaching single-copy detection. China's tier-one hospital networks are driving installed base expansion for oncology companion diagnostics and infectious disease subtyping, with procurement favoring integrated workflow automation over standalone modules.
- Blood Gas Analyzers:Point-of-care devices measure pH, oxygen, and carbon dioxide in arterial samples for critical care triage in Russian federal hospital emergency departments.
- Hematology Analyzers:Mature cell-counting platforms face replacement-driven demand in Indian state hospital networks with limited budget for premium feature upgrades.
Volume sits with Immunoassays; growth tilts toward Molecular Diagnostics.
End User:
Application urgency and sample volume dictate facility-level purchasing patterns.
- Diagnostic Laboratories:High-throughput reference labs process thousands of daily samples across automated immunoassay and molecular platforms, with Brazilian and Chinese urban networks consolidating vendor relationships through multi-year exclusive contracts. Margin compression from centralized tendering is forcing independent labs toward outsourcing partnerships with platform-integrated service providers.
- Hospitals:Acute care facilities require rapid turnaround for emergency and perioperative testing, driving demand for point-of-care blood gas and cardiac marker systems. Russian federal hospital procurement mandates favor localized manufacturing partnerships, redirecting multinational capital toward joint venture structures for analyzer placement.
- Research Institutions:Academic medical centers in India and China acquire next-generation sequencing and mass spectrometry platforms for biomarker discovery, though capital constraints limit replacement cycles.
- Home Care Settings:Glucose monitoring and infectious disease self-testing remain underpenetrated in BRIC rural markets due to reimbursement gaps and cold-chain logistics for reagent stability.
Procurement concentration favors Diagnostic Laboratories; expansion opportunity clusters in Home Care Settings.
Technology:
Customer type determines sensitivity requirements and operator skill thresholds.
- Polymerase Chain Reaction:Thermal cycling amplification of DNA/RNA targets enables pathogen quantification and genetic variant detection with picogram sensitivity. China's tertiary hospital oncology departments are adopting real-time PCR for liquid biopsy workflows, with reagent suppliers bundling instrument placements to secure multi-year consumable commitments.
- Next-Generation Sequencing:Massively parallel sequencing platforms generate gigabase-scale readouts for tumor profiling and hereditary disease screening. Indian metropolitan cancer centers are piloting targeted gene panels for solid tumor stratification, constrained by bioinformatics talent scarcity and interpretive workflow bottlenecks.
- Enzyme-Linked Immunosorbent Assay:Colorimetric antibody-antigen detection remains prevalent in resource-limited settings for HIV and hepatitis screening, though chemiluminescence displacement is accelerating.
- Mass Spectrometry:High-resolution metabolite and protein quantification supports newborn screening and therapeutic drug monitoring in Brazilian reference laboratories with specialized technical staff.
Installed base dominance belongs to Polymerase Chain Reaction; steepest expansion trajectory attaches to Next-Generation Sequencing.
Application:
Maturity curves and reimbursement generosity shape geographic deployment priorities.
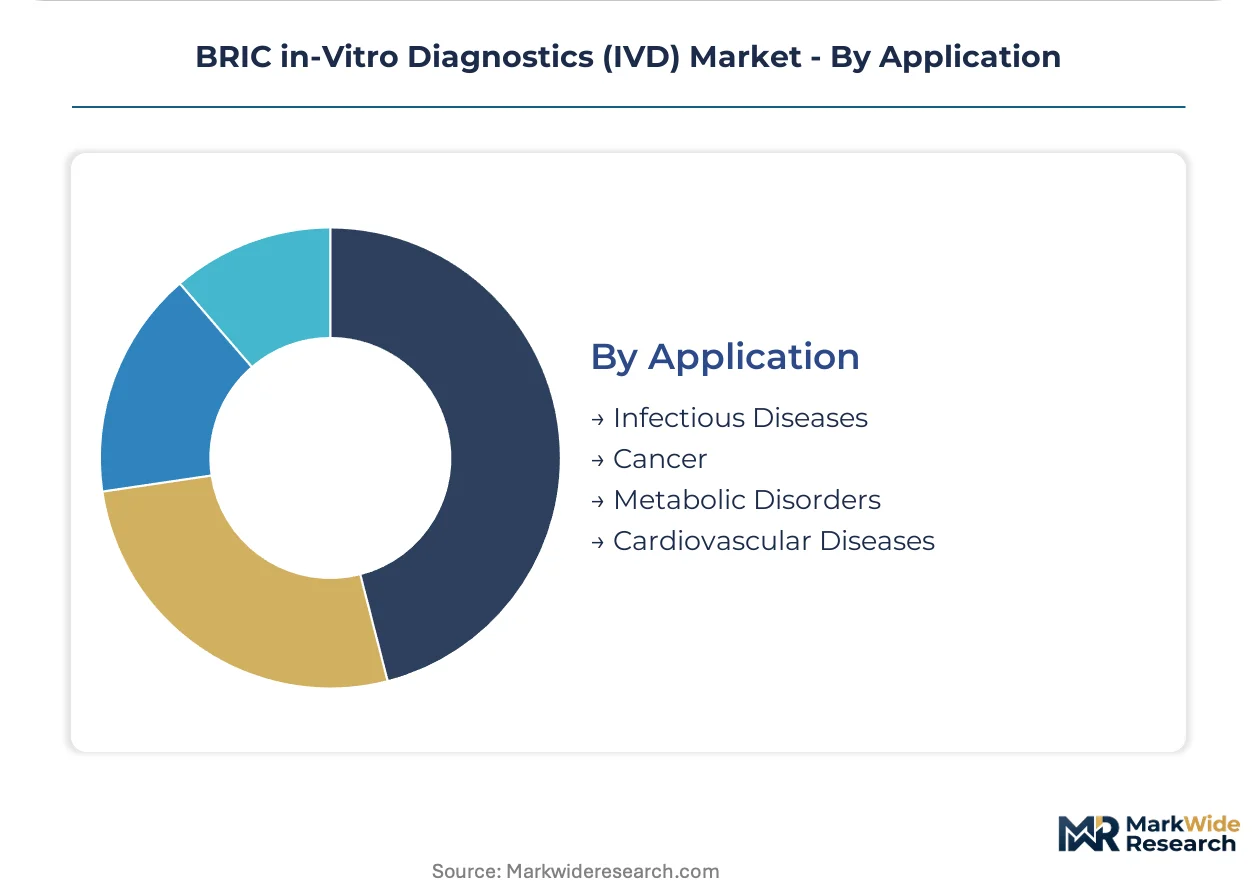
- Infectious Diseases:HIV, tuberculosis, and hepatitis screening protocols anchor immunoassay and molecular test volumes across BRIC public health programs. India's national disease control missions fund centralized laboratory networks for molecular TB diagnostics, while Brazil's ANVISA post-market surveillance requirements extend compliance timelines for new infectious disease assay launches.
- Cancer:Oncology diagnostics command premium pricing for companion diagnostic stratification of targeted therapies. Chinese tertiary hospitals are adopting PD-L1 expression and EGFR mutation testing at accelerated replacement cycles, with procurement departments consolidating vendor relationships through framework agreements that favor integrated platform providers.
- Metabolic Disorders:Diabetes and thyroid function testing represents high-frequency routine screening with established reimbursement in Russian outpatient clinics.
- Cardiovascular Diseases:Troponin and BNP testing for acute coronary syndrome triage concentrates in hospital emergency departments with point-of-care deployment constraints.
Revenue concentration rests with Infectious Diseases; margin expansion concentrates in Cancer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's medical device parks in Andhra Pradesh and Gujarat concentrate diagnostic manufacturing capacity through PLI-linked tax incentives. These zones anchor reagent kit production and analyzer assembly for molecular testing infrastructure.
Brazil
Urban diagnostic laboratories in São Paulo and Rio de Janeiro drive automated platform consolidation for infectious disease screening. ANVISA's tightened post-market surveillance for Class IV devices extends compliance timelines. The São Paulo metropolitan corridor hosts reference laboratory networks locking into multi-year exclusive vendor contracts.
Russia
Federal hospital procurement mandates prioritize localized manufacturing partnerships for state tender eligibility. The national regulator requires joint venture structures for analyzer placement in Moscow and St. Petersburg clinical networks. These cities concentrate service revenue from installed hematology and immunoassay platforms.
India
Maharashtra and Karnataka state hospital networks consolidate vendor relationships through centralized tendering platforms. CDSCO's alignment negotiations with WHO prequalification standards promise accelerated registration pathways. The Maharashtra diagnostic service outsourcing market specifies exclusive analyzer fleet commitments in framework agreements.
China
Tier-one hospital oncology departments in Beijing and Shanghai adopt real-time PCR and next-generation sequencing for liquid biopsy workflows. NMPA enforces divergent clinical evidence requirements that fragment product launch cadences. The Yangtze River Delta cluster concentrates demand for integrated molecular diagnostic automation.
BRIC in-Vitro Diagnostics (IVD) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing multi-year consumable contracts while standalone reagent suppliers face margin compression. The vendor base concentrates around three strategic archetypes: full-stack automation specialists, point-of-care portable device manufacturers, and molecular workflow integrators. Consolidation through exclusive analyzer fleet commitments and bundled instrument-consumable contracts represents the dominant competitive dynamic.
Among Switzerland-based diagnostics conglomerates, Roche Diagnostics occupies a position exemplifying installed-base leverage for service revenue retention. Abbott Laboratories Inc. represents the point-of-care specialization archetype in primary health settings. Siemens Healthineers anchors the integrated imaging-diagnostic workflow segment in federal hospital networks. These three entities collectively illustrate how geographic footprint alignment with regulatory procurement mandates determines competitive positioning across BRIC jurisdictions.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories Inc. |
| Siemens Healthineers |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| Sysmex Corporation |
| Bio-Rad Laboratories, Inc. |
| bioMérieux |
| Becton, Dickinson and Company |
| Others |
Value Chain & Pricing Dynamics
Centralized tendering platforms in Maharashtra and Karnataka state hospital networks are consolidating vendor relationships into multi-year exclusive framework agreements, forcing reagent suppliers to absorb margin compression or exit while automated platform providers capture locked-in consumable revenue streams across Brazilian and Chinese diagnostic laboratories.
Pricing Analysis
Premium pricing for expedited reagent delivery compresses against spot-market discounts for bulk oligonucleotide inventories, with contract-based long-term offtake dominating procurement relationships. Price differentiation hinges on ISO 13485 certification tier and after-sales technical support bundling. Pricing pressure stems from enzyme input cost volatility concentrated in East Asian contract manufacturers. Tier-two diagnostic laboratories exhibit acute price sensitivity, while tier-one hospital networks prioritize workflow integration over unit economics.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and Russia's federal procurement rules are redirecting foreign capital toward joint venture manufacturing structures for analyzer assembly and reagent kit production. Supply concentration centers on China for polymerase chain reaction thermal cyclers, Germany for precision optics, and the United States for next-generation sequencing flow cells. Raw material dependencies include photoresists, rare-earth magnets, and fluorophore dyes. Single-source vulnerability in biotech enzyme supply chains poses structural risk. Distribution runs through regional distributor networks with hospital GPO consolidation accelerating direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BRIC in-vitro diagnostics sector sits in a technology-transition phase where real-time PCR and next-generation sequencing platforms are systematically displacing legacy enzyme-linked immunosorbent assay formats, stranding capital in installed bases while opening whitespace for integrated workflow automation.
For Market Incumbents: Extend service revenue capture through multi-year consumable-lock contracts for cobas and Alinity platforms, while accelerating backward integration into reagent manufacturing to offset enzyme price volatility. Chemiluminescence displacement of ELISA formats threatens legacy analyzer valuations. Prioritize CDSCO-WHO harmonization alignment to compress registration timelines in India. For New Entrants and Emerging Players: Rural primary health clinics in India's underserved states present a penetrable entry point for portable point-of-care devices with simplified operator interfaces and ambient-temperature reagent stability. Tier-three Chinese hospitals seeking liquid biopsy automation without full NGS capital commitment offer secondary whitespace. Pursue diagnostic service outsourcing partnerships rather than direct analyzer sales. For Investors and Strategic Acquirers: The window for entry favors molecular workflow integrators with captive bioinformatics capabilities and installed base momentum in oncology companion diagnostics. Long-term viability rests on consolidation plays that bridge instrument placement with multi-year consumable revenue. Monitor CDSCO-WHO prequalification alignment negotiations as inflection signal for accelerated Indian market access.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO-WHO Harmonization Alignment | Accelerates registration pathways for multinational IVD registrants seeking Indian market entry. |
| Joint Venture Manufacturing Structure | Satisfies Russia's federal procurement mandates for localized production eligibility. |
| Reagent-Locked Instrument Placement | Captures multi-year consumable revenue streams in Brazilian diagnostic laboratory networks. |
| Point-of-Care Device Miniaturization | Opens rural clinic penetration in Indian primary health settings with limited cold-chain infrastructure. |
| Liquid Biopsy Workflow Integration | Addresses oncology companion diagnostic demand in Chinese tertiary hospital networks. |
Study Parameters
Regulatory filings with ANVISA, CDSCO, and NMPA, hospital procurement databases, and GPO contract repositories formed the secondary backbone, supplemented by primary interviews with diagnostic laboratory directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers across São Paulo, Moscow, Mumbai, and Shanghai. Bottom-up installed base modeling triangulated against top-down market sizing from customs trade data and reagent import records.
Historical trendline analysis of analyzer placement cycles and consumable consumption patterns anchored the analytical framework across the projection horizon, with segmentation modeling across product type, end user, technology, and application dimensions. CAGRs derived from regression analysis of replacement-driven demand and technology substitution rates, incorporating molecular diagnostics adoption curves and immunoassay displacement trajectories as industry-specific forecast inputs.
Revisions become necessary when regulatory harmonization negotiations stall, biotech raw material supply chains experience sustained disruption, or federal procurement mandates shift domestic-content thresholds. Forecasts reflect documented assumptions regarding technology adoption rates and reimbursement pathway stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
FISH Probe Market
Diagnostics
Semen Analysis Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Sweden in-Vitro Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Animal Diagnostics Market
Diagnostics
Cellular Health Screening Market
Diagnostics
LDL Test Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
North America Breast Cancer Screening Tests Market