
 Spain in-Vitro Diagnostics Market | 2026-2036
Spain in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain in-Vitro Diagnostics Market Analytics
Digital pathology integration with automated slide scanning and AI-assisted image analysis is tilting the technology stack toward platform-centric laboratory workflows. F. Hoffmann-La Roche AG leverages its installed base of cobas analyzers to sustain reagent pull-through across Spanish hospital networks. Danaher Corporation anchors its position through Beckman Coulter's hematology and immunoassay systems, while bioMerieux SA specializes in microbiology identification and antimicrobial susceptibility testing for infectious disease applications.
In-vitro diagnostics encompasses medical tests performed on blood, tissue, urine, or other biological specimens outside the living organism, typically requiring reagent-based chemical reactions, antibody-antigen binding, or nucleic acid amplification with sensitivity thresholds measured in picograms per milliliter. Molecular diagnostics represents the fastest-expanding technology dimension, driven by PCR and next-generation sequencing platforms that deliver pathogen identification and pharmacogenomic profiling for precision oncology. Reagents and assays generate the recurring revenue pool, while instruments function as capital placements that lock in long-term consumable contracts across hospital laboratories and blood bank screening operations.
The EU In Vitro Diagnostic Regulation (IVDR) and CE marking requirements administered by Spanish notified bodies reshape product registration timelines and elevate clinical evidence standards for market access. AEMPS, Spain's national medicines and health products agency, coordinates post-market surveillance and vigilance reporting that directly influences procurement specifications in autonomous community health systems. Stakeholders must monitor how IVDR transition deadlines compress supplier certification pipelines and whether centralized tendering in Catalonia and Andalusia accelerates consolidation among compliant manufacturers.
Market Dynamics
The EU In Vitro Diagnostic Regulation (IVDR) is compressing certification timelines and elevating clinical evidence requirements, forcing Spanish laboratories to consolidate supplier relationships around compliant manufacturers with established notified body partnerships.
Growth Catalysts
- IVDR Compliance Deadlines:The transition timeline for CE marking under IVDR is accelerating procurement decisions among autonomous community health systems, favoring suppliers with completed technical documentation.
- Molecular Diagnostics Platforms:PCR and next-generation sequencing adoption in Madrid and Barcelona reference laboratories is expanding test menus for oncology and infectious disease applications.
- Centralized Laboratory Networks:Regional health service consolidation in Catalonia and Andalusia is aggregating purchasing power toward platform-centric reagent contracts.
Market Restraints
- Notified Body Bottlenecks:Limited Spanish and EU notified body capacity for IVDR conformity assessment is extending product registration timelines by 12-24 months for novel IVD submissions.
- Reagent Supply Concentration:Dependence on single-source enzyme and oligonucleotide suppliers creates vulnerability in PCR assay production chains serving hospital laboratories.
- Capital Equipment Replacement Cycles:Extended depreciation schedules for automated analyzers in public hospital networks delay platform refresh opportunities for molecular diagnostics vendors.
Strategic Opportunities
- Digital Pathology Integration:AI-assisted image analysis convergence with automated slide scanning is creating new workflow automation contracts in large pathology departments.
- Pharmacogenomic Testing Expansion:Oncology departments in tertiary hospitals are building precision medicine programs requiring companion diagnostic partnerships.
- Point-of-Care Molecular Testing:Decentralized PCR platforms for respiratory and sepsis panels present white space in emergency departments and intensive care units outside Madrid and Barcelona.
Industry Challenges
- Bioinformatics Talent Scarcity:Next-generation sequencing data interpretation requires computational biology expertise that Spanish clinical laboratories struggle to recruit and retain.
- Legacy System Interoperability:Hospital information system integration with new IVD platforms demands customized middleware development that stretches IT deployment timelines.
- Post-Market Surveillance Reporting:AEMPS vigilance requirements for adverse event documentation impose ongoing compliance costs that mid-sized IVD distributors find disproportionately burdensome.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain in-Vitro Diagnostics Market |
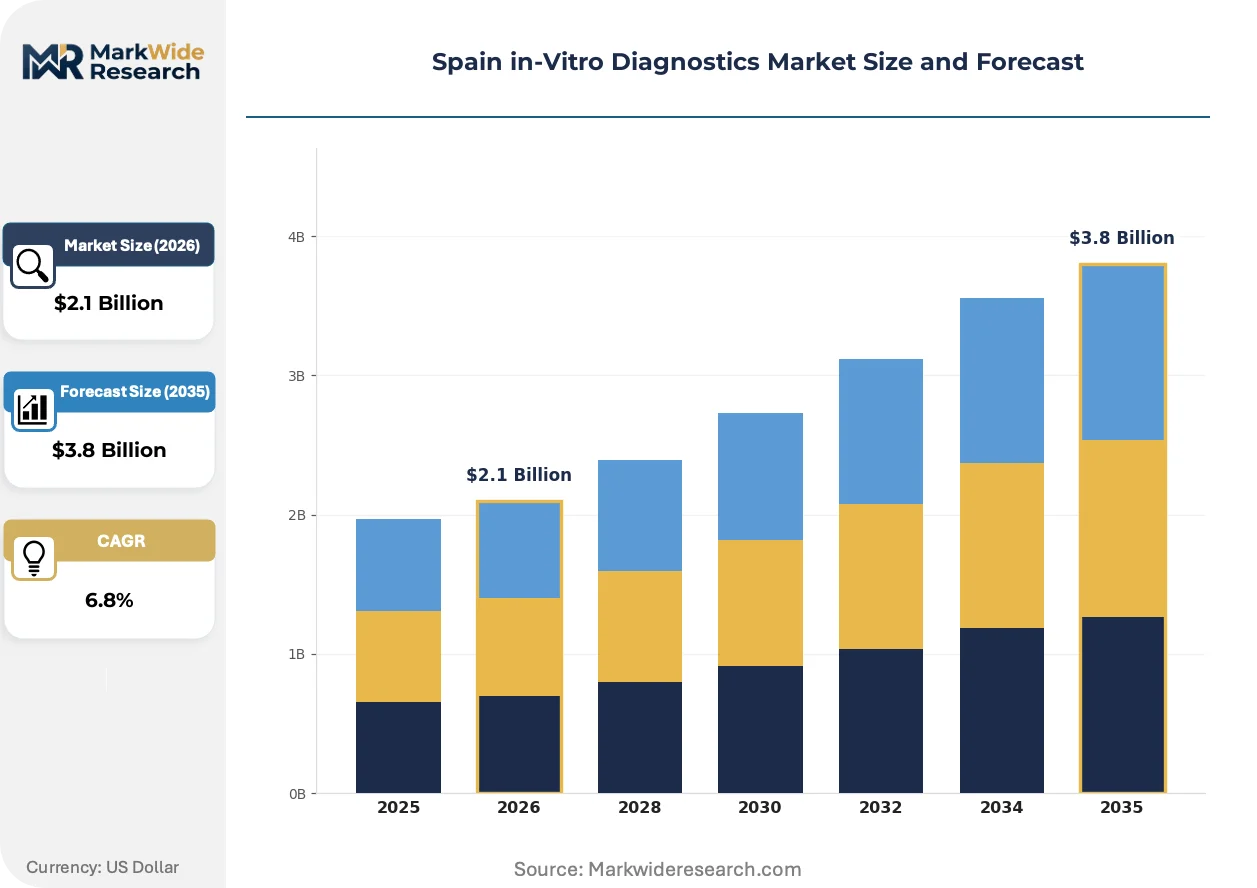
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Instruments, Software End User: Hospitals, Clinics, Laboratories, Blood Banks Technology: Microbiology, Immunology, Molecular Diagnostics, Hematology Application: Oncology, Infectious Diseases, Metabolic Disorders, Cardiology |
| Companies Covered | F. Hoffmann-La Roche AG, Danaher Corporation, Abbott Laboratories, Becton, Dickinson and Company, Bio-Rad Laboratories Inc., bioMerieux SA, Siemens Healthineers AG, Sysmex Corporation, Ortho Clinical Diagnostics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain in-Vitro Diagnostics Market Evolving Landscape
Spanish clinical laboratories are reconfiguring their technology stacks around automation, regulatory compliance, and data integration capabilities that compress turnaround times while satisfying IVDR documentation requirements.
Digital pathology platforms combining whole-slide imaging with computational diagnostic algorithms are virtualizing traditional microscopy workflows in large hospital pathology departments. The Hospital Clínic de Barcelona and similar tertiary centers are deploying these systems for histopathology screening. This virtualization is compressing specialist pathologist review times and enabling remote consultation networks across autonomous community health systems.
IVDR recertification mandates are reshaping product registration strategies for IVD manufacturers seeking Spanish market access. The regulation's elevated clinical evidence standards and quality management system requirements are filtering out smaller suppliers without dedicated regulatory affairs functions. High-complexity molecular diagnostics and companion diagnostics face the steepest compliance burdens, driving consolidation in oncology testing portfolios.
Consolidated tendering through regional purchasing cooperatives is displacing hospital-level procurement autonomy in Catalonia, Andalusia, and the Basque Country. These aggregators negotiate multi-year reagent supply contracts tied to instrument placement commitments. The shift is most visible in blood bank screening and clinical chemistry segments, where standardized platforms reduce per-test costs across networked laboratory facilities.
Spain in-Vitro Diagnostics Market Segmentation
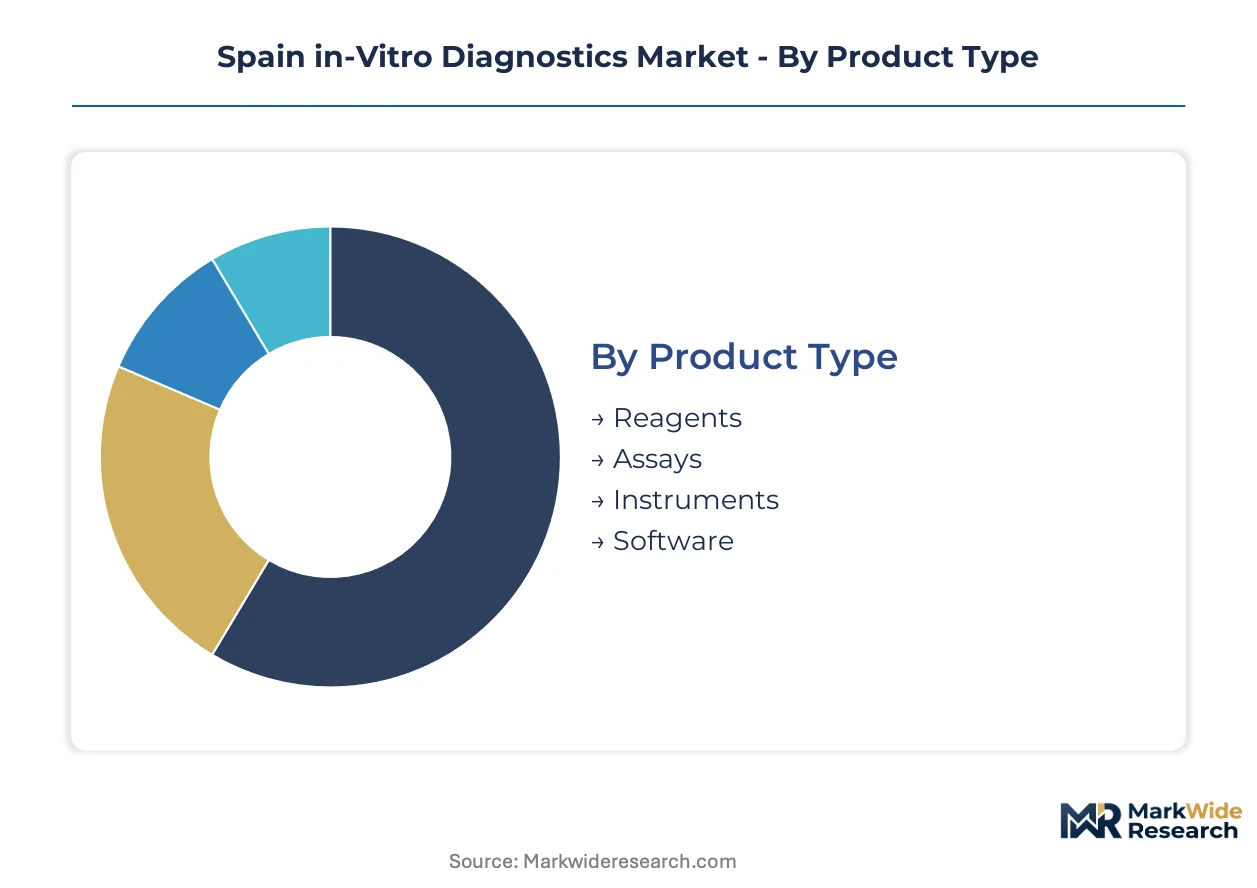
IVD market segmentation in Spain reflects procurement patterns shaped by IVDR compliance timelines and regional health system consolidation. Understanding how product categories, technology platforms, and end-user requirements intersect reveals where commercial leverage concentrates across autonomous community tenders.
Product Type:
The use-case spectrum spans consumable-intensive routine testing to capital-intensive platform deployments with multi-year reagent lock-in contracts.
- Reagents:Enzyme-based and antibody-conjugated chemical formulations drive recurring revenue through standardized kits for clinical chemistry and immunoassay menus. Procurement concentrates in Catalonia and Andalusia regional purchasing cooperatives, where multi-year supply agreements tied to analyzer placements compress per-test costs across networked hospital laboratories.
- Assays:Pre-validated test protocols for specific biomarkers or pathogens include PCR panels, ELISA kits, and rapid diagnostic tests with defined sensitivity thresholds. Madrid reference laboratories are expanding oncology and infectious disease assay menus as precision medicine programs require companion diagnostic partnerships with pharmaceutical sponsors.
- Instruments:Automated analyzers, nucleic acid extraction platforms, and next-generation sequencing systems function as capital placements that secure long-term consumable contracts.
- Software:Laboratory information management systems, middleware for instrument integration, and AI-assisted image analysis tools enable workflow automation and regulatory documentation.
Established volume favors Reagents; emerging adoption favors Software.
End User:
Customer concentration follows Spain's autonomous community health system structure, with procurement authority shifting from individual hospitals to regional aggregators.
- Hospitals:Tertiary centers in Barcelona and Madrid anchor demand for high-complexity molecular diagnostics and companion testing, with pathology departments driving digital slide scanning adoption.
- Clinics:Primary care settings and specialist outpatient facilities utilize point-of-care devices for rapid glucose monitoring, coagulation testing, and infectious disease screening with same-day turnaround requirements.
- Laboratories:Public hospital networks and private reference laboratories process high-throughput sample volumes, with centralized facilities in Catalonia consolidating testing previously distributed across smaller sites.
- Blood Banks:Transfusion services and tissue typing centers maintain stringent screening protocols for infectious disease markers, with regional blood transfusion centers operating under AEMPS vigilance oversight.
Procurement gravity centers on Laboratories; point-of-care expansion targets Clinics.
Technology:
Platform selection determines regulatory pathway complexity, with IVDR recertification timelines varying substantially across technology categories.
- Microbiology:Culture-based identification and antimicrobial susceptibility testing systems remain essential for hospital-acquired infection surveillance, with automated platforms reducing time-to-result for bloodstream pathogens.
- Immunology:Antibody-antigen binding assays for autoimmune markers, allergy panels, and infectious disease serology generate stable volume through standardized reagent contracts.
- Molecular Diagnostics:PCR and next-generation sequencing platforms represent the steepest expansion trajectory, driven by oncology pharmacogenomic testing and respiratory pathogen panels in Madrid and Barcelona reference laboratories.
- Hematology:Cell counting and coagulation analyzers serve routine clinical chemistry menus with established instrument placements requiring periodic refresh cycles.
Technology maturity favors Immunology; capability investment flows to Molecular Diagnostics.
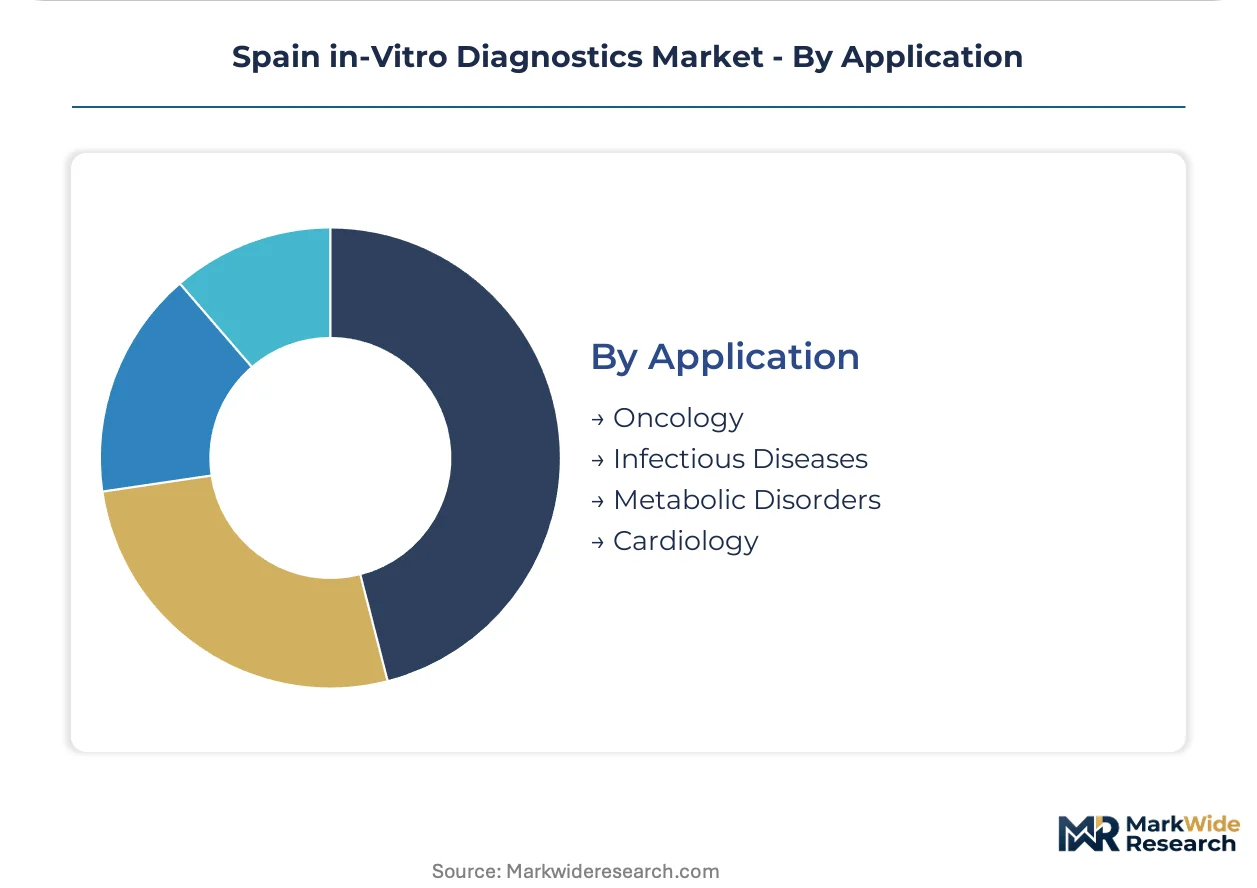
Application:
Clinical indication prioritization reflects disease burden demographics and pharmaceutical pipeline activity requiring companion diagnostic development.
- Oncology:Precision medicine programs in tertiary hospitals demand biomarker profiling for targeted therapy selection, with next-generation sequencing panels expanding to cover solid tumor and hematologic malignancy mutations.
- Infectious Diseases:Respiratory panels, sepsis screening, and antimicrobial resistance surveillance drive molecular platform adoption, with hospital-acquired infection protocols requiring rapid pathogen identification.
- Metabolic Disorders:Diabetes monitoring and lipid profiling generate high-frequency testing volume through clinical chemistry analyzers with established reimbursement pathways.
- Cardiology:Cardiac biomarker testing for acute coronary syndrome diagnosis and heart failure management operates through standardized troponin and natriuretic peptide assays.
Revenue stability anchors in Metabolic Disorders; innovation investment clusters in Oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German IVD manufacturers export diagnostic platforms and reagent systems to Spanish hospital networks and reference laboratories. This trade corridor channels capital equipment and consumable supplies through Madrid and Barcelona procurement hubs.
Madrid
The capital region concentrates Spain's largest public hospital networks and the Carlos III Health Institute's reference laboratories. AEMPS headquarters in Madrid shapes national procurement specifications and IVDR compliance timelines. The La Paz University Hospital anchors molecular diagnostics demand for oncology and infectious disease panels.
Catalonia
Barcelona's Hospital Clínic and Vall d'Hebron University Hospital drive adoption of digital pathology and next-generation sequencing platforms. The Catalan Health Service's centralized tendering aggregates purchasing power across 7.5 million residents. The Barcelona Science Park clusters biotechnology firms developing companion diagnostics for precision medicine programs.
Andalusia
Seville and Málaga anchor southern Spain's laboratory network consolidation under the Andalusian Health Service. Regional purchasing cooperatives negotiate multi-year reagent contracts tied to analyzer placements. The Virgen del Rocío University Hospital in Seville processes high-throughput infectious disease screening for the region's 8.4 million population.
Basque Country
Bilbao's Osakidetza health system operates centralized laboratories serving the autonomous community's 2.2 million residents. The region's industrial policy supports local biotechnology clusters developing diagnostic reagents. The Cruces University Hospital in Barakaldo leads antimicrobial resistance surveillance protocols.
Valencia
The Valencian Community's reference laboratory network in Valencia city processes specialized testing for 5 million residents. Regional health authorities consolidate procurement through the FISABIO foundation's laboratory services. The La Fe University Hospital anchors molecular diagnostics capacity for transplantation and immunogenetics testing.
Spain in-Vitro Diagnostics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Spain's IVD procurement landscape. The market structures around platform-centric reagent contracts and multi-year supply agreements negotiated through regional purchasing cooperatives. Two strategic archetypes dominate: diversified conglomerates with broad analyzer portfolios and focused specialists in microbiology or molecular diagnostics. Competitive moves center on IVDR certification completion and regional tender participation.
Among Swiss-headquartered conglomerates, F. Hoffmann-La Roche AG occupies a position exemplifying platform-centric reagent lock-in strategies. Danaher Corporation, a US-based diversified manufacturer, sits within the capital-equipment-plus-consumables archetype. bioMerieux SA, a French specialist, represents focused expertise in microbiology identification systems. These three entities anchor distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Danaher Corporation |
| Abbott Laboratories |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories Inc. |
| bioMerieux SA |
| Siemens Healthineers AG |
| Sysmex Corporation |
| Ortho Clinical Diagnostics |
| Others |
Value Network & Pricing Analysis
Underutilized notified body capacity in Southern Europe is compressing IVDR certification timelines for compliant manufacturers while forcing price concessions from suppliers still navigating technical documentation gaps. This utilization asymmetry rewards early-certifiers with pricing power in Madrid and Barcelona tenders while squeezing margins for laggards locked in legacy CE-IVD transition cycles.
Pricing Analysis
Current-generation molecular diagnostics platforms command premium positioning against prior-generation immunoassay systems and emerging next-generation sequencing installations. Contract-based long-term offtake agreements dominate, with price differentiation resting on IVDR certification tier and regional purchasing cooperative volume scale. Cost compression in standard clinical chemistry menus is intensifying because Andalusian and Catalan aggregators consolidate reagent contracts. Mid-sized distributors serving autonomous community laboratories exhibit highest price sensitivity; tertiary hospital networks in Barcelona demonstrate lowest sensitivity due to companion diagnostic partnership requirements.
Supply Chain Analysis
Extended payment terms from Spanish regional health services are forcing reagent manufacturers to deploy supply-chain finance facilities covering 90-120 day receivables cycles. Manufacturing concentrates in Germany, Switzerland, and France for automated analyzers, while enzyme and oligonucleotide inputs draw from specialized chemical suppliers in the Netherlands and Ireland. Single-source vulnerability in PCR polymerase supply creates exposure for assay kit producers serving hospital laboratories. Distribution runs through Madrid-based medical device distributors with AEMPS warehousing licenses and direct regional health service contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain IVD market functions as a regulatory entrenchment moat where IVDR certification completion creates switching costs that cement incumbent positions across autonomous community laboratory networks.
For Market Incumbents: Harden platform lock-in through exclusive reagent supply agreements tied to next-generation sequencing instrument placements in Catalonia and Andalusia. Deepen backward integration into oligonucleotide synthesis to mitigate single-source enzyme supplier vulnerability. IVDR recertification deadlines compressing competitive windows favor suppliers with completed technical documentation. For New Entrants and Emerging Players: Point-of-care molecular testing in Seville, Málaga, and Valencia emergency departments represents the most penetrable entry point outside Madrid-Barcelona procurement gravity. Decentralized PCR platforms for respiratory and sepsis panels in intensive care units offer white-space positioning. Target intensive care unit clinical directors with workflow integration demonstrations bypassing centralized laboratory procurement committees. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue consolidation play because reagent pull-through economics dominate capital equipment depreciation cycles in Spanish hospital networks. Acquisition targets should exhibit completed IVDR certification for Class C/D devices and established notified body partnerships. Monitor AEMPS vigilance reporting volume as signal for quality system stress among mid-tier distributors.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Certification Completion | CE marking under IVDR unlocks participation in Catalan and Andalusian regional tenders aggregating 15 million residents. |
| Regional Purchasing Cooperative Partnership | Direct contracting with CatSalut and SAS bypasses hospital-level procurement fragmentation in consolidated laboratory networks. |
| Companion Diagnostic Co-Development | Oncology pharmacogenomic alliances with pharmaceutical sponsors secure premium positioning in Madrid tertiary centers. |
| Digital Pathology Platform Integration | AI-assisted slide scanning contracts at Hospital Clínic de Barcelona establish reference site credibility for autonomous community expansion. |
| Point-of-Care Molecular Manufacturing | Decentralized PCR production for emergency departments addresses underpenetrated demand outside reference laboratory hubs. |
Research Methodology
The analysis maps molecular diagnostics, immunoassay, microbiology identification, and digital pathology sub-sectors, each validated through hospital laboratory directors, GPO contracts managers, biomedical engineers, and AEMPS regulatory affairs specialists. Primary interviews with procurement leads at CatSalut, SAS, and Osakidetza combined with secondary validation against AEMPS vigilance databases, EU IVDR notified body registries, and autonomous community tender documentation. Bottom-up instrument placement tracking and top-down health expenditure analysis triangulate market sizing.
Assumptions held fixed include IVDR transition timeline adherence, regional health system consolidation trajectories, and molecular diagnostics reimbursement pathways. Segmentation dimensions modeled span product type, technology platform, end-user facility tier, and autonomous community regulatory cluster across the projection horizon. CAGRs derive from reagent consumption intensity per analyzer placement and platform refresh cycle timing. Forecast inputs incorporate companion diagnostic pipeline activity and antimicrobial resistance surveillance protocol expansion.
Macroeconomic conditions sit as an overlay; deviation in Spanish regional health budgets, EU MDR/IVDR regulatory enforcement intensity, or nucleic acid reagent input costs would shift the trajectory. Forecasts reflect documented assumptions regarding certification completion rates and tender participation thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fungal Antigens Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Breast Cancer Diagnostics Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
Viral Antigens Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Artificial Intelligence in IVD Market