
 Ventilated Bulk Bags Market | 2026-2036
Ventilated Bulk Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Ventilated Bulk Bags Market Outlook
Food-grade certification tiers are redrawing competitive boundaries in ventilated bulk bags. Berry Global Group sustains R&D intensity across multi-layer woven laminates for moisture-controlled agricultural transport. Conitex Sonoco dominates North American channel control through captive distribution networks serving grain cooperatives. Zibo Haosence Packaging anchors cost-efficient polypropylene weaving capacity that extends into custom-ventilation patterns for tropical crop exporters.
Ventilated bulk bags are woven polypropylene or natural-fiber containers engineered with perforated panels or mesh strips that permit airflow rates of 15–50 cubic feet per minute, designed to prevent condensation damage during extended storage of hygroscopic commodities. Food-grade bag specifications now command premium positioning as agricultural exporters in Brazil and Vietnam adopt breathable packaging for coffee bean transit. Polypropylene material grades lead volume due to tensile strength above 1,200 denier and resistance to mold colonization, while jute alternatives capture niche demand among organic-certified producers seeking biodegradable end-of-life pathways. Direct sales channels concentrate margin pools through long-term supply agreements with multinational agricultural traders, though distributor networks remain essential for fragmented smallholder cooperatives across Sub-Saharan Africa and Southeast Asia.
EU REACH compliance and FDA food-contact substance regulations shape material selection and migration testing protocols for cross-border agricultural shipments. BIS certification requirements in India mandate tensile-load testing for woven sacks exceeding 500 kilogram capacity, restricting market access for uncertified imports. ISO 21898 standards for flexible intermediate bulk containers provide the foundational safety benchmark that insurers and commodity traders reference in procurement contracts. Stakeholders must monitor evolving national implementations of extended producer responsibility frameworks, as these will determine whether recycled-content mandates reshape virgin polypropylene economics before the forecast horizon closes.
Market Dynamics
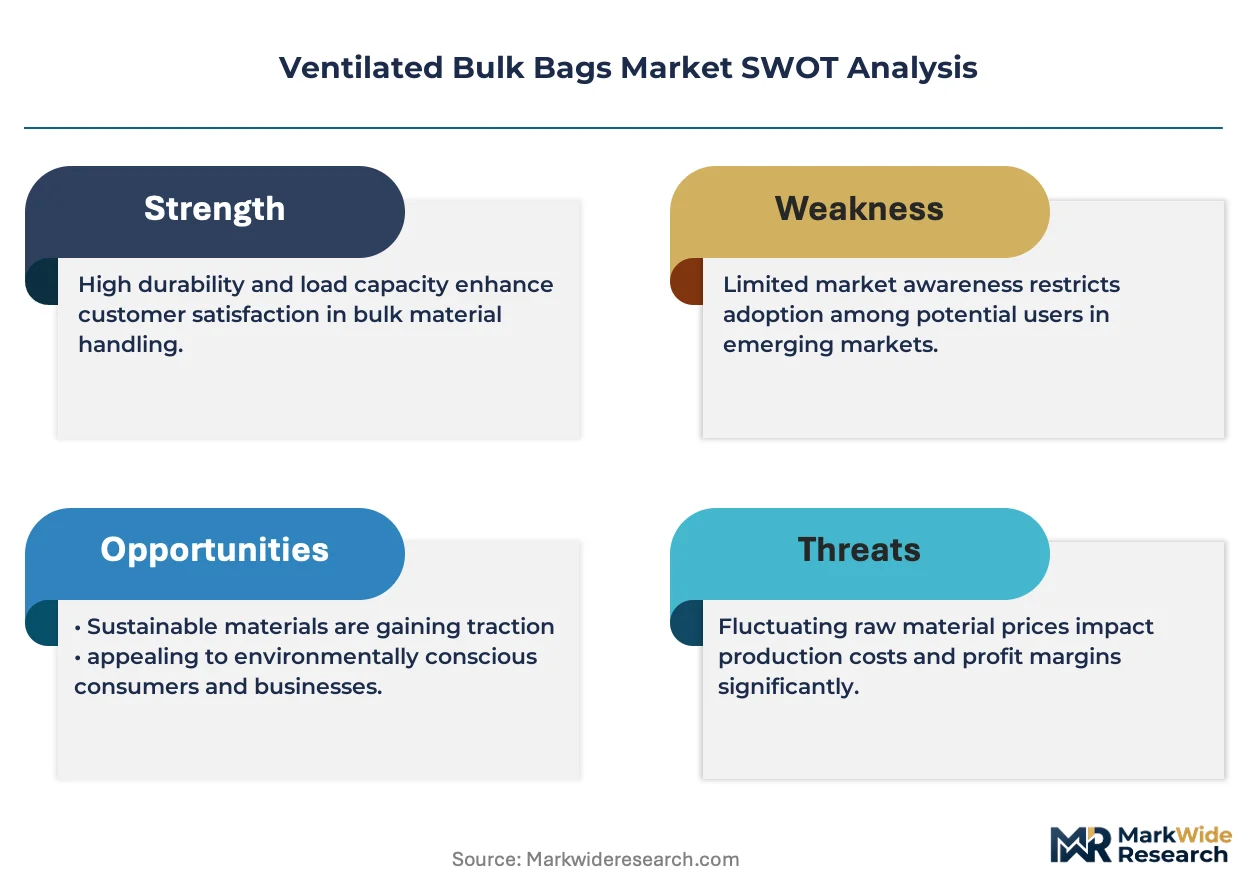
EU REACH compliance and FDA food-contact substance regulations are forcing material traceability upgrades across agricultural supply chains, compressing margins for non-compliant producers while rewarding certified manufacturers with premium positioning in moisture-sensitive crop logistics.
Growth Catalysts
- REACH material traceability mandates:European agricultural exporters must document polymer sourcing through supply chains, creating captive demand for certified ventilated bulk bag producers who pre-validate compliance documentation.
- Brazilian grain belt storage losses:Post-harvest spoilage rates exceeding industry benchmarks in Mato Grosso and Goiás drive cooperative procurement of breathable polypropylene containers with 15–50 CFM airflow ratings.
- Multi-layer woven laminate R&D:Advances in co-extruded barrier films enable moisture-controlled transport of coffee and cocoa beans across tropical humidity zones without condensation damage.
Market Restraints
- Virgin polypropylene price volatility:Propylene feedstock costs fluctuate with crude oil indices, squeezing converter margins and limiting pricing flexibility for standard-grade ventilated bags.
- Zibo weaving cluster concentration:Cost-efficient polypropylene fabric production concentrates in Shandong Province, creating single-source dependency risks for global bag assemblers.
- Jute substitution ceiling:Natural fiber alternatives face tensile strength limitations below 800 denier, restricting load capacity for grain applications above 500 kilograms.
Strategic Opportunities
- Vietnamese coffee exporter certification gaps:Dak Lak and Lam Dong provinces lack local food-grade bag converters, opening channel entry for pre-certified import suppliers.
- Extended producer responsibility frameworks:EU Packaging and Packaging Waste Regulation implementation will mandate recycled-content thresholds, advantaging early movers with post-industrial polypropylene recycling streams.
- Direct-to-cooperative digital platforms:Agritech marketplaces in Sub-Saharan Africa bypass fragmented distributor networks, enabling margin capture from smallholder coffee and cashew collectives.
Industry Challenges
- ISO 21898 testing capacity bottlenecks:Third-party certification backlog for flexible intermediate bulk container safety validation delays product launches by 4–8 months.
- Migration testing protocol complexity:FDA food-contact substance regulations require polymer additive quantification at parts-per-billion thresholds, demanding laboratory infrastructure beyond mid-tier converter capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventilated Bulk Bags Market |
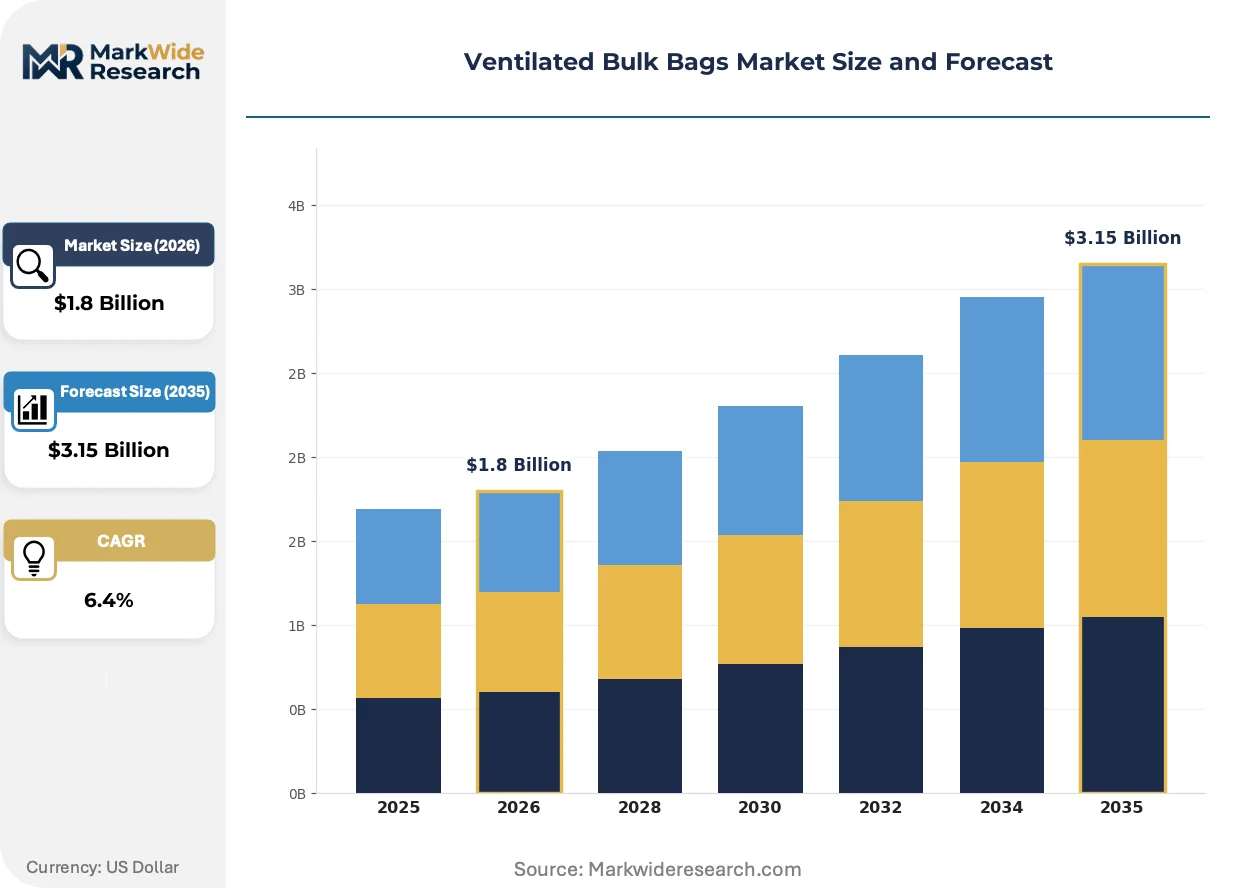
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
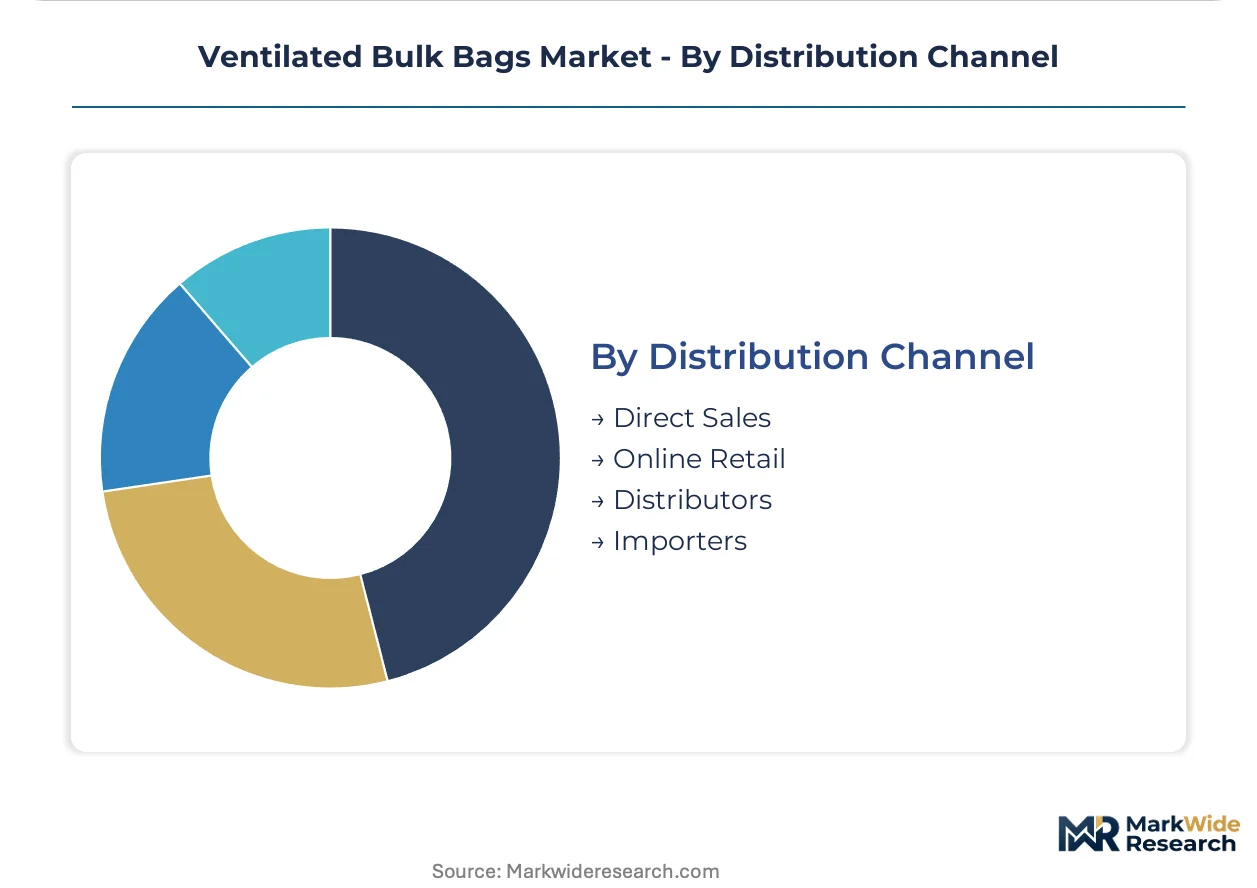
| Segmentation | Product Type: Open-Top Bags, Food-Grade Bags, Heavy-Duty Bags, Custom Design Bags Material: Polypropylene, Jute, Cotton, Nylon End User: Agriculture, Food Processing, Chemical Industry, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Importers |
| Companies Covered | Star Industries, Conitex Sonoco, Global-Pak Inc., Berry Global Group, Inc., Zibo Haosence Packaging Co., Ltd., JumboSack Corporation, Bagwell Supply, Alpine FIBC Pvt. Ltd., LC Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventilated Bulk Bags Market Strategic Shifts
Material science convergence with digital traceability infrastructure is reconfiguring how agricultural packaging suppliers demonstrate compliance and capture premium positioning across moisture-sensitive supply chains.
Co-extruded multi-layer woven laminates are decomposing the traditional trade-off between breathability and moisture barrier performance. Vietnamese and Brazilian coffee exporters are adopting these structures for containerized ocean transit of high-value arabica lots. The technology is decomposing commodity-grade bag pricing power by enabling certified producers to command tiered premiums based on validated humidity protection metrics.
EU Packaging and Packaging Waste Regulation enforcement is tightening extended producer responsibility obligations across member states. Agricultural traders sourcing from non-EU origins now face documentation requirements for polymer recyclability and recycled-content percentages. Brazilian soy and coffee exporters serving Rotterdam and Hamburg terminals are pre-qualifying suppliers based on pre-submitted compliance dossiers to avoid customs delays.
Certification-driven procurement criteria are displacing price-first vendor selection among multinational agricultural traders. Coffee cooperatives in Colombia and Ethiopia now require ISO 21898 safety certification and REACH-compliant material declarations as mandatory bid preconditions. This behavioral shift concentrates contract awards among vertically integrated converters with in-house testing laboratories, compressing market access for undifferentiated regional assemblers.
Ventilated Bulk Bags Market Segmentation
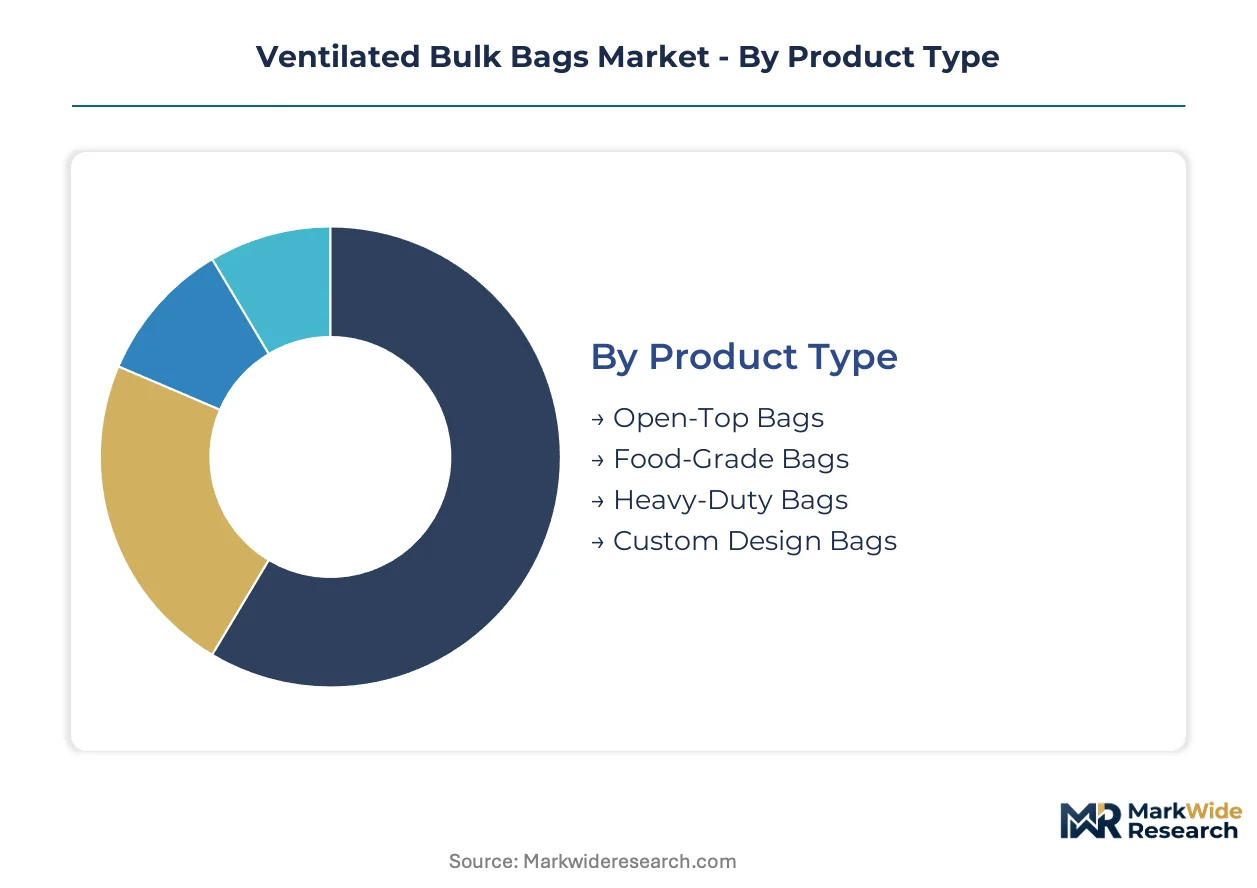
Ventilated bulk bag procurement patterns diverge sharply across product tiers and material grades, with regulatory compliance serving as the primary sorting mechanism for supplier qualification in moisture-sensitive agricultural supply chains.
Product Type:
FDA food-contact substance regulations and EU REACH material traceability mandates create divergent compliance burdens across product categories, compressing margins for uncertified open-top variants while enabling premium capture by validated food-grade alternatives.
- Food-Grade Bags:Multi-layer woven laminates with co-extruded barrier films meet FDA migration testing protocols at parts-per-billion thresholds. Brazilian coffee exporters in Minas Gerais and Vietnamese arabica shippers in Dak Lak mandate these specifications for ocean container transit of high-value lots, with certification documentation required as mandatory bid preconditions.
- Open-Top Bags:Standard woven polypropylene construction without specialized barrier properties dominates commodity grain handling in Brazil's Mato Grosso belt. Post-harvest storage losses exceeding industry benchmarks drive cooperative procurement of breathable 15–50 CFM airflow configurations for soy and maize.
- Heavy-Duty Bags:Tensile strength above 1,200 denier supports load capacities exceeding 500 kilograms for construction aggregate and chemical mineral transport.
- Custom Design Bags:Tailored ventilation patterns and dimensional specifications address tropical crop exporter requirements for humidity-controlled transit.
Established volume favors open-top configurations; emerging adoption favors food-grade certified alternatives.
Material:
Cost tier differentiation separates virgin polypropylene leaders from biodegradable niche contenders, with feedstock price volatility reshaping converter economics across material grades.
- Polypropylene:Virgin resin grades deliver tensile strength above 1,200 denier and mold colonization resistance essential for extended agricultural storage. Shandong Province weaving clusters in China anchor global supply, though single-source dependency risks concentrate procurement vulnerability.
- Jute:Natural fiber construction captures organic-certified producer demand in India and Bangladesh seeking biodegradable end-of-life pathways. Tensile strength limitations below 800 denier restrict load capacity for grain applications above 500 kilograms.
- Cotton:Breathable woven construction serves specialty coffee cooperatives in Ethiopia and Colombia requiring chemical-free material contact.
- Nylon:Superior abrasion resistance supports chemical industry applications with repeated handling cycles.
Polypropylene commands dominant volume share; jute and cotton gain traction fastest among sustainability-mandated procurement programs.
End User:
Application-specific performance requirements drive divergent specification standards, with agricultural moisture sensitivity demanding the most stringent certification protocols.
- Agriculture:Coffee, cocoa, and grain exporters in Brazil, Vietnam, and Colombia require ISO 21898 safety certification and REACH-compliant material declarations. Co-extruded multi-layer laminates enable humidity-controlled transit across tropical zones without condensation damage.
- Food Processing:FDA food-contact substance regulations mandate polymer additive quantification and migration testing documentation for cross-border shipments.
- Chemical Industry:Static-dissipative woven constructions address flammable powder handling requirements.
- Construction:Heavy-duty polypropylene withstands aggregate abrasion and UV exposure during outdoor storage.
Agricultural applications anchor current demand; food processing represents the steepest expansion trajectory as certification requirements tighten.
Distribution Channel:
Customer type and purchase scale determine channel economics, with direct sales capturing margin pools from multinational traders while distributor networks serve fragmented smallholder bases.
- Direct Sales:Long-term supply agreements with multinational agricultural traders concentrate margin pools through pre-validated compliance documentation. Berry Global Group and Conitex Sonoco leverage captive relationships with grain cooperatives and coffee exporters.
- Distributors:Fragmented smallholder cooperatives across Sub-Saharan Africa and Southeast Asia depend on regional distributor networks for procurement access and technical specification guidance.
- Online Retail:Agritech marketplaces in Kenya and Nigeria enable direct-to-cooperative platform sales, bypassing traditional distributor markups.
- Importers:Pre-certified bag suppliers in Germany and the Netherlands serve EU agricultural traders facing Packaging and Packaging Waste Regulation documentation requirements.
Direct sales channels dominate value capture; online retail platforms expand most quickly among digitally-enabled smallholder collectives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian coffee and soybean exporters shipping to Rotterdam and Hamburg terminals drive procurement of REACH-compliant ventilated bulk bags, while Vietnamese arabica shippers serving European specialty roasters anchor Southeast Asian demand for food-grade certified packaging.
Brazil
Minas Gerais coffee cooperatives and Mato Grosso grain elevators mandate ISO 21898 certification for ocean-bound shipments. ANVISA food-contact regulations align with FDA migration testing protocols for cross-border agricultural trade. São Paulo-based converters supply breathable polypropylene containers with validated 15–50 CFM airflow ratings to multinational traders.
Vietnam
Dak Lak and Lam Dong arabica exporters face certification gaps in local food-grade bag production. The country's national agricultural regulator enforces packaging safety standards for commodity exports. Ho Chi Minh City distributors serve as procurement hubs for pre-certified import suppliers targeting European specialty coffee channels.
United States
Midwest grain cooperatives and specialty crop handlers require FDA food-contact substance documentation for domestic and export shipments. EPA regulations on polymer additives influence material selection for breathable agricultural containers. Chicago and Minneapolis distribution corridors concentrate captive supply relationships with multinational packaging converters.
Germany
Hamburg and Bremen port terminals enforce EU Packaging and Packaging Waste Regulation documentation requirements for incoming agricultural shipments. ECHA REACH compliance mandates polymer traceability through supply chains. North Rhine-Westphalia logistics clusters pre-validate supplier dossiers to prevent customs delays for Brazilian and Vietnamese cargo.
India
Gujarat and Maharashtra jute weaving centers supply biodegradable alternatives for organic-certified producers. BIS certification requirements mandate tensile-load testing for woven sacks exceeding 500 kilogram capacity. Mumbai and Ahmedabad industrial corridors restrict market access for uncertified imports through mandatory safety validation protocols.
Ventilated Bulk Bags Market Competitive Environment
Listed leaders compete with private specialists across certification documentation and channel control dimensions. The vendor base organizes around three tiers: multinational converters with in-house testing laboratories, regional fabricators leveraging cost-efficient weaving capacity, and specialty distributors serving fragmented smallholder networks. Strategic moves concentrate on backward integration into polypropylene resin sourcing and geographic expansion through pre-qualified importer relationships in EU port terminals.
Among North American packaging groups, Berry Global Group, Inc. and Conitex Sonoco exemplify the laboratory-integrated tier with captive distribution networks. Zibo Haosence Packaging Co., Ltd. anchors the cost-efficient fabrication archetype from Shandong Province weaving clusters. These three occupy positions spanning premium certification services through economy-grade volume production.
| Leading Market Players |
|---|
| Star Industries |
| Conitex Sonoco |
| Global-Pak Inc. |
| Berry Global Group, Inc. |
| Zibo Haosence Packaging Co., Ltd. |
| JumboSack Corporation |
| Bagwell Supply |
| Alpine FIBC Pvt. Ltd. |
| LC Packaging |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day order lead times for REACH-compliant food-grade bags concentrate pricing power with pre-certified Shandong Province converters, while virgin polypropylene feedstock volatility compresses margins for standard-grade assemblers lacking long-term resin offtake agreements.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA food-contact certification tier and volume scale, with multinational agricultural traders commanding lowest unit costs through multi-year contracts. Cost compression in economy-grade open-top configurations is intensifying because Zibo weaving clusters face propylene feedstock volatility. Smallholder cooperatives across Sub-Saharan Africa exhibit highest price sensitivity, while EU specialty coffee importers prioritize certified food-grade specifications over unit economics.
Supply Chain Analysis
Inventory buffers of 45-60 days at Hamburg and Rotterdam port terminals reflect single-source dependency on Shandong Province polypropylene weaving clusters. Raw material inputs draw from Saudi Arabian propylene crackers, Chinese virgin resin grades, and Indian jute fiber cultivation. Single-source vulnerability concentrates risk in Shandong's cost-efficient fabric production, where any disruption cascades through global bag assembler networks. Distribution runs through captive direct-sales relationships with multinational traders, supplemented by regional distributor networks serving fragmented agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital traceability platform adoption by Brazilian coffee exporters signals an interoperability inflection, where compliance documentation becomes the core value layer rather than physical bag production.
For Market Incumbents: Consolidate laboratory-integrated certification capabilities to defend against emerging digital-native competitors offering automated REACH documentation. Backward integration into post-industrial polypropylene recycling streams captures margin pools as EU Packaging and Packaging Waste Regulation mandates tighten. Channel control through pre-qualified importer relationships at Hamburg and Rotterdam terminals reinforces captive positioning. For New Entrants and Emerging Players: Certification-as-a-service gaps in Vietnamese Dak Lak and Lam Dong provinces expose penetrable white space for pre-validated import suppliers. Direct-to-cooperative agritech platforms in Kenya and Nigeria bypass traditional distributor markups, enabling margin capture from digitally-enabled smallholder collectives. Go-to-market execution should anchor on ISO 21898 safety validation bundled with compliance documentation automation. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging conglomerates seeking to divest non-core agricultural container divisions. Long-term viability frames around extended producer responsibility compliance infrastructure rather than commodity-grade volume production. Watch for EU member state implementation variance in recycled-content thresholds as the decisive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Streams | Post-industrial polypropylene recovery secures EU Packaging and Packaging Waste Regulation compliance positioning. |
| Laboratory Certification Capacity Expansion | In-house ISO 21898 and FDA migration testing reduces third-party validation bottlenecks for food-grade bag launches. |
| Direct-to-Cooperative Platform Development | Agritech marketplace integration captures margin pools from Kenyan and Nigerian smallholder coffee collectives. |
| Pre-Qualified Importer Network Establishment | Rotterdam and Hamburg terminal relationships prevent customs delays for Brazilian and Vietnamese agricultural exporters. |
| Multi-Layer Woven Laminate R&D Investment | Co-extruded barrier film advances enable humidity-controlled transit premiums for arabica and cocoa bean shippers. |
Study Parameters
Desk research of customs trade databases, BIS certification registries, and SEC packaging converter filings preceded structured interviews with agricultural procurement managers, polypropylene resin traders, and third-party testing laboratory directors. Primary fieldwork with Brazilian coffee cooperative logistics officers and Vietnamese arabica exporters validated supply chain concentration assumptions. Secondary triangulation drew from EU REACH compliance documentation, FDA food-contact substance guidance, and ISO 21898 safety standard interpretations. Bottom-up volume estimates from end-use application segmentation converged with top-down market sizing through converter capacity analysis.
Variance decomposition across material grade, certification tier, and distribution channel dimensions structured the analytical framework over the projection horizon. Modeled segmentation captured product type, material composition, end-user industry, and geographic production hub variations. CAGRs derived from weighted average growth rates across these segments, with agricultural commodity trade flow data and post-harvest loss reduction investment trends serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU REACH, FDA food-contact substance, and BIS certification regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Air Bubble Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Trash Can Liners Market