
 Bagster Bag Market | 2026-2036
Bagster Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Bagster Bag Market Analysis
EPA landfill diversion mandates is expanding collection infrastructure for flexible waste containment solutions. Waste Management Inc. leverages its national hauling network to bundle Bagster pickup with residential accounts. Republic Services Inc. anchors its competitive stance through integrated disposal site ownership. Clean Harbors Inc. specializes in contractor-facing logistics that streamline job-site bag deployment.
A Bagster bag is a woven polypropylene flexible waste container designed for temporary debris collection, typically rated for three cubic yards of material and capable of holding up to 3,300 pounds of construction or household waste. The product serves residential renovation and light commercial demolition by bridging the gap between standard trash receptacles and roll-off dumpsters. Heavy-Duty Bagster variants command margin premiums due to reinforced lifting straps and puncture-resistant fabric. Construction Sites application demand tracks housing starts and remodeling permit volumes. Waste Management Companies distribution channel captures recurring revenue through scheduled collection contracts.
FDA regulations on recycled content in food-contact plastics indirectly shape virgin polypropylene sourcing costs for Bagster manufacturers. EPA Resource Conservation and Recovery Act provisions govern debris classification and disposal routing from collection bags. OSHA job-site safety standards influence bag placement protocols and weight limit enforcement on commercial projects. Stakeholders must monitor polymer price volatility and municipal franchise agreement renegotiations to protect margin structures.
Market Dynamics
Residential renovation permit volumes in suburban counties are compressing collection scheduling windows and forcing haulers to densify Bagster pickup routes around metropolitan ring roads.
Growth Catalysts
- EPA landfill diversion mandates:State-level waste reduction targets are expanding curbside collection infrastructure for flexible containment solutions in jurisdictions facing capacity constraints.
- Polypropylene woven fabric advances:Reinforced lifting strap configurations now support heavier debris loads without puncture failure, extending use cases to light commercial demolition.
- Suburban county clustering:Homeowner association renovation guidelines in counties surrounding Atlanta, Dallas, and Phoenix are normalizing temporary debris containment protocols.
Market Restraints
- Resin price volatility:Virgin polypropylene feedstock costs fluctuate with propylene monomer supply disruptions from Gulf Coast petrochemical complexes.
- Roll-off dumpster substitution:Small-container rental services capture projects exceeding three cubic yards, capping Bagster addressable volume at the threshold where per-pound economics invert.
- OSHA weight enforcement:Job-site safety inspections impose documentation burdens that slow deployment velocity on commercial construction sites.
Strategic Opportunities
- Rural county penetration:Unincorporated areas beyond municipal franchise boundaries lack scheduled bulky waste pickup, creating white space for on-demand collection models.
- Heavy-Duty variant expansion:Reinforced fabric specifications open contractor-facing channels where puncture resistance commands sustained margin premiums.
- Integrated disposal site bundling:Haulers with captive landfill or transfer station assets can compress collection-to-disposal cycle times and improve route density.
Industry Challenges
- Route optimization complexity:Dispersed bag placement across low-density suburban geographies degrades truck utilization rates and inflates per-stop costs.
- Contamination sorting requirements:Mixed construction debris streams trigger manual pre-sorting labor at transfer stations, compressing disposal margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bagster Bag Market |
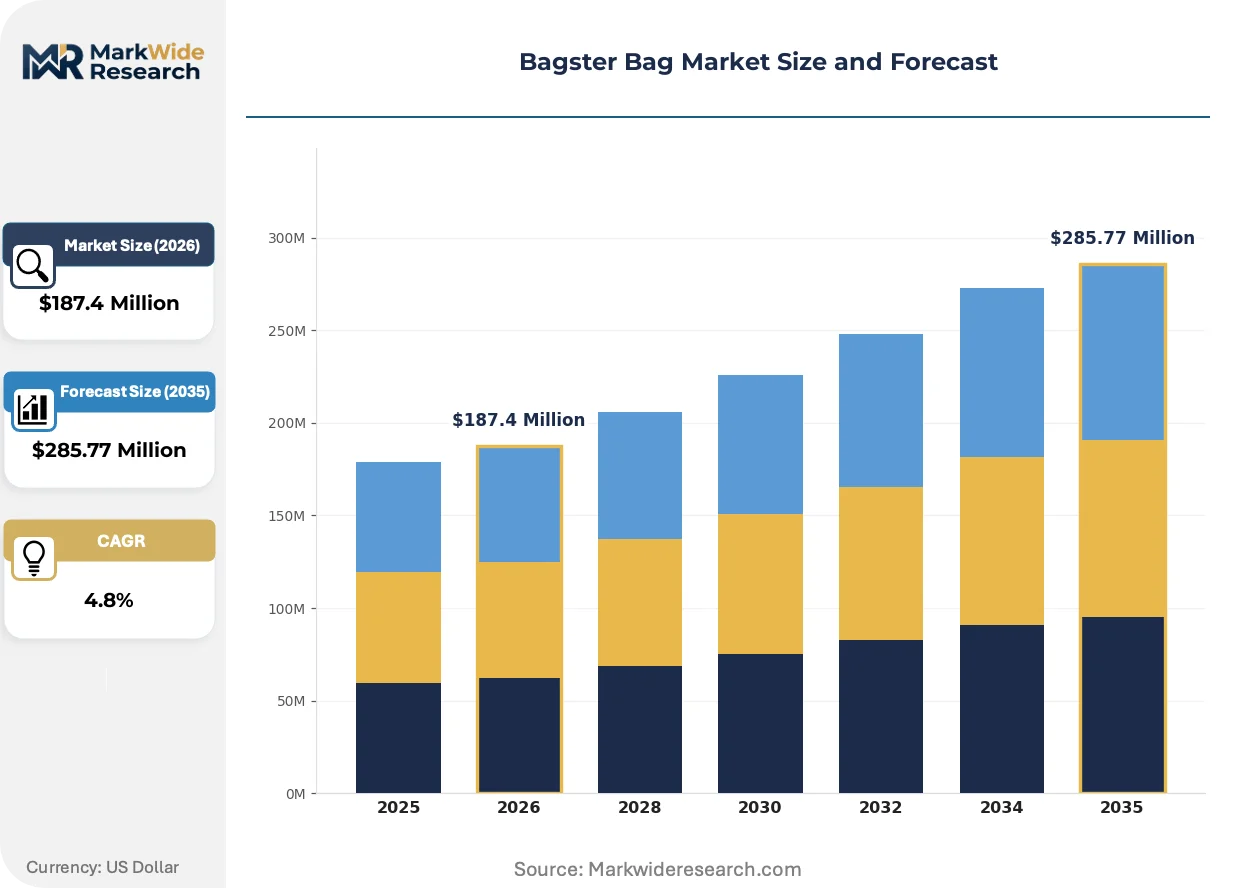
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bagster, Large Bagster, Mini Bagster, Heavy-Duty Bagster Application: Residential Use, Construction Sites, Landscaping Projects, Renovation Distribution Channel: Home Improvement Stores, Online Retailers, Landscaping Suppliers, Waste Management Companies End User: Homeowners, Contractors, Construction Firms, Property Managers |
| Companies Covered | Covanta Holding Corporation, Advanced Disposal Services, Waste Management Inc., Recology, Casella Waste Systems, Republic Services Inc., Stericycle Inc., Biffa, Clean Harbors Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bagster Bag Market Emerging Trajectories
Digital scheduling platforms and reinforced fabric specifications are compressing the gap between homeowner debris generation and collection fulfillment, reshaping how temporary waste containment is procured and serviced.
Recycled-content polypropylene blends are electrifying sustainability positioning for woven bag manufacturers. Large renovation contractors now specify minimum recycled thresholds in procurement documents. This material shift is enabling premium pricing tiers while compressing virgin resin exposure.
EPA Resource Conservation and Recovery Act provisions are tightening debris classification requirements across multiple states. Industrial waste streams from light commercial demolition now face stricter routing documentation. Heavy-Duty Bagster variants with reinforced seams are capturing this compliance-driven demand as contractors seek pre-approved containment methods.
Homeowner buying patterns are fragmenting across digital-native scheduling platforms and traditional phone-based ordering. Waste haulers with integrated mobile applications are displacing voice-only contractors in suburban counties. This channel rotation is most visible in Sun Belt metropolitan areas where renovation activity concentrates.
Bagster Bag Market Segmentation
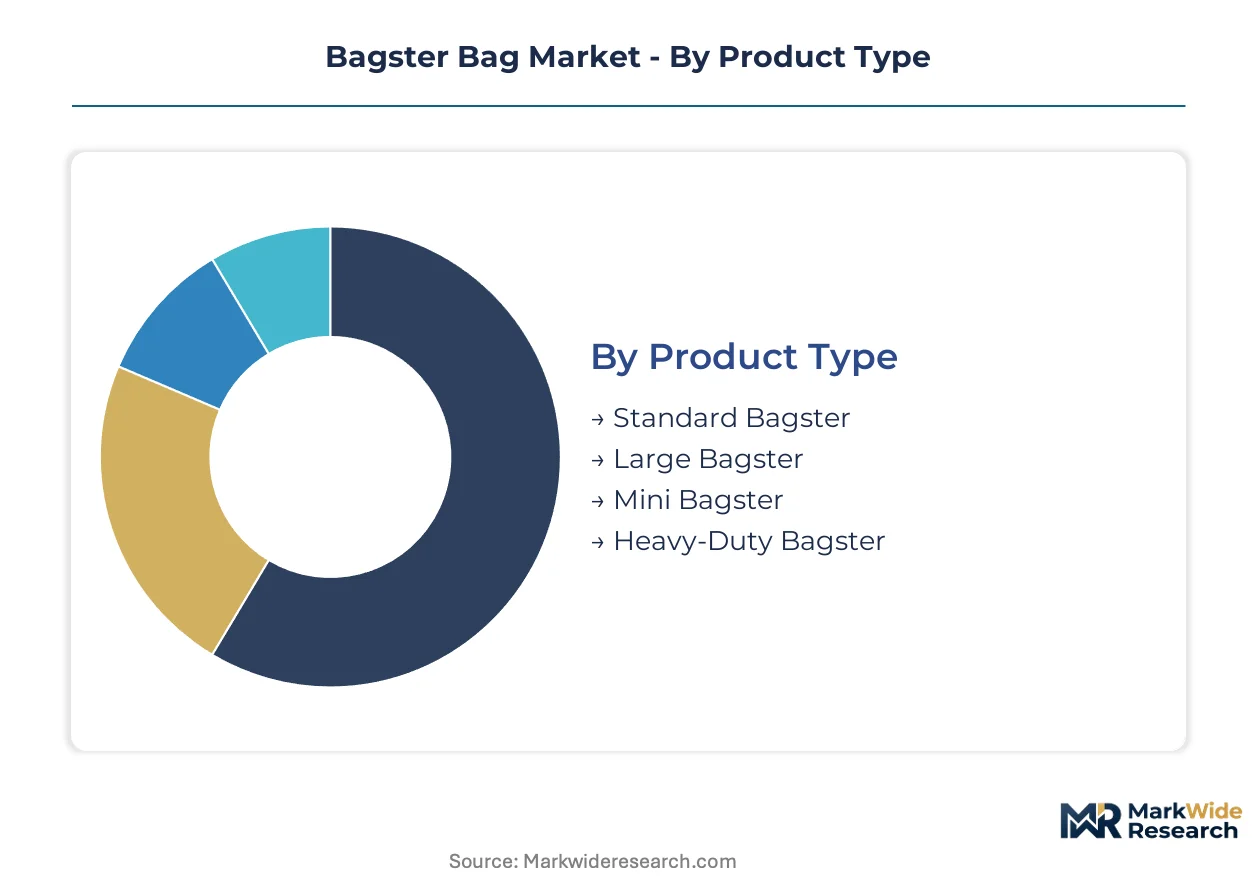
Segmentation in the Bagster Bag Market reveals how capital deployment, route density economics, and procurement channel preferences fragment revenue capture across product tiers and customer types. Manufacturers and haulers calibrate fabric specifications, distribution partnerships, and pickup logistics against distinct debris volumes and scheduling tolerances.
Product Type:
Capital intensity escalates with load-bearing capacity and reinforced seam engineering, separating commodity-grade production from specialized contractor-facing variants.
- Standard Bagster:Woven polypropylene construction rated for 3,300 pounds across three cubic yards serves baseline residential renovation demand. Homeowners in suburban Atlanta counties deploy this variant for kitchen and bathroom remodeling debris where project scale stays below roll-off dumpster thresholds.
- Heavy-Duty Bagster:Reinforced lifting straps and puncture-resistant fabric command margin premiums from commercial contractors. EPA landfill diversion documentation requirements in multiple states favor this pre-approved containment method for light demolition debris routing.
- Large Bagster:Expanded cubic yard capacity addresses whole-home renovation scope without crossing into roll-off rental economics.
- Mini Bagster:Compact footprint suits single-room projects and HOA-restricted placement zones in dense suburban developments.
Standard Bagster absorbs the bulk of installed capacity; Heavy-Duty Bagster is expanding most quickly.
Application:
Debris composition and scheduling urgency vary sharply across use cases, dictating bag specification and collection frequency.
- Construction Sites:OSHA weight enforcement and documentation burdens slow deployment velocity. Contractors in Phoenix metropolitan ring counties specify Heavy-Duty variants to satisfy job-site safety protocols and debris classification requirements.
- Residential Use:Homeowner-driven demand concentrates in suburban counties surrounding Dallas where renovation permit volumes compress collection scheduling windows.
- Renovation:Kitchen and bathroom remodeling generates predictable debris streams with moderate weight profiles.
- Landscaping Projects:Seasonal demand spikes around yard waste collection bans in multiple jurisdictions.
Residential Use captures the greatest volume throughput; Construction Sites follow the steepest expansion trajectory as commercial permitting accelerates.
Distribution Channel:
Channel selection determines customer acquisition cost and pickup bundling potential, with integrated haulers leveraging route density against standalone retailers.
- Waste Management Companies:Scheduled collection contracts generate recurring revenue through bundled residential accounts. National hauling networks compress collection-to-disposal cycle times where captive landfill assets exist.
- Home Improvement Stores:Impulse placement at point-of-sale captures homeowner project initiation moments.
- Online Retailers:Digital-native scheduling platforms displace voice-only ordering in Sun Belt metropolitan areas.
- Landscaping Suppliers:Contractor-facing logistics streamline job-site bag deployment for seasonal green waste.
Waste Management Companies anchor channel revenue; Online Retailers are climbing the fastest as mobile application penetration deepens.
End User:
Procurement authority and volume scale separate price-sensitive residential buyers from margin-rich commercial accounts with recurring debris streams.
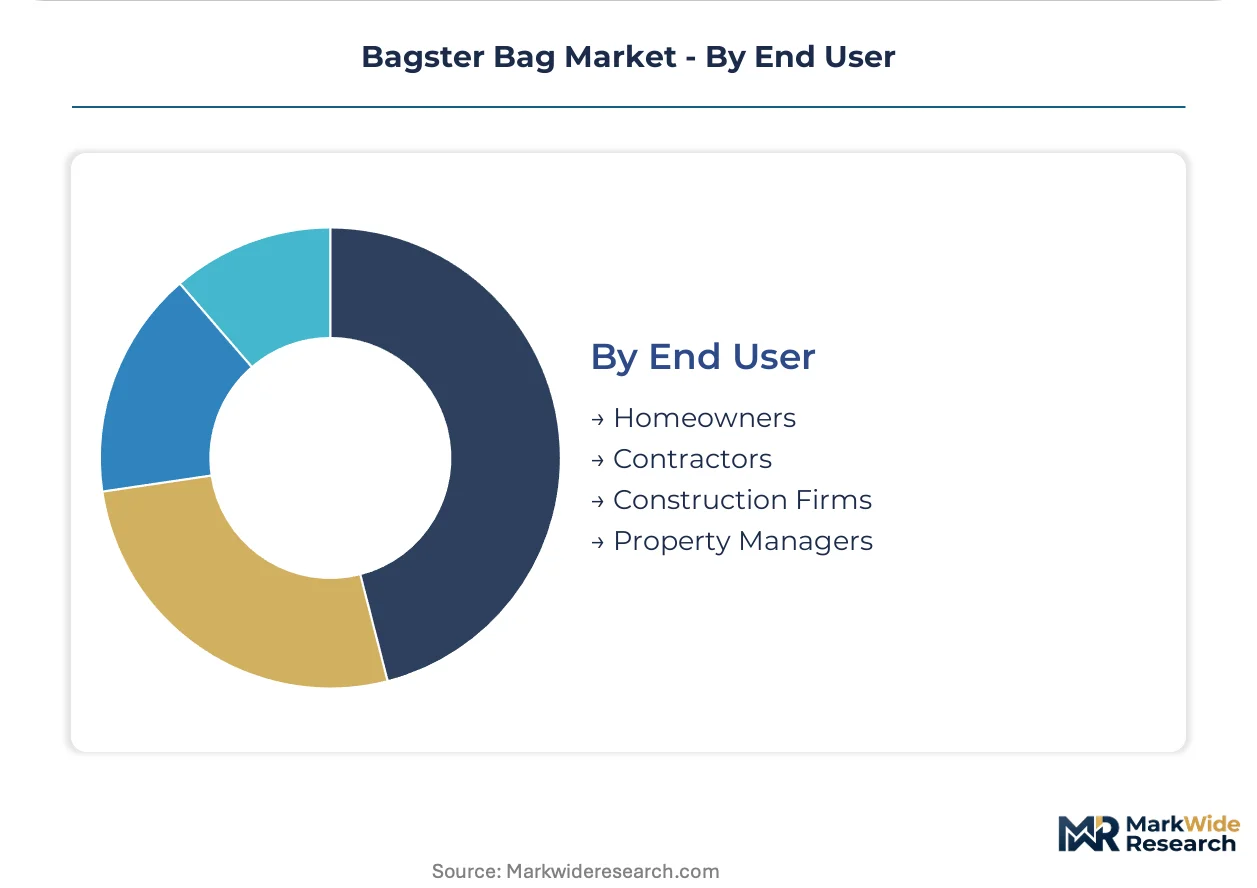
- Contractors:Large renovation contractors now specify minimum recycled-content thresholds in procurement documents. This segment commands premium pricing tiers while driving fabric specification innovation.
- Homeowners:Fragmented buying patterns across digital and traditional channels concentrate in suburban counties with active HOA renovation guidelines.
- Construction Firms:Integrated disposal site bundling appeals to firms with multi-project portfolios requiring predictable debris routing.
- Property Managers:Turnover-driven demand from rental property maintenance follows lease cycle timing rather than renovation permit volumes.
Homeowners represent the largest addressable base; Contractors are gaining share fastest through specification influence and volume commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suburban Atlanta counties anchor Bagster demand as kitchen and bathroom renovation permits compress collection scheduling windows across metropolitan ring roads.
United States
EPA landfill diversion mandates in Georgia, Texas, and Arizona expand curbside infrastructure for flexible containment solutions. Homeowner association renovation guidelines in Dallas-Fort Worth suburbs normalize temporary debris protocols. Heavy-Duty variants capture contractor demand in Phoenix metropolitan counties where OSHA documentation burdens intensify.
Canada
Residential renovation activity concentrates in Greater Toronto and Vancouver metropolitan corridors. Provincial extended producer responsibility frameworks tighten waste handling requirements across Ontario and British Columbia. Suburban municipalities surrounding Calgary deploy Bagster solutions for seasonal landscaping debris spikes.
Germany
REACH compliance costs elevate virgin polypropylene sourcing thresholds for woven fabric manufacturers. Construction sector renovation cycles in Bavaria and North Rhine-Westphalia generate predictable debris streams. Industrial clusters around Stuttgart specify reinforced containment for light commercial demolition documentation.
United Kingdom
Household renovation permits in Southeast England counties drive seasonal demand fluctuations. Environment Agency waste classification rules tighten debris routing documentation for mixed construction streams. Greater Manchester ring suburbs exhibit clustering patterns similar to Sun Belt US metropolitan areas.
Australia
Metropolitan Sydney and Melbourne renovation markets mirror US suburban county dynamics. State-level landfill diversion targets in New South Wales and Victoria expand collection infrastructure for flexible solutions. Queensland seasonal landscaping bans concentrate green waste containment demand in Brisbane peripheral counties.
Bagster Bag Market Vendor Landscape
Premium-margin players sit above commodity-margin players across route density and captive disposal asset ownership. National hauling networks with integrated landfill positions compress collection-to-disposal cycle times. Three archetypes dominate: scale-driven integrated waste managers, regional route-density specialists, and contractor-facing logistics providers. Dominant competitive moves include bundled residential account penetration and heavy-duty variant portfolio expansion.
Within the integrated network tier, Waste Management Inc. and Republic Services Inc. exemplify scale-driven consolidation through captive disposal site ownership. Clean Harbors Inc. occupies a specialized position in contractor-facing deployment logistics. Covanta Holding Corporation anchors energy-from-waste integration strategies that reshape debris routing economics.
| Leading Market Players |
|---|
| Covanta Holding Corporation |
| Advanced Disposal Services |
| Waste Management Inc. |
| Recology |
| Casella Waste Systems |
| Republic Services Inc. |
| Stericycle Inc. |
| Biffa |
| Clean Harbors Inc. |
| Others |
Supply Flow & Price Mechanics
Captive landfill ownership by national hauling networks anchors both supply security and pricing power in the Bagster market, compressing collection-to-disposal cycle times while enabling bundled residential account penetration that smaller route-density specialists cannot match.
Pricing Analysis
Per-pickup transactional pricing tied to debris weight and disposal routing anchors revenue capture across the Bagster market. Three-tier pricing structure across Heavy-Duty, Standard, and Mini variants separates contractor-facing premiums from homeowner economy tiers. Pricing pressure stems from roll-off dumpster substitution at the three-cubic-yard threshold, where per-pound economics invert. Homeowners exhibit highest price sensitivity; commercial contractors accept premium positioning for OSHA-compliant documentation bundles.
Supply Chain Analysis
Direct-to-contractor channels handle commercial job-site deployment, while retail placement at home improvement stores captures homeowner project initiation. Virgin polypropylene feedstock draws from Gulf Coast petrochemical complexes in the United States, with secondary sourcing from Canadian resin distributors and Mexican fabric weavers. Single-source vulnerability concentrates in propylene monomer supply disruptions from Texas-Louisiana corridor weather events. Distribution runs through waste management companies with captive hauling networks, home improvement retail partnerships, and digital-native scheduling platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital scheduling platforms are displacing phone-based ordering as the dominant procurement interface, replacing legacy voice-only contractor relationships with integrated mobile application workflows.
For Market Incumbents: Deploy route densification algorithms to compress per-stop costs in dispersed suburban geographies. Waste Management Inc. and Republic Services Inc. should expand Heavy-Duty variant portfolios to capture contractor specification influence. Threat substitution from small-container roll-off rentals demands defensive bundling of Bagster pickup with residential waste accounts.
For New Entrants and Emerging Players: Enter via rural county on-demand collection models where municipal franchise boundaries leave scheduled bulky waste pickup gaps. White space concentrates in unincorporated areas beyond Atlanta, Dallas, and Phoenix ring roads. Go-to-market positioning should emphasize digital-native scheduling platforms with EPA diversion documentation compliance.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated waste managers seeking route density in Sun Belt metropolitan corridors. Long-term viability hinges on landfill diversion mandate expansion and recycled-content polypropylene blend adoption. Monitor OSHA weight enforcement documentation burden intensity as inflection indicator for Heavy-Duty variant demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Duty Variant Portfolio Expansion | Captures contractor demand where EPA documentation requirements intensify debris routing compliance. |
| Digital Scheduling Platform Integration | Displaces voice-only ordering in Sun Belt metropolitan areas with concentrated renovation activity. |
| Rural County Route Densification | Penetrates unincorporated areas beyond municipal franchise boundaries lacking scheduled pickup. |
| Recycled-Content Polypropylene Transition | Enables premium pricing tiers while compressing virgin resin exposure to Gulf Coast supply disruptions. |
| Captive Landfill Asset Bundling | Compresses collection-to-disposal cycle times for integrated waste managers against standalone haulers. |
Methodological Framework
Independent corroboration across waste hauler operations directors, home improvement retail category managers, and municipal solid waste planners underwrites the qualitative findings. Primary interviews with EPA regional compliance officers, polypropylene fabric procurement leads, and renovation contractor site supervisors combined with secondary validation from EPA Resource Conservation and Recovery Act filings, OSHA job-site inspection databases, and suburban county building permit records. Bottom-up route density economics and top-down landfill diversion mandate trajectories were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic baseline through post-renovation boom normalization anchored the forecast window across the analysis window. Segmentation dimensions modeled include product load-bearing tier, application debris composition, distribution channel integration depth, and end-user procurement authority. CAGRs were derived from housing start permit velocity, remodeling spend patterns, and polypropylene price elasticity assumptions. Industry-specific inputs incorporated EPA state-level diversion target timelines and homeowner association guideline adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene monomer supply disruption scenarios or accelerated roll-off dumpster rental pricing compression. Practitioners should monitor OSHA enforcement intensity, recycled-content procurement specification spreads, and municipal franchise agreement renegotiation cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Jumbo Bags Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
FIBC Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Compression Bags Market